
 MEMS Mirrors Market | 2026-2036
MEMS Mirrors Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Mirrors Market Foresight
Silicon-on-insulator wafers is shifting from bulk-micromachined substrates in high-performance MEMS mirror fabrication, reducing die warpage and improving optical flatness. Texas Instruments leverages vertical integration across its digital micromirror device foundry operations in Texas. Hamamatsu Photonics sustains R&D intensity in electromagnetic actuation architectures for industrial inspection systems. Mirrorcle Technologies specializes in tip-tilt-piston architectures for optical beam steering in research instrumentation.
MEMS mirrors are micro-electromechanical reflective surfaces, typically 0.5 to 3 millimeters in diameter, actuated by electrostatic, electromagnetic, thermal, or piezoelectric forces to achieve angular deflections up to several degrees with microsecond response times. Their primary commercial purpose is precise, high-speed optical beam manipulation in projection, sensing, and communication systems. Digital micromirror devices anchor the largest installed base through legacy projector demand, while optical beam deflectors for lidar systems capture the fastest expansion trajectory. Electrostatic actuation dominates volume production due to CMOS-compatible fabrication, though piezoelectric variants command premium positioning in medical imaging where nanoradian stability is required.
FDA device classification rules shape medical imaging mirror requirements in the United States, while the EU Green Deal automotive emissions framework accelerates lidar integration mandates for autonomous mobility in Europe. ISO 26262 functional safety standards govern automotive mirror reliability thresholds, creating certification barriers for non-compliant suppliers. Stakeholders must monitor evolving automotive lidar performance specifications and corresponding test protocols as OEMs transition from mechanical to solid-state beam steering architectures.
Market Dynamics
Automotive OEMs are consolidating lidar procurement around solid-state MEMS architectures, compressing qualification timelines from 48 to 24 months while ISO 26262 functional safety mandates harden certification barriers for non-compliant mirror suppliers.
Growth Catalysts
- EU Green Deal automotive mandates:Emissions frameworks accelerate lidar integration requirements for autonomous mobility, forcing tier-1 suppliers to source solid-state beam steering components from certified MEMS foundries.
- Silicon-on-insulator wafer adoption:Substrate migration from bulk-micromachined alternatives reduces die warpage and improves optical flatness in high-performance mirror fabrication.
- Germany automotive cluster concentration:Stuttgart and Munich OEMs anchor demand for next-generation vehicle platforms integrating electromagnetic actuation architectures.
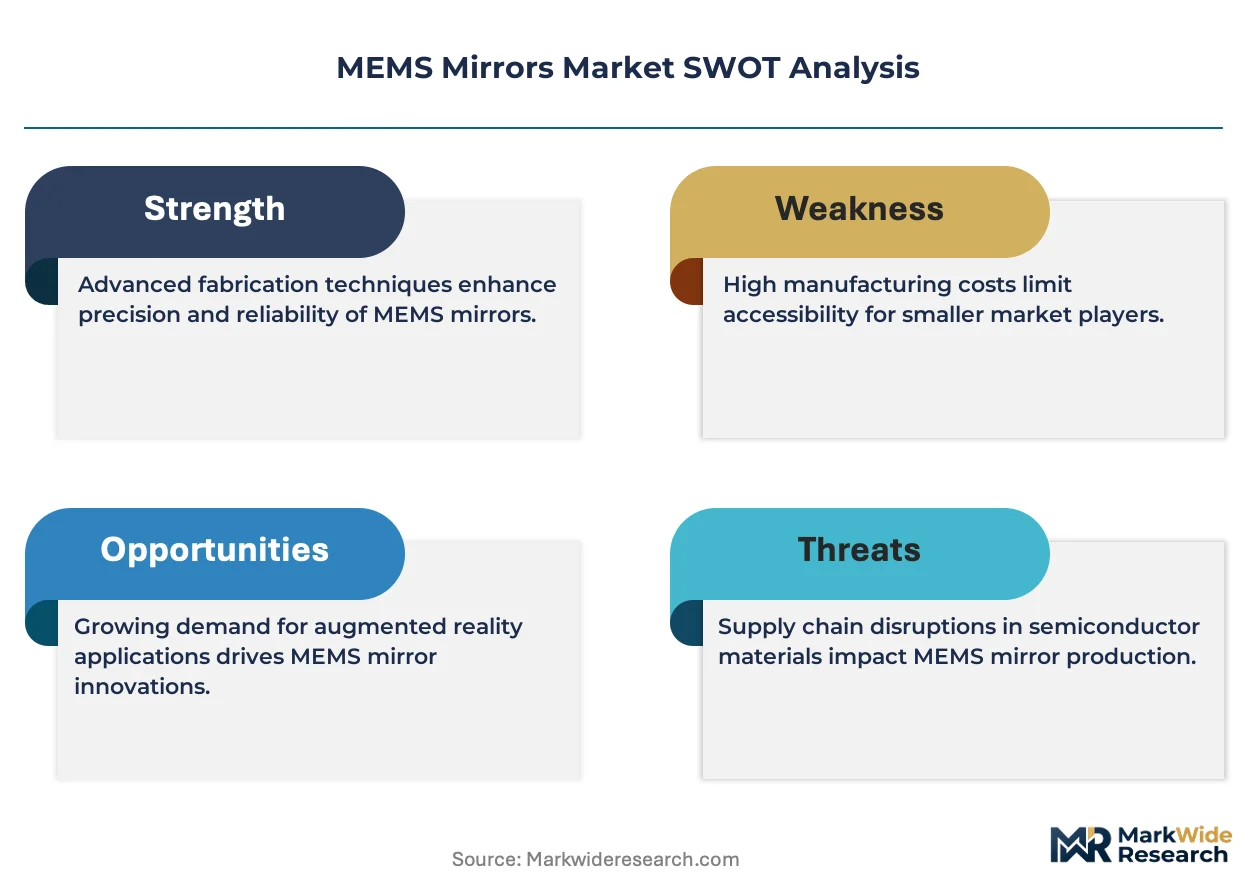
Market Restraints
- Piezoelectric material cost volatility:Lead zirconate titanate supply concentration in East Asian refineries exposes medical imaging mirror producers to input price swings.
- Electrostatic actuation technical ceiling:CMOS-compatible fabrication limits angular deflection range to several degrees, constraining long-range lidar performance specifications.
- CE marking friction:EU AI Act certification timelines for autonomous vehicle components extend product validation cycles by 8-12 months.
Strategic Opportunities
- Industrial inspection systems:Electromagnetic actuation architectures from Japanese R&D centers are penetrating non-automotive beam steering applications.
- Medical imaging nanoradian stability:FDA device classification rules in the United States create premium positioning for piezoelectric variants in surgical navigation.
- Research instrumentation channel:Tip-tilt-piston architectures are capturing optical beam steering demand from university and government laboratory procurement.
Industry Challenges
- ISO 26262 functional safety talent scarcity:Automotive reliability engineering expertise concentrates in German and Japanese supplier ecosystems, constraining new entrant qualification capacity.
- Legacy mechanical lidar integration complexity:OEM platform engineering teams face firmware and optical stack reconfiguration when substituting solid-state MEMS for rotating mirror assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Mirrors Market |
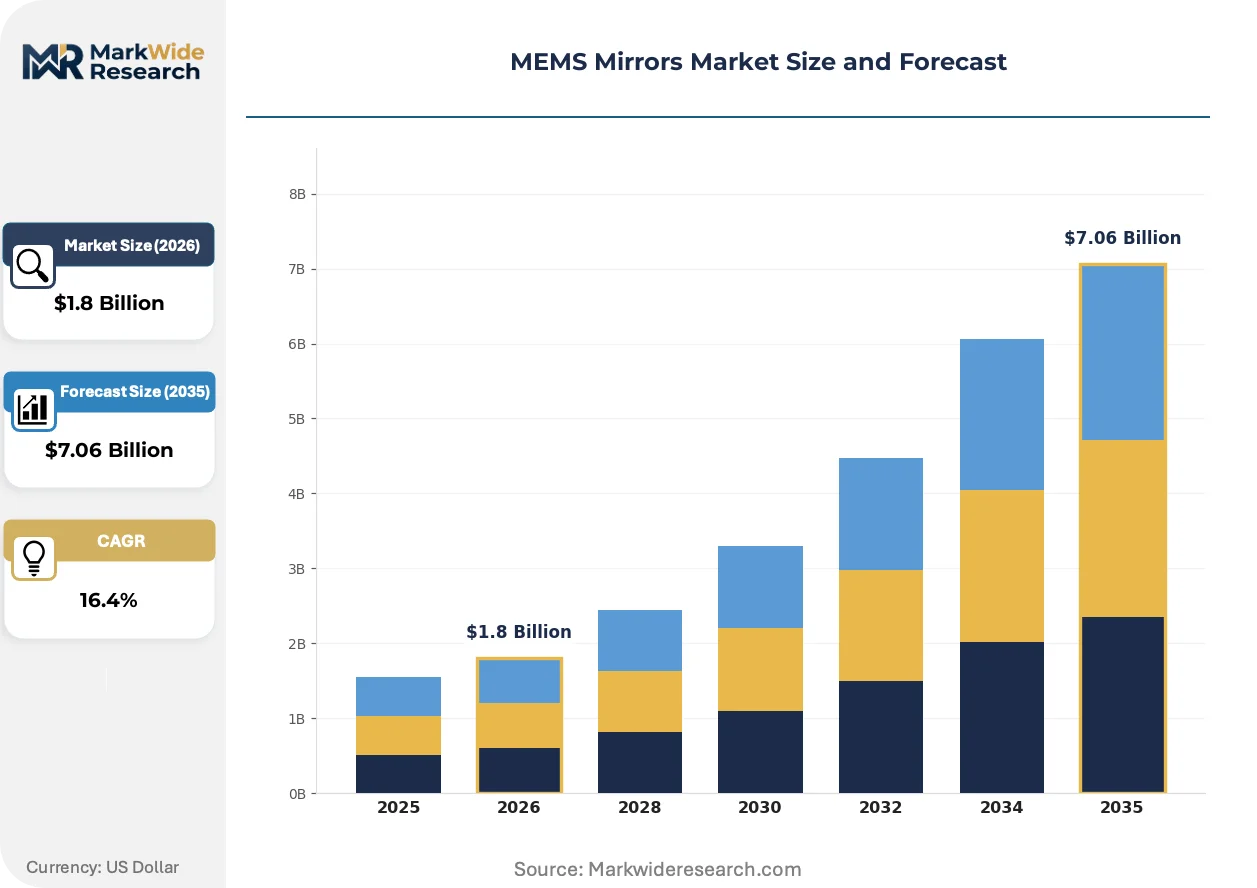
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Micromirror Devices, Optical Beam Deflectors, Micro-Mirrors, Laser Projectors Technology: Electrostatic, Electromagnetic, Thermal, Piezoelectric End User: Consumer Electronics, Automotive, Medical Devices, Industrial Applications Application: Projectors, Lidar Systems, Augmented Reality, Optical Communication |
| Companies Covered | Mirrorcle Technologies, Hamamatsu Photonics, MicroVision, Texas Instruments, Sercalo Microtechnology, OQmented, Boston Micromachines Corporation, Opus Microsystems, Preciseley Microtechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Mirrors Market Shifts & Advancements
Solid-state beam steering architectures are compressing the competitive moat around mechanical lidar incumbents while reshaping supplier qualification protocols across automotive and industrial sensing verticals.
Electromagnetic MEMS actuation is decentralizing optical beam control from centralized galvo-mirror systems to chip-scale deflectors. Automotive lidar engineering teams at German and Japanese OEMs are adopting these architectures at 18-month design cycles. The shift is compressing subsystem supplier tiers from five layers to three, collapsing margin capture at the module level.
The EU AI Act's product certification requirements for autonomous vehicle components are hardening CE marking standards for optical beam steering modules. Industrial consequence includes mandatory third-party validation of mirror reliability under thermal cycling and vibration stress. Automotive tier-1 suppliers in Stuttgart and Munich are responding by consolidating procurement around vertically integrated MEMS foundries with in-house test capabilities.
Buyer concentration among top-10 automotive OEMs is forcing component suppliers to absorb warranty liability and field failure costs previously borne by system integrators. Direct procurement contracts are displacing distributor-mediated supply relationships in lidar mirror categories. This pattern is most visible in Germany, where BMW, Mercedes-Benz, and Volkswagen Group have established captive engineering offices inside MEMS foundry development centers.
MEMS Mirrors Market Segmentation
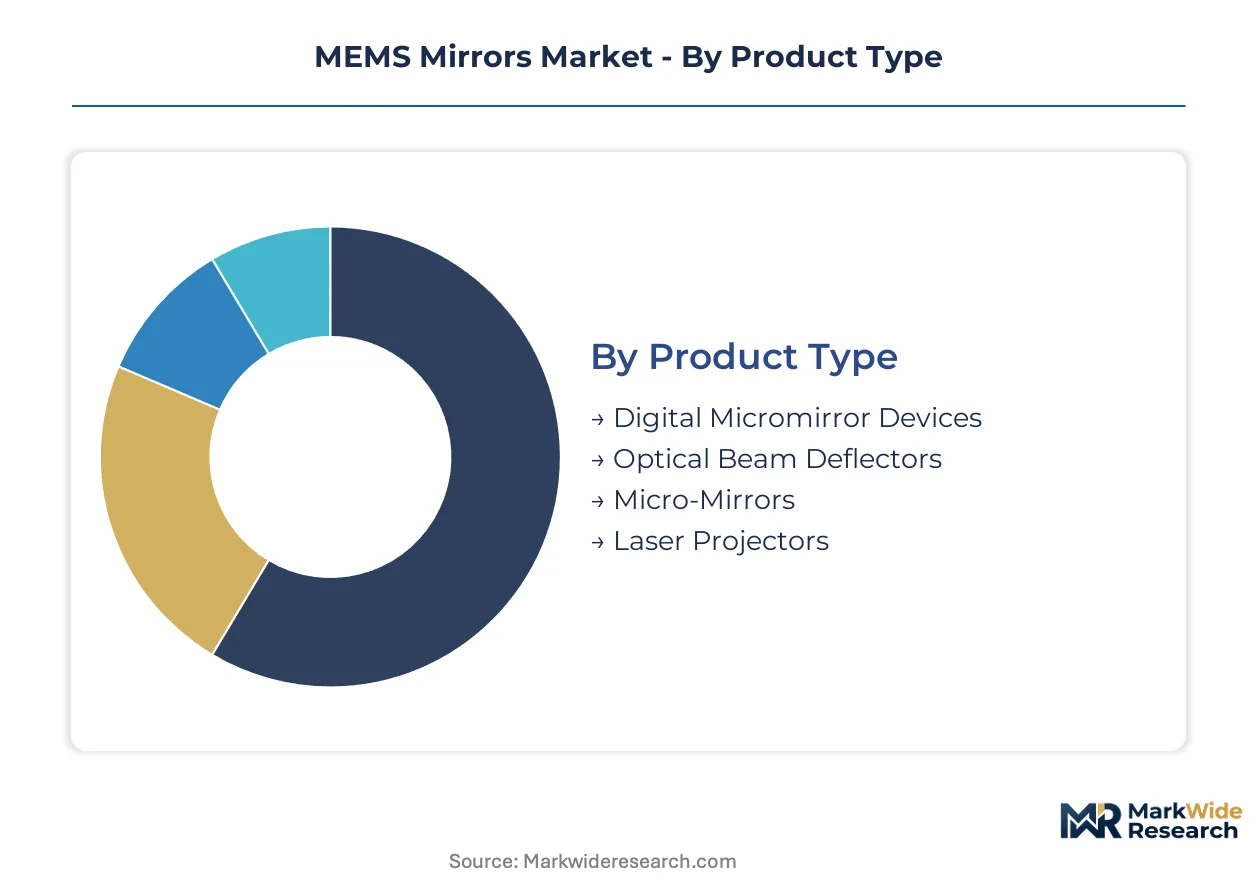
MEMS mirror procurement patterns diverge sharply across actuation physics and end-use reliability requirements. Automotive lidar qualification protocols and medical imaging stability standards create incompatible sourcing pools that fragment supplier capabilities across segment boundaries.
Product Type:
Supply concentration in Texas Instruments' foundry operations anchors digital micromirror device availability, while optical beam deflector capacity disperses across specialized MEMS houses serving automotive qualification timelines.
- Digital Micromirror Devices:Aluminum micromirror arrays on CMOS substrates deliver binary or grayscale modulation at megahertz refresh rates. Legacy projector demand in education and cinema sectors sustains volume production, though automotive lidar procurement is compressing foundry allocation timelines.
- Optical Beam Deflectors:Gimbal-mounted mirrors achieve continuous angular sweep with microsecond settling times. Stuttgart and Munich OEMs are consolidating procurement around electromagnetic variants for next-generation solid-state lidar platforms, forcing tier-1 suppliers to absorb ISO 26262 certification costs.
- Micro-Mirrors:Compact die-level devices serve research instrumentation and optical switching applications.
- Laser Projectors:RGB combiner architectures integrate multiple MEMS elements for pico-projection and head-up displays.
Digital micromirror devices absorb the bulk of installed capacity; optical beam deflectors are expanding most quickly.
Technology:
Cost tier stratification separates CMOS-compatible electrostatic platforms from premium piezoelectric variants commanding medical imaging price multiples.
- Electrostatic:Comb-drive or parallel-plate electrodes fabricated in standard CMOS foundries enable sub-dollar die costs at million-unit scales. Angular deflection limits of several degrees constrain long-range lidar specifications, compressing electrostatic architectures into short-range automotive and consumer proximity sensing.
- Piezoelectric:Lead zirconate titanate thin films deposited on silicon substrates achieve nanoradian stability with hysteresis below 0.1%. FDA device classification rules in the United States create premium positioning for surgical navigation and ophthalmic imaging systems where drift tolerance is non-negotiable.
- Electromagnetic:Voice-coil or Lorentz force actuation delivers larger angular excursions with linear response characteristics.
- Thermal:Bimorph structures exploit coefficient-of-expansion mismatch for low-cost, moderate-speed beam steering.
Electrostatic platforms dominate unit shipments; piezoelectric variants capture the steepest price premiums.
End User:
Application maturity splits the installed base between legacy consumer projection and emerging automotive sensing volumes.
- Automotive:Solid-state lidar integration mandates under the EU Green Deal framework are accelerating electromagnetic MEMS procurement. German OEM engineering teams have established captive development offices inside foundry operations, collapsing traditional supplier tier structures from five layers to three.
- Medical Devices:FDA 510(k) clearance pathways and EU MDR conformity assessment procedures impose multi-year validation cycles. Piezoelectric architectures with documented reliability under thermal cycling capture surgical navigation and endoscopic imaging demand.
- Consumer Electronics:Pico-projector and head-up display applications sustain digital micromirror device volumes.
- Industrial Applications:Machine vision and laser marking systems source electromagnetic deflectors from Japanese R&D centers.
Automotive procurement is gaining share fastest; consumer electronics retains the largest cumulative installed base.
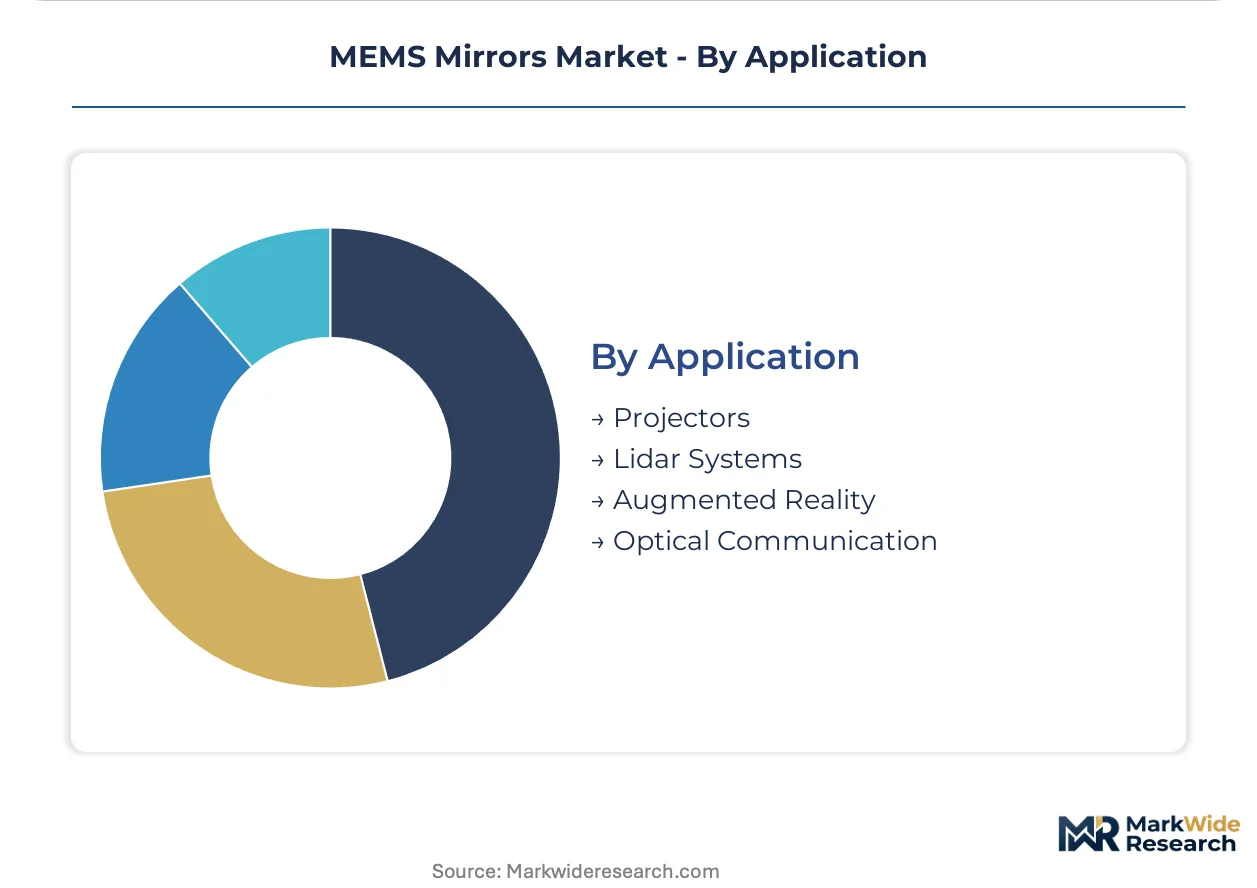
Application:
Customer type concentration in top-10 automotive OEMs is forcing direct procurement contracts that displace distributor-mediated supply relationships in lidar mirror categories.
- Lidar Systems:Solid-state beam steering eliminates rotating mechanical assemblies, reducing form factor and improving shock tolerance. BMW, Mercedes-Benz, and Volkswagen Group procurement offices in Germany are consolidating qualification around vertically integrated MEMS foundries with in-house thermal cycling and vibration test capabilities.
- Projectors:Cinema and education display markets sustain digital micromirror device demand with predictable replacement cycles.
- Augmented Reality:Waveguide-coupled MEMS scanning mirrors enable retinal projection and laser beam scanning architectures.
- Optical Communication:Free-space optical links and fiber switching matrices employ micro-mirror arrays for wavelength routing.
Projector applications retain the deepest installed base; lidar systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart automotive cluster and Saxony's Silicon Saxony semiconductor corridor concentrate MEMS mirror foundry investment through federal tax incentives for autonomous vehicle component manufacturing.
United States
FDA device classification rules and NHTSA autonomous vehicle guidance shape dual demand tracks for medical imaging and automotive lidar mirrors. Texas and Arizona semiconductor corridors host captive engineering offices serving Detroit OEM qualification programs. Boston and San Francisco research clusters drive tip-tilt-piston architecture procurement for laboratory instrumentation.
Germany
KBA type-approval requirements and EU AI Act CE marking timelines compress supplier qualification windows to 24 months. Stuttgart and Munich OEM engineering teams have established direct development partnerships inside MEMS foundry operations. Bavaria's automotive supplier ecosystem anchors electromagnetic actuation procurement for solid-state lidar platforms.
Japan
METI's semiconductor revitalization subsidies and PMDA medical device regulations bifurcate demand between industrial inspection and surgical navigation applications. Hamamatsu's photonics corridor sustains R&D intensity in electromagnetic architectures. Nagoya automotive engineering centers integrate chip-scale deflectors into tier-1 lidar module supply.
China
MIIT automotive intelligence mandates and GB standards for lidar performance specifications accelerate domestic MEMS mirror foundry capacity expansion. Yangtze River Delta packaging houses are migrating from mechanical galvo-mirror assembly to solid-state chip-scale integration. Shenzhen consumer electronics clusters sustain pico-projector demand for digital micromirror device variants.
South Korea
MFDS medical device clearance pathways and Ministry of Trade semiconductor support programs split procurement between imaging stability requirements and automotive sensing volumes. Seoul Capital Area foundries are qualifying electromagnetic architectures for Hyundai-Kia lidar integration programs. Busan industrial automation clusters source beam deflectors for machine vision retrofit installations.
MEMS Mirrors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive lidar procurement consolidating around vertically integrated foundries while medical imaging tolerates distributed supply chains. The vendor base organizes into three tiers: captive semiconductor divisions serving captive OEM demand, independent MEMS houses with ISO 26262 certification capacity, and research-oriented specialists supplying low-volume precision applications. Dominant competitive moves include backward integration into wafer-level packaging and strategic partnerships collapsing traditional five-layer supplier tiers into three-layer direct procurement structures.
Among US-based fabricators, Texas Instruments and Boston Micromachines Corporation occupy positions at opposite ends of the scale-specialization spectrum, while Hamamatsu Photonics represents the Japanese vertically integrated archetype with domestic R&D-to-production control. Mirrorcle Technologies exemplifies the research-channel specialist model serving university and government laboratory procurement with configurable tip-tilt-piston architectures. These three company structures illustrate how geographic clustering and end-use focus determine competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Mirrorcle Technologies |
| Hamamatsu Photonics |
| MicroVision |
| Texas Instruments |
| Sercalo Microtechnology |
| OQmented |
| Boston Micromachines Corporation |
| Opus Microsystems |
| Preciseley Microtechnology |
| Others |
Supply & Pricing Matrix
Silicon-on-insulator wafer migration from bulk-micromachined substrates simultaneously compresses die warpage defects and concentrates foundry bargaining power among German and Japanese automotive tier-1 suppliers. This substrate transition reshapes cost economics at the wafer level while tightening supply concentration around vertically integrated MEMS houses with in-house optical flatness testing.
Pricing Analysis
Volume production of electrostatic MEMS mirrors runs on per-unit transactional pricing at sub-dollar die costs, while piezoelectric variants command premium-mid-economy pricing differentiation based on FDA certification tiers and nanoradian stability specifications. Price differentiation hinges on ISO 26262 functional safety compliance and electromagnetic actuation performance grades. Cost compression in automotive lidar tiers is intensifying because OEM procurement offices are consolidating direct contracts and absorbing warranty liability previously borne by distributors. Consumer electronics buyers exhibit highest price sensitivity, while medical imaging purchasers prioritize drift tolerance over unit economics.
Supply Chain Analysis
EU AI Act local-content rules and CE marking mandates are reshaping sourcing patterns toward German and Japanese foundries with third-party validation capabilities. Geographic supply concentration centers on Germany, Japan, and the United States for electromagnetic and piezoelectric architectures. Raw material dependencies draw from East Asian lead zirconate titanate refineries, Texas CMOS foundry capacity, and Saxony silicon-on-insulator wafer production. Single-source vulnerability in piezoelectric ceramic supply exposes medical imaging mirror producers to input price volatility. Distribution runs through direct procurement contracts displacing traditional distributor tiers in automotive lidar categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state MEMS beam steering is displacing mechanical rotating mirror assemblies across automotive lidar platforms, compressing qualification timelines and collapsing traditional supplier hierarchies. This technology-transition phase demands repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: To counter electromagnetic architecture commoditization from Japanese R&D centers, Texas Instruments and Hamamatsu Photonics should deepen backward integration into silicon-on-insulator wafer processing and captive optical testing. ISO 26262 certification capacity in German automotive clusters represents the priority defensive lever against tier-1 supplier consolidation. For New Entrants and Emerging Players: Research instrumentation channel partners in Boston and San Francisco offer the most penetrable white-space target for tip-tilt-piston architectures with configurable actuation profiles. Industrial inspection systems in Busan and Nagoya present secondary entry points. A demonstration-led go-to-market angle with university procurement offices bypasses automotive qualification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive tier-1 supplier acquisition of electromagnetic MEMS specialists with KBA type-approval track records. Long-term viability across the analysis window favors foundries with in-house thermal cycling and vibration stress validation. The signal to watch is Stuttgart OEM establishment of captive engineering offices inside target foundry operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Processing | Captive silicon-on-insulator supply secures optical flatness control for German automotive OEM qualification. |
| ISO 26262 Certification Investment | Functional safety compliance unlocks direct procurement contracts with Stuttgart and Munich tier-1 suppliers. |
| Research Channel Partnership | University laboratory placements build reference demand for tip-tilt-piston architectures ahead of automotive adoption. |
| Electromagnetic Architecture Scale-Up | Chip-scale deflector production addresses solid-state lidar procurement from BMW, Mercedes-Benz, and Volkswagen Group. |
| Third-Party Validation Capability | In-house thermal cycling and vibration testing satisfies EU AI Act CE marking timelines for autonomous vehicle components. |
Research Methodology
Trade databases, SEC semiconductor capex disclosures, and EU automotive type-approval filings formed the secondary backbone, supplemented by primary interviews with MEMS foundry operations directors, automotive tier-1 procurement leads, FDA regulatory affairs specialists, and university laboratory instrumentation officers. Bottom-up and top-down triangulation validated segment-level assumptions across actuation physics, end-use reliability requirements, and regional regulatory clusters.
Bottom-up modeling of unit economics and foundry capacity utilization combined with top-down demand aggregation from automotive OEM platform engineering disclosures. Segmentation dimensions included actuation technology, mirror architecture type, end-use application, and regional production hub. CAGRs were derived from installed base replacement cycles and emerging solid-state lidar penetration curves, with inputs from piezoelectric material cost trajectories and electromagnetic actuation performance roadmaps.
Caveats apply where EU AI Act certification timeline extensions, lead zirconate titanate supply disruptions, or mechanical lidar incumbent defensive patent actions could materially shift the outlook. Forecasts reflect documented assumptions about automotive platform transition rates and medical imaging stability requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Europe Laser Interferometer Market
Optics
Glass Scintillator Market
Optics
Photonics Market
Optics
Liquid Crystal on Silicon Market
Optics
Fiber-Optic Couplers Market
Optics
Acrylic Lenses Market
Optics
Fiber Optic Development Tools Market
Optics
Optical Telephoto Lens Market
Optics
Excimer Laser Market
Optics
Sports Optics Market
Optics
Smart Photochromic Lenses Market
Optics
Global Semiconductor Lasers Market
Optics
Fiber Optical Receivers Market
Optics
Tunable Laser Market
Optics
India Laser Market
Optics
Optical Sensing Market