
 Adult Malignant Glioma Therapeutics Market | 2026-2036
Adult Malignant Glioma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Adult Malignant Glioma Therapeutics Market Intelligence
The time lag between genomic sequencing and therapeutic decision-making is collapsing, accelerating the adoption of personalized medicine. This shift benefits companies with strong pipelines in targeted therapies. F. Hoffmann-La Roche Ltd leverages its diagnostics capabilities to link specific mutations to its therapeutic agents. Merck & Co., Inc. sustains its market position through extensive clinical trials for its immunotherapy treatments in glioblastoma.
Adult malignant glioma therapeutics encompass a range of pharmaceutical agents designed to combat aggressive brain tumors. These treatments often involve compounds that target specific molecular pathways, such as the IDH1 mutation, or utilize cytotoxic agents to inhibit cell division. The primary objective is to slow tumor progression and extend patient survival. Glioblastoma Multiforme constitutes the largest segment within the therapy area, reflecting its prevalence. Meanwhile, Targeted Therapy Agents and Immunotherapy Treatments are gaining share over traditional chemotherapy due to improved efficacy and safety profiles.
Regulatory oversight from bodies like the US FDA and the EMA dictates the pace of new drug approvals through rigorous clinical trial requirements. In parallel, China's NMPA is streamlining its review processes for innovative cancer drugs, influencing market access strategies. Navigating the complex reimbursement landscapes and designing adaptive clinical trials will be critical for developers seeking to commercialize next-generation glioma therapies.
Market Dynamics
The central structural force shaping the adult malignant glioma therapeutics market is the rapid integration of genomic diagnostics into clinical practice. This collapses the time between tumor profiling and treatment selection, fundamentally altering development priorities and favoring therapies linked to specific, identifiable biomarkers like the IDH1 mutation.
Growth Catalysts
- Advanced Therapeutic Modalities:The development of sophisticated gene therapy and CAR-T cell therapy products is creating entirely new mechanisms of action against gliomas, attracting significant research investment and expanding the therapeutic arsenal beyond conventional chemotherapy.
- Regulatory Streamlining:Initiatives like China's NMPA priority review for innovative cancer drugs and the FDA's Breakthrough Therapy designation are shortening development timelines, encouraging developers to invest in novel glioma treatments.
- Concentrated Care Infrastructure:The expansion of specialized Neuro-Oncology Centers in countries like the United States and Germany concentrates patient populations and clinical trial expertise, accelerating enrollment and data generation for new agents.
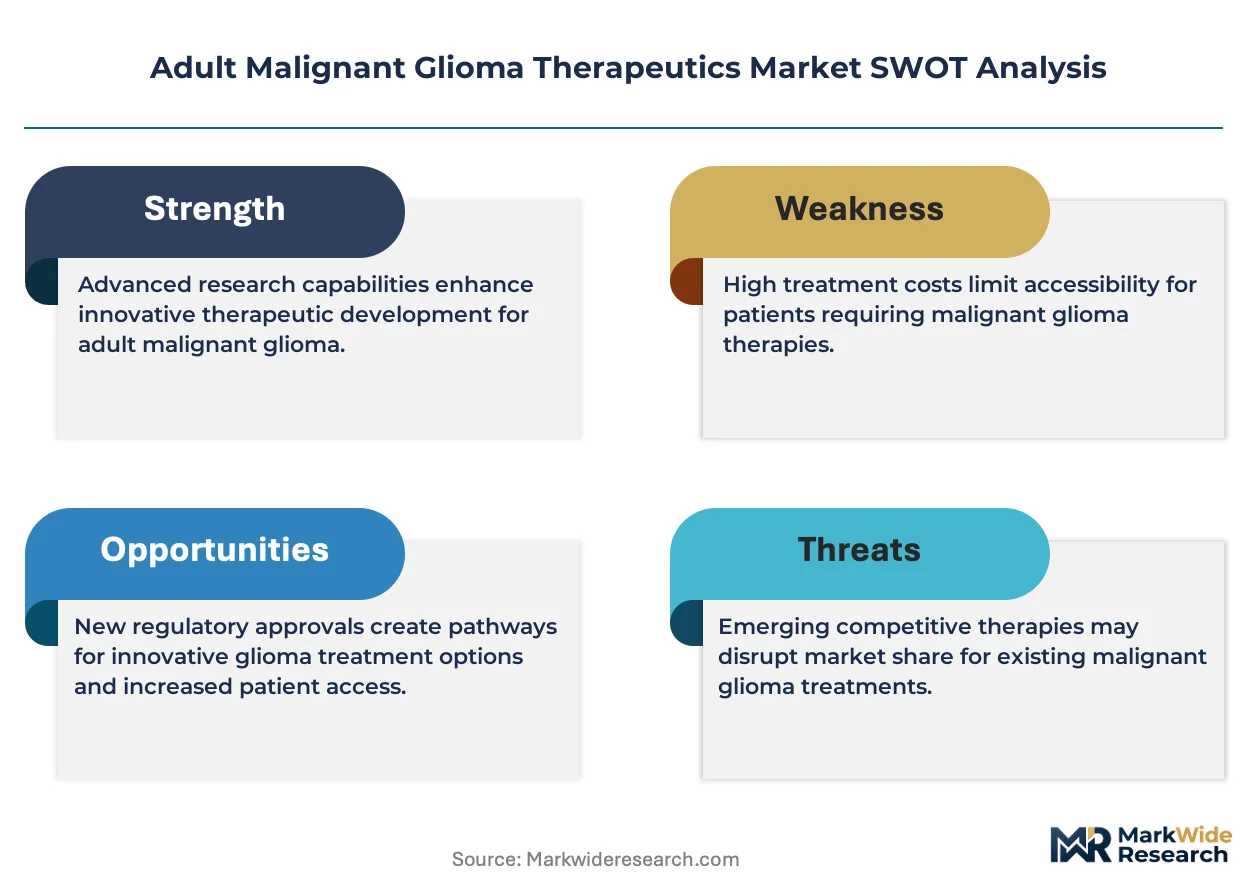
Market Restraints
- High Treatment Costs:The substantial price of targeted therapies and immunotherapies presents a significant barrier to access, leading to restrictive reimbursement policies from payers in both public and private healthcare systems.
- Drug Delivery Challenges:The physiological blood-brain barrier effectively blocks many systemic therapeutic agents from reaching brain tumors in sufficient concentrations, limiting the efficacy of potentially potent compounds.
- Complex Clinical Trial Pathways:Stringent evidence requirements from regulatory bodies such as the EMA and FDA necessitate large, long, and expensive clinical trials, which can be particularly challenging for rare glioma subtypes.
Strategic Opportunities
- Combination Therapy Regimens:Investigating novel combinations of immunotherapy, targeted agents, and radiation offers a significant opportunity to overcome resistance mechanisms and improve survival outcomes, creating value for developers with diverse portfolios.
- Orphan Drug Incentives:Regulatory frameworks like the Orphan Drug Act in the United States provide market exclusivity and financial incentives for developing treatments for less common forms of glioma, de-risking investment in these areas.
- AI in Drug Discovery:Leveraging artificial intelligence platforms to analyze genomic data and predict patient responses can identify novel drug targets and biomarkers, accelerating the preclinical development phase for next-generation glioma therapies.
Industry Challenges
- Specialized Talent Scarcity:A shortage of trained neuro-oncologists, clinical trial staff, and genomic data scientists impedes the execution of complex trials and the broad adoption of personalized medicine protocols.
- Adaptive Trial Design Complexity:Designing and executing adaptive clinical trials that can incorporate new biomarkers and treatment arms mid-study requires sophisticated statistical expertise and regulatory alignment, posing an operational hurdle.
- Patient Stratification Hurdles:The increasing molecular segmentation of gliomas requires robust and accessible diagnostic testing to accurately identify eligible patient populations for targeted therapies, creating a logistical challenge for healthcare systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adult Malignant Glioma Therapeutics Market |
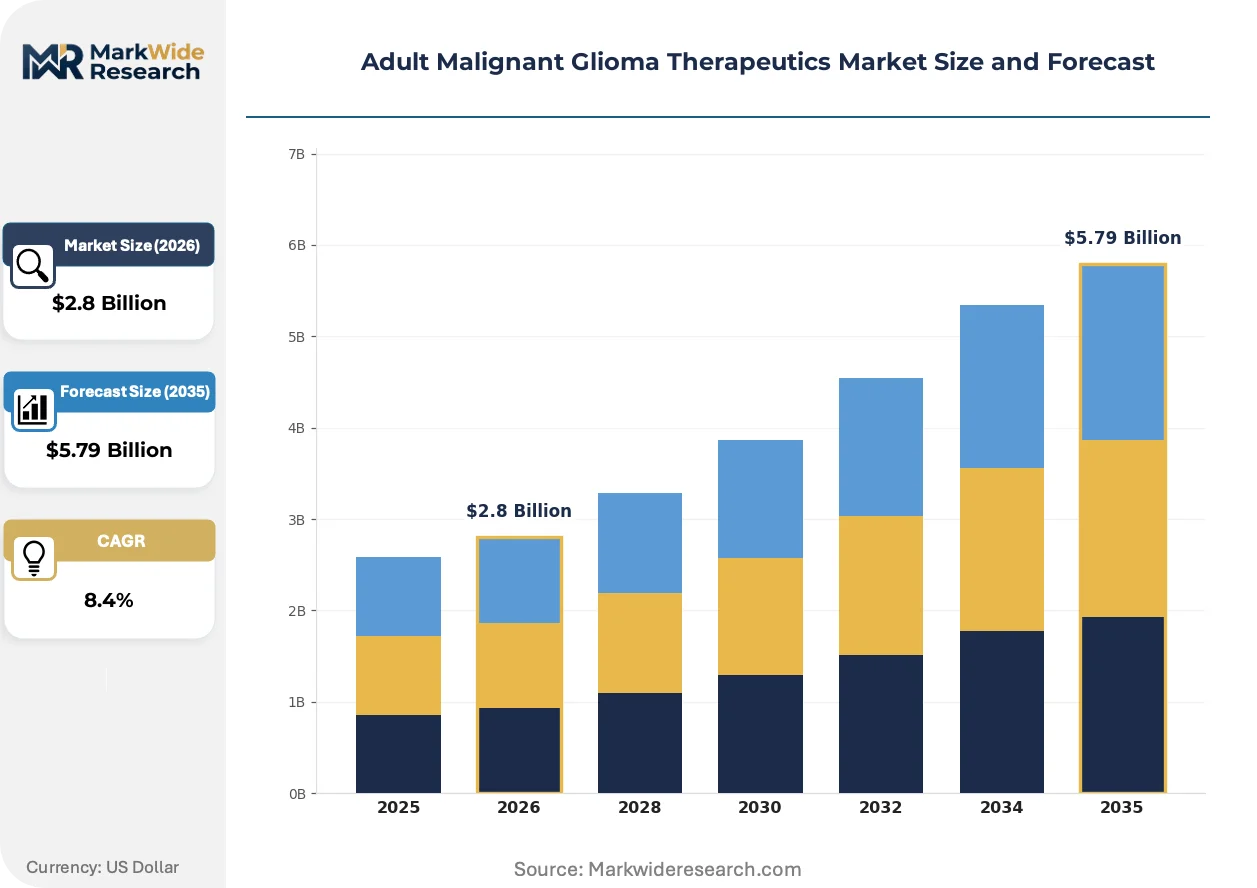
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Drugs, Targeted Therapy Agents, Immunotherapy Treatments, Radiopharmaceuticals, Gene Therapy Products Therapy Area: High-Grade Glioma, Anaplastic Astrocytoma, Glioblastoma Multiforme, Recurrent Glioma, Diffuse Intrinsic Pontine Glioma End User: Neuro-Oncology Centers, Research Institutions, Specialized Clinics, Oncology Hospitals, Academic Medical Centers Delivery Mode: Oral Administration, Intravenous Infusion, Intratumoral Injection, Convection-Enhanced Delivery, Stereotactic Radiosurgery |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sanofi, Novartis AG, AstraZeneca, Bristol-Myers Squibb, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adult Malignant Glioma Therapeutics Market Strategic Shifts & Innovations
The therapeutic landscape for adult malignant glioma is being redefined by the convergence of advanced diagnostics and precision medicine. This shift moves treatment paradigms away from one-size-fits-all chemotherapy and towards mutation-specific interventions, demanding new clinical and commercial strategies from drug developers.
Liquid biopsy technologies are enabling the non-invasive monitoring of tumor-specific genetic markers, such as IDH1 mutations and MGMT promoter methylation, directly from patient blood samples. Neuro-oncology centers across the United States and Europe are adopting these tools for disease surveillance and response assessment. This capability is fragmenting the patient population into smaller, genetically-defined subgroups that require hyper-targeted therapies rather than broad-spectrum agents.
The European Medicines Agency's PRIME scheme provides enhanced scientific and regulatory support for medicines targeting significant unmet needs. This initiative accelerates the clinical assessment of promising glioma therapeutics, offering a faster path to market authorization. Developers of cell-based therapies and novel radiopharmaceuticals are most affected, adjusting their European development strategies to qualify for the program and engage with regulators earlier.
A distinct change is occurring in how clinical evidence is valued by both regulators and payers, with a greater emphasis on real-world data. This involves collecting and analyzing data from electronic health records, patient registries, and digital health applications to supplement traditional clinical trial results. This trend is most apparent in post-market surveillance in the US, influencing reimbursement decisions and label expansion efforts for approved glioma drugs.
Adult Malignant Glioma Therapeutics Market Segmentation
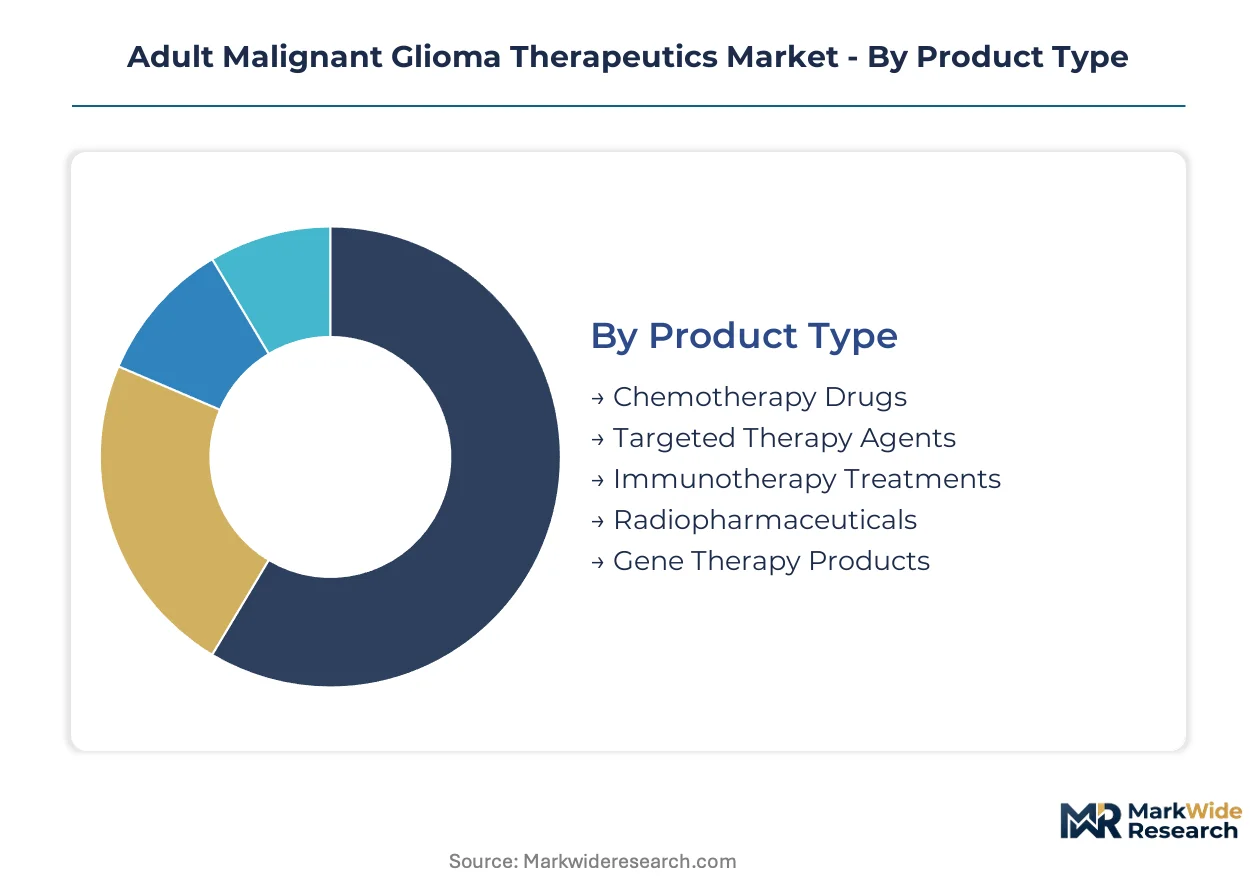
The adult malignant glioma therapeutics market segments by product type, therapy area, end user, and delivery mode. Understanding these distinctions helps developers target specific patient populations and treatment modalities. Each segment reflects unique clinical needs and commercial opportunities for novel interventions.
Product Type:
Substitution pressure is intense within product types, as newer, more effective agents displace traditional treatments. This dynamic drives continuous innovation in drug development.
- Targeted Therapy Agents:These compounds specifically inhibit molecular pathways implicated in tumor growth, such as IDH1 mutations. Demand concentrates in the United States, where genomic sequencing rapidly identifies eligible patients.
- Immunotherapy Treatments:These therapies harness the body's immune system to recognize and destroy cancer cells, often through checkpoint inhibitors. Clinical trials in Germany and France demonstrate their potential for improved patient outcomes.
- Chemotherapy Drugs:Traditional cytotoxic agents like Temozolomide inhibit cell division, serving as a foundational treatment for many glioma patients.
- Radiopharmaceuticals:These agents combine radioactive isotopes with tumor-targeting molecules to deliver localized radiation directly to cancer cells.
- Gene Therapy Products:Advanced genetic engineering techniques introduce therapeutic genes into glioma cells, aiming to correct molecular defects or induce cell death.
Chemotherapy Drugs anchor the volume base while Immunotherapy Treatments gain share at the steepest rate.
Therapy Area:
The volume of patients within each therapy area directly influences research and development priorities for drug developers. Larger patient populations attract greater investment.
- Glioblastoma Multiforme:This aggressive brain tumor represents the largest patient segment within malignant gliomas, driving significant research into new drug candidates. Treatment centers in the United Kingdom focus on improving survival rates for these patients.
- High-Grade Glioma:This category encompasses various fast-growing and invasive brain tumors, requiring complex, multi-modal treatment approaches. Neuro-oncology centers in Canada increasingly adopt personalized medicine for these cases.
- Anaplastic Astrocytoma:This less common but still aggressive glioma type requires tailored therapeutic strategies based on molecular profiling.
- Recurrent Glioma:Patients whose tumors return after initial treatment present a significant challenge, necessitating novel therapies to overcome resistance mechanisms.
- Diffuse Intrinsic Pontine Glioma:This rare and highly aggressive pediatric brain tumor has very limited treatment options, spurring focused research efforts.
Glioblastoma Multiforme commands the largest patient volume, with Diffuse Intrinsic Pontine Glioma expanding most quickly due to unmet need.
End User:
The specialization of end-user facilities dictates the complexity of treatments and diagnostic tools they can deploy. Highly specialized centers drive advanced therapy adoption.
- Neuro-Oncology Centers:These specialized facilities integrate multidisciplinary care, including advanced diagnostics and clinical trials, for brain tumor patients. Demand for specialized care is high in urban centers across the United States.
- Oncology Hospitals:Comprehensive cancer treatment hospitals provide a broad range of services, including chemotherapy and radiation, to a diverse patient population. These hospitals serve as primary treatment hubs in many European nations.
- Research Institutions:These organizations focus on preclinical and early-phase clinical research, developing new therapeutic agents and understanding disease mechanisms.
- Specialized Clinics:Smaller clinics offer targeted treatments or follow-up care, often collaborating with larger hospitals for complex cases.
- Academic Medical Centers:These institutions combine patient care with medical education and research, often participating in cutting-loop clinical trials.
Neuro-Oncology Centers lead in advanced treatment adoption, while Oncology Hospitals manage the largest patient throughput.
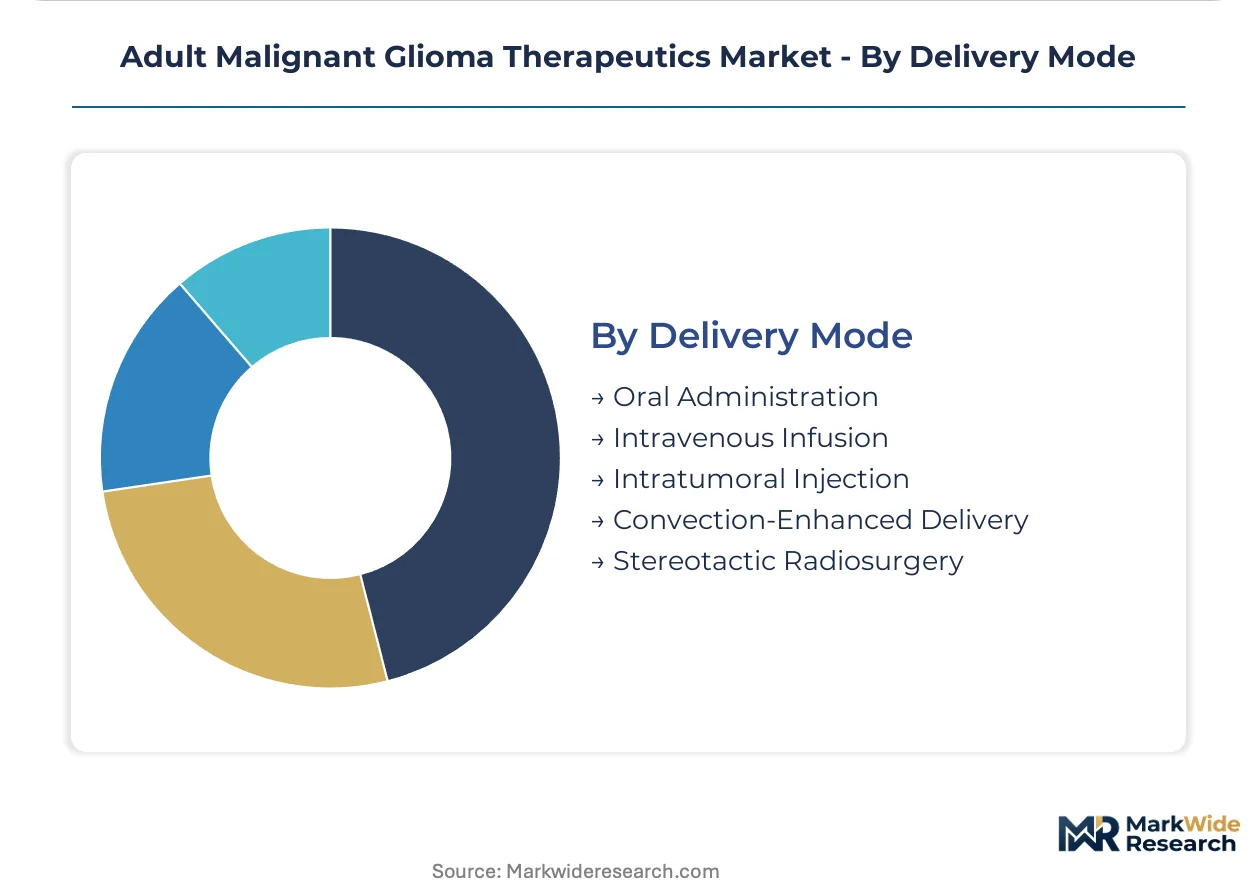
Delivery Mode:
The innovation and complexity of drug delivery modes influence patient compliance and therapeutic efficacy. Overcoming the blood-brain barrier remains a key challenge.
- Intravenous Infusion:Systemic administration through a vein ensures widespread drug distribution, a common method for chemotherapy and immunotherapy. This method is standard in hospitals and clinics globally.
- Oral Administration:Patients take these drugs by mouth, offering convenience and enabling at-home treatment. The United States sees high patient preference for oral options.
- Intratumoral Injection:Direct injection into the tumor allows for high local drug concentrations, minimizing systemic side effects.
- Convection-Enhanced Delivery:This technique uses continuous pressure to deliver therapeutic agents directly into brain tissue, bypassing the blood-brain barrier.
- Stereotactic Radiosurgery:Highly focused radiation beams precisely target tumors, minimizing damage to surrounding healthy tissue.
Intravenous Infusion remains the most established delivery mode, and Convection-Enhanced Delivery shows significant promise in overcoming physiological barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's rigorous approval processes anchor advancements in adult malignant glioma therapeutics. This regulatory environment fosters significant research and development investments, particularly in novel gene therapies and personalized medicine approaches. Demand for innovative treatments is also high in other developed economies with robust healthcare infrastructures.
United States
Demand for adult malignant glioma therapies in the United States is driven by a high prevalence of cases and substantial R&D investment. The FDA's Breakthrough Therapy designation accelerates the review of promising new agents, encouraging pharmaceutical innovation. Major biotech clusters in Boston and the San Francisco Bay Area lead in developing gene therapies and targeted agents.
Germany
Germany maintains a strong position in clinical trials for glioma treatments, supported by advanced neuro-oncology centers. The European Medicines Agency (EMA) oversees drug approvals, ensuring high efficacy and safety standards for new therapies. Research hubs in Berlin and Munich actively contribute to immunotherapy and targeted therapy advancements.
China
China's market for malignant glioma therapeutics is expanding due to a large patient population and regulatory streamlining. The NMPA is actively prioritizing the review of innovative cancer drugs, improving market access for novel treatments. Pharmaceutical centers in Shanghai and Guangzhou are becoming key sites for both clinical research and manufacturing.
United Kingdom
The United Kingdom focuses on improving survival rates for glioma patients, especially within its specialized neuro-oncology units. NICE guidelines influence the adoption and reimbursement of new therapeutic agents, emphasizing cost-effectiveness and clinical benefit. London and Cambridge serve as prominent research and clinical trial centers for brain tumor therapies.
Adult Malignant Glioma Therapeutics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the adult malignant glioma therapeutics market. The competitive structure is tiered, featuring global pharmaceutical companies, specialized biotechnology firms, and academic research institutions. These archetypes often engage in strategic partnerships, portfolio diversification, and technology licensing to advance their market positions.
Global pharmaceutical companies, such as Merck & Co., Inc., F. Hoffmann-La Roche Ltd, and Novartis AG, exemplify broad market presence and extensive R&D capabilities. These entities leverage their diagnostic capabilities and clinical trial networks to bring novel targeted therapies and immunotherapies to market. Their scale allows for significant investment in complex clinical development pathways and global regulatory navigation.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Novartis AG |
| AstraZeneca |
| Bristol-Myers Squibb |
| Amgen Inc. |
| Others |
Cost & Logistics Intelligence
Specialized reagent procurement lead times, often exceeding six months, directly influence the adult malignant glioma therapeutics supply chain shape, contributing to concentrated production and supporting premium pricing for novel therapies.
Pricing Analysis
Significant geographic price spreads exist for malignant glioma therapeutics, particularly between the United States and European markets. Value-based pricing dominates for innovative targeted therapies and immunotherapies, reflecting clinical efficacy and regulatory designations like FDA Breakthrough Therapy status. Upward pricing pressure persists due to high R&D costs and complex clinical trial requirements. Public healthcare systems, such as those in the UK, exhibit higher price sensitivity compared to private payers in the US.
Supply Chain Analysis
Strategic stockpiling of critical raw materials and complex intermediates characterizes the adult malignant glioma therapeutics supply chain, moving away from pure just-in-time models. Manufacturing concentrates in the United States and Germany, with China emerging as a key API source. The industry relies heavily on specialized biologics, viral vectors for gene therapies, and complex small molecule APIs. Single-source vulnerability for highly specialized components and cold chain logistics for biologics pose significant structural risks. Distribution runs through highly specialized channels, often direct-to-neuro-oncology centers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adult malignant glioma therapeutics market presents a significant service-attach opportunity. Diagnostic testing and ongoing patient monitoring services, critical for personalized medicine, are expanding faster than the core drug sales, creating new revenue streams.
For Market Incumbents: Fortify existing market positions by accelerating pipeline diversification into novel combination therapies. Integrate diagnostic capabilities more deeply to link specific mutations with therapeutic agents. Expand global clinical trial networks to maintain leadership in glioblastoma treatments. This strategy addresses the threat from specialized gene therapy firms and increasingly stringent reimbursement policies across Europe.
For New Entrants and Emerging Players: Anchor in underserved rare glioma subtypes, such as Diffuse Intrinsic Pontine Glioma, leveraging orphan drug incentives. Focus on AI-driven drug discovery platforms to identify novel targets and accelerate preclinical development. Target specific biomarker-driven niches with hyper-targeted therapies offering superior efficacy. Utilize adaptive clinical trial designs to rapidly generate evidence and accelerate regulatory approval through schemes like EMA's PRIME.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger pharmaceutical entities divesting non-core neuro-oncology assets or from smaller biotech firms with promising early-stage pipelines. The market shows strong long-term growth potential over the next 5-10 years due to significant unmet medical needs and continuous therapeutic innovation. Seek specialized biotech firms with advanced gene therapy platforms or proprietary diagnostic intellectual property. Successful Phase 2/3 clinical trial data for novel modalities or NMPA fast-track approvals in China indicate significant value inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates evidence generation for new targeted agents and immunotherapies in glioblastoma. |
| Regulatory Approval Pathway Optimization | Streamlines market access for innovative therapies through FDA Breakthrough and EMA PRIME designations. |
| Licensing Agreements for Gene Therapy IP | Expands therapeutic portfolios with advanced genetic engineering techniques for malignant glioma. |
| Manufacturing Scale-Up for Biologics | Ensures consistent supply of complex immunotherapies and gene therapy products to neuro-oncology centers. |
| Pipeline Diversification into Combination Therapies | Addresses drug resistance mechanisms and improves patient survival outcomes across various glioma types. |
Research Approach
The analysis maps adult malignant glioma therapeutics sub-sectors, each validated through extensive primary interviews with key industry stakeholders. Engagements included neuro-oncologists, pharmaceutical R&D executives, regulatory affairs specialists, and hospital procurement managers. Secondary validation involved rigorous review of FDA filings, EMA submissions, ClinicalTrials.gov data, and peer-reviewed academic journals. A bottom-up and top-down triangulation approach ensured data accuracy and comprehensive market sizing.
Forecast outputs were rigorously cross-referenced against external benchmarks and validated through a multi-factor analytical framework across the analysis window. The model segmented the market by product type, therapy area, end user, delivery mode, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected future adoption rates. Key forecast inputs included clinical trial success rates for novel agents and new drug approval rates from major regulatory bodies.
Material uncertainties — including unforeseen regulatory changes or unexpected clinical trial failures — sit outside the modeled envelope. Forecasts inherently reflect a set of underlying assumptions about market evolution. Revision becomes warranted when these critical assumptions or risk factors cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Polychondritis Disease Treatment Market