
 Global Scleroderma Therapeutics Market | 2026-2036
Global Scleroderma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scleroderma Therapeutics Market Foresight
Market Context with Strategic Players
The capital-intensity divergence between large-cap biopharmaceutical platforms and mid-cap immunology specialists is reorganizing competitive dynamics in scleroderma therapeutics. F. Hoffmann-La Roche Ltd leverages its deep biologics manufacturing infrastructure to sustain dominance in systemic therapy supply. Bristol-Myers Squibb Company anchors its position through autoimmune franchise breadth, while Corbus Pharmaceuticals Holdings, Inc. differentiates via concentrated fibrosis-targeting R&D pipelines.
Technical Definition and Structural Segments
Scleroderma therapeutics comprise pharmaceutical agents modulating immune dysregulation, vascular pathology, and fibrotic tissue remodeling in systemic sclerosis, with formulations ranging from small-molecule immunosuppressants to monoclonal antibody biologics requiring cold-chain distribution. These therapies serve to halt disease progression, manage organ involvement, and improve survival outcomes in a condition with historically limited treatment options. Biologics command premium positioning due to targeted mechanism complexity, while immunosuppressants occupy the volume base through established oral and intravenous protocols. The therapy area dimension shows diffuse cutaneous systemic sclerosis generating the most intensive therapeutic intervention, whereas limited cutaneous forms sustain steady demand through vasodilator maintenance regimens.
Regulatory Frame and Forward-Looking Close
The FDA orphan drug program, EMA's accelerated assessment pathway, and Japan's PMDA sakigake designation collectively shape development incentives and market access timelines for novel scleroderma compounds. REACH compliance in Europe and FDA good manufacturing practice standards dictate formulation purity thresholds and clinical trial documentation burdens that filter participant pools. Stakeholders must monitor how evolving biomarker qualification standards across FDA and EMA frameworks will reshape patient stratification and trial endpoint definitions.
Market Dynamics
The FDA orphan drug designation framework is compressing clinical trial timelines while concentrating R&D investment among biopharmaceutical platforms with existing biologics infrastructure. This regulatory acceleration is restructuring competitive entry barriers around manufacturing scale rather than discovery capability alone.
Growth Catalysts
- EMA Accelerated Assessment Pathway:European regulators compress marketing authorization review periods for systemic sclerosis therapies addressing unmet medical need. German rheumatology centers expand patient access to novel biologics through this mechanism.
- Japan Sakigake Designation:PMDA priority review incentives attract fibrosis-focused drug developers to conduct pivotal trials in Japanese academic medical centers clustered in Tokyo and Osaka.
- Academic Medical Hub Concentration:Specialized scleroderma centers in the United States generate concentrated investigator expertise and streamlined patient recruitment for interventional studies.
Market Restraints
- Cold-Chain Distribution Costs:Monoclonal antibody formulations require temperature-controlled logistics infrastructure that elevates per-dose delivery expenses and limits pharmacy dispensing flexibility.
- Biomarker Qualification Uncertainty:FDA and EMA have not harmonized surrogate endpoint acceptance criteria for fibrosis regression, forcing sponsors to design parallel trial protocols.
- Specialized Infusion Center Scarcity:Biologic administration depends on rheumatology clinics with trained nursing staff, creating geographic access gaps outside major metropolitan areas.
Strategic Opportunities
- Brazil ANVISA Priority Review:Latin America's largest pharmaceutical market offers expedited pathways for orphan indications that could anchor regional expansion before broader BRIC entry.
- Subcutaneous Formulation Innovation:Self-administration delivery systems would shift administration from infusion centers to home settings, expanding addressable patient populations.
- Digital Biomarker Integration:Wearable devices capturing skin stiffness and digital thermography data are converging with electronic patient-reported outcomes to enable decentralized trial models.
Industry Challenges
- Fibrosis Biologist Talent Scarcity:Deep expertise in myofibroblast biology and extracellular matrix dynamics remains concentrated among a limited pool of academic researchers.
- Legacy Immunosuppressant Protocol Inertia:Established cyclophosphamide and mycophenolate mofetil regimens create clinical practice barriers to biologic adoption despite superior efficacy signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scleroderma Therapeutics Market |
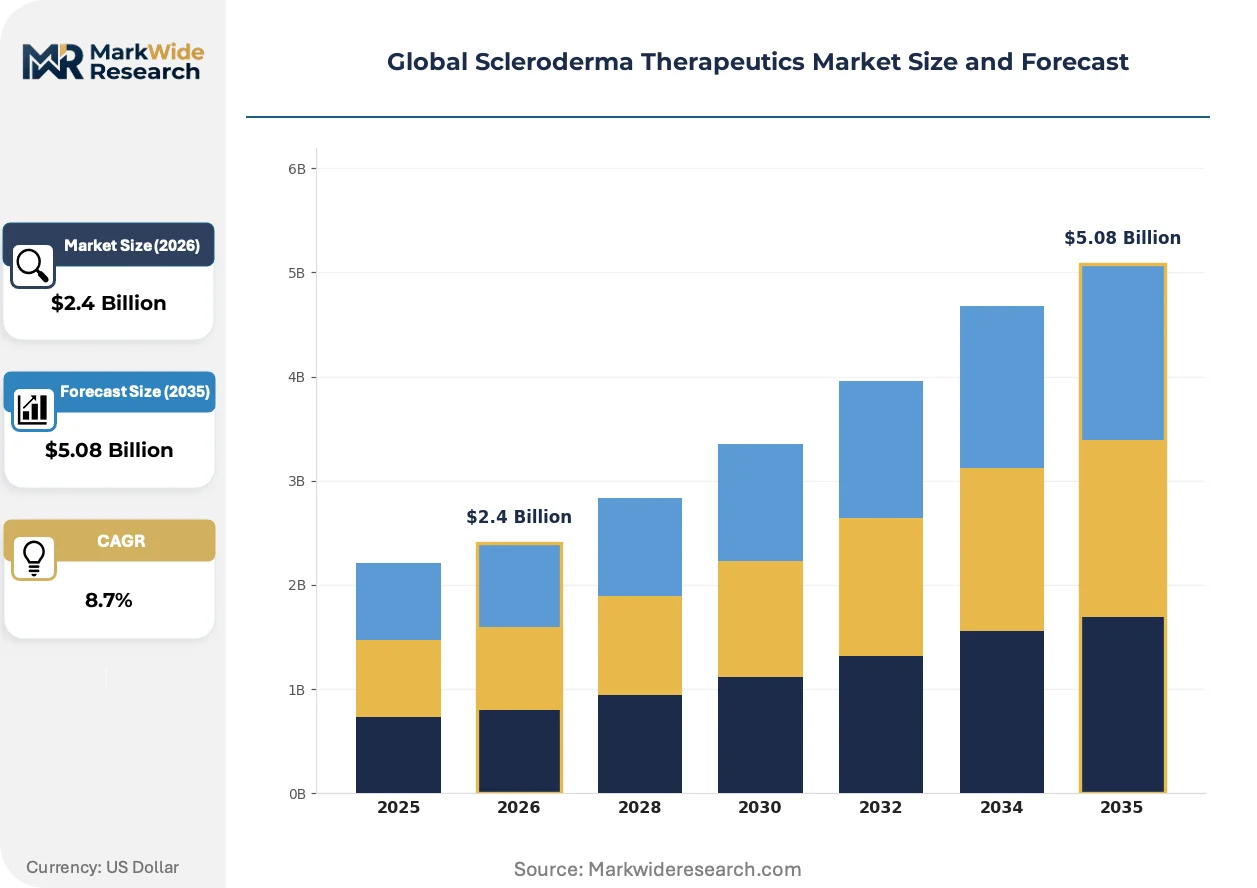
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Vasodilators, Antifibrotics, Corticosteroids, Biologics Therapy Area: Diffuse Cutaneous, Limited Cutaneous, Systemic, Localized, Overlap Syndromes End User: Rheumatology Clinics, Specialized Centers, Clinical Research Institutes, Diagnostic Labs Delivery Mode: Oral, Intravenous, Subcutaneous, Topical, Inhalation |
| Companies Covered | F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Bayer AG, Boehringer Ingelheim International GmbH, Sanofi, Corbus Pharmaceuticals Holdings, Inc., Novartis AG, GlaxoSmithKline plc, Actelion Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scleroderma Therapeutics Market Shifts & Advancements
Targeted fibrosis pathway modulation is displacing broad immunosuppression as the dominant therapeutic paradigm. This shift demands new clinical trial infrastructure and is compressing development timelines for mechanism-specific compounds.
Interleukin-6 receptor antagonists are supplanting conventional disease-modifying antirheumatic drugs in first-line systemic sclerosis protocols. Rheumatology clinics in the United States and Germany are adopting tocilizumab-based regimens for early diffuse cutaneous disease. This mechanism-specific approach is enabling patient stratification by autoantibody profile and organ involvement pattern rather than treating all systemic sclerosis as a uniform indication.
REACH compliance requirements in Europe are elevating purity thresholds for biologic active pharmaceutical ingredients used in scleroderma formulations. EMA's evolving impurity guidelines now demand extended characterization of host cell protein residuals. Contract manufacturing organizations serving European markets are responding by retrofitting purification trains with additional chromatography steps.
Patient advocacy organizations are consolidating purchasing influence through specialty pharmacy networks that negotiate directly with manufacturers. United States-based scleroderma foundations now channel members toward preferred infusion centers with outcome transparency agreements. This aggregation is most visible in California and New York, where foundation-affiliated centers command volume-based rebates previously reserved for national payers.
Global Scleroderma Therapeutics Market Segmentation
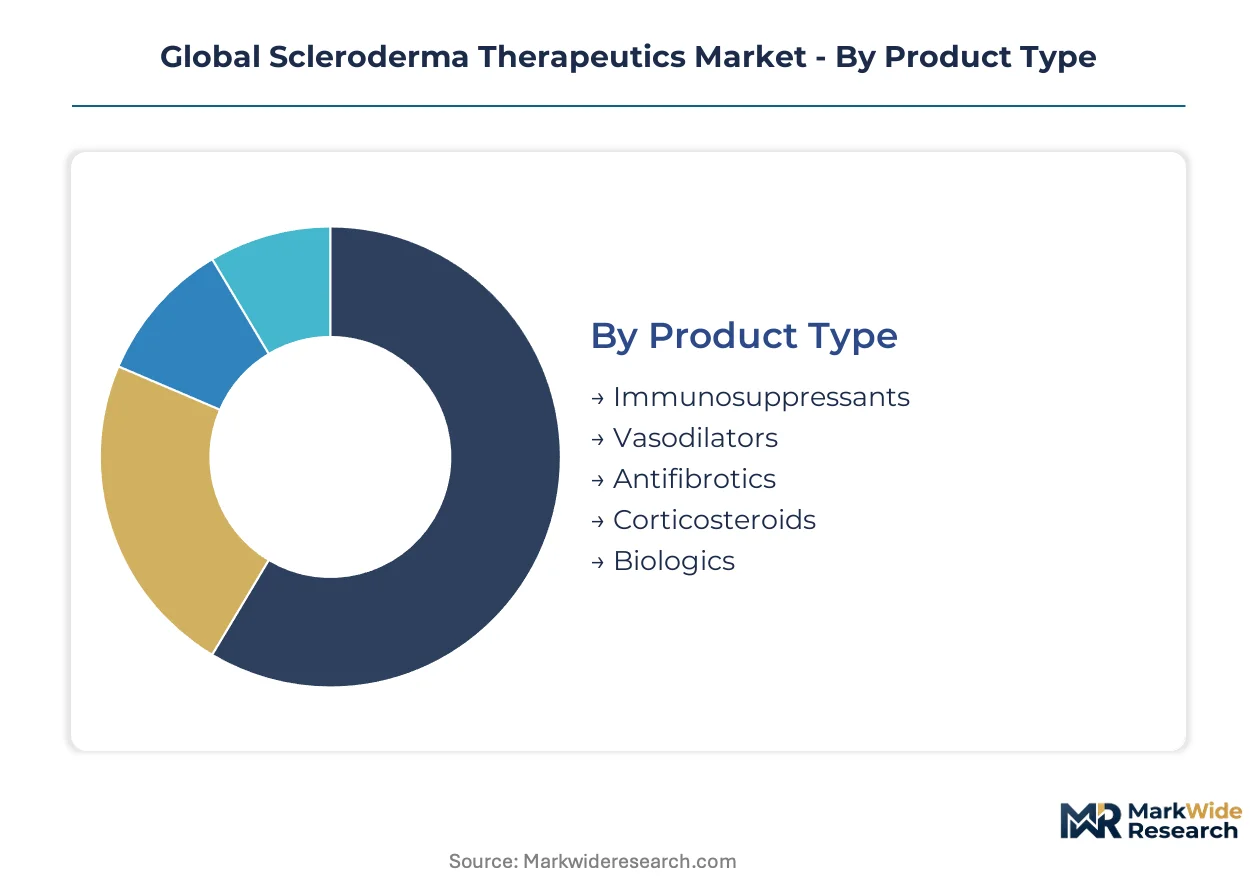
Scleroderma therapeutics segmentation reveals how treatment paradigms fragment across mechanism of action, disease phenotype, and care delivery infrastructure. Understanding these divides exposes where substitution pressures and pricing power concentrate.
Product Type:
Substitution pressure runs strongest against legacy immunosuppressants as biologics and antifibrotics demonstrate superior efficacy signals in head-to-head trials.
- Immunosuppressants:Cyclophosphamide and mycophenolate mofetil formulations dominate current prescription volumes through established oral and intravenous protocols. German rheumatology centers maintain these regimens for cost-sensitive patient segments despite biologic alternatives.
- Biologics:Monoclonal antibodies targeting interleukin-6 and B-cell pathways command premium positioning. United States academic medical centers in Boston and San Francisco drive adoption through specialized infusion infrastructure.
- Vasodilators:Calcium channel blockers and prostacyclin analogs address vascular manifestations in limited cutaneous disease.
- Antifibrotics:Transforming growth factor-beta inhibitors and tyrosine kinase antagonists target myofibroblast activation pathways.
- Corticosteroids:Prednisone and methylprednisolone serve acute inflammatory flares rather than maintenance therapy.
Immunosuppressants retain volume leadership; biologics hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates intensive intervention in diffuse disease from maintenance regimens in limited forms.
- Diffuse Cutaneous:Rapid skin thickening and internal organ involvement drive the highest per-patient pharmaceutical expenditure. Japanese PMDA sakigake designation trials concentrate recruitment in Tokyo-based centers for this population.
- Limited Cutaneous:CREST syndrome variants sustain steady demand for vasodilator and antacid combinations. United Kingdom scleroderma units in Manchester and London manage these patients through primary-secondary care interfaces.
- Systemic:Multi-organ involvement requires combination therapy approaches across immunosuppressant and biologic classes.
- Localized:Morphea and linear scleroderma variants in pediatric populations drive topical formulation demand.
- Overlap Syndromes:Mixed connective tissue disease presentations complicate diagnostic categorization and therapeutic targeting.
Diffuse cutaneous commands the premium tier; limited cutaneous sustains the broadest addressable base.
End User:
Application concentration determines where novel therapies achieve first commercial traction versus where volume prescriptions accumulate.
- Rheumatology Clinics:Community and hospital-based practices generate the highest prescription volumes through established referral networks. France's ANSM-regulated centers in Paris and Lyon anchor European biologic adoption.
- Specialized Centers:Academic scleroderma programs in Johns Hopkins, University of Pittsburgh, and Leiden University Medical Center concentrate investigator expertise and trial recruitment.
- Clinical Research Institutes:Contract research organizations and academic medical centers conduct interventional studies under FDA and EMA protocols.
- Diagnostic Labs:Autoantibody testing facilities in Munich and Osaka stratify patients for mechanism-specific therapy selection.
Rheumatology clinics retain volume leadership; specialized centers hold the steepest expansion curve.
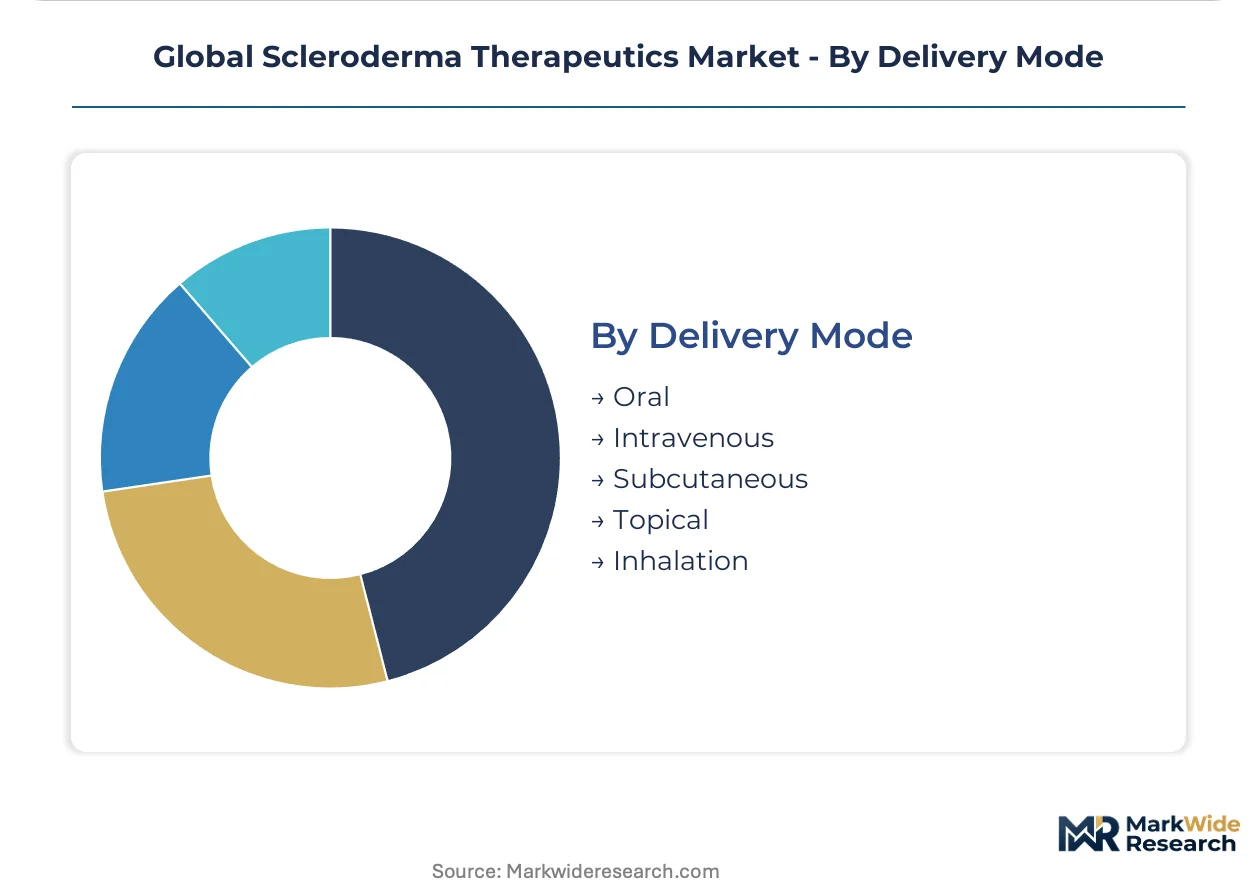
Delivery Mode:
Supply concentration in cold-chain infrastructure favors intravenous administration while patient convenience pressures drive subcutaneous innovation.
- Intravenous:Hospital and infusion center administration dominates biologic delivery. REACH-compliant manufacturing in Basel and Amsterdam supplies European monoclonal antibody demand.
- Subcutaneous:Prefilled syringe and autoinjector formats are gaining traction for interleukin-6 receptor antagonists. Self-administration potential expands addressable populations beyond urban infusion center catchments.
- Oral:Small-molecule immunosuppressants and vasodilators sustain the highest prescription convenience.
- Topical:Localized disease management relies on cream and ointment formulations with limited systemic absorption.
- Inhalation:Pulmonary arterial hypertension variants require prostacyclin analog delivery through nebulized systems.
Intravenous retains volume leadership; subcutaneous holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where specialized scleroderma centers command premium reimbursement rates, while Japan and emerging markets operate under tighter cost-control frameworks that compress margins for novel biologics.
United States
Johns Hopkins and University of Pittsburgh scleroderma programs drive investigator-initiated trials and accelerate biologic adoption through foundation-affiliated infusion networks. FDA orphan drug designation compresses development timelines for mechanism-specific compounds. Boston and San Francisco academic medical centers anchor the highest per-patient pharmaceutical expenditure in diffuse cutaneous systemic sclerosis.
Germany
Rheumatology centers in Munich and Berlin expand patient access to interleukin-6 receptor antagonists through EMA accelerated assessment pathways. REACH compliance elevates purity thresholds for biologic active pharmaceutical ingredients manufactured in Basel-supplied facilities. The Leiden University Medical Center collaboration network extends German investigator expertise into Dutch and Belgian patient recruitment pools.
Japan
PMDA sakigake designation attracts fibrosis-focused developers to conduct pivotal trials in Tokyo and Osaka academic hubs. METI funding programs support domestic biologics manufacturing infrastructure for cold-chain monoclonal antibody distribution. Japanese scleroderma centers concentrate in the Kanto region where autoantibody stratification protocols enable mechanism-specific patient selection.
United Kingdom
Manchester and London scleroderma units manage limited cutaneous disease through primary-secondary care interfaces that optimize vasodilator maintenance regimens. NICE technology appraisals create transparent cost-effectiveness thresholds for biologic reimbursement. The UK regulator's alignment with EMA accelerated pathways streamlines marketing authorization for orphan indications.
Brazil
ANVISA priority review pathways for orphan indications anchor Latin American expansion strategies before broader regional entry. São Paulo and Rio de Janeiro rheumatology clinics concentrate biologic infusion capacity despite cold-chain distribution cost barriers. Brazilian patient advocacy organizations are consolidating purchasing influence through specialty pharmacy network negotiations.
Global Scleroderma Therapeutics Market Competitive Landscape
Concentration sits with large-cap biopharmaceutical platforms possessing established biologics manufacturing infrastructure and autoimmune franchise breadth. Mid-cap immunology specialists occupy differentiated positions through concentrated fibrosis-targeting pipelines. Three archetypes dominate: integrated biologics manufacturers with global cold-chain distribution, autoimmune portfolio diversifiers leveraging cross-indication regulatory experience, and mechanism-focused developers betting on specific fibrosis pathway modulation. Competitive moves center on manufacturing scale expansion to capture orphan drug exclusivity premiums and strategic partnerships to access academic medical center trial networks.
Within the large-cap integrated tier, F. Hoffmann-La Roche Ltd and Bristol-Myers Squibb Company represent the dominant archetypes of biologics manufacturing depth and autoimmune franchise breadth respectively. Corbus Pharmaceuticals Holdings, Inc. occupies a position exemplifying the mechanism-focused developer archetype with concentrated fibrosis-targeting R&D. These three companies illustrate how competitive positioning fragments across manufacturing scale, portfolio diversification, and scientific specialization rather than converging on a single winning model.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| Corbus Pharmaceuticals Holdings, Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Actelion Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Monoclonal antibody cold-chain substitution for oral immunosuppressants is simultaneously redrawing manufacturing geography toward Basel and Amsterdam hubs while bifurcating pricing economics between premium biologic tiers and compressed generic maintenance regimens.
Pricing Analysis
Configured-to-order pricing for patient-stratified biologics commands spreads over standard immunosuppressant protocols. Contract-based long-term offtake agreements dominate, with price differentiation driven by autoantibody stratification protocols and infusion center certification tiers. Cost compression in the immunosuppressant tier is intensifying because German rheumatology centers negotiate volume-based tenders for mycophenolate mofetil. Community rheumatology clinics exhibit highest price sensitivity; academic medical centers with foundation-affiliated networks demonstrate lowest.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp lanes elevates inbound logistics costs for REACH-compliant active pharmaceutical ingredients. Manufacturing concentrates in Switzerland, the Netherlands, and Germany. Raw material dependencies include CHO cell lines, single-use bioreactor components, and pharmaceutical-grade excipients. Single-source vulnerability sits with specialized CMOs holding EMA-certified monoclonal antibody capacity. Distribution runs through cold-chain logistics networks terminating at hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specialty pharmacy network consolidation, with United States scleroderma foundations aggregating patient volumes to negotiate direct manufacturer rebates previously reserved for national payers.
For Market Incumbents: Fortify cold-chain manufacturing scale in Basel-supplied facilities to capture orphan drug exclusivity premiums before biosimilar entry. Anchor autoimmune franchise breadth through interleukin-6 receptor antagonist line extensions. Defend against mechanism-focused developers by locking academic medical center trial networks through preferred investigator partnerships. For New Entrants and Emerging Players: Lead with subcutaneous formulation innovation targeting diffuse cutaneous systemic sclerosis patients outside urban infusion center catchments. Brazil's ANVISA priority review pathway offers the most penetrable regulatory entry point. Pursue foundation-affiliated specialty pharmacy networks as direct go-to-market channels bypassing traditional hospital formulary committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations holding EMA-certified biologics capacity and academic medical center trial site networks. Five-to-ten year viability hinges on fibrosis pathway mechanism validation and biomarker qualification harmonization across FDA and EMA frameworks. Watch for surrogate endpoint acceptance criteria convergence as inflection indicator for trial cost structures and time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Manufacturing Scale-Up | REACH-compliant Basel facilities capture EMA orphan exclusivity premiums before competitor entry. |
| Subcutaneous Formulation Development | Self-administration delivery shifts patient populations beyond urban infusion center geographic constraints. |
| Academic Medical Center Partnership | Johns Hopkins and University of Pittsburgh networks concentrate investigator expertise and streamline recruitment. |
| Digital Biomarker Integration | Wearable skin stiffness sensors enable decentralized trial models reducing site infrastructure burden. |
| Specialty Pharmacy Network Consolidation | Foundation-affiliated purchasing aggregations in California and New York command volume-based manufacturer rebates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA orphan drug designations, EMA accelerated assessment submissions, ClinicalTrials.gov protocols, and formulary database audits. Bottom-up patient population sizing and top-down pharmaceutical expenditure triangulation anchored market estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including therapy area phenotype, mechanism of action, administration route, and regional regulatory cluster. CAGRs derived from treatment line progression curves and biologic substitution elasticity parameters. Forecast inputs incorporated PMDA sakigake designation velocity and REACH compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in FDA orphan drug, EMA accelerated assessment, and PMDA sakigake frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market