
 Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market | 2026-2036
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market Foresight
CE marking under the EU In Vitro Diagnostic Regulation is redrawing competitive access for European-origin assay suppliers entering Middle East and Africa distribution channels. F Hoffmann-La Roche Ltd leverages its automated tissue diagnostic platforms to sustain premium positioning in Gulf private hospital networks. Merck & Co Inc anchors its presence through oncology therapeutic portfolios aligned with regional formularies. Sanofi competes via established hormonal therapy supply chains reaching North African markets.
Uterine cancer therapeutics and diagnostics encompass pharmaceutical interventions and detection modalities for endometrial malignancies, including carboplatin-paclitaxel chemotherapy regimens, anti-PD-1 immunotherapy agents, and immunohistochemical biomarker assays performed on formalin-fixed paraffin-embedded tissue specimens. Chemotherapy retains the largest patient volume share across the region, while immunotherapy represents the fastest-expanding therapeutic class driven by checkpoint inhibitor approvals. Biomarker testing generates disproportionate margin concentration due to companion diagnostic requirements for targeted therapy eligibility.
South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce divergent registration pathways that fragment product launch timelines across the region. The EU AI Act and GDPR extraterritorial provisions increasingly govern artificial intelligence-enabled diagnostic algorithms deployed by multinational device vendors. Stakeholders must monitor harmonization efforts between Gulf Cooperation Council regulatory frameworks and national competent authorities to anticipate market access evolution.
Market Dynamics
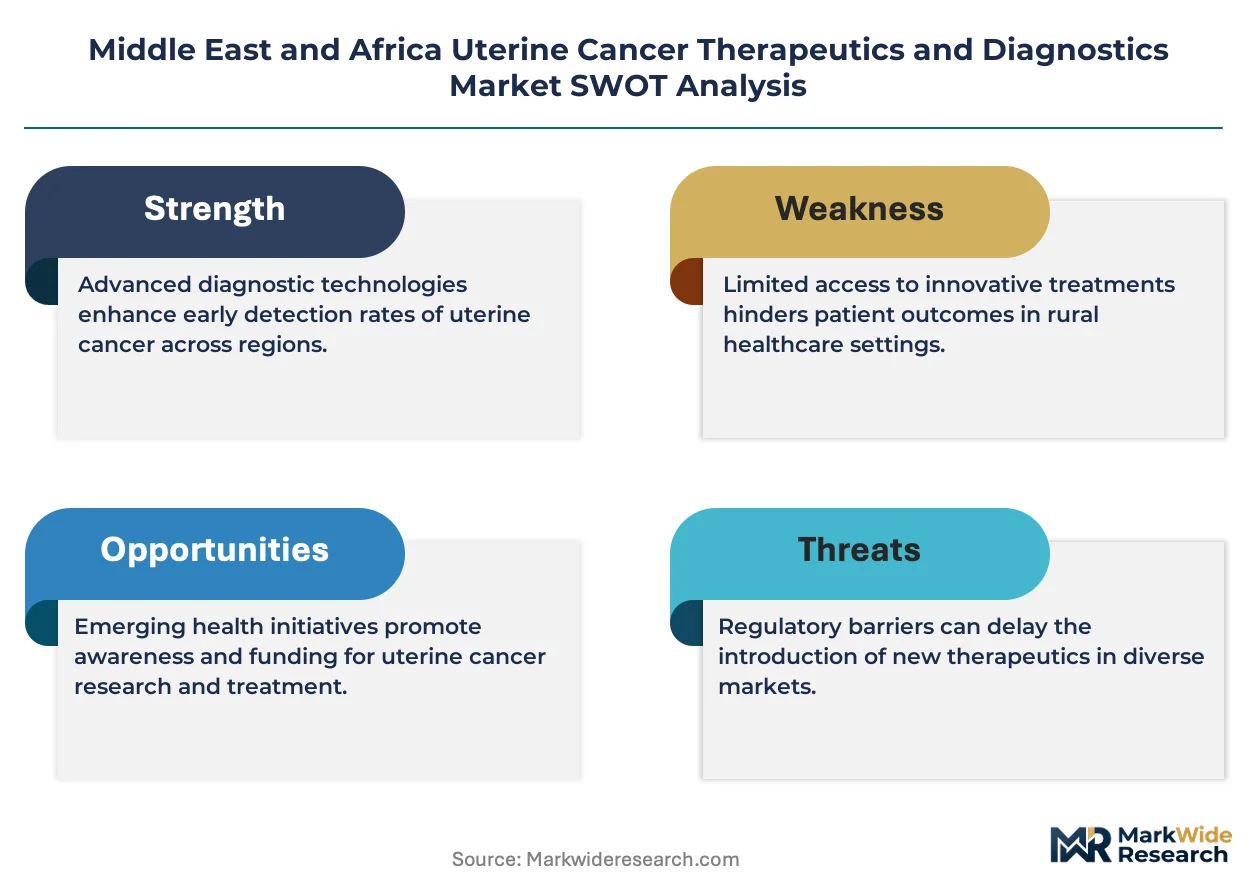
Saudi Arabia's SFDA and South Africa's Health Products Regulatory Authority have imposed divergent molecular diagnostic registration requirements, fragmenting product launch timelines and forcing vendors to maintain parallel regulatory compliance infrastructures across Gulf and sub-Saharan distribution channels.
Growth Catalysts
- Companion diagnostic mandates:SFDA and MOHAP now require biomarker testing prior to targeted therapy authorization, expanding immunohistochemistry assay volumes in tertiary oncology centers across Riyadh and Dubai.
- Carboplatin-paclitaxel standardization:Gulf Cooperation Council formularies have adopted this chemotherapy backbone as first-line endometrial carcinoma protocol, anchoring therapeutic demand across Saudi Arabia and the United Arab Emirates.
- Private hospital network expansion:Tertiary oncology departments in Abu Dhabi and Jeddah are installing automated tissue processing platforms, creating concentrated demand nodes for integrated diagnostic-therapeutic workflows.
Market Restraints
- Reagent import dependency:Formalin-fixed paraffin-embedded tissue processing consumables concentrate through European distribution hubs, exposing margins to euro-denominated cost volatility and customs clearance friction at Jebel Ali and Durban ports.
- Pathologist scarcity:Gynecologic pathology subspecialty training programs remain underdeveloped across Nigeria, Egypt, and Kenya, constraining diagnostic throughput regardless of installed instrument capacity.
- Checkpoint inhibitor cold-chain limitations:Anti-PD-1 immunotherapy storage requirements at negative 80 degrees Celsius exceed rural hospital infrastructure across Ethiopia, Tanzania, and Uganda, restricting addressable patient populations to urban tertiary centers.
Strategic Opportunities
- Telepathology networks:Digital slide scanning and remote consultation platforms enable Abu Dhabi and Johannesburg academic medical centers to extend diagnostic coverage into underpenetrated Egyptian and Nigerian provincial hospitals lacking on-site gynecologic pathologists.
- EU AI Act algorithmic certification:Artificial intelligence-enabled histopathology screening tools that achieve CE marking under IVDR can leverage regulatory reciprocity discussions between Gulf Cooperation Council technical committees and European notified bodies, accelerating SFDA and MOHAP approval pathways.
- Hormonal therapy supply chain optimization:Sanofi's established North African distribution infrastructure for progestin-based regimens creates template for expanding aromatase inhibitor access into Moroccan and Tunisian public oncology programs.
Industry Challenges
- Multi-jurisdictional quality management system certification:Vendors must simultaneously maintain ISO 13485, SFDA Good Manufacturing Practice, and South African Health Products Regulatory Authority medical device quality system compliance, extending audit cycles and documentation overhead.
- Legacy chemotherapy inventory integration:Public hospital formularies across Cairo and Lagos retain substantial carboplatin and paclitaxel stockpiles under older procurement contracts, complicating transition negotiations toward immunotherapy-inclusive treatment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market |
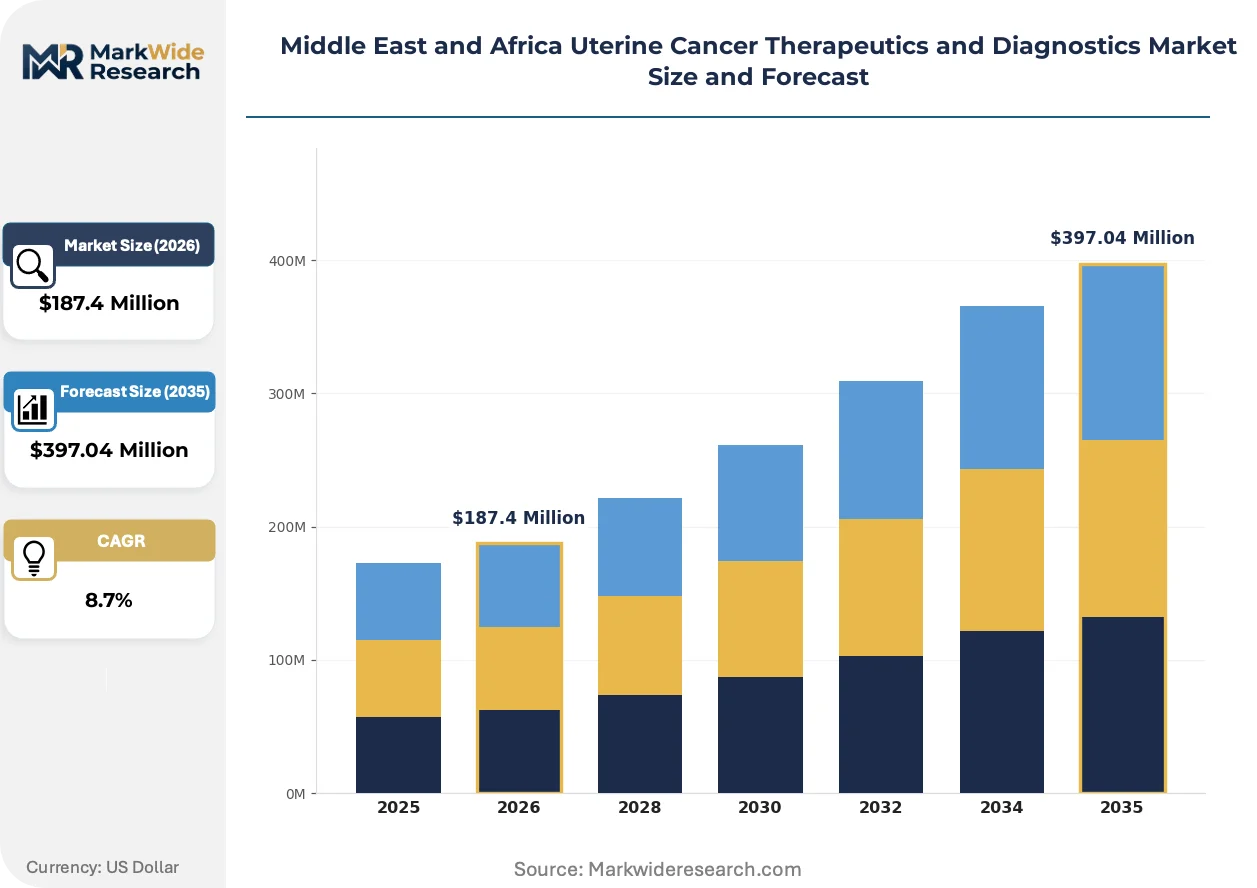
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Application: Early Detection, Treatment Monitoring, Palliative Care, Post-operative Care End User: Hospitals, Cancer Centers, Clinics, Homecare Settings Technology: Next-Generation Sequencing, Biomarker Testing, Imaging Techniques, Diagnostic Kits |
| Companies Covered | Sanofi, Novartis AG, Merck & Co Inc, F Hoffmann-La Roche Ltd, GlaxoSmithKline Plc, Becton Dickinson & Company, Takeda Pharmaceutical Company Limited, Abbott Laboratories, Siemens Healthcare Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Automated immunohistochemistry platforms and artificial intelligence-enabled histopathology analysis are compressing diagnostic turnaround times from days to hours, while regulatory frameworks governing algorithmic medical devices are rewriting vendor certification requirements across Middle East and Africa distribution channels.
Next-generation sequencing-based comprehensive genomic profiling is displacing single-gene immunohistochemistry testing as the standard for molecular subtype classification in endometrial carcinoma. Private oncology centers in Dubai Healthcare City and King Faisal Specialist Hospital are adopting these panels at accelerating pace. This displacement is compressing reimbursement timelines for traditional biomarker assays while expanding pharmaceutical companion diagnostic partnership opportunities.
CE marking under the EU In Vitro Diagnostic Regulation now governs market access for European-origin assay suppliers entering Middle East and Africa channels, with Gulf Cooperation Council regulatory harmonization initiatives progressively aligning SFDA and MOHAP technical documentation requirements with European notified body standards. Saudi Arabia's medical device cluster at King Abdullah Economic City is responding by establishing localized conformity assessment capabilities to accelerate IVDR-equivalent certification for regional manufacturers.
Gulf private hospital networks are consolidating procurement authority into centralized pharmacy and therapeutics committees, displacing individual physician preference-based purchasing with formulary-driven tender processes. This concentration is compressing vendor negotiation leverage and favoring suppliers offering integrated diagnostic-therapeutic portfolios. The United Arab Emirates' mandatory health insurance framework is accelerating this behavioral shift by linking reimbursement authorization to committee-approved protocol compliance.
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market Segmentation
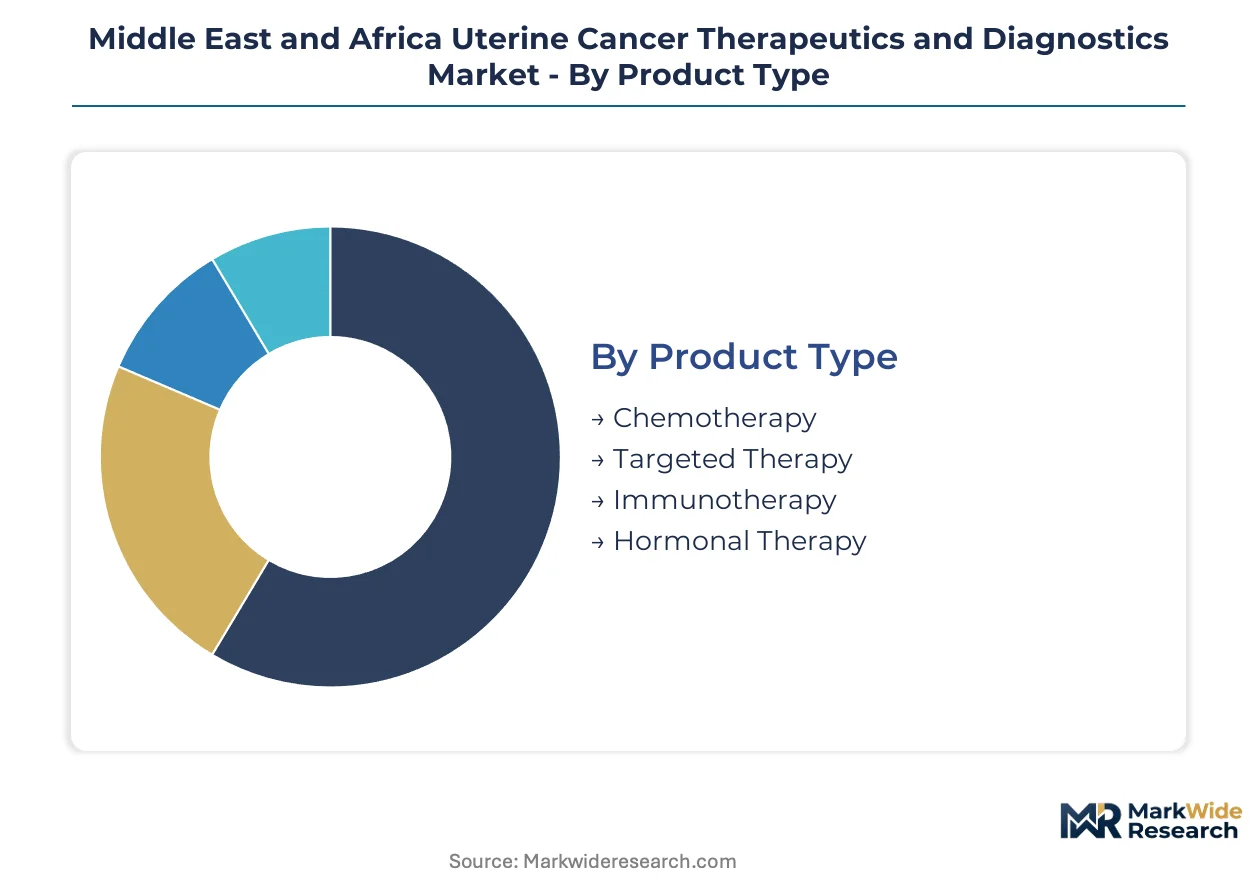
Segmentation in the Middle East and Africa uterine cancer therapeutics and diagnostics market reveals how regulatory divergence, infrastructure gaps, and technology adoption curves concentrate value capture across distinct product and service categories. Understanding these fault lines enables vendors to align portfolio investments with addressable patient populations and reimbursement pathways.
Product Type:
Immunotherapy exerts the strongest substitution pressure on legacy chemotherapy protocols as Gulf Cooperation Council formularies incorporate checkpoint inhibitor mandates, though cold-chain limitations and procurement contract lock-ins slow displacement timelines across sub-Saharan Africa.
- Chemotherapy:Carboplatin-paclitaxel regimens constitute the established first-line protocol across Saudi tertiary hospitals and South African oncology networks. Demand concentrates in public sector formularies where procurement committees prioritize cost containment over therapeutic innovation, constraining transition negotiations toward newer modalities.
- Immunotherapy:Anti-PD-1 agents require biomarker-driven patient selection and ultra-cold storage infrastructure available only at King Faisal Specialist Hospital and select Dubai private networks. Abu Dhabi and Riyadh academic medical centers anchor regional demand as SFDA companion diagnostic mandates expand eligible patient identification.
- Targeted Therapy:Poly-ADP ribose polymerase inhibitors and anti-angiogenic agents serve molecularly defined subpopulations in South African and Gulf private settings.
- Hormonal Therapy:Progestin-based regimens retain utility for fertility-preserving early-stage protocols across North African public oncology programs.
Chemotherapy anchors the volume base while immunotherapy gains share at the steepest rate.
Application:
Cost tier stratification separates curative-intent interventions from supportive care applications, with early detection commanding premium pricing in Gulf private networks and palliative care relying on fragmented public procurement across Egypt and Nigeria.
- Early Detection:Transvaginal ultrasound and endometrial biopsy protocols concentrate demand in Saudi and Emirati screening programs targeting high-risk populations. King Abdullah Economic City medical device cluster localization efforts aim to reduce import dependency for diagnostic consumables.
- Treatment Monitoring:Circulating tumor DNA and imaging surveillance generate recurring revenue streams at Johannesburg and Cairo tertiary centers. South Africa's Health Products Regulatory Authority tightened in vitro diagnostic registration requirements, accelerating quality upgrades among monitoring assay suppliers.
- Post-operative Care:Adjuvant therapy selection depends on molecular risk stratification available primarily at Gulf private oncology departments.
- Palliative Care:Symptom management protocols face formulary restrictions across Kenyan and Tanzanian public hospital systems.
Treatment monitoring captures the most predictable recurring revenue while early detection shows the steepest expansion trajectory.
End User:
Customer type determines technology access tiers, with tertiary hospital networks consolidating procurement authority and homecare settings remaining underdeveloped due to nursing workforce constraints and reimbursement gaps.
- Hospitals:Tertiary oncology departments across Riyadh, Dubai, and Johannesburg deploy automated tissue processing platforms and next-generation sequencing infrastructure. SFDA and MOHAP centralized tender processes favor suppliers offering integrated diagnostic-therapeutic portfolios.
- Cancer Centers:Specialized gynecologic oncology units at King Faisal Specialist Hospital and Dubai Healthcare City anchor high-complexity case volume. Pathologist scarcity across Egyptian and Nigerian provincial facilities limits diagnostic throughput regardless of installed instrument capacity.
- Clinics:Community-based screening and referral functions concentrate in South African urban corridors and Moroccan private networks.
- Homecare Settings:Oral hormonal therapy administration faces nursing supervision requirements and cold-chain limitations for biologic agents across Ethiopian and Ugandan rural catchments.
Hospitals retain the dominant patient volume share while cancer centers expand most quickly through Gulf private network specialization.
Technology:
Supply concentration in European reagent manufacturing and algorithm development shapes competitive access for diagnostic technology categories, with CE marking under EU IVDR progressively governing Middle East and Africa distribution channels.
- Biomarker Testing:Immunohistochemistry and fluorescence in situ hybridization assays for mismatch repair deficiency and microsatellite instability guide immunotherapy eligibility decisions. SFDA companion diagnostic mandates expand assay volumes at Saudi tertiary centers while reagent import dependency exposes margins to euro-denominated volatility.
- Next-Generation Sequencing:Comprehensive genomic profiling panels displace single-gene testing for molecular subtype classification at Dubai Healthcare City and King Faisal Specialist Hospital. EU AI Act and GDPR extraterritorial provisions increasingly govern artificial intelligence-enabled variant interpretation algorithms deployed by multinational vendors.
- Imaging Techniques:Magnetic resonance imaging and positron emission tomography staging concentrates at Abu Dhabi and Johannesburg academic medical centers with tele-radiology extension capabilities.
- Diagnostic Kits:Point-of-care molecular assays face regulatory fragmentation between Gulf Cooperation Council harmonization initiatives and South African national registration pathways.
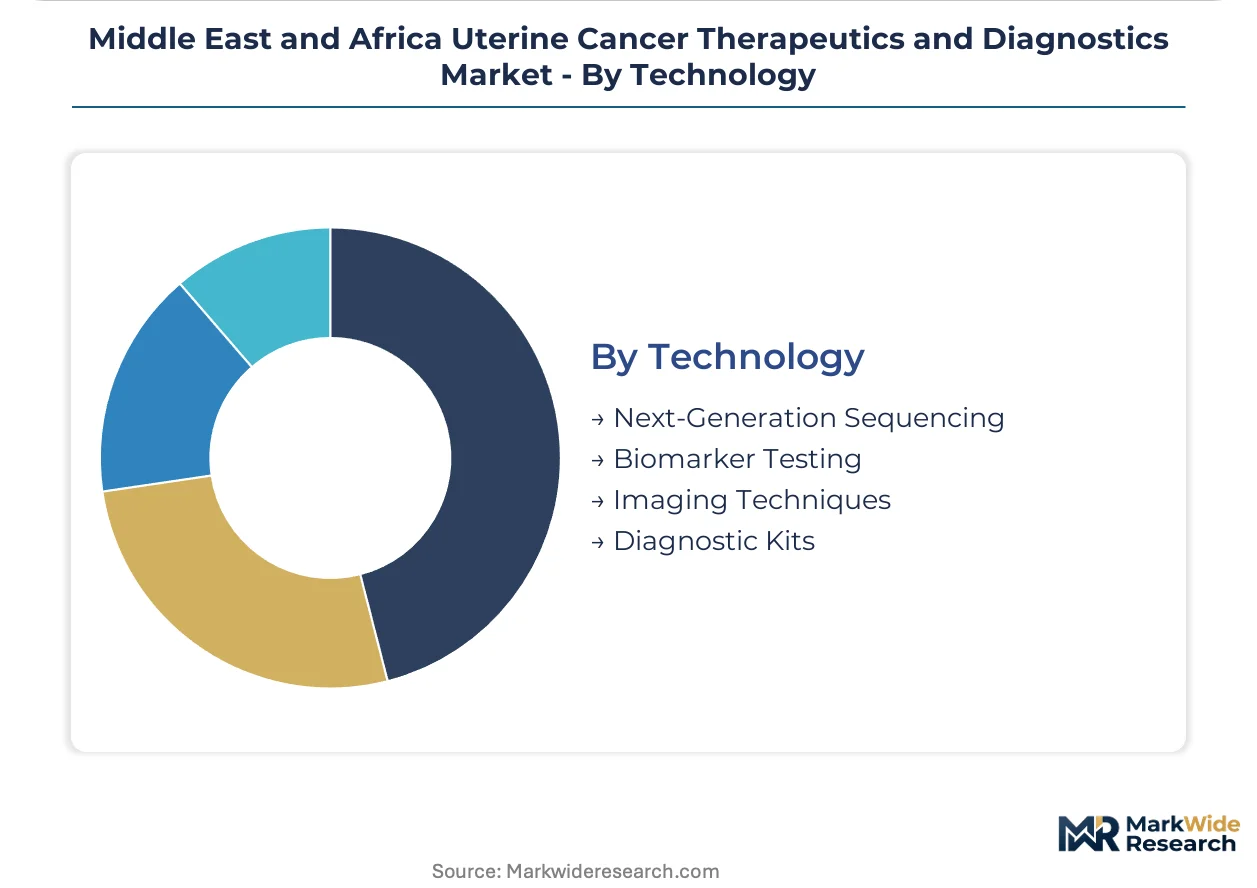
Biomarker testing anchors current diagnostic revenue while next-generation sequencing climbs the fastest as comprehensive profiling becomes standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private hospital procurement committees and government oncology initiatives concentrate demand across Gulf States and select sub-Saharan markets, with tertiary care networks anchoring technology adoption tiers.
Saudi Arabia
King Faisal Specialist Hospital and Riyadh tertiary centers drive immunotherapy volume as SFDA mandates companion diagnostics for checkpoint inhibitor authorization. The national medical device cluster at King Abdullah Economic City is localizing conformity assessment capabilities to accelerate IVDR-equivalent certification timelines for regional manufacturers.
United Arab Emirates
Dubai Healthcare City and Abu Dhabi private oncology networks deploy next-generation sequencing infrastructure for molecular risk stratification. MOHAP centralized tender processes favor suppliers offering integrated diagnostic-therapeutic portfolios under the mandatory health insurance framework linking reimbursement to committee-approved protocols.
South Africa
Johannesburg academic medical centers anchor comprehensive genomic profiling adoption while the Health Products Regulatory Authority's tightened IVD registration requirements accelerate quality upgrades among monitoring assay suppliers. Cape Town and Gauteng provinces concentrate pathology capacity that serves as a diagnostic hub for neighboring markets.
Egypt
Cairo public hospital formularies retain substantial carboplatin-paclitaxel stockpiles under legacy procurement contracts, complicating transition negotiations toward newer modalities. The country's national pharmaceutical regulator maintains divergent registration pathways from Gulf Cooperation Council frameworks, fragmenting vendor launch timelines.
Nigeria
Lagos and Abuja urban corridors concentrate screening and referral functions, though pathologist scarcity across provincial facilities constrains diagnostic throughput regardless of installed instrument capacity. Cold-chain limitations for anti-PD-1 agents restrict addressable patient populations to these tertiary centers.
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with oncology portfolios, automated diagnostic platform specialists, and hormonal therapy supply chain incumbents. Market structure concentrates around integrated diagnostic-therapeutic bundling as Gulf hospital procurement committees displace physician preference-based purchasing. Three archetypes dominate: European-origin assay suppliers leveraging CE marking reciprocity, multinational pharmaceutical firms anchoring therapeutic formularies, and regional distributors managing reagent import logistics. Competitive moves center on regulatory harmonization positioning and companion diagnostic partnership structures.
Within the pharmaceutical conglomerate tier, Merck & Co Inc and Sanofi occupy positions reflecting distinct geographic anchoring strategies. F Hoffmann-La Roche Ltd exemplifies the automated platform specialist archetype. Merck & Co Inc represents the oncology therapeutic portfolio approach aligned with regional formularies. Sanofi sits within the hormonal therapy supply chain optimization segment, with established North African distribution infrastructure creating template potential for aromatase inhibitor expansion. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Sanofi |
| Novartis AG |
| Merck & Co Inc |
| F Hoffmann-La Roche Ltd |
| GlaxoSmithKline Plc |
| Becton Dickinson & Company |
| Takeda Pharmaceutical Company Limited |
| Abbott Laboratories |
| Siemens Healthcare Inc |
| Others |
Supply & Pricing Matrix
CE marking under the EU In Vitro Diagnostic Regulation gates both supply qualification and price differentiation simultaneously, as Gulf hospital procurement committees require IVDR-certified assays for formulary inclusion while using certification tier to stratify payment bands across premium automated platforms and standard manual testing workflows.
Pricing Analysis
Cost-plus contracts with euro-denominated indexation dominate reagent supply agreements for formalin-fixed paraffin-embedded tissue processing consumables, exposing margins to currency volatility at Jebel Ali and Durban ports. Price differentiation centers on certification grade and after-sales service bundling, with IVDR-certified automated platforms commanding premium positioning against standard-tier manual assays. Cost compression in public sector procurement is intensifying because Saudi SFDA and UAE MOHAP centralized tender processes prioritize volume scale over therapeutic innovation. Government hospital formularies exhibit the highest price sensitivity, while Gulf private oncology networks demonstrate greater willingness to pay for integrated diagnostic-therapeutic portfolios.
Supply Chain Analysis
Inventory lead times for immunohistochemistry reagents stretch to 12-16 weeks due to European manufacturing concentration and customs clearance friction at regional ports. Supply concentrates in Germany, the Netherlands, and Switzerland for diagnostic consumables, while active pharmaceutical ingredients for carboplatin-paclitaxel regimens source from India and China. Raw material dependencies span diagnostic antibodies, polymerase chain reaction master mixes, and ultra-cold storage equipment for checkpoint inhibitors. Single-source vulnerability in European reagent manufacturing creates supply chain risk given limited qualified alternative suppliers. Distribution runs through centralized Gulf Cooperation Council pharmacy and therapeutics committees displacing physician preference-based purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where companion diagnostic partnership structures and recurring biomarker testing revenue expand faster than capital equipment hardware sales across Saudi and Emirati tertiary oncology centers.
For Market Incumbents: Compound defensive positioning through backward integration into reagent manufacturing to reduce euro-denominated cost volatility exposure, while securing exclusive companion diagnostic partnerships with checkpoint inhibitor developers to lock formulary placement against emerging molecular diagnostic entrants. Threat substitution from next-generation sequencing comprehensive genomic profiling panels demands rapid immunohistochemistry platform upgrade cycles. Certification investment in Saudi SFDA Good Manufacturing Practice and South African Health Products Regulatory Authority quality system compliance extends audit overhead but creates regulatory moats. For New Entrants and Emerging Players: Anchor in telepathology network infrastructure serving Egyptian and Nigerian provincial hospitals lacking on-site gynecologic pathologists, where diagnostic throughput constraints create addressable white space regardless of installed instrument capacity. The most penetrable segment spans AI-enabled histopathology screening tools achieving CE marking under IVDR to leverage regulatory reciprocity discussions with Gulf Cooperation Council technical committees. Go-to-market execution should prioritize Abu Dhabi and Johannesburg academic medical center partnerships for remote consultation platform deployment. For Investors and Strategic Acquirers: SFDA companion diagnostic mandate implementation reshapes the acquisition landscape by concentrating value capture in biomarker testing assay developers with established Saudi regulatory dossiers. Long-term viability across the analysis window favors integrated diagnostic-therapeutic platform vendors over standalone pharmaceutical or device pure-plays. Target acquisition archetype: regional distributors managing reagent import logistics with captive relationships to King Faisal Specialist Hospital and Dubai Healthcare City procurement committees. Signal to monitor: harmonization progress between Gulf Cooperation Council regulatory frameworks and national competent authorities as inflection indicator for market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | SFDA mandates biomarker testing prior to checkpoint inhibitor authorization, expanding assay volumes at Saudi tertiary centers. |
| CE Marking Pathway | IVDR certification enables regulatory reciprocity leverage with Gulf Cooperation Council technical committees for accelerated SFDA approval. |
| Hospital System Partnership | Integrated diagnostic-therapeutic bundling aligns with Abu Dhabi and Riyadh procurement committee formulary-driven tender processes. |
| Software Companion Development | AI-enabled histopathology screening tools compress diagnostic turnaround times from days to hours at Dubai Healthcare City. |
| Reimbursement Strategy | Mandatory health insurance framework in UAE links authorization to committee-approved protocol compliance, favoring formulary-aligned suppliers. |
Research Methodology
A spread of perspectives from oncology department heads, hospital procurement committee chairs, regulatory affairs specialists at SFDA and MOHAP, and gynecologic pathology laboratory directors converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from SFDA medical device registration databases, South African Health Products Regulatory Authority IVD filings, ClinicalTrials.gov checkpoint inhibitor study records, and Gulf Cooperation Council harmonization initiative documentation. Bottom-up patient volume modeling and top-down market sizing triangulation anchored quantitative outputs.
Segmentation dimensions modeled span therapeutic class, diagnostic technology platform, end-user facility type, and regional regulatory cluster across the projection horizon. CAGRs derived from patient population epidemiology, treatment protocol evolution assumptions, and biomarker testing penetration curves. Industry-specific forecast inputs incorporated SFDA companion diagnostic mandate implementation timelines and next-generation sequencing infrastructure deployment rates at King Faisal Specialist Hospital and Dubai Healthcare City.
Decision-makers should treat outputs as directional under base assumptions of sustained Gulf government health initiative funding and stable European reagent supply channels; material deviation in either would warrant model refresh. Specific risk factors spanning pathologist scarcity constraints, checkpoint inhibitor cold-chain infrastructure gaps, and multi-jurisdictional quality management system certification overhead could revise forecast trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Kaposi Sarcoma Market