
 Preclinical Ultrasound Systems Market | 2026-2036
Preclinical Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Preclinical Ultrasound Systems Market Analytics
Direct sales channels serving academic medical centers is tilting toward bundled service contracts that span hardware, software, and technical training. Siemens leverages its installed base in European research hospitals to sustain recurring revenue from service agreements. FUJIFILM VisualSonics dominates the high-frequency micro-imaging segment with specialized transducers designed for rodent cardiovascular studies. Thermo Fisher Scientific competes through its life sciences distribution network, extending reach into pharmaceutical toxicology departments that lack dedicated imaging core facilities.
Preclinical ultrasound systems employ acoustic frequencies typically ranging from fifteen to seventy megahertz to achieve micrometer-scale resolution in small-animal models, enabling longitudinal tracking of tumor progression, cardiac function, and vascular morphology without terminal sacrifice. Tabletop systems anchor the installed base due to their balance of imaging depth and laboratory footprint, while high-frequency systems capture expanding interest from neurology and ophthalmology research programs where superficial tissue resolution demands exceed standard capabilities. Contrast-enhanced ultrasound technology leads growth in oncology and cardiovascular application areas, as microbubble agents enable perfusion quantification that rivals magnetic resonance and computed tomography methods at substantially lower per-scan cost.
FDA oversight of preclinical imaging data integrity under 21 CFR Part 11 shapes software development priorities, compelling vendors to embed audit trails and electronic signature capabilities that satisfy submissions for investigational new drug applications. ISO 10993 biocompatibility standards govern transducer materials and coupling gels that contact animal subjects, while IEC 60601-1 electrical safety requirements apply to system design for laboratory environments. Stakeholders must monitor how evolving EPA guidelines on laboratory animal welfare intersect with imaging protocol standardization efforts, as institutional review boards increasingly mandate non-invasive monitoring methods that reduce cohort sizes and longitudinal study costs.
Market Dynamics
FDA 21 CFR Part 11 compliance mandates are compressing vendor timelines for integrated software-hardware platforms, forcing simultaneous hardware certification and audit-trail deployment rather than sequential rollouts.
Growth Catalysts
- Oncology Contract Research:Contract research organizations in the United States and Germany are expanding high-frequency system procurement for longitudinal tumor tracking studies.
- Contrast-Enhanced Perfusion Imaging:Microbubble agent protocols enable quantitative perfusion analysis that rivals magnetic resonance and computed tomography at lower per-scan cost.
- EPA Laboratory Animal Welfare Guidelines:Institutional review boards increasingly mandate non-invasive monitoring methods that reduce cohort sizes and terminal sacrifice requirements.
Market Restraints
- Transducer Material Costs:Piezoelectric crystal supply concentrates among Asian specialty chemical suppliers, creating input cost volatility for frequencies above fifty megahertz.
- Technical Resolution Limits:Acoustic attenuation in soft tissue restricts imaging depth below three centimeters at seventy megahertz, constraining large-animal cardiovascular applications.
- ISO 10993 Certification Friction:Biocompatibility testing for new transducer polymers and coupling gels extends product development cycles by twelve to eighteen months.
Strategic Opportunities
- Neurology Research Expansion:High-frequency systems for superficial brain imaging in rodent stroke models remain underpenetrated in Chinese academic medical centers.
- Service Contract Unbundling:Pharmaceutical toxicology departments without dedicated imaging cores present channel innovation potential for remote technical support and pay-per-scan arrangements.
- Artificial Intelligence Integration:Machine learning-based segmentation algorithms converging with real-time beamforming enable automated cardiac function quantification without specialized sonographer training.
Industry Challenges
- Specialized Sonographer Shortage:Rodent cardiovascular imaging requires expertise in anatomical variant recognition that outpaces training program output in European research hospitals.
- Legacy Data Migration:FDA audit-trail requirements for investigational new drug submissions force retrospective validation of historical imaging databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preclinical Ultrasound Systems Market |
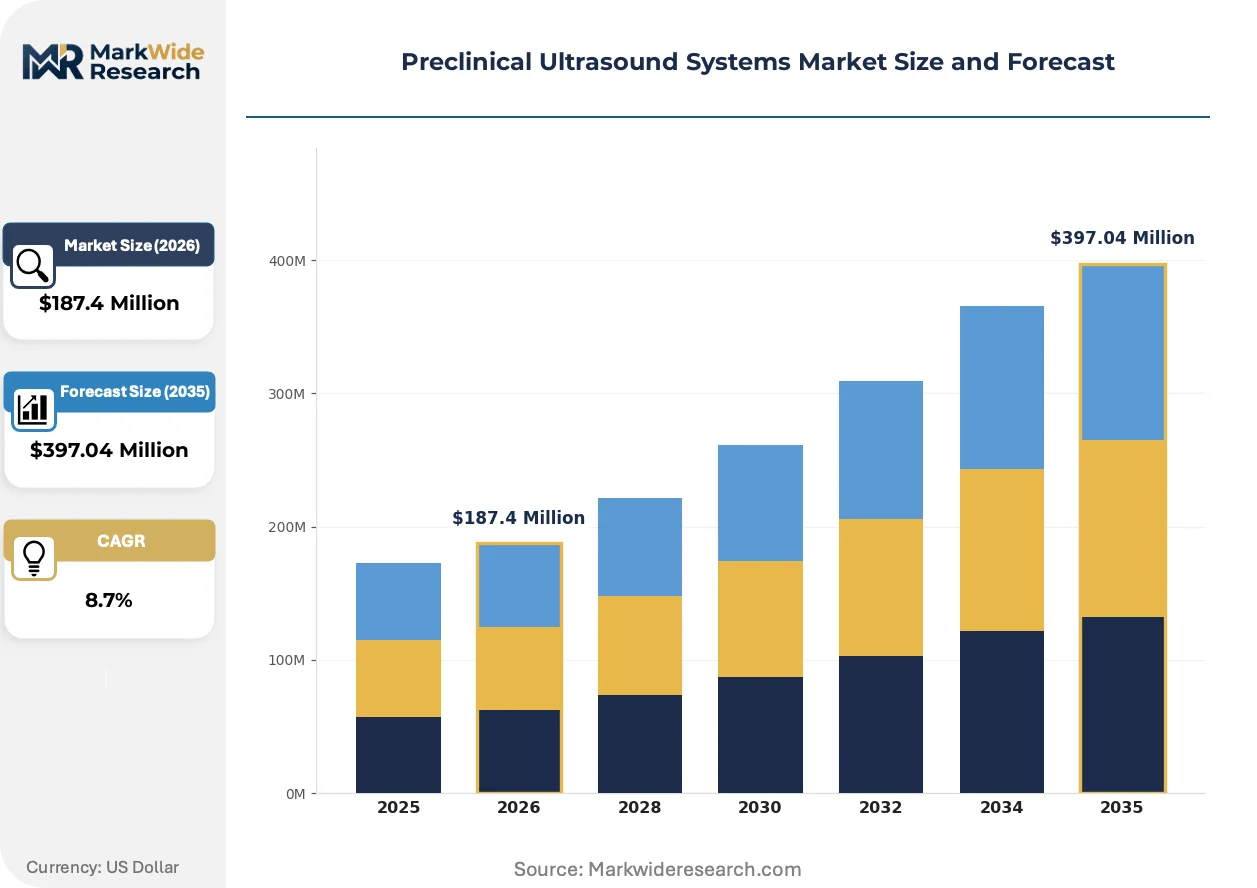
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Tabletop Systems, High-Frequency Systems, Imaging Software End User: Research Institutions, Pharmaceutical Companies, Contract Research Organizations, Academic Centers Application: Cardiovascular Research, Cancer Research, Neurological Research, Musculoskeletal Studies Technology: 2D Ultrasound, 3D Ultrasound, Doppler Ultrasound, Contrast-Enhanced Ultrasound |
| Companies Covered | Siemens, Thermo Fisher Scientific, FUJIFILM VisualSonics, MILabs, GE, PerkinElmer, TriFoil Imaging, MR Solutions, Bruker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preclinical Ultrasound Systems Market Evolving Landscape
Preclinical ultrasound is experiencing convergence between hardware miniaturization and software automation, compressing the traditional boundary between imaging core facilities and distributed laboratory deployment.
Shear-wave elastography is rendering obsolete static B-mode morphology assessment in fibrosis quantification protocols. Oncology and hepatology research programs at United States academic medical centers are adopting real-time tissue stiffness mapping for longitudinal therapeutic response monitoring. This modality compression eliminates sequential magnetic resonance elastography scheduling bottlenecks that previously extended study timelines by weeks.
EMA's evolving position on 3R principles (replacement, reduction, refinement) for animal research is mandating non-invasive longitudinal endpoints in preclinical efficacy studies. European pharmaceutical sponsors must now justify terminal imaging timepoints with equivalent non-invasive alternatives. High-frequency ultrasound systems with automated measurement protocols are capturing preference share in German and Swiss contract research facilities facing institutional review board scrutiny.
Academic medical center purchasing committees are consolidating vendor relationships through multi-year bundled agreements spanning hardware, software licenses, and technical training. Siemens and FUJIFILM VisualSonics compete for sole-source contracts that displace spot procurement of individual transducers or software modules. This concentration is most visible in United States National Institutes of Health-funded institutions where grant compliance requirements favor standardized platforms across collaborating laboratories.
Preclinical Ultrasound Systems Market Segmentation
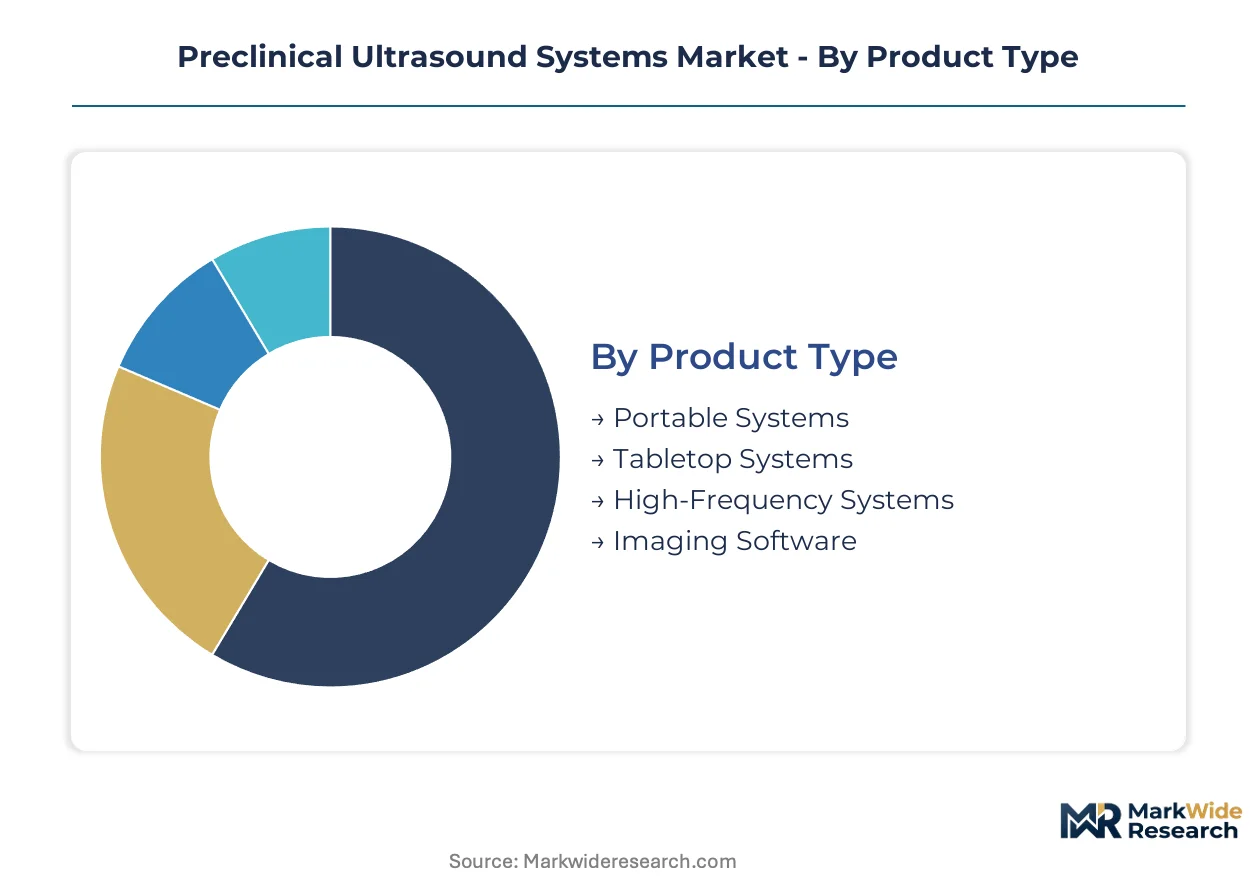
Preclinical ultrasound segmentation reveals distinct service intensity profiles across hardware platforms and software modules. Vendors calibrate field engineering coverage and training commitments differently for each tier, creating divergent margin structures that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across hardware tiers, with high-frequency systems demanding specialized transducer refurbishment programs and tabletop platforms requiring routine calibration protocols that anchor recurring revenue streams.
- Portable Systems:Compact units with battery-powered operation enable distributed deployment across multi-building research campuses. Demand concentrates in United States academic medical centers where principal investigators require imaging capability at satellite vivarium facilities without core facility scheduling delays. These systems carry lower per-unit service contract values but higher incident rates from field transport damage.
- Tabletop Systems:Fixed-installation platforms balance imaging depth with laboratory footprint through integrated probe switching and motorized positioning stages. German contract research organizations favor these configurations for standardized oncology protocols across multi-site studies. Service contracts typically bundle annual calibration, software updates, and operator recertification training.
- High-Frequency Systems:Specialized platforms operating above fifty megahertz for rodent ophthalmology and superficial neurology applications.
- Imaging Software:Standalone analysis modules for offline reconstruction, automated segmentation, and regulatory-compliant data archiving.
By volume, Tabletop Systems leads. By growth pace, High-Frequency Systems is expanding most quickly.
End User:
Customer type determines procurement authority structures and budget cycle timing, with pharmaceutical sponsors operating on fiscal-year capital allocation while academic centers align purchases with grant award schedules.
- Research Institutions:National laboratories and independent research foundations with dedicated imaging core facilities. Chinese institutes of biomedical sciences are expanding high-frequency procurement for cardiovascular phenotyping centers.
- Pharmaceutical Companies:Internal R&D divisions and toxicology departments with centralized imaging infrastructure. United States sponsors prioritize FDA 21 CFR Part 11 compliant platforms for IND-enabling studies.
- Contract Research Organizations:Multi-site service providers executing sponsored preclinical studies under GLP protocols. German CROs dominate European procurement for oncology longitudinal tracking contracts.
- Academic Centers:University-affiliated medical schools with NIH-funded investigator programs. These buyers favor bundled hardware-software-training contracts that standardize platforms across collaborating laboratories.
Contract Research Organizations capture the steepest expansion trajectory as pharmaceutical outsourcing deepens. Academic Centers maintain the largest installed base by unit count.
Application:
Clinical translation proximity shapes technology requirements, with cardiovascular and cancer applications driving contrast-enhanced perfusion capabilities while neurological research pushes resolution boundaries.
- Cardiovascular Research:ECG-gated imaging for ventricular function quantification and vascular flow mapping in rodent and large-animal models. United States academic medical centers anchor demand for automated cardiac function packages that reduce sonographer training burdens.
- Cancer Research:Longitudinal tumor volume tracking and therapeutic response monitoring using contrast-enhanced perfusion quantification. Microbubble agent protocols enable vascular permeability assessment that rivals MRI at lower per-scan cost.
- Neurological Research:Superficial brain imaging in stroke and trauma models through thinned-skull or cranial window preparations.
- Musculoskeletal Studies:Tendon, ligament, and joint imaging for injury and repair models in orthopedics research programs.
Cancer Research commands the highest average system configuration value. Neurological Research is gaining share fastest as Chinese academic centers expand stroke model programs.
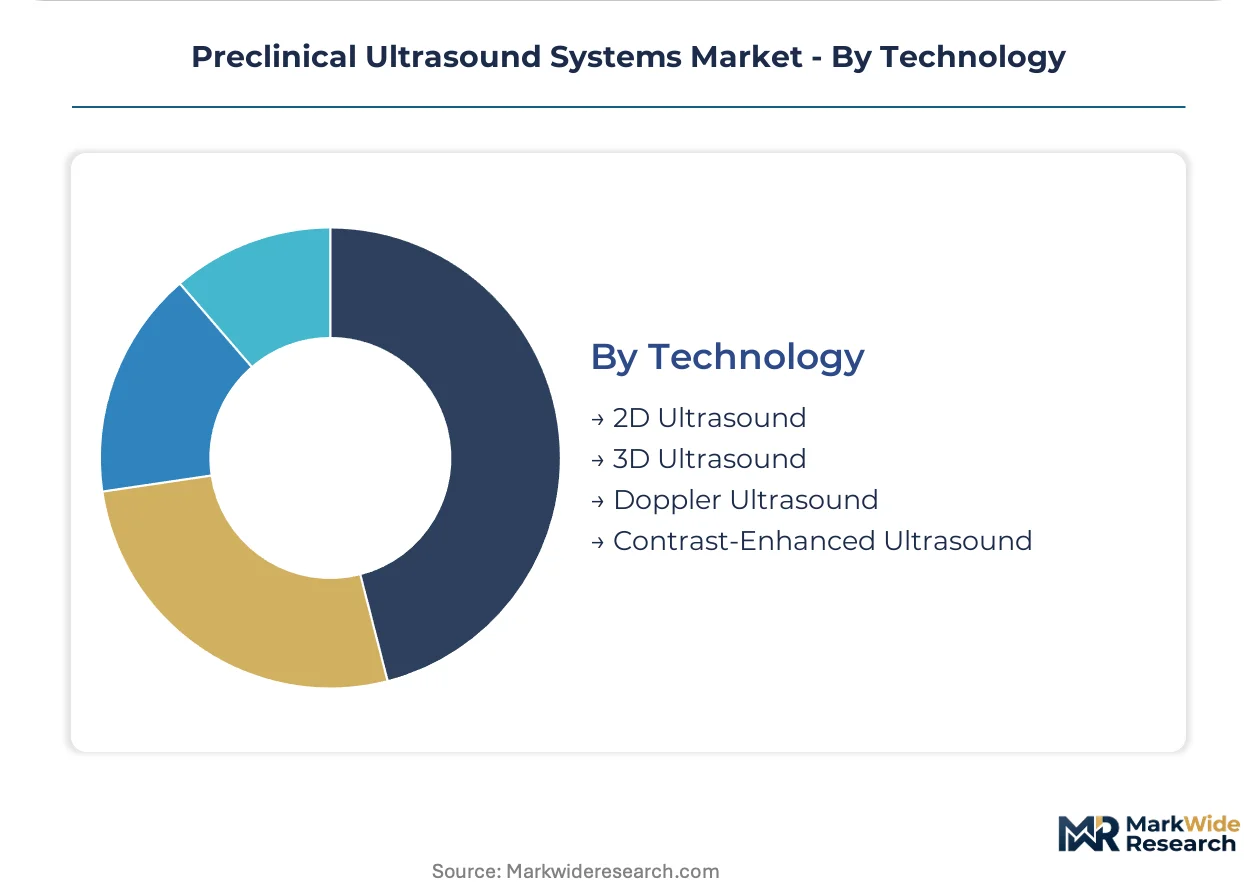
Technology:
Modalities stack in typical procurement configurations, with 2D and Doppler forming baseline capabilities and 3D reconstruction plus contrast enhancement commanding premium positioning.
- 2D Ultrasound:Real-time B-mode grayscale imaging for anatomical visualization and guided injection procedures. Standard capability across all hardware tiers with mature transducer supply chains.
- 3D Ultrasound:Volumetric acquisition and multiplanar reconstruction for organ volume quantification without geometric assumptions. German research hospitals favor these systems for cardiac mass and tumor burden assessments.
- Doppler Ultrasound:Pulsed-wave and color flow mapping for hemodynamic assessment in cardiovascular and tumor angiogenesis studies.
- Contrast-Enhanced Ultrasound:Microbubble-based perfusion imaging with quantitative time-intensity curve analysis. United States oncology CROs are standardizing these protocols for anti-angiogenic therapeutic monitoring.
2D Ultrasound dominates unit shipments. Contrast-Enhanced Ultrasound shows the steepest adoption curve as regulatory acceptance for IND submissions solidifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics infrastructure underwrites Western Europe's preclinical imaging supply chain, while Shanghai Pudong International Airport's cold-chain cargo terminals anchor Asia-Pacific distribution networks for microbubble contrast agents.
United States
NIH-funded academic medical centers in Boston and San Francisco drive procurement of high-frequency systems for cardiovascular phenotyping. FDA 21 CFR Part 11 compliance mandates shape vendor selection for IND-enabling studies. The Research Triangle Park cluster in North Carolina concentrates contract research organization imaging cores serving oncology sponsors.
Germany
EMA's 3R principles for animal research compel pharmaceutical sponsors to adopt non-invasive longitudinal endpoints. The Heidelberg-Mannheim bioengineering corridor hosts multi-site CRO facilities standardizing contrast-enhanced perfusion protocols. Baden-Württemberg's university hospitals anchor service contract bundling across hardware and software tiers.
China
NMPA regulatory harmonization with ICH guidelines accelerates adoption of FDA-compliant imaging platforms for domestic drug development. The Suzhou Industrial Park biomedical cluster attracts high-frequency system deployments for stroke model programs. Shanghai's Fudan University medical center network expands rodent ophthalmology imaging capabilities.
United Kingdom
UK Research and Innovation funding streams prioritize replacement technologies that reduce animal cohort sizes in preclinical efficacy studies. The Cambridge-London biomedical corridor concentrates academic purchasing power for bundled platform agreements. Oxford's preclinical imaging core facilities standardize on systems with automated cardiac function quantification.
Switzerland
Swissmedic's alignment with EMA standards streamlines multi-site study protocols across Basel's pharmaceutical R&D hub. ETH Zurich's engineering school drives demand for shear-wave elastography systems in fibrosis research. The Basel-Strasbourg cross-border cluster coordinates transducer refurbishment programs serving German and French CROs.
Preclinical Ultrasound Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in transducer materials and microbubble agent supply. The vendor base consolidates around three to four integrated hardware-software providers, with mid-scale specialists occupying niche frequency bands above fifty megahertz. Two dominant strategic archetypes emerge: imaging conglomerates leveraging installed base service contracts, and frequency-domain specialists defending technical differentiation in rodent micro-imaging. Competitive moves center on sole-source contract consolidation at academic medical centers and unbundled service offerings for distributed pharmaceutical toxicology departments.
Within the integrated platform tier, Siemens and FUJIFILM VisualSonics exemplify divergent archetypes. Siemens represents the imaging conglomerate model, anchoring recurring revenue through European research hospital service agreements. FUJIFILM VisualSonics occupies the high-frequency specialization position, with its nomenclature indicating Japanese corporate origin and visual-sonics domain focus. Thermo Fisher Scientific sits within the life sciences distribution archetype, extending platform reach through channel partnerships rather than direct field engineering coverage.
| Leading Market Players |
|---|
| Siemens |
| Thermo Fisher Scientific |
| FUJIFILM VisualSonics |
| MILabs |
| GE |
| PerkinElmer |
| TriFoil Imaging |
| MR Solutions |
| Bruker |
| Others |
Value Network & Pricing Analysis
Piezoelectric crystal supply concentration among Asian specialty chemical suppliers creates input cost volatility that simultaneously compresses margins at the high-frequency tier and forces three-tier pricing stratification across premium, standard, and economy system configurations. This feedstock dependency cascades through transducer refurbishment programs and coupling gel certification costs, reshaping how vendors structure bundled service contracts versus spot procurement.
Pricing Analysis
Volume-discount tiering separates sole-source academic medical center contracts from spot procurement by pharmaceutical toxicology departments lacking imaging cores. Price differentiation hinges on FDA 21 CFR Part 11 certification grade and after-sales service bundling intensity. Cost compression in the portable systems tier is intensifying because transport damage incident rates inflate field engineering overhead. Contract research organizations exhibit the highest price sensitivity due to GLP protocol standardization mandates, while NIH-funded academic centers prioritize platform standardization over unit cost.
Supply Chain Analysis
Upstream feedstock for high-frequency transducers draws from Japanese and South Korean piezoelectric crystal manufacturers, with Chinese suppliers dominating coupling gel polymer production. Raw material dependencies center on lead zirconate titanate ceramics, specialized acoustic matching layers, and ISO 10993-certified biocompatible gels. Single-source vulnerability concentrates in frequencies above fifty megahertz where qualified crystal vendors number fewer than five globally. Distribution runs through life sciences distribution networks for pharmaceutical accounts and direct field engineering teams for academic medical center deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around multi-year bundled agreements at United States academic medical centers, fragmenting spot procurement leverage among distributed pharmaceutical toxicology departments without dedicated imaging cores.
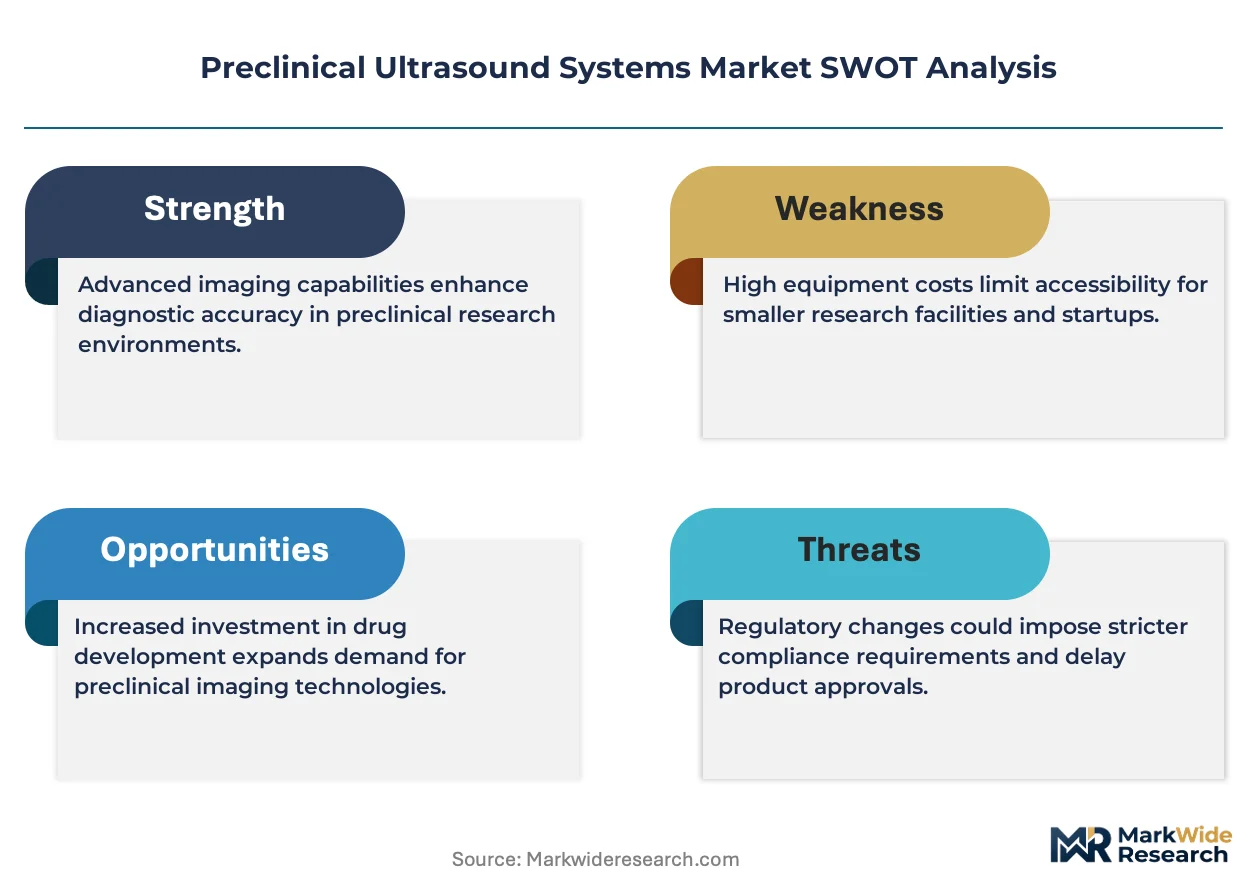
For Market Incumbents: Pre-empt sole-source contract displacement by embedding AI-driven automated cardiac function quantification into existing hardware platforms before emerging software specialists capture preference share. Deepen backward integration into piezoelectric crystal supply through captive sourcing agreements with Japanese specialty chemical vendors to defend margin position against input cost volatility. For New Entrants and Emerging Players: Chinese academic medical centers expanding stroke model programs represent the most penetrable entry point for high-frequency systems below the Siemens-FUJIFILM VisualSonics radar. Remote technical support and pay-per-scan arrangements for pharmaceutical toxicology departments without imaging cores offer a channel innovation angle that bypasses incumbent field engineering density. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors frequency-domain specialists with defensible transducer IP over imaging conglomerates dependent on service contract renewal rates. Acquisition targets should demonstrate installed base concentration in NMPA-harmonized Chinese facilities or EMA 3R-compliant European CROs. Watch for NMPA regulatory harmonization completion as the inflection signal accelerating domestic Chinese vendor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Software Companion Development | Automated cardiac segmentation reduces sonographer training burdens at NIH-funded academic centers. |
| Backward Integration into Transducer Materials | Captive piezoelectric crystal supply insulates margins from Asian specialty chemical volatility. |
| CE Marking Pathway for Shear-Wave Elastography | EMA 3R compliance positioning captures German CRO preference for non-invasive fibrosis endpoints. |
| Hospital System Partnership for Service Unbundling | Remote pay-per-scan arrangements penetrate pharmaceutical toxicology departments lacking imaging cores. |
| Reimbursement Strategy for Contrast-Enhanced Protocols | IND submission acceptance solidifies microbubble perfusion as standard oncology monitoring. |
Research Methodology
Cross-validation between primary interviews with preclinical imaging core directors, biomedical engineers, CRO procurement leads, and pharmaceutical toxicology department heads and secondary validation anchors the qualitative findings. FDA 510(k) filings, EMA scientific advice letters, NIH grant award databases, and institutional review board protocol registries provide regulatory trajectory calibration. Bottom-up system shipment tallies by hardware tier and top-down service contract value estimates triangulate market sizing.
Calibration against historical CAGRs in adjacent preclinical imaging modalities and elasticity analysis of academic medical center capital expenditure cycles inform the projection framework across the analysis window. Segmentation dimensions span product type, end user archetype, application area, and technology modality stack. Growth rates derive from installed base replacement velocity, contrast-enhanced protocol adoption curves, and regional regulatory harmonization timelines.
Stress conditions across piezoelectric crystal supply disruption, NMPA regulatory timeline acceleration, and CRO outsourcing depth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FDA 21 CFR Part 11 compliance mandate enforcement and EMA 3R principle adoption velocity. Quarterly review of NIH grant award flows, microbubble agent regulatory submissions, and high-frequency transducer vendor qualification expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
US Imaging Services Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Ultrasound Systems Market