
 Mice Model Technologies Market | 2026-2036
Mice Model Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Mice Model Technologies Market Foresight
A shortage of trained veterinary pathologists and geneticists is redrawing competitive boundaries in the mice model technologies sector. Charles River Laboratories leverages its global breeding infrastructure to sustain long-term supply contracts with major pharmaceutical clients. The Jackson Laboratory anchors academic demand through its specialized repository of inbred and mutant strains. Taconic Biosciences differentiates through targeted service models for European biotech customers.
Mice model technologies encompass live mammalian systems, breeding methodologies, and genetic modification platforms used to replicate human disease pathways in controlled laboratory settings. CRISPR-based engineering now enables precise germline modifications within single-generation timelines, replacing slower traditional breeding approaches. Genetically engineered mice and knockout variants command premium positioning due to their specialized research utility in oncology and neurological studies. Contract research organizations represent the fastest-growing end-user channel as pharmaceutical sponsors outsource preclinical validation work.
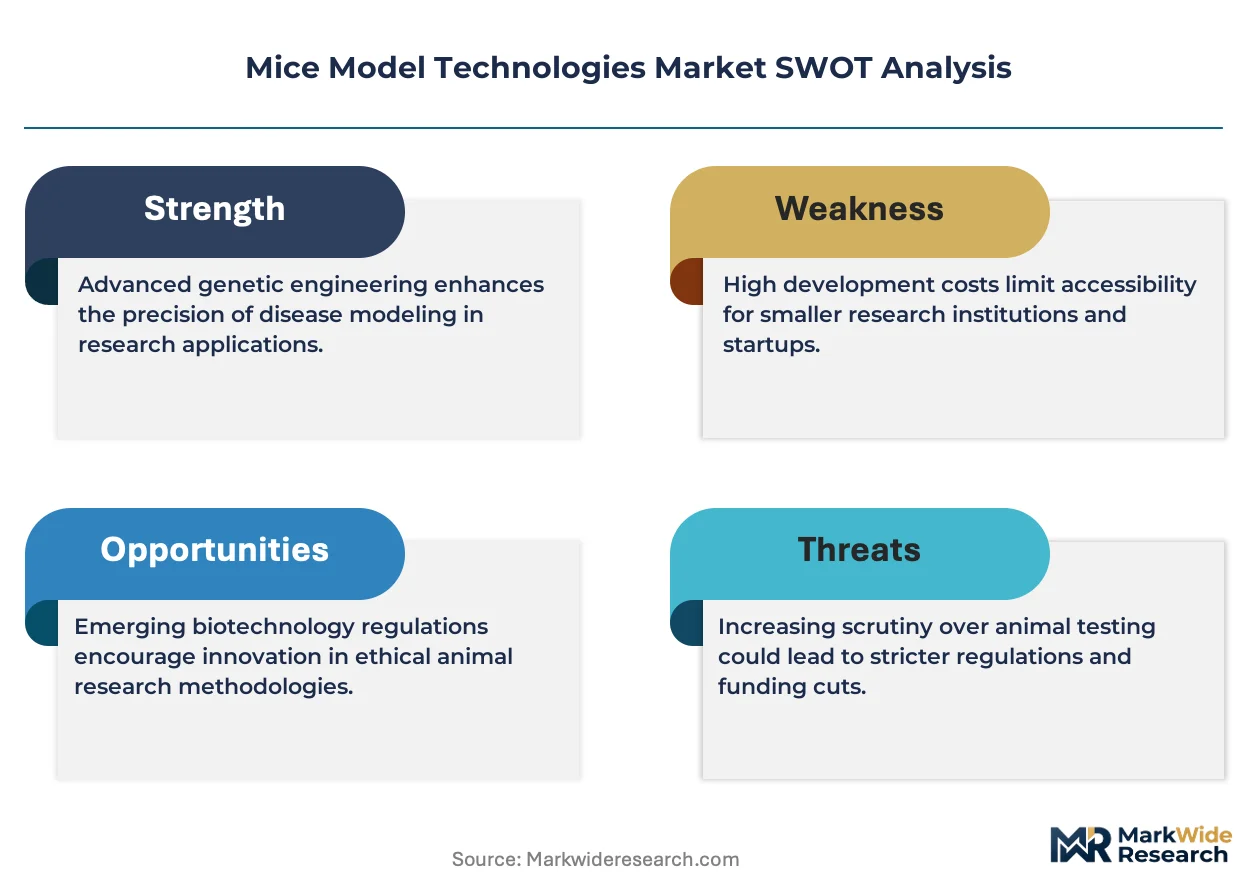
FDA guidelines for preclinical safety assessment and EPA protocols for environmental toxicology testing shape mandatory model specifications for U.S.-based drug developers. ISO 10993 biocompatibility standards and OECD test guidelines further constrain acceptable methodologies for international regulatory submissions. Stakeholders must monitor evolving FDA policy on humanized mouse models for immuno-oncology applications to anticipate qualification requirements for next-generation therapeutic platforms.
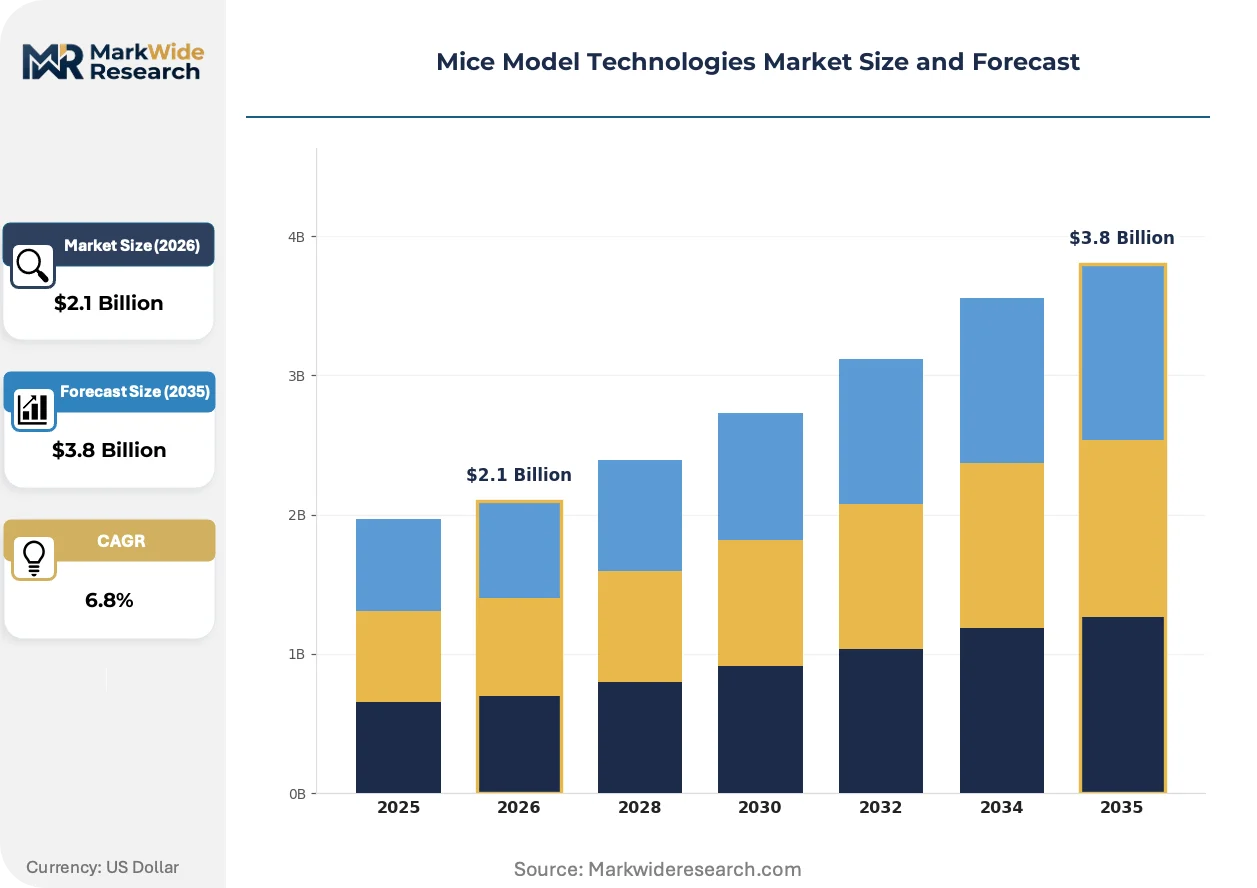
Market Dynamics
CRISPR-based germline engineering is compressing model development timelines from multi-year breeding cycles to single-generation modifications, fundamentally restructuring competitive positioning around speed-to-delivery rather than historical strain repositories.
Growth Catalysts
- Federal research funding:United States NIH allocations sustain large-scale academic breeding programs that anchor baseline demand for genetically engineered variants.
- OECD test guidelines:Mandatory preclinical protocols for environmental toxicology testing create recurring procurement cycles for standardized mouse cohorts.
- Contract research organizations:Pharmaceutical sponsors are outsourcing preclinical validation work to specialized service providers, expanding the fastest-growing end-user channel.
Market Restraints
- Specialized talent scarcity:Veterinary pathologists and geneticists command premium compensation, inflating operational costs for breeding facilities.
- Supply concentration risk:Repository-dependent breeding programs face single-source vulnerability when proprietary strains lack viable alternatives.
- ISO 10993 compliance friction:Biocompatibility certification requirements extend qualification timelines for novel humanized variants.
Strategic Opportunities
- Immuno-oncology applications:FDA policy evolution on humanized mouse qualification standards creates first-mover advantage for platform developers.
- European biotech demand:Taconic Biosciences' service model demonstrates addressable white space for specialized regional providers.
- CRISPR-NGS convergence:Integrated editing and sequencing workflows enable multiplexed validation, compressing downstream characterization cycles.
Industry Challenges
- Genetic drift management:Maintaining strain fidelity across distributed breeding colonies requires continuous genotyping surveillance and quality control investment.
- Legacy system integration:Digital phenotyping platforms must interface with established laboratory information management systems, creating implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mice Model Technologies Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetically Engineered Mice, Knockout Mice, Transgenic Mice, Spontaneous Mice Application: Oncology Research, Neurological Studies, Metabolic Disorders, Immunology Insights End User: Pharmaceutical Companies, Academic Research Institutions, Biotechnology Firms, Contract Research Organizations Technology: CRISPR, zygote-based Engineering, Traditional Breeding, Viral Vectors |
| Companies Covered | Charles River Laboratories, The Jackson Laboratory, Taconic Biosciences, Biocytogen, Cyagen Biosciences, GemPharmatech, genOway, Inotiv, Ozgene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mice Model Technologies Market Shifts & Advancements
Platform technologies are fragmenting traditional breeding value chains while regulatory scrutiny intensifies around model qualification standards. Three developments merit particular attention.
CRISPR-Cas9 multiplexing is decomposing the traditional sequential breeding paradigm by enabling simultaneous modification of multiple loci. Large pharmaceutical sponsors are adopting these platforms for oncology target validation programs. The technology is decomposing historical barriers between academic tool development and commercial model production.
EMA's evolving position on humanized mouse acceptability for biologics safety assessment is tightening qualification documentation requirements. Sponsors must now demonstrate graft stability and immune reconstitution kinetics with greater granularity. European contract research organizations are responding by investing in specialized vivarium infrastructure.
Biopharma procurement teams are consolidating supplier relationships around vertically integrated providers capable of delivering both models and downstream pathology services. This pattern displaces fragmented sourcing across separate breeding and analytical vendors. The United States exhibits the most pronounced consolidation, driven by sponsor demands for single-accountability contracting.
Mice Model Technologies Market Segmentation
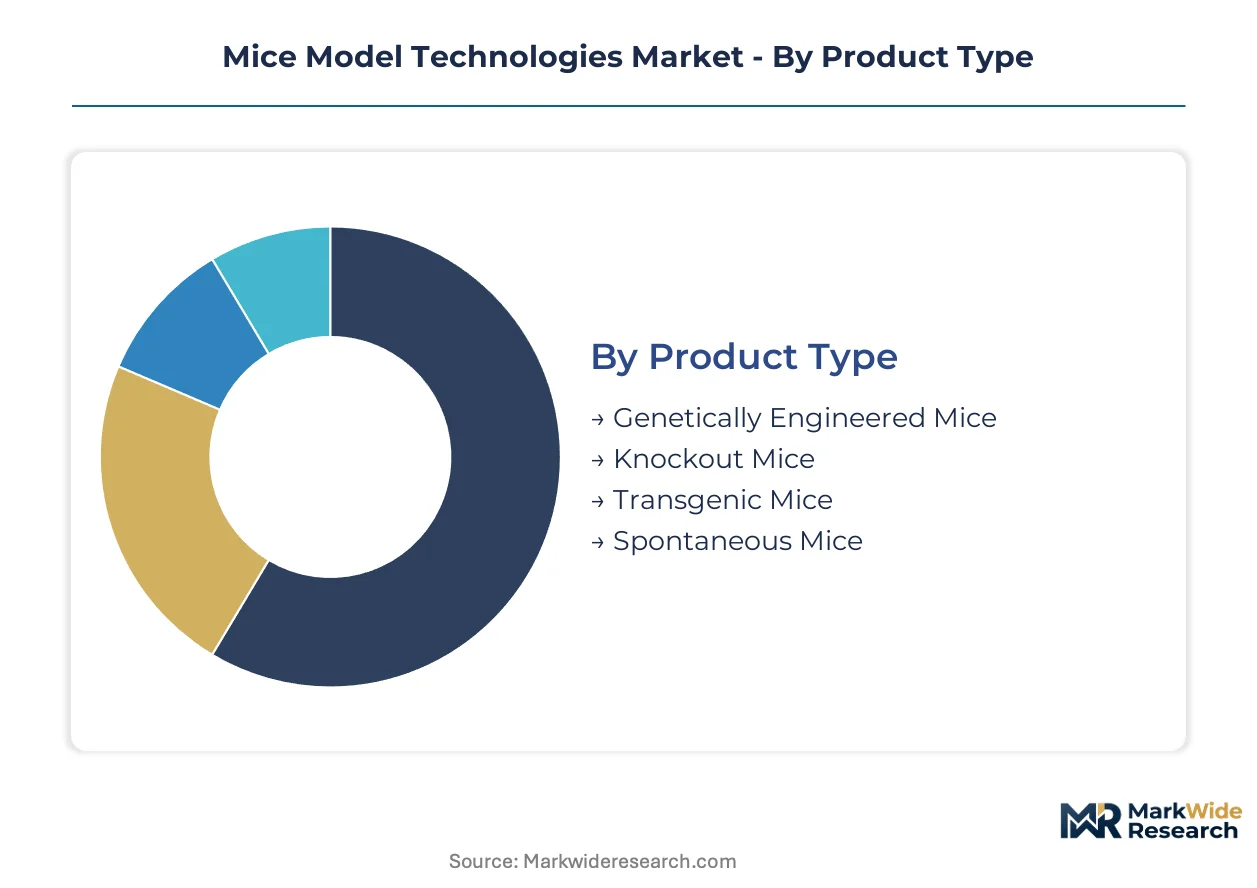
Segmentation in the mice model technologies market reveals distinct value capture patterns across genetic engineering platforms, therapeutic research domains, and customer procurement structures. Each dimension exposes different competitive dynamics: product types separate premium-engineered variants from commodity breeding outputs, while end-user channels diverge sharply between centralized pharmaceutical procurement and fragmented academic purchasing.
Product Type:
Substitution pressure concentrates most intensely on spontaneous mice as CRISPR-engineered alternatives compress development timelines and improve reproducibility. Traditional breeding-dependent segments face existential repositioning.
- Genetically Engineered Mice:Precise germline modifications enable single-generation disease pathway replication through CRISPR-Cas9 or homologous recombination techniques. Pharmaceutical oncology pipelines in the United States anchor demand, with sponsors prioritizing humanized immune system variants for immuno-oncology validation. FDA qualification standards for these models tighten continuously, extending commercialization timelines but reinforcing premium positioning.
- Knockout Mice:Targeted gene deletion strains eliminate specific protein expression to isolate disease mechanisms or validate therapeutic targets. Academic repositories in the United States maintain extensive collections, though commercial breeding facilities now compete through speed-to-delivery guarantees rather than historical strain depth alone.
- Transgenic Mice:Foreign gene insertion models express human proteins or reporter constructs for biomarker tracking. Demand clusters in neurological research applications where fluorescent tagging enables longitudinal imaging studies.
- Spontaneous Mice:Naturally occurring mutant strains developed through selective breeding without direct genetic manipulation. Cost advantages persist in basic toxicology screening, though CRISPR alternatives displace share in hypothesis-driven research programs.
Genetically engineered mice anchors the volume base while knockout variants gain share at the steepest rate as pharmaceutical sponsors accelerate target validation outsourcing.
Application:
Margin structures diverge sharply across therapeutic domains, with oncology commanding premium pricing due to humanized model complexity while metabolic disorder applications standardize around commodity cohort specifications.
- Oncology Research:Patient-derived xenograft and humanized immune system models replicate tumor microenvironment dynamics for immuno-oncology therapeutic development. CRISPR-engineered variants with multiplexed genetic modifications dominate preclinical validation for checkpoint inhibitor programs. United States-based contract research organizations invest heavily in specialized vivarium infrastructure to meet FDA documentation requirements.
- Neurological Studies:Alzheimer's, Parkinson's, and amyotrophic lateral sclerosis models require extended longitudinal observation protocols. Transgenic strains with age-dependent phenotypic progression support therapeutic mechanism studies, though model reproducibility challenges persist across breeding facilities.
- Metabolic Disorders:Obesity and diabetes models leverage leptin pathway mutations or diet-induced phenotypes. Standardized cohort procurement from commercial breeders dominates this application, with less customization than oncology or neurology segments.
- Immunology Insights:Autoimmune and infectious disease models require precise genetic background control for reproducible immune response characterization. Humanized variants with engrafted human immune components command substantial premiums but face graft stability validation burdens.
Neurological studies maintains the largest installed base of active research programs while immuno-oncology applications within oncology research demonstrate the steepest expansion trajectory.
End User:
Procurement concentration patterns separate consolidated pharmaceutical purchasing from fragmented academic decision-making, with biotechnology firms occupying an intermediate position on standardization and volume.
- Pharmaceutical Companies:Centralized procurement functions negotiate multi-year supply agreements with vertically integrated model providers. Preclinical safety assessment requirements under FDA and EPA protocols mandate standardized strain documentation and quality control traceability. Large sponsors increasingly outsource model validation to contract research organizations while retaining strategic breeding relationships for proprietary target programs.
- Academic Research Institutions:Federally funded breeding programs at the United States National Institutes of Health sustain baseline demand for inbred and mutant strain repositories. Principal investigator-driven purchasing fragments across multiple suppliers, though core facility consolidation is reshaping procurement patterns at major research universities.
- Biotechnology Firms:Emerging therapeutic developers balance custom model development against cost constraints through hybrid sourcing strategies. European biotech clusters demonstrate particular demand for specialized service models combining model supply with downstream pathology support.
- Contract Research Organizations:Pharmaceutical sponsor outsourcing of preclinical validation work positions this channel as the most dynamic demand source. Integrated providers offering both model supply and toxicology services capture disproportionate share growth as sponsors consolidate vendor relationships.
Pharmaceutical companies anchor procurement volume while contract research organizations demonstrate the most rapid demand acceleration as outsourcing penetration deepens.
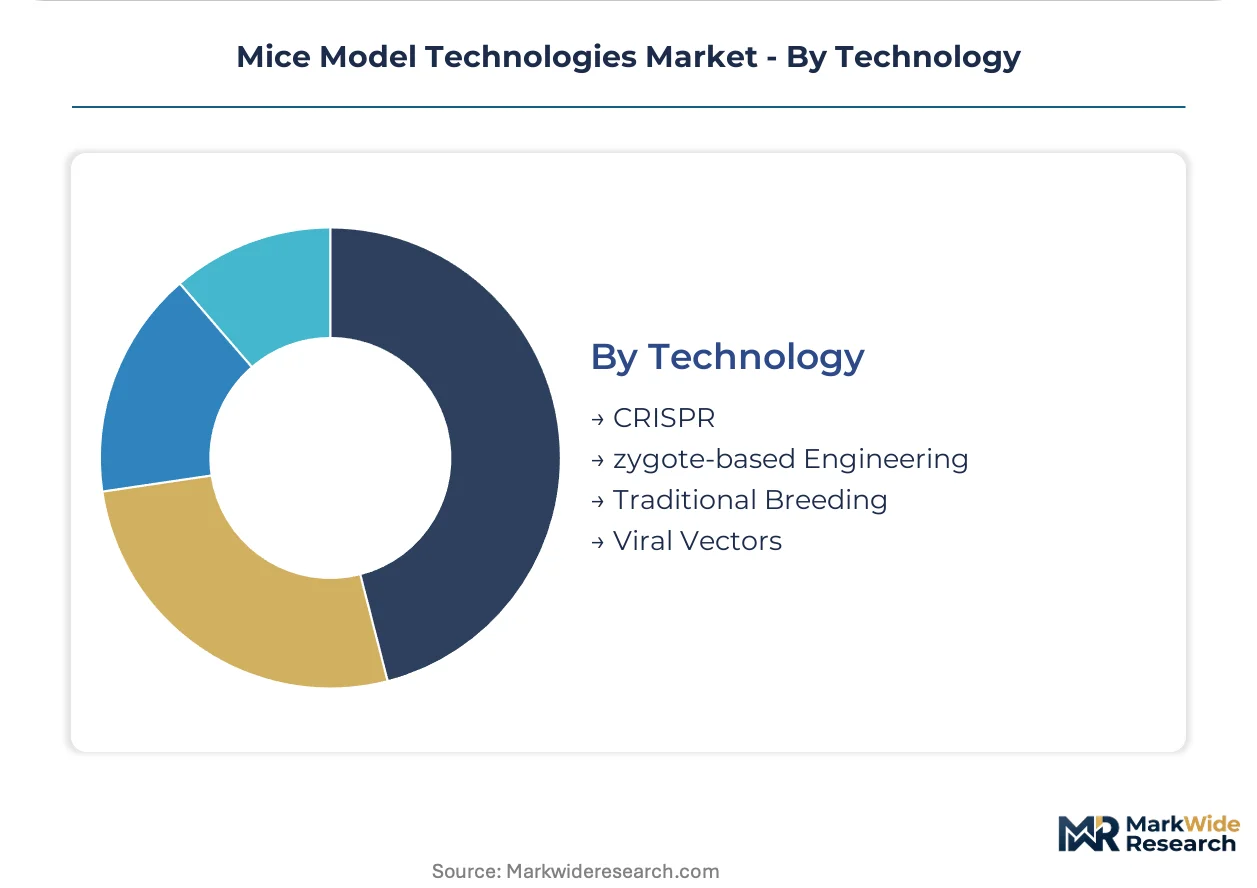
Technology:
Development timeline compression separates CRISPR-enabled platforms from legacy methodologies, with viral vector approaches occupying a narrowing niche for applications requiring transient rather than germline modification.
- CRISPR:Cas9-mediated double-strand breaks with homology-directed repair enable precise, multiplexed genetic modifications within single-generation timelines. Large pharmaceutical sponsors have adopted these platforms for internal oncology target validation, displacing traditional breeding for new model development. The technology dissolves historical barriers between academic tool development and commercial production.
- Zygote-based Engineering:Direct microinjection into fertilized eggs supports rapid founder generation for CRISPR or transgenic constructs. Specialized technical expertise requirements limit provider proliferation, concentrating supply among established breeding facilities with embryology capabilities.
- Traditional Breeding:Multi-generational backcrossing and selective mating maintains strain fidelity for established models. Cost advantages persist for standard inbred lines, though the approach faces irreversible displacement for complex genetic modifications.
- Viral Vectors:Lentiviral or adeno-associated virus delivery enables gene transfer without germline modification, supporting transient expression studies. Applications concentrate in proof-of-concept research rather than therapeutic validation programs requiring heritable genetic stability.
Traditional breeding retains volume leadership for standardized strain maintenance while CRISPR platforms capture all incremental growth in complex model development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European providers compete through specialized service differentiation. NIH allocations sustain premium positioning for domestic breeding programs. Asian facilities leverage cost structures for standardized strain production.
United States
Federal research funding through NIH sustains the world's largest academic breeding infrastructure. FDA guidelines for preclinical safety assessment mandate standardized strain documentation for pharmaceutical sponsors. The Boston-Cambridge corridor anchors commercial demand through dense pharmaceutical R&D concentration.
Germany
EMA qualification standards for humanized mouse models drive investment in specialized vivarium infrastructure. REACH protocols for environmental toxicology testing create recurring procurement cycles for standardized cohorts. The Munich-Heidelberg biotech cluster concentrates contract research organization expansion.
China
Domestic pharmaceutical R&D expansion accelerates demand for genetically engineered variants. NMPA evolving preclinical guidelines tighten documentation requirements for biologics safety assessment. The Yangtze River Delta biotech corridor attracts breeding facility investment from international providers.
United Kingdom
Academic research institutions maintain substantial inbred strain repositories through Medical Research Council funding. UK Home Office regulations on animal research procedures constrain breeding facility operational flexibility. The Oxford-Cambridge-London golden triangle concentrates oncology target validation outsourcing.
Japan
PMDA preclinical guidelines shape mandatory model specifications for domestic pharmaceutical developers. METI technology transfer programs accelerate CRISPR platform adoption in commercial breeding facilities. The Kansai region's pharmaceutical manufacturing base sustains demand for toxicology screening cohorts.
Mice Model Technologies Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Repository-dependent specialists command premium positioning through strain depth and qualification documentation. Speed-to-delivery platforms compete through compressed development timelines. Strategic moves concentrate on geographic expansion and integrated service bundling.
Among repository-anchored specialists, Charles River Laboratories and The Jackson Laboratory exemplify divergent positioning strategies. Taconic Biosciences occupies a position within the European service-focused tier, demonstrating regional specialization viability.
| Leading Market Players |
|---|
| Charles River Laboratories |
| The Jackson Laboratory |
| Taconic Biosciences |
| Biocytogen |
| Cyagen Biosciences |
| GemPharmatech |
| genOway |
| Inotiv |
| Ozgene |
| Others |
Supply & Pricing Matrix
Repository-scale breeding economies in the United States compress per-unit costs for standardized inbred strains while simultaneously elevating price floors for CRISPR-engineered variants through technical complexity premiums. Charles River Laboratories and The Jackson Laboratory leverage captive vivarium networks to sustain premium positioning against smaller competitors lacking comparable scale infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order CRISPR-engineered mice from catalog spontaneous strains. Project-based pricing dominates complex germline modifications, with FDA qualification documentation and ISO 10993 biocompatibility certification tiers driving substantial price differentiation. Cost compression in spontaneous mice intensifies as CRISPR alternatives displace share, while academic buyers exhibit greatest price sensitivity and pharmaceutical sponsors accept premiums for humanized immune system variants.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled live animal transport from Charles River's Wilmington, Massachusetts breeding hub to West Coast pharmaceutical R&D clusters constrain just-in-time delivery windows. Supply concentrates in the United States, Germany, and China, with germplasm repositories and specialized pathogen-free barrier facilities anchoring upstream capacity. The supply chain draws from cryopreserved embryo banks, live breeding colonies, and CRISPR reagent suppliers, with single-source vulnerability for proprietary knockout strains posing structural risk. Distribution runs through direct long-term contracts with pharmaceutical sponsors and academic core facility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-NGS convergence is disrupting traditional multi-year breeding timelines, compressing model development to single-generation cycles and rewiring competitive advantage around speed rather than historical strain depth.
For Market Incumbents: Fortify repository value through continuous genotyping surveillance investments that prevent genetic drift across distributed colonies. Pursue backward integration into pathology services to capture downstream analytical revenue streams threatened by CRO consolidation. Charles River Laboratories' global infrastructure demonstrates how captive breeding networks defend against emerging CRISPR-platform specialists. For New Entrants and Emerging Players: FDA qualification fast-tracks for humanized mouse variants open immediate white-space opportunity in immuno-oncology validation services. European biotech clusters present penetrable geography where Taconic Biosciences' regional service model validates specialized provider viability. A go-to-market angle combining CRISPR platform access with integrated toxicology reporting addresses unmet demand from mid-size pharmaceutical sponsors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated CROs with captive model supply rather than standalone breeding specialists facing margin compression. Long-term viability hinges on regulatory qualification depth and sponsor relationship stickiness. The signal to watch is FDA policy evolution on humanized mouse standards for biologics safety assessment, which would recalibrate platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Scale-Up | Compresses development timelines from multi-year breeding to single-generation modifications for oncology pipelines. |
| Humanized Mouse Qualification | Anticipates FDA documentation requirements for immuno-oncology therapeutic validation programs. |
| Integrated Pathology Services | Captures downstream analytical revenue through bundled model supply and toxicology reporting. |
| European Service Expansion | Addresses specialized demand from Munich-Heidelberg and Oxford-Cambridge-London biotech clusters. |
| Cryopreservation Infrastructure | Secures genetic fidelity against drift risks across distributed breeding colonies. |
Research Methodology
A standing panel of preclinical development executives, veterinary pathologists, regulatory affairs specialists, and academic core facility directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with breeding facility operations managers and pharmaceutical procurement leads, validated against secondary sources including FDA preclinical guidance documents, NIH funding allocation databases, and OECD test guideline protocols. Bottom-up strain-level demand modeling and top-down therapeutic pipeline analysis were triangulated for consistency.
Consistency checks validated volume and value outputs against external benchmarks including pharmaceutical R&D expenditure patterns and CRO outsourcing penetration metrics. The analytical framework segmented demand across genetic engineering platforms, therapeutic research domains, and procurement channels throughout the projection horizon. CAGRs were derived from modeled adoption curves for CRISPR-engineered variants and documented sponsor outsourcing trends. Industry-specific inputs included NIH allocation trajectories and EMA qualification standard evolution for humanized models.
Decision-makers should treat outputs as directional under assumptions of sustained federal research funding and stable regulatory qualification pathways; material deviation in FDA humanized mouse policy or NIH appropriations would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Forensic Medicine Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
North America Biobanks Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
PDX Models Market
Medical Research
Global Human Liver Models Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Metabolomics Market
Medical Research
Preventive Medicine Market
Medical Research
Global Mice Model Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Europe AMH Market
Medical Research
Malaria Vaccine Market
Medical Research
Precision Medicine Market