
 Global Acute Agitation and Aggression Treatment Market | 2026-2036
Global Acute Agitation and Aggression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Agitation and Aggression Treatment Market Foresight
Market Context
The acute agitation and aggression treatment landscape is pivoting around a widening split between premium patented formulations and commoditized generic benzodiazepines. Eli Lilly and Company leverages its established antipsychotic portfolio to sustain premium positioning in emergency psychiatric settings. Pfizer, Inc. competes through manufacturing scale across multiple dosage forms, while Johnson & Johnson anchors its presence with long-acting injectable platforms that reduce readmission rates.
Technical and Segment Structure
Acute agitation and aggression treatment encompasses pharmacological interventions designed to rapidly de-escalate violent or severely disruptive behavior, typically achieving therapeutic onset within 15-60 minutes through intramuscular or intravenous delivery. Antipsychotics dominate emergency department formularies due to their dual efficacy for agitation and underlying psychosis, while intramuscular injection leads delivery mode preference where oral compliance is impossible. Combination therapies represent the fastest-expanding segment as protocols increasingly layer benzodiazepines with antipsychotics for refractory presentations.
Regulatory Environment
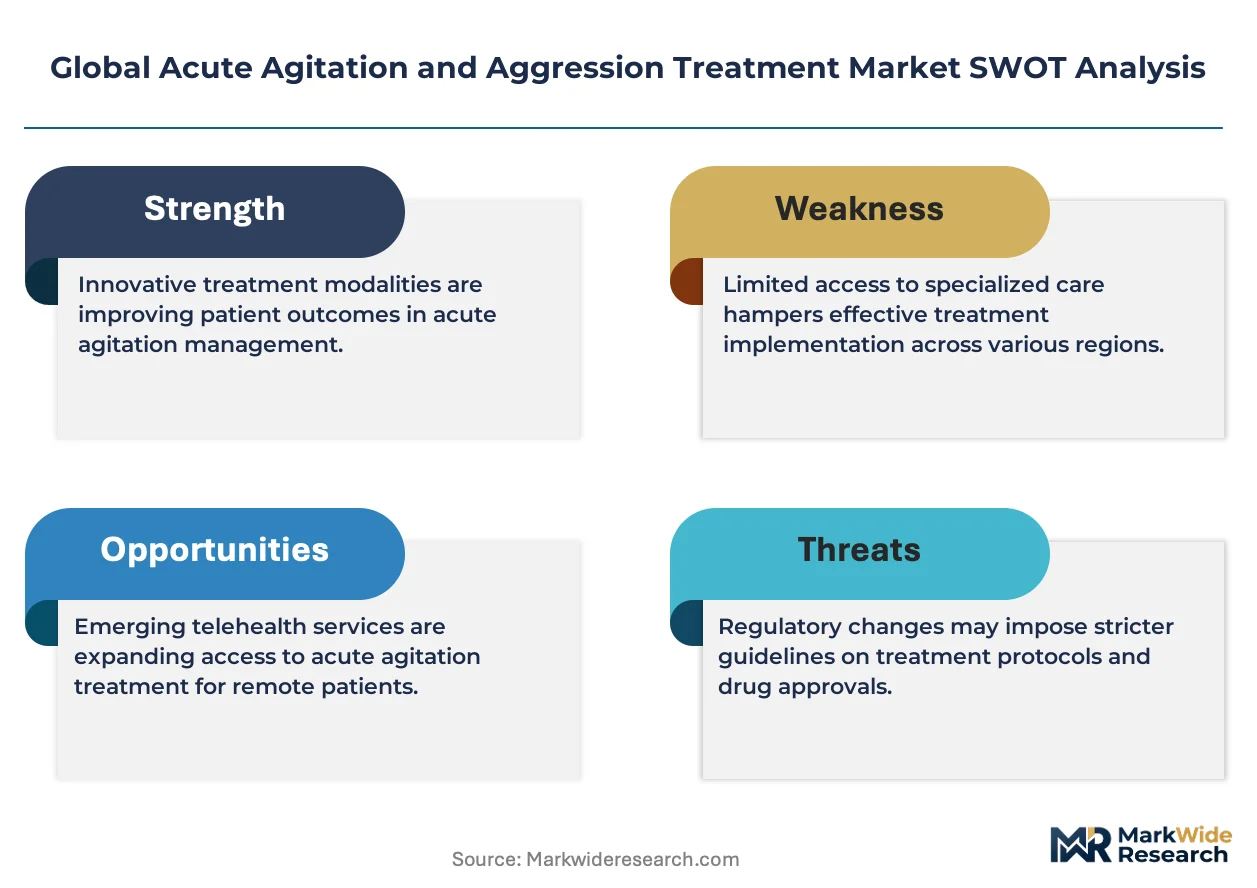
The FDA oversees new drug approvals and post-market safety surveillance for all formulations used in acute psychiatric emergencies, while the EMA's centralized procedure governs market access across European Union member states and the PMDA evaluates novel agents for Japan's psychiatric hospital networks. Regulatory scrutiny of QT prolongation risk and metabolic side effects directly shapes clinical trial designs and label expansions for new entrants. Stakeholders must monitor evolving REMS requirements and pharmacovigilance obligations as novel rapid-onset mechanisms advance through development pipelines.
Market Dynamics
The FDA's accelerated approval pathways for novel antipsychotic formulations are compressing development timelines and forcing established emergency psychiatry protocols to accommodate faster therapeutic onboarding.
Growth Catalysts
- REMS Flexibility:The FDA's evolving Risk Evaluation and Mitigation Strategies framework is streamlining post-market surveillance for rapid-acting injectables, reducing time-to-formulary placement in emergency departments.
- German Hospital Protocol Standardization:Hospital-based psychiatric emergency units across Germany are mandating rapid-acting injectable therapies as first-line intervention, creating concentrated demand pull.
- Combination Therapy Protocols:Emergency medicine residency programs are training physicians to layer benzodiazepines with antipsychotics for refractory agitation, expanding the addressable patient pool.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient manufacturing for second-generation antipsychotics concentrates in Chinese and Indian contract manufacturers, exposing supply chains to geopolitical friction.
- QT Prolongation Liability:Regulatory scrutiny of cardiac arrhythmia risk forces expensive electrocardiographic monitoring requirements that limit outpatient administration expansion.
- Generic Benzodiazepine Substitution:Commoditized lorazepam and midazolam formulations capture cost-sensitive hospital formularies, pressuring premium patented antipsychotic pricing power.
Strategic Opportunities
- Japan's Psychiatric Hospital Networks:The PMDA's streamlined review pathways for psychiatric emergencies remain underpenetrated by rapid-acting intramuscular platforms, offering first-mover positioning.
- Pre-Hospital Administration:Emergency medical services protocols in the United States are expanding paramedic scope to include intramuscular antipsychotic administration prior to hospital arrival.
- Long-Acting Injectable Convergence:Integration of acute agitation management with maintenance antipsychotic therapy is creating bundled protocol opportunities that reduce readmission-driven penalties.
Industry Challenges
- Psychiatric Emergency Medicine Specialist Shortage:Fellowship-trained emergency psychiatrists remain scarce in rural and suburban United States markets, constraining protocol adoption outside academic medical centers.
- REMS Compliance Infrastructure:Manufacturers must maintain costly distribution and prescriber certification systems that fragment operational focus from core R&D activities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Agitation and Aggression Treatment Market |
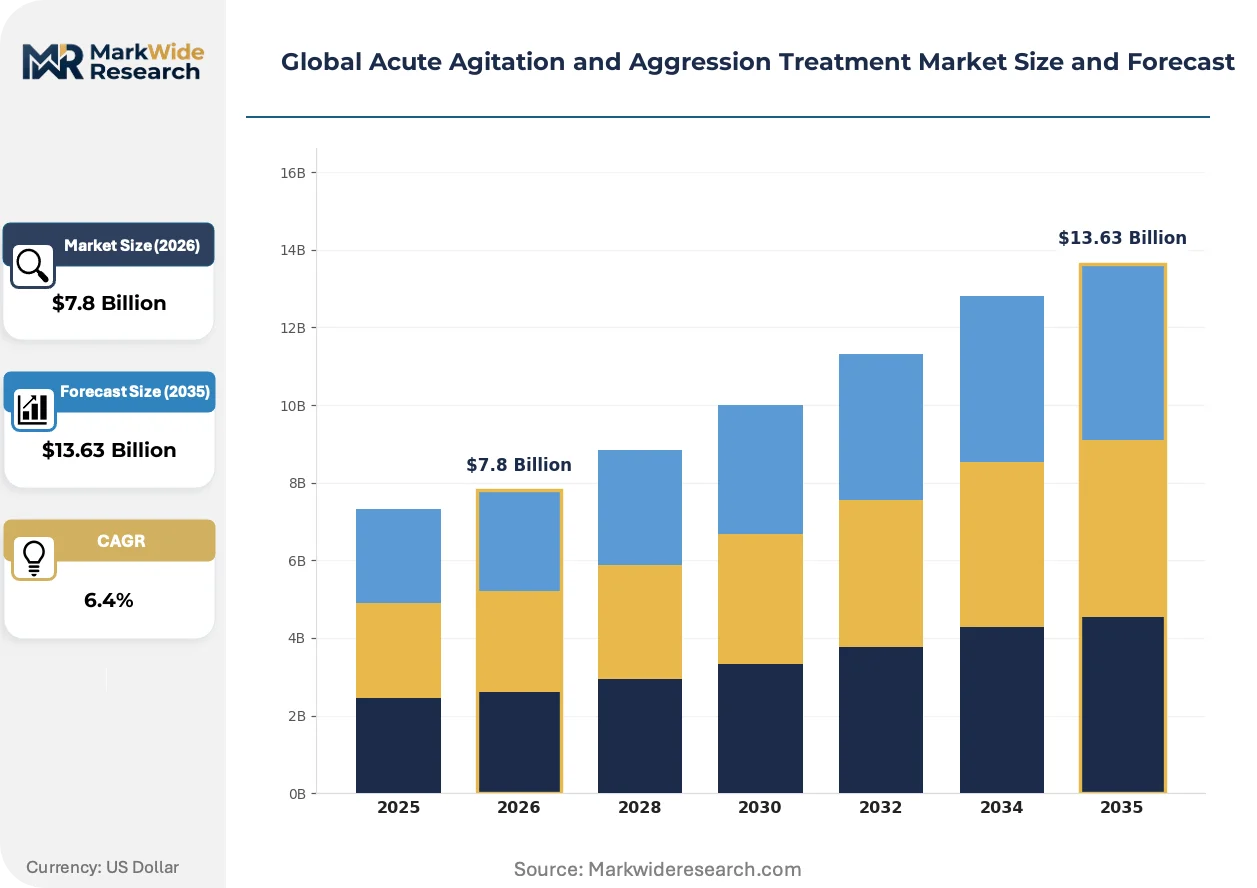
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Benzodiazepines, Mood Stabilizers, Combination Therapies Therapy Area: Schizophrenia, Bipolar Disorder, Dementia, Post-Traumatic Stress Disorder Care Setting: Emergency Departments, Psychiatric Units, Long-Term Care Facilities, Outpatient Clinics Delivery Mode: Oral Tablets, Intramuscular Injection, Intravenous Infusion, Nasal Spray |
| Companies Covered | Eli Lilly and Company, Pfizer, Inc., Johnson & Johnson, GlaxoSmithKline, H. Lundbeck A/S, Otsuka Pharmaceutical Co., Ltd., Bristol-Myers Squibb, Roche, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Agitation and Aggression Treatment Market Shifts & Advancements
Formulation science and regulatory science are converging to reshape how acute agitation therapies reach emergency settings, with delivery mechanism innovation outpacing molecular discovery.
Inhaled antipsychotic delivery systems are integrating precision dose-control mechanisms with rapid pulmonary absorption profiles. Emergency departments in the United States are piloting these platforms for patients with needle phobia or bleeding risk contraindications. This convergence is integrating non-invasive administration into protocols previously dominated by intramuscular injection, compressing the time-to-therapeutic-effect gap.
The EMA's centralized procedure for psychiatric emergency medications is tightening cardiovascular safety documentation requirements ahead of marketing authorization. This policy shift is forcing sponsors to conduct larger Phase III trials with mandatory telemetry monitoring. Manufacturers targeting European Union access are responding by embedding cardiac safety endpoints earlier in development pipelines.
Hospital procurement committees are consolidating vendor relationships around full-spectrum agitation management contracts that span acute intervention through maintenance therapy. This behavioral shift is displacing single-product purchasing agreements in favor of integrated formulary partnerships. The United States academic medical center segment exhibits the most visible consolidation, with three-to-five-year sole-source agreements replacing annual competitive bidding cycles.
Global Acute Agitation and Aggression Treatment Market Segmentation
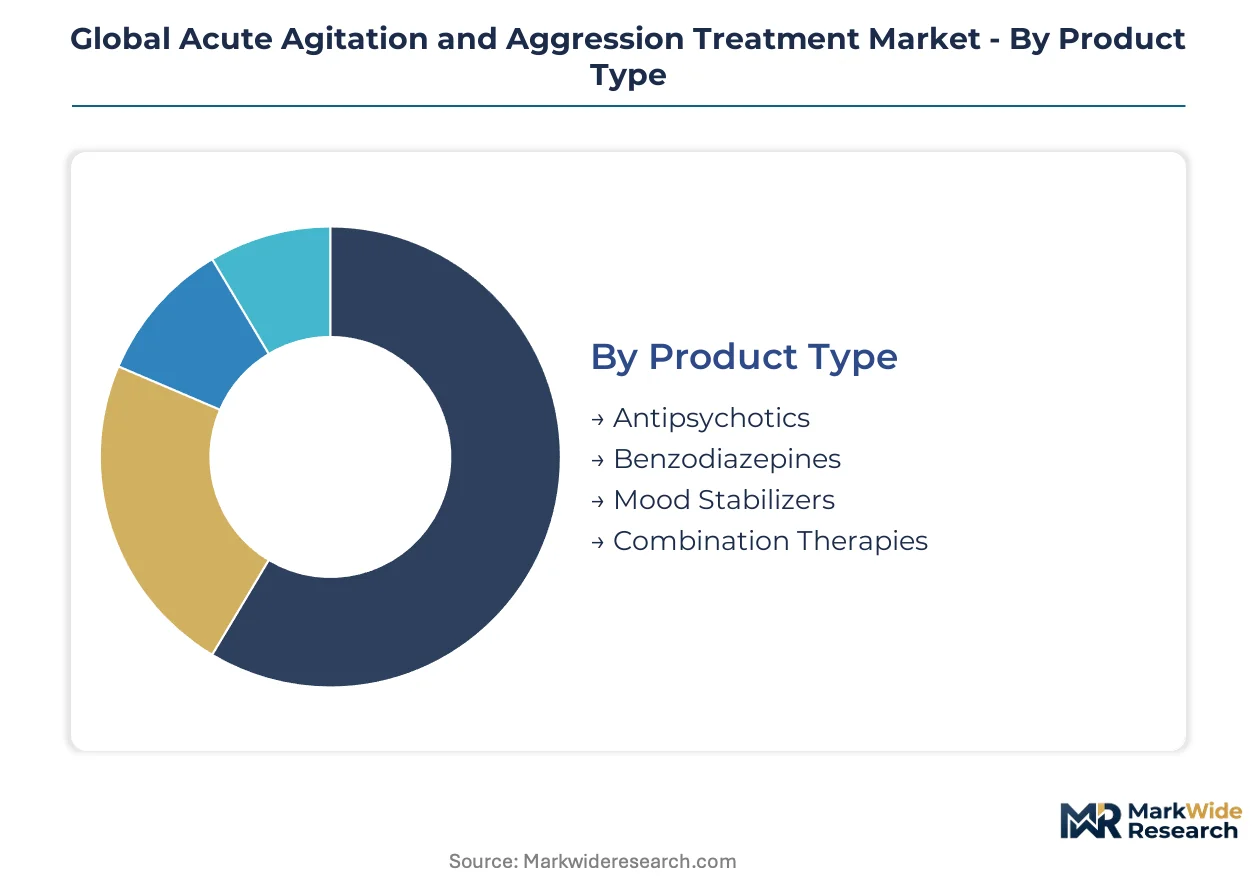
Acute agitation and aggression treatment markets fragment across pharmacological mechanism, clinical indication, and care setting. Supply chain configuration and regulatory approval pathways differ sharply across these boundaries, reshaping competitive positioning for manufacturers.
Product Type:
Active pharmaceutical ingredient sourcing concentrates differently across these four pharmacological classes, with second-generation antipsychotic manufacturing clustering in Asian contract manufacturers while benzodiazepine synthesis retains more geographic dispersion.
- Antipsychotics:Second-generation formulations such as olanzapine and ziprasidone achieve therapeutic onset within 15-30 minutes via intramuscular delivery. Emergency departments in the United States favor these agents for psychosis-driven agitation, though QT prolongation monitoring requirements constrain outpatient expansion.
- Combination Therapies:Layered benzodiazepine-antipsychotic protocols target refractory presentations unresponsive to monotherapy. German hospital emergency units increasingly mandate these combinations as first-line intervention, creating concentrated demand pull for co-formulation development.
- Benzodiazepines:Lorazepam and midazolam remain cost-competitive staples with rapid anxiolytic effect.
- Mood Stabilizers:Valproate and lithium formulations serve bipolar-specific agitation presentations with slower onset profiles.
Antipsychotics absorb the bulk of installed capacity; combination therapies are expanding most quickly.
Therapy Area:
Clinical indication shapes reimbursement pathways and prescriber training requirements, with dementia-related agitation facing distinct regulatory hurdles compared to primary psychiatric disorders.
- Schizophrenia:Acute exacerbations drive the highest volume of emergency psychiatric encounters, with dopamine antagonism providing both agitation control and psychosis resolution. The FDA's accelerated approval pathways for novel antipsychotic formulations target this indication preferentially.
- Bipolar Disorder:Mixed and manic episodes require rapid mood stabilization alongside behavioral de-escalation. Academic medical centers in the United States are piloting bundled protocols that transition patients seamlessly from acute intervention to maintenance therapy.
- Dementia:Behavioral and psychological symptoms in Alzheimer's disease present unique safety challenges given cardiovascular comorbidities and fall risk.
- Post-Traumatic Stress Disorder:Trauma-informed care protocols increasingly restrict coercive medication administration, favoring voluntary oral uptake.
Schizophrenia claims the greatest addressable patient volume; bipolar disorder demonstrates the steepest protocol innovation trajectory.
Care Setting:
Facility type determines staffing ratios, monitoring capabilities, and formulary autonomy, with emergency departments maintaining the broadest therapeutic armamentarium.
- Emergency Departments:Twenty-four-hour psychiatric crisis services in United States hospitals administer the full spectrum of injectable and oral agents. Telemetry availability enables QT-prolonging antipsychotic use that would be unsafe in lower-acuity environments.
- Psychiatric Units:Locked inpatient settings prioritize long-acting injectable platforms to reduce readmission penalties. Johnson & Johnson anchors its presence here with extended-release formulations that bridge acute and maintenance phases.
- Long-Term Care Facilities:Regulatory restrictions on chemical restraint limit pharmacological options for dementia-related agitation.
- Outpatient Clinics:Oral tablet formulations dominate where rapid onset is less critical and patient cooperation permits.
Emergency departments command the highest per-patient medication expenditure; psychiatric units are gaining share fastest through bundled care contracts.
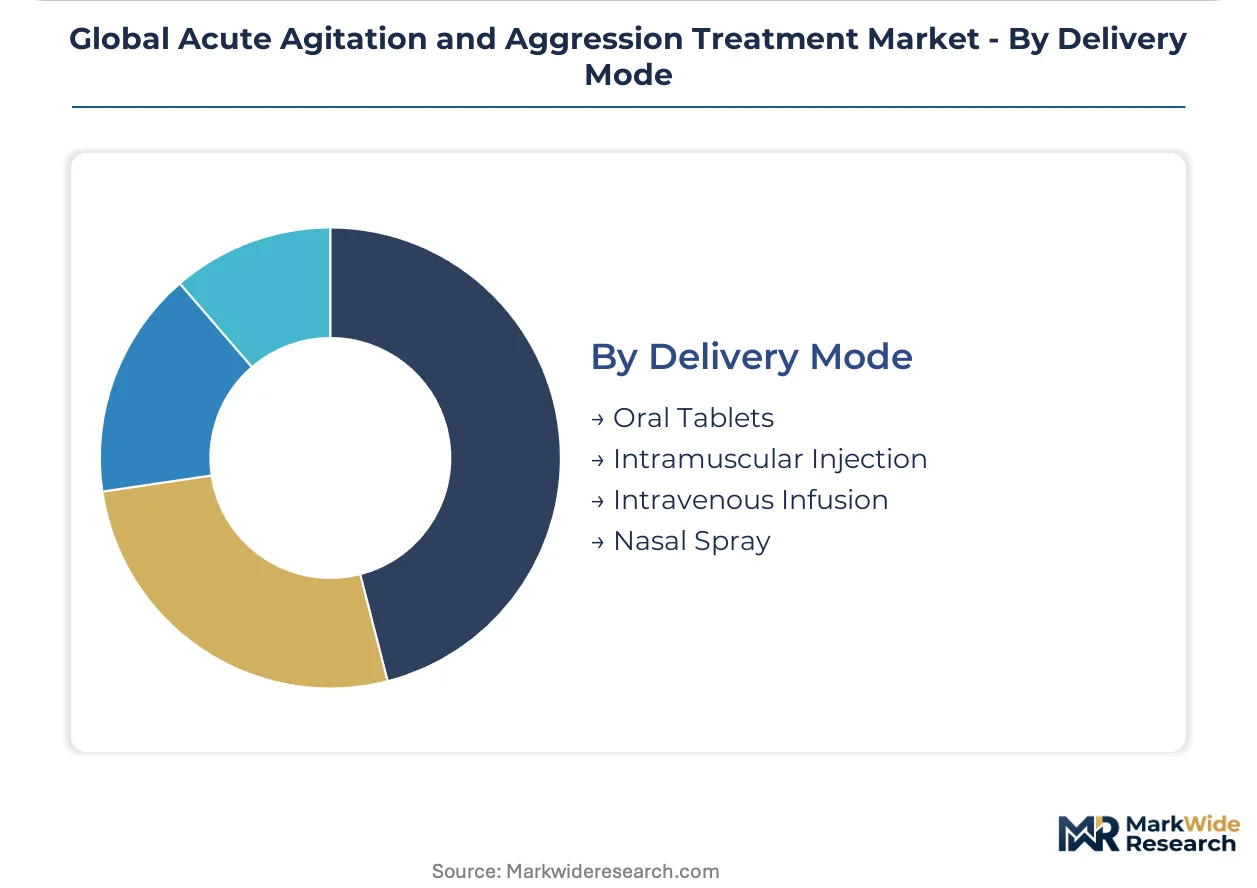
Delivery Mode:
Route of administration determines onset speed, patient acceptability, and required clinical infrastructure, with injectable formats concentrating in hospital-based settings.
- Intramuscular Injection:Rapid absorption through deltoid or gluteal administration achieves therapeutic levels within 15-30 minutes. Paramedic scope expansion in United States emergency medical services is extending pre-hospital administration prior to hospital arrival.
- Nasal Spray:Pulmonary and intranasal absorption profiles offer needle-free alternatives for patients with bleeding disorders or severe phobia. Pilot programs in United States emergency departments are integrating these platforms into voluntary uptake protocols.
- Intravenous Infusion:Immediate bioavailability serves the most severe presentations requiring continuous titration.
- Oral Tablets:Sublingual and standard oral formulations retain role in cooperative patients with lower acuity.
Intramuscular injection maintains dominant procedure volume; nasal spray formats are climbing the fastest as non-invasive alternatives gain protocol acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor drives psychiatric emergency protocol innovation, with Massachusetts General Hospital and Brigham and Women's Hospital piloting integrated agitation management pathways that bridge pre-hospital and emergency department care.
United States
Emergency departments across the United States are expanding dedicated psychiatric crisis services with 24-hour staffing. The FDA's accelerated approval pathways compress development timelines for novel rapid-acting formulations. Academic medical centers in Boston, New York, and San Francisco pilot bundled protocols that transition patients from acute intervention to maintenance therapy.
Germany
Hospital-based psychiatric emergency units mandate rapid-acting injectable therapies as first-line intervention. The EMA's centralized procedure governs market access with tightening cardiovascular safety documentation requirements. Industrial pharmaceutical clusters in Bavaria and North Rhine-Westphalia concentrate manufacturing capacity for second-generation antipsychotic APIs.
Japan
Psychiatric hospital networks remain underpenetrated by rapid-acting intramuscular platforms despite streamlined PMDA review pathways. The country's national pharmaceutical regulator evaluates novel agents for emergency use with emphasis on geriatric safety profiles. Tokyo and Osaka metropolitan areas concentrate specialized emergency psychiatry fellowship programs.
United Kingdom
NHS England procurement frameworks favor cost-effective generic benzodiazepines over premium patented antipsychotics in emergency settings. The MHRA oversees post-Brexit regulatory alignment with EMA safety standards. London's Maudsley Hospital and South London and Maudsley NHS Foundation Trust anchor clinical trial recruitment for novel inhaled delivery systems.
India
Contract manufacturing facilities in Hyderabad and Ahmedabad supply active pharmaceutical ingredients for second-generation antipsychotics consumed in Western markets. The CDSCO streamlines approval pathways for psychiatric emergency medications with bioequivalence requirements. Domestic hospital networks in Mumbai and Delhi expand emergency psychiatry capacity amid rising urban mental health demand.
Global Acute Agitation and Aggression Treatment Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across the acute agitation treatment landscape. The market structure consolidates around three strategic tiers: diversified pharmaceutical conglomerates with established antipsychotic portfolios, mid-cap specialists focused on rapid-onset delivery mechanisms, and generic manufacturers competing on benzodiazepine cost. Dominant competitive moves include strategic partnerships between device developers and pharmaceutical sponsors for non-invasive delivery platforms, and geographic expansion into underpenetrated Asian psychiatric hospital networks.
Among North American pharmaceutical conglomerates, Eli Lilly and Company and Pfizer, Inc. occupy positions representing the diversified portfolio archetype, while Johnson & Johnson anchors the long-acting injectable specialization tier. These three entities exemplify distinct strategic postures: premium patented formulation defense, manufacturing scale across dosage forms, and integrated acute-to-maintenance therapy bundling respectively.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Pfizer, Inc. |
| Johnson & Johnson |
| GlaxoSmithKline |
| H. Lundbeck A/S |
| Otsuka Pharmaceutical Co., Ltd. |
| Bristol-Myers Squibb |
| Roche |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Captive API production for second-generation antipsychotics anchors both supply security and pricing power for integrated pharmaceutical conglomerates, while contract manufacturers in India and China serve cost-optimized generic benzodiazepine demand. This bifurcation concentrates margin capture among vertically positioned players and fragments pricing leverage across the formulation tier.
Pricing Analysis
Outcome-linked reimbursement for readmission reduction anchors premium pricing for long-acting injectable platforms, while per-dose transactional pricing governs acute emergency department use. Price differentiation hinges on FDA REMS certification status and hospital formulary tier placement, with academic medical centers exhibiting lowest sensitivity and rural emergency services facing acute cost compression. Generic lorazepam substitution intensifies pricing pressure in cost-sensitive hospital systems.
Supply Chain Analysis
Active pharmaceutical ingredient supply for olanzapine and ziprasidone rests on contract manufacturing facilities in Hyderabad, Ahmedabad, and select Chinese industrial zones. Key inputs include specialty chemical intermediates, sterile manufacturing equipment, and cold-chain distribution infrastructure. Single-source vulnerability concentrates in Indian API synthesis for second-generation antipsychotics. Distribution runs through hospital procurement consortia and group purchasing organizations with three-to-five-year contract cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity constraints for rapid-acting injectable therapies prop premium pricing, with Chinese and Indian contract facility utilization rates sustaining margin structures for integrated players.
For Market Incumbents: Deepen backward integration into specialty chemical intermediate production to offset API concentration risk in Asian contract manufacturers. Secure REMS certification infrastructure as a defensive moat against generic benzodiazepine substitution in emergency department formularies. For New Entrants and Emerging Players: Rural and suburban United States emergency departments present the most penetrable buyer archetype, given psychiatric emergency medicine specialist shortages constraining protocol adoption. Target pre-hospital administration partnerships with emergency medical services as a differentiated go-to-market pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking rapid-onset formulation capabilities. Long-term viability favors platforms with integrated acute-to-maintenance therapy bundling. Watch FDA accelerated approval pathway expansion for novel delivery mechanisms as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Infrastructure | Establishes mandatory distribution controls that lock out generic competitors from premium hospital formularies. |
| Pre-Hospital Administration Partnership | Expands addressable market into emergency medical services scope expansion prior to hospital arrival. |
| API Manufacturing Scale-Up | Reduces single-source dependency on Indian and Chinese contract manufacturers for second-generation antipsychotics. |
| Inhaled Delivery System Development | Captures needle-phobic patient segments through pulmonary absorption platforms piloted in United States academic centers. |
| Long-Acting Injectable Convergence | Bundles acute intervention with maintenance therapy to reduce hospital readmission penalties under value-based contracts. |
Research Methodology
Multi-period observation of FDA approval timelines, EMA centralized procedure outcomes, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with emergency psychiatry fellowship directors, hospital procurement managers, regulatory affairs leads at pharmaceutical sponsors, and group purchasing organization contract specialists. Secondary validation drew from FDA REMS documentation, EMA assessment reports, ClinicalTrials.gov enrollment data, and hospital procurement database disclosures. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-verified segment sizing.
Input-output matrices mapped pharmacological mechanism to care setting demand, dosage form to regulatory pathway, and geographic market to reimbursement structure across the projection horizon. Segmentation dimensions included product type, therapy area, care setting, delivery mode, and regional regulatory cluster. CAGRs derived from historical approval-to-adoption lag analysis and protocol penetration curves. Forecast inputs incorporated psychiatric emergency encounter volume trajectories and REMS program expansion timelines.
Revisions become necessary when FDA accelerated approval pathway criteria shift, major API manufacturing facilities face regulatory action, or hospital reimbursement structures pivot from fee-for-service to bundled episode payments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market