
 Autism Spectrum Disorder Management Market | 2026-2036
Autism Spectrum Disorder Management Market Size, Share, and Industry Trends Forecast 2026-2036
Autism Spectrum Disorder Management Market Outlook
Artificial intelligence-driven diagnostic screening is rewriting how clinicians identify autism spectrum conditions in early childhood. Eli Lilly and Company leverages decades of psychiatric drug development to anchor its presence in pediatric neuropharmacology. AbbVie Inc. competes through sustained investment in neurology pipelines targeting social communication deficits. Johnson & Johnson differentiates by operating integrated care networks that bridge pharmaceutical and behavioral interventions.
Autism spectrum disorder management encompasses pharmacological, behavioral, and educational interventions designed to reduce core symptom severity and improve adaptive functioning across social, communicative, and repetitive behavior domains; diagnostic protocols typically incorporate standardized instruments such as the ADOS-2 and ADI-R alongside clinician judgment to establish severity classifications and tailor intervention intensity. The medications segment dominates current revenue as pharmaceutical developers pursue novel targets for irritability and social withdrawal, while the telehealth delivery mode represents the fastest-expanding channel as asynchronous therapy platforms and remote parent coaching dissolve geographic barriers to specialist access. Behavioral therapy retains the deepest margin pool due to recurring session-based billing and payer-mandated treatment hour minimums, particularly for applied behavior analysis.
The FDA maintains stringent pediatric trial requirements for neurodevelopmental therapeutics, while HIPAA governs how telehealth platforms handle protected health information during remote autism assessments. The EMA's pediatric investigation plans further shape European development timelines and label claims for autism-related pharmaceuticals. Stakeholders must monitor how evolving FDA digital health guidance and state-level insurance parity statutes reshape competitive access and reimbursement architecture.
Market Dynamics
State-level insurance parity mandates in the United States are compressing access barriers while FDA pediatric trial requirements for neurodevelopmental drugs extend development timelines and reshape competitive entry sequencing.
Growth Catalysts
- Telehealth platform penetration:Asynchronous therapy delivery and remote parent coaching dissolve geographic distance to board-certified behavior analysts, particularly in rural counties across the United States.
- HIPAA-aligned telehealth infrastructure:Clarified guidance on protected health information handling during remote autism assessments reduces platform liability exposure and accelerates payer contract negotiations.
- Special education budget expansion:School districts in the United States and Germany are allocating dedicated line items for digital behavioral therapy platform licensing and staff training.
Market Restraints
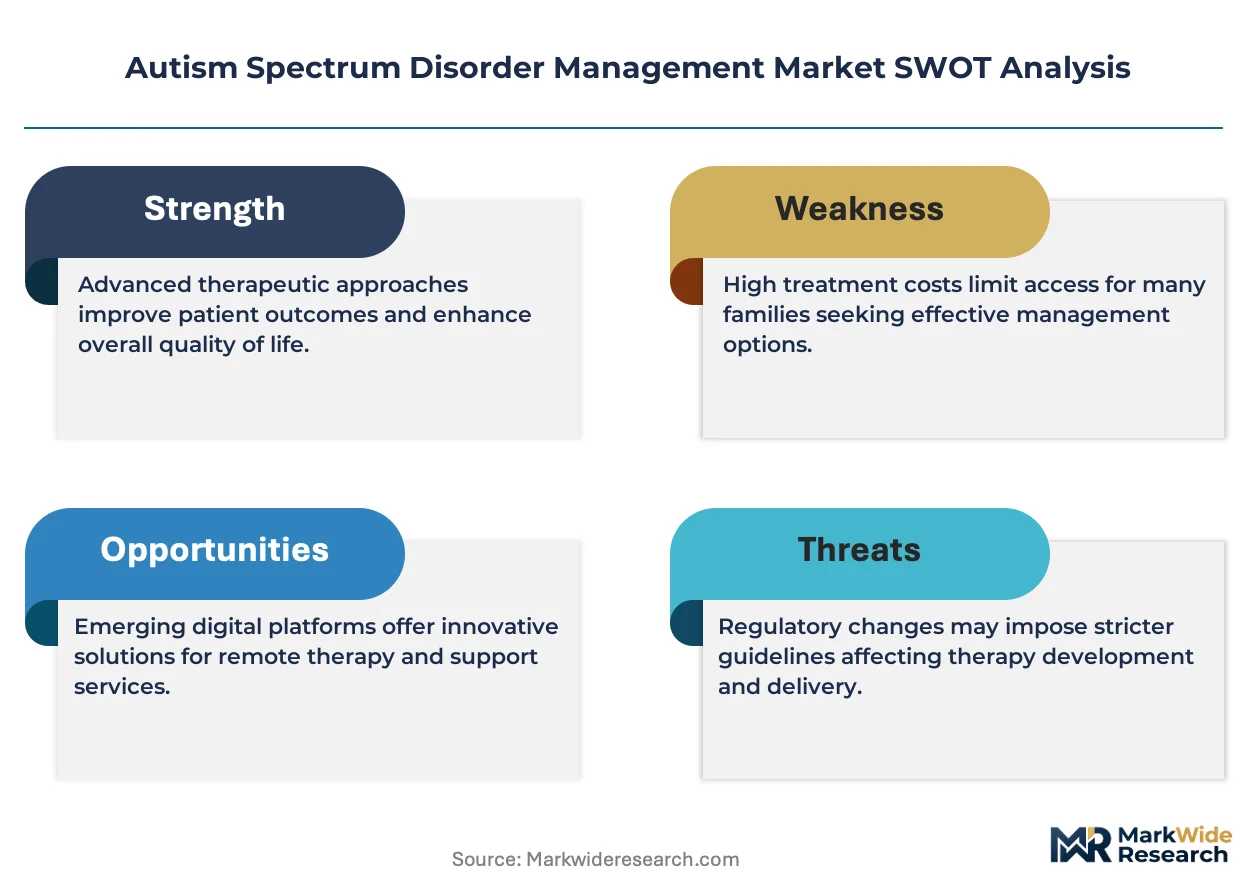
- Specialist workforce scarcity:Board-certified behavior analyst credentialing bottlenecks in the United States create waitlists exceeding twelve months in high-demand metropolitan areas.
- Pediatric trial cost structure:FDA-mandated long-term safety monitoring for neurodevelopmental therapeutics adds substantial per-patient expense and extends time-to-approval.
- Reimbursement fragmentation:Medicaid fee schedules vary by U.S. state, creating administrative complexity for multi-state therapy providers and platform operators.
Strategic Opportunities
- EMA pediatric investigation plan alignment:Early engagement with European regulatory pathways enables synchronized U.S.-EU label claims and accelerates market access in Germany, France, and the Netherlands.
- AI-augmented diagnostic workflow integration:Machine learning screening tools paired with standardized instruments such as ADOS-2 reduce specialist time burden and expand clinic throughput capacity.
- School-based direct contracting:Institutional procurement channels bypass individual insurance preauthorization friction and secure multi-year platform commitments.
Industry Challenges
- Behavioral therapist credentialing pipelines:University training program capacity constraints limit annual board-certified behavior analyst output despite escalating employer demand.
- Interoperability with electronic health record systems:Therapy outcome data standardization gaps complicate payer reporting requirements and value-based contract structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autism Spectrum Disorder Management Market |
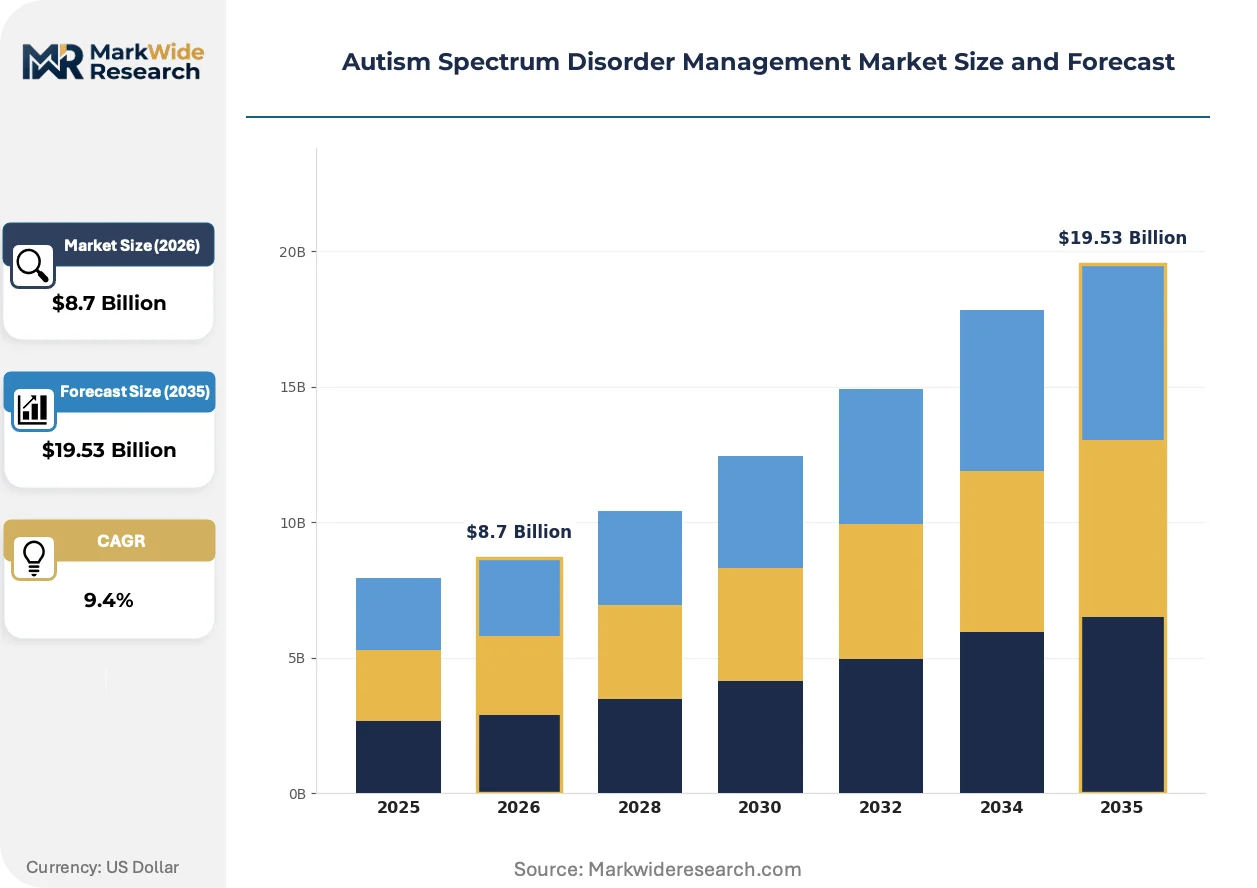
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Behavioral Therapy, Diagnostic Tools, Educational Resources Delivery Mode: In-Person, Telehealth, Mobile Applications, Workshops End User: Parents, Therapists, Schools, Healthcare Providers Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Eli Lilly and Company, AbbVie Inc., Johnson & Johnson, BlueSprig, H. Lundbeck A/S, Otsuka Pharmaceutical Co., Ltd., Pfizer Inc., Jazz Pharmaceuticals, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autism Spectrum Disorder Management Market Strategic Shifts
Digital therapeutic delivery and artificial intelligence integration are restructuring how autism services are accessed, reimbursed, and clinically validated across developed healthcare systems.
Virtual reality exposure therapy platforms are virtualizing social skills training for children with autism spectrum conditions. Pediatric clinics in the United States and Germany are piloting immersive environments for practicing peer interaction scenarios. This modality is virtualizing the traditional in-clinic role-play format and expanding session frequency beyond physical facility constraints.
REACH-aligned chemical safety assessments in Europe are extending pediatric neuropharmacology development timelines. The European Medicines Agency's pediatric investigation plans now require earlier submission of juvenile toxicology data. Formulation developers targeting irritability indications are restructuring phase sequencing to accommodate these documentation demands.
Parent-mediated intervention models are displacing clinic-exclusive delivery in early intervention programs. Self-directed digital curricula with remote specialist oversight are capturing share from center-based applied behavior analysis in the United States. State Medicaid programs in California and Texas are revising reimbursement codes to accommodate this hybrid format.
Autism Spectrum Disorder Management Market Segmentation
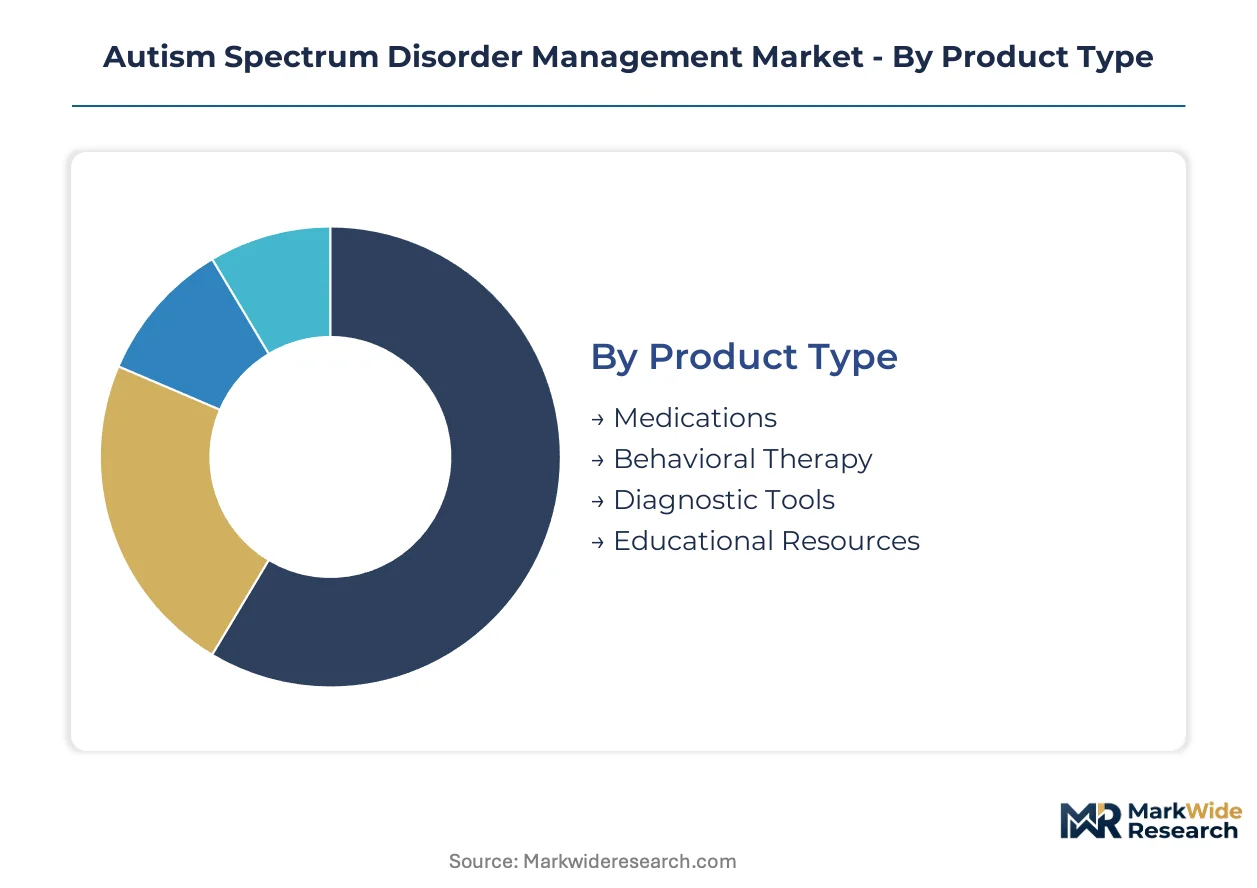
Autism spectrum disorder management segments diverge sharply by intervention intensity, reimbursement pathway, and regulatory classification. Each category reflects distinct stakeholder economics, from pharmaceutical development timelines to behavioral therapy credentialing requirements.
Product Type:
Use-case intensity spans acute symptom management through lifelong adaptive skill development.
- Medications:Psychotropic formulations target irritability, hyperactivity, and social withdrawal through dopaminergic and serotonergic modulation. FDA pediatric trial requirements extend development cycles, while Medicaid formularies in the United States drive volume concentration for approved agents.
- Behavioral Therapy:Applied behavior analysis and structured skill-building programs constitute the deepest margin pool through recurring session billing. State-level insurance parity mandates in the United States compress access barriers, though board-certified behavior analyst scarcity creates twelve-month waitlists in metropolitan markets.
- Diagnostic Tools:Standardized instruments including ADOS-2 and ADI-R anchor clinical classification protocols.
- Educational Resources:Curriculum adaptations and sensory accommodation materials serve individualized education program compliance.
The dominant share belongs to Behavioral Therapy, while Medications is closing the gap fastest through novel target exploration.
Delivery Mode:
Channel economics reshape margin capture through reimbursement code alignment and platform scalability.
- Telehealth:Asynchronous therapy platforms and remote parent coaching dissolve geographic barriers to specialist access. HIPAA-aligned infrastructure clarifications reduce liability exposure and accelerate payer contract negotiations across United States state Medicaid programs.
- In-Person:Center-based delivery retains premium reimbursement rates for intensive applied behavior analysis programs. Physical facility requirements limit expansion velocity in rural United States counties.
- Mobile Applications:Self-directed digital curricula with remote oversight capture early intervention share from traditional clinic models.
- Workshops:Group-format parent training and educator professional development serve institutional procurement channels.
Telehealth commands expanding share through reimbursement code revisions, while Mobile Applications is gaining ground fastest among parent-mediated intervention models.
End User:
Procurement authority concentrates with institutional payers and individual caregivers across distinct budget lines.
- Schools:Special education departments in the United States and Germany allocate dedicated line items for digital behavioral therapy platform licensing. Individualized education program mandates create recurring procurement cycles with multi-year commitment horizons.
- Parents:Direct-pay and insurance-reimbursed out-of-pocket spending drives demand for telehealth and mobile application solutions. State Medicaid fee schedule variations create administrative complexity for multi-state platform operators.
- Therapists:Independent practitioners and clinic networks prioritize credentialing-compatible platform tools and outcome documentation systems.
- Healthcare Providers:Pediatricians and developmental specialists coordinate referral pathways and medication management protocols.
Schools anchor institutional volume, while Parents is expanding most quickly through direct-to-consumer platform adoption.
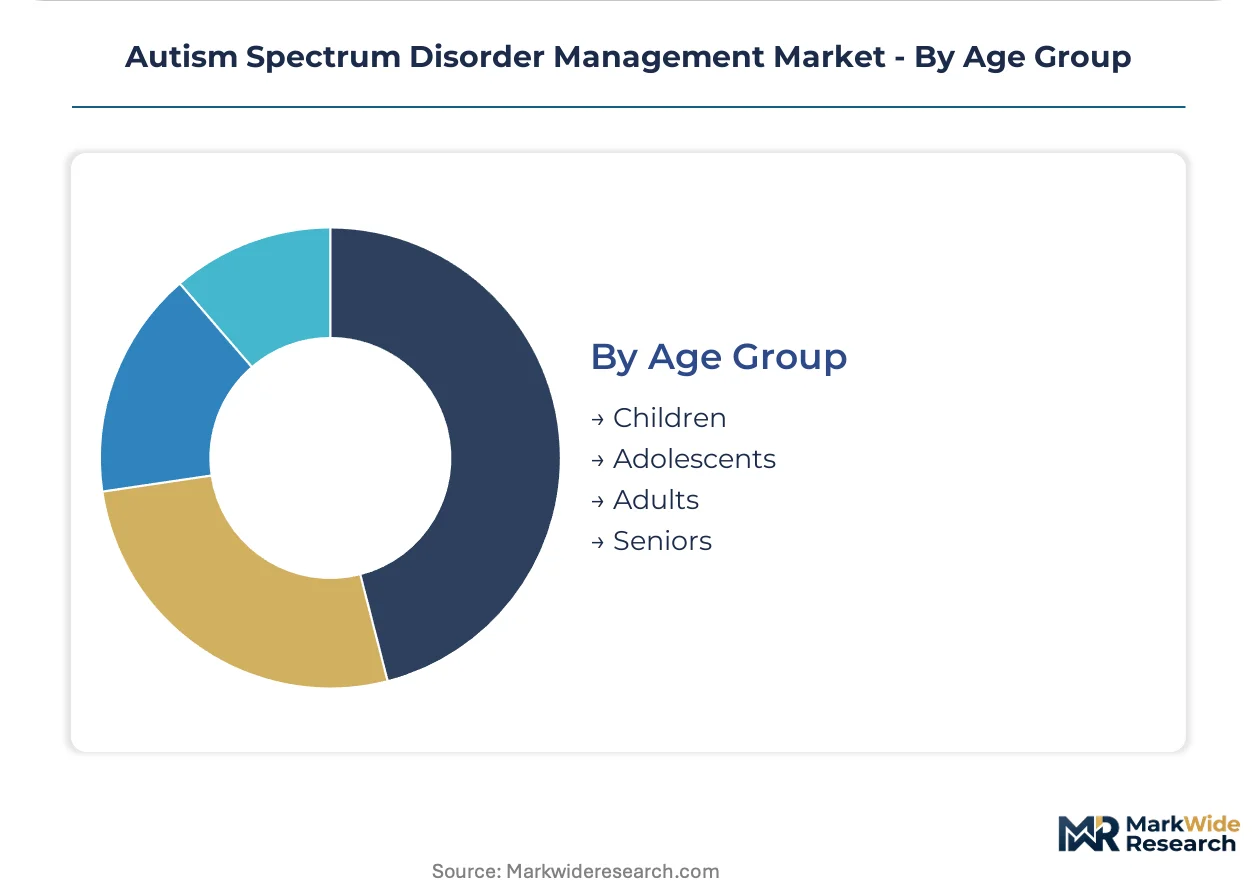
Age Group:
Developmental window urgency and intervention intensity vary across neuroplasticity phases.
- Children:Early intervention programs target ages two through five with highest per-capita service intensity. California and Texas Medicaid programs are revising reimbursement codes to accommodate hybrid parent-mediated formats.
- Adolescents:Transition planning and social skills training address vocational preparation and independent living competencies.
- Adults:Employment support and residential service coordination extend across lifespan management models.
- Seniors:Late-diagnosed cohorts and aging caregiver transitions constitute emerging service demand.
Children retains the deepest service penetration, while Adults is climbing the fastest as lifespan perspective restructures program design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service delivery corridors from the United States into Canada and Mexico reshape cross-border autism care procurement. Regulatory divergence between FDA pediatric pathways and Health Canada neurodevelopmental standards creates compliance complexity for platform operators.
United States
State-level insurance parity mandates and Medicaid fee schedule expansions drive applied behavior analysis utilization. FDA pediatric trial requirements for neurodevelopmental therapeutics extend pharmaceutical development timelines. California and Texas Medicaid programs are revising reimbursement codes to accommodate hybrid parent-mediated intervention formats.
Germany
Special education budget allocations and school-based digital therapy platform licensing anchor institutional demand. EMA pediatric investigation plans require earlier juvenile toxicology data submission for neuropharmacology developers. REACH-aligned chemical safety assessments in Baden-Württemberg extend formulation development timelines for irritability-targeting compounds.
United Kingdom
National Health Service autism diagnostic pathway backlogs and private telehealth adoption accelerate platform penetration. Care Quality Commission oversight of remote behavioral health delivery shapes platform liability frameworks. London and Southeast England clinic networks are piloting AI-augmented diagnostic workflows paired with ADOS-2 protocols.
Canada
Provincial autism funding programs and individualized funding model transitions expand family-directed service purchasing. Health Canada neurodevelopmental drug approval pathways diverge from FDA timelines, creating asynchronous market entry. Ontario's school district procurement channels are licensing digital behavioral therapy platforms for special education compliance.
France
HAS autism care pathway standardization and diagnostic center accreditation requirements concentrate service delivery. ANSM pediatric neuropharmacology vigilance protocols extend post-market surveillance obligations for approved agents. Île-de-France regional health agencies are contracting telehealth platforms to reduce diagnostic waitlist durations.
Autism Spectrum Disorder Management Market Competitive Environment
On the supply side, the industry is bifurcated between pharmaceutical developers pursuing neuropharmacology targets and behavioral service platforms scaling telehealth delivery. Large-cap pharmaceutical entities anchor the medications segment through psychiatric drug development legacies, while fragmented behavioral therapy networks compete on credentialing density and payer contract breadth. Strategic archetypes span integrated care conglomerates, pure-play digital therapeutic platforms, and specialty pharmaceutical developers. Competitive positioning hardens through M&A consolidation of regional therapy networks and strategic partnerships between AI diagnostic developers and established assessment instrument licensors.
Within the integrated pharmaceutical tier, Eli Lilly and Company, AbbVie Inc., and Johnson & Johnson occupy positions that exemplify divergent strategic orientations toward pediatric neurodevelopment. Eli Lilly represents legacy psychiatric drug development anchored in decades of CNS therapeutic experience. AbbVie exemplifies neurology pipeline specialization targeting social communication deficit mechanisms. Johnson & Johnson anchors its position through care network integration spanning pharmaceutical and behavioral intervention modalities.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| AbbVie Inc. |
| Johnson & Johnson |
| BlueSprig |
| H. Lundbeck A/S |
| Otsuka Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Jazz Pharmaceuticals |
| Roche |
| Others |
Value Chain & Pricing Dynamics
FDA pediatric trial requirement bottlenecks determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic distribution of manufacturing capacity for neuropharmacology developers. Supply chain shape for behavioral therapy platforms reflects state Medicaid reimbursement rate fragmentation and board-certified behavior analyst credentialing pipeline constraints.
Pricing Analysis
Technology-generation pricing gaps separate legacy in-clinic applied behavior analysis from asynchronous telehealth platforms and AI-augmented diagnostic workflows. The market operates on a subscription-SaaS-tiered model for digital therapeutic delivery, with price differentiation driven by HIPAA certification tier and after-sales specialist coaching intensity. Cost compression in the standard tier is intensifying because parent-mediated intervention models displace higher-margin center-based delivery. School district procurement represents the least price-sensitive buyer archetype due to individualized education program mandate compliance requirements, while direct-pay parents exhibit highest sensitivity to per-session billing rates.
Supply Chain Analysis
Extended payment terms from state Medicaid programs and supply-chain finance facilities for multi-state therapy platform operators shape working capital requirements across the value chain. Manufacturing concentration for psychotropic formulations centers on the United States, Ireland, and Switzerland, while digital therapeutic development draws from software engineering clusters in the United States, Germany, and Israel. Raw material dependencies include active pharmaceutical ingredients, cloud computing infrastructure, and standardized assessment instrument licensing. Single-source vulnerability exists for board-certified behavior analyst training program accreditation. Distribution runs through institutional procurement channels for schools and direct-to-consumer platforms for parent-mediated interventions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. State-level insurance parity mandates and FDA pediatric trial requirements create substantial barriers to competitive replication for established participants.
For Market Incumbents: Insulate market position by deepening vertical integration into AI-augmented diagnostic workflows to reduce specialist time burden and expand clinic throughput capacity. Acquire regional therapy networks in high-demand metropolitan areas where board-certified behavior analyst waitlists exceed twelve months, consolidating credentialing density against emerging pure-play telehealth platforms.
For New Entrants and Emerging Players: Establish a beachhead in adult lifespan management services, the fastest-climbing age segment as diagnostic awareness expands beyond childhood intervention windows. Target school-based direct contracting in Germany and Canada where institutional procurement channels bypass individual insurance preauthorization friction. Deploy hybrid parent-mediated intervention models with remote specialist oversight to capture share from traditional center-based applied behavior analysis.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated care conglomerates with pharmaceutical and behavioral intervention capabilities. Long-term viability across the projection horizon rests on synchronized U.S.-EU label claims and multi-state payer contract breadth. Acquisition target archetypes include AI diagnostic developers with established assessment instrument partnerships. The signal to watch is EMA pediatric investigation plan submission timing as an inflection indicator for European market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Diagnostic Workflow Integration | Machine learning screening tools paired with ADOS-2 protocols reduce specialist burden and expand throughput in London and Southeast England clinic networks. |
| School-Based Direct Contracting | Institutional procurement channels in Ontario and Baden-Württemberg secure multi-year platform commitments bypassing individual insurance preauthorization friction. |
| EMA Pediatric Investigation Plan Alignment | Early engagement with European regulatory pathways enables synchronized U.S.-EU label claims and accelerates market access in Germany, France, and the Netherlands. |
| Telehealth Platform HIPAA Infrastructure Investment | Clarified guidance on protected health information handling during remote autism assessments reduces liability exposure and accelerates payer contract negotiations. |
| Parent-Mediated Intervention Model Development | Self-directed digital curricula with remote specialist oversight capture early intervention share from center-based applied behavior analysis in California and Texas Medicaid programs. |
Study Parameters
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in documented regulatory and procurement practices. Interview participants included board-certified behavior analysts, digital therapeutic platform executives, state Medicaid formulary directors, school district special education administrators, and pediatric neuropharmacology regulatory affairs leads. Secondary sources comprised FDA pediatric trial filings, EMA pediatric investigation plan submissions, state-level insurance parity statute databases, and CMS Medicaid fee schedule variations. Bottom-up therapy session volume estimates and top-down pharmaceutical revenue triangulation were reconciled across data streams.
Calibration against historical adoption curves for telehealth behavioral health delivery and pharmaceutical approval timelines shaped the analytical framework. Segmentation dimensions modeled encompass intervention intensity, delivery mode, end-user procurement authority, and age group developmental window across the projection horizon. CAGRs were derived from therapy session growth rates and pharmaceutical pipeline progression assumptions. Forecast inputs included board-certified behavior analyst training program output projections and state Medicaid reimbursement code revision timelines.
Sensitivities concentrate around FDA digital health guidance evolution, state-level insurance parity mandate expansion velocity, and EMA REACH-aligned chemical safety assessment timeline extensions. Forecasts reflect assumptions regarding regulatory pathway stability and payer contract negotiation success rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Vertebral Radiculopathy Market