
 Porphyria Treatment Market | 2026-2036
Porphyria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Porphyria Treatment Market Outlook
Multi-source procurement of active pharmaceutical ingredients is realigning supply security for hemin and givosiran manufacturers. Recordati Rare Diseases leverages European distribution infrastructure to sustain orphan drug access across Mediterranean markets. Alnylam Pharmaceuticals anchors RNA interference therapy development through proprietary synthesis platforms. Mitsubishi Tanabe Pharma competes in acute porphyria management with established hospital formulary relationships in East Asia.
Porphyria treatment encompasses pharmacologic interventions targeting heme biosynthesis pathway defects, including intravenous hemin formulations that restore regulatory heme pools and subcutaneous RNAi therapies suppressing aminolevulinic acid synthase. These interventions serve to abort acute neurovisceral attacks and prevent recurrent episodes in hepatic porphyria subtypes. Givosiran dominates revenue contribution among product types due to its preventive mechanism and premium positioning, while intravenous administration routes retain volume leadership in acute care settings. Hospital end users concentrate the largest margin pool given emergency administration requirements and specialist monitoring protocols.
FDA orphan drug exclusivity provisions and EMA priority medicines frameworks shape clinical trial investment and reimbursement negotiations for porphyria developers. National health technology assessment bodies in Germany, France, and England determine market access timelines and pricing corridors for novel therapies. Stakeholders must monitor evolving RNAi manufacturing scale-up capabilities and hemin raw material sourcing resilience as patient identification campaigns expand treatable populations.
Market Dynamics
RNA interference manufacturing scale-up is compressing treatment timelines while hemin raw material sourcing concentrates among three API suppliers, forcing hospital procurement officers to negotiate multi-year supply agreements with built-in price adjustment clauses.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Extended market protection periods incentivize clinical trial investment for hepatic porphyria subtypes, accelerating novel therapy development timelines.
- Subcutaneous RNAi Administration:Home-based injection protocols reduce hospital bed utilization and expand treatable patient populations beyond specialist center catchment areas.
- German National Referral Networks:Coordinated specialist treatment centers streamline diagnosis-to-treatment pathways, compressing time-to-therapy for acute neurovisceral attacks.
Market Restraints
- Bovine Hemin Supply Concentration:Three API manufacturers control hemin raw material sourcing, creating vulnerability to livestock disease outbreaks and export restriction cascades.
- EMA Reimbursement Negotiation Timelines:Health technology assessment bodies in France, Germany, and England impose 18-24 month market access delays for novel RNAi therapies.
- Plasma-Derived Substitute Development:Recombinant heme biosynthesis research threatens long-term demand for intravenous hemin formulations in prophylactic indications.
Strategic Opportunities
- Brazil ANVISA Fast-Track Pathway:Emerging market regulatory acceleration creates first-mover positioning for manufacturers establishing local distribution partnerships.
- Pharmacogenomic Companion Diagnostics:ALAD and HMBS mutation profiling integration enables precision patient stratification and premium pricing justification.
- Direct-to-Patient Specialty Pharmacy Channels:Cold-chain RNAi distribution bypasses hospital formulary bottlenecks, capturing margin from specialty pharmacy networks.
Industry Challenges
- Rare Disease Clinical Trial Recruitment:Hepatic porphyria prevalence of 1-5 per 100,000 necessitates multi-country trial designs and extended enrollment periods.
- RNAi Manufacturing Facility Validation:GMP-compliant oligonucleotide synthesis requires $200M+ facility investments with 36-month construction-to-approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porphyria Treatment Market |
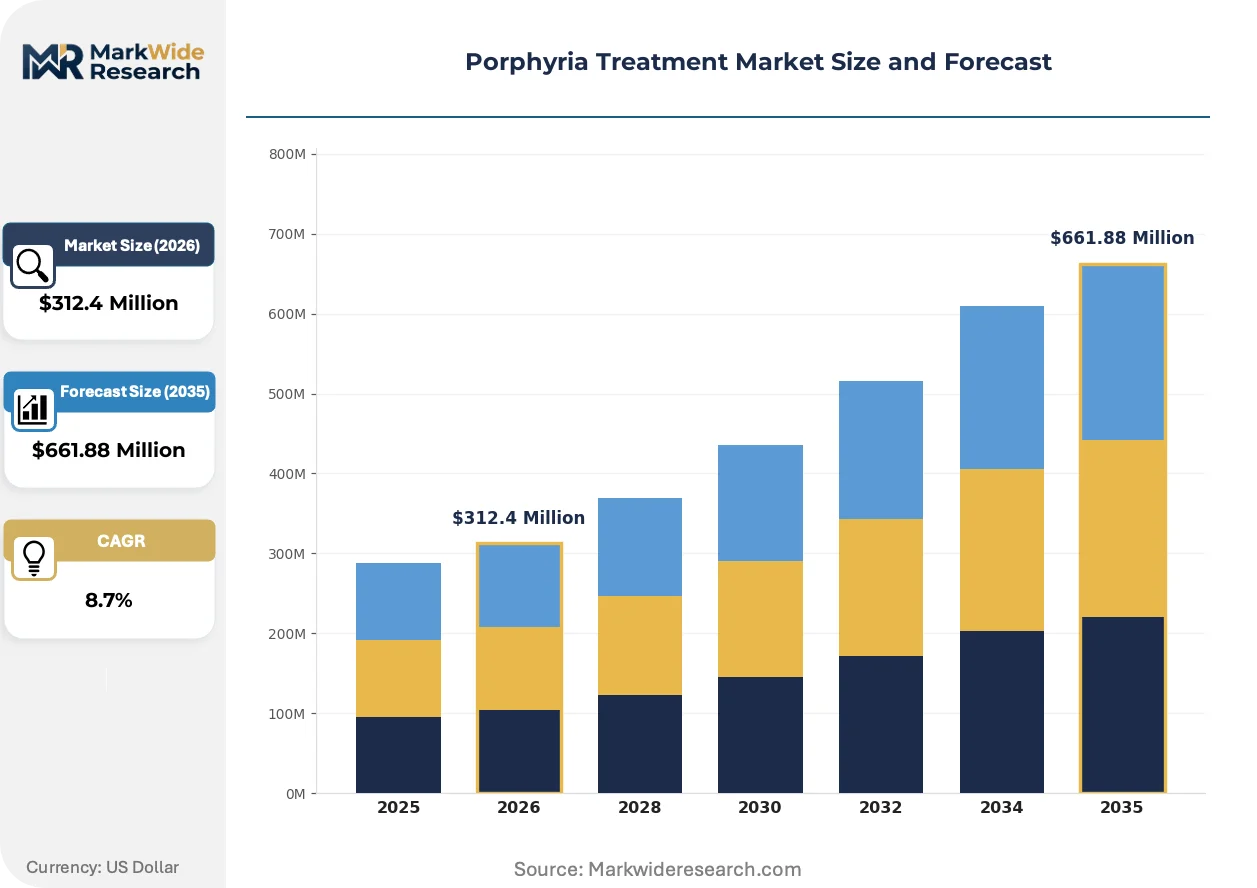
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemin, Panhematin, Givosiran, Others Administration Route: Intravenous, Oral, Subcutaneous, Others Indication: Acute Porphyria, Erythropoietic Porphyria, Cutaneous Porphyria, Others End User: Hospitals, Clinics, Homecare, Others |
| Companies Covered | Alnylam Pharmaceuticals, Recordati Rare Diseases, Teva Pharmaceutical Industries, Pfizer Inc., Sanofi, Mitsubishi Tanabe Pharma, BioMarin Pharmaceutical, H. Lundbeck A/S, Clinuv el Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porphyria Treatment Market Strategic Shifts
Patient identification campaigns and newborn screening expansion are reshaping addressable market calculations, while manufacturing technology advances compress production costs for complex biologics.
Subcutaneous RNA interference delivery systems are decentralizing acute porphyria management from emergency departments to outpatient settings. Home health nursing networks are adopting these technologies at accelerating rates in Germany and Japan. This shift is decentralizing hospital revenue capture and redistributing margin toward specialty pharmacy and home infusion providers.
EMA Priority Medicines designation frameworks are compressing regulatory review timelines for therapies addressing unmet hepatic porphyria needs. Manufacturers gain accelerated assessment pathways and enhanced scientific advice access. RNAi developers targeting aminolevulinic acid synthase suppression are prioritizing PRIME eligibility submissions to secure early reimbursement dialogues.
Hospital procurement officers are consolidating orphan drug purchasing through group purchasing organizations and national tender mechanisms. Single-source RNAi therapies face price transparency pressures as German hospital federations aggregate demand across state-level networks. This concentration is most visible in North Rhine-Westphalia and Bavaria, where centralized pharmacy committees negotiate multi-hospital contracts.
Porphyria Treatment Market Segmentation
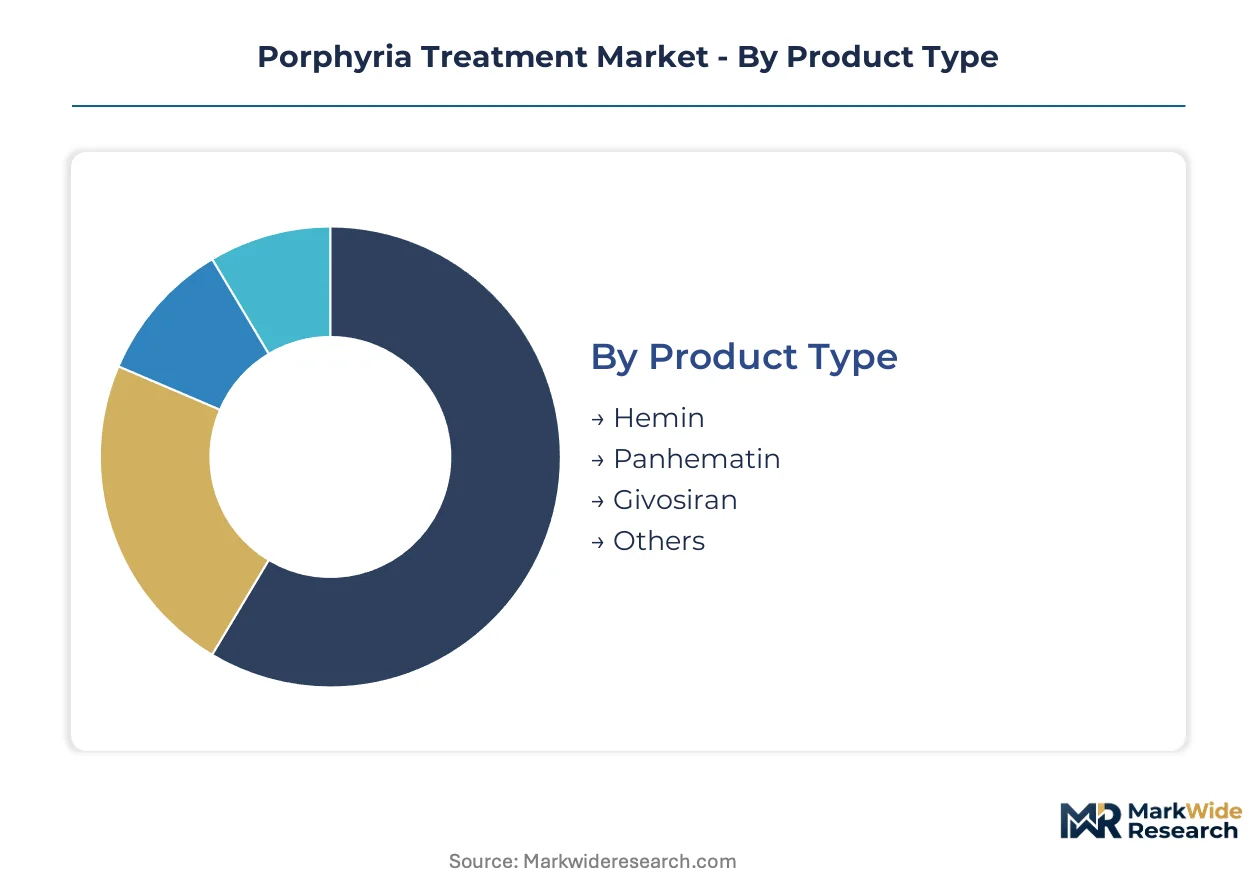
Porphyria treatment segmentation reveals how supply chain configuration shapes competitive positioning across therapeutic modalities. Product type and administration route categories concentrate margin capture, while indication and end user dimensions determine access pathways and reimbursement dynamics.
Product Type:
Supply concentration among API manufacturers for hemin derivatives creates procurement leverage disparities that favor integrated developers.
- Hemin:Intravenous formulations derived from processed bovine hemoglobin restore regulatory heme pools during acute neurovisceral attacks. Hospital procurement officers in the United States negotiate multi-year supply agreements with built-in price adjustment clauses due to livestock sourcing vulnerabilities.
- Givosiran:Subcutaneous RNA interference therapy suppresses aminolevulinic acid synthase production, preventing precursor accumulation in hepatic porphyria subtypes. German specialist treatment centers coordinate national referral networks to streamline patient identification and therapy initiation for this preventive mechanism.
- Panhematin:Lyophilized hemin formulation requiring reconstitution prior to intravenous administration, with established hospital formulary relationships in acute care settings.
- Others:Emerging gene therapy candidates and small-molecule ALA dehydratase modulators in preclinical and early clinical development stages.
Today's leader: Givosiran. Tomorrow's challenger: Hemin (if recombinant biosynthesis research succeeds).
Administration Route:
Cost tier stratification separates emergency inpatient interventions from outpatient maintenance protocols, redistributing margin across care settings.
- Intravenous:Hospital-based infusion of hemin formulations requires specialist monitoring during acute attacks, capturing the largest margin pool through emergency department billing codes and critical care protocols.
- Subcutaneous:Home-based RNAi injection protocols reduce hospital bed utilization and expand treatable populations beyond specialist center catchment areas in Japan and Germany.
- Oral:Limited current availability for porphyria-specific indications, with research focusing on heme arginate and porphyrin precursor absorption inhibitors.
- Others:Investigational depot formulations and implantable delivery systems in early development for prophylactic administration.
Intravenous administration anchors current revenue. Subcutaneous delivery gains share fastest as home health nursing networks expand.
Indication:
Application urgency varies dramatically across porphyria subtypes, with hepatic forms driving acute intervention demand versus chronic management for cutaneous variants.
- Acute Porphyria:Acute intermittent porphyria, variegate porphyria, and hereditary coproporphyria present with life-threatening neurovisceral attacks requiring immediate hemin infusion or RNAi prevention protocols.
- Cutaneous Porphyria:Porphyria cutanea tarda and erythropoietic protoporphyria manifest with photosensitivity and skin fragility, driving demand for photoprotective interventions and liver monitoring services.
- Erythropoietic Porphyria:Congenital erythropoietic porphyria and rare erythroid-specific enzyme defects require specialized hematology referral pathways and bone marrow transplant evaluation.
- Others:Dual porphyria presentations and mixed hepatoerythropoietic forms with overlapping clinical features complicating diagnosis and treatment selection.
Acute porphyria commands premium pricing. Cutaneous porphyria offers volume expansion as screening programs broaden detection.
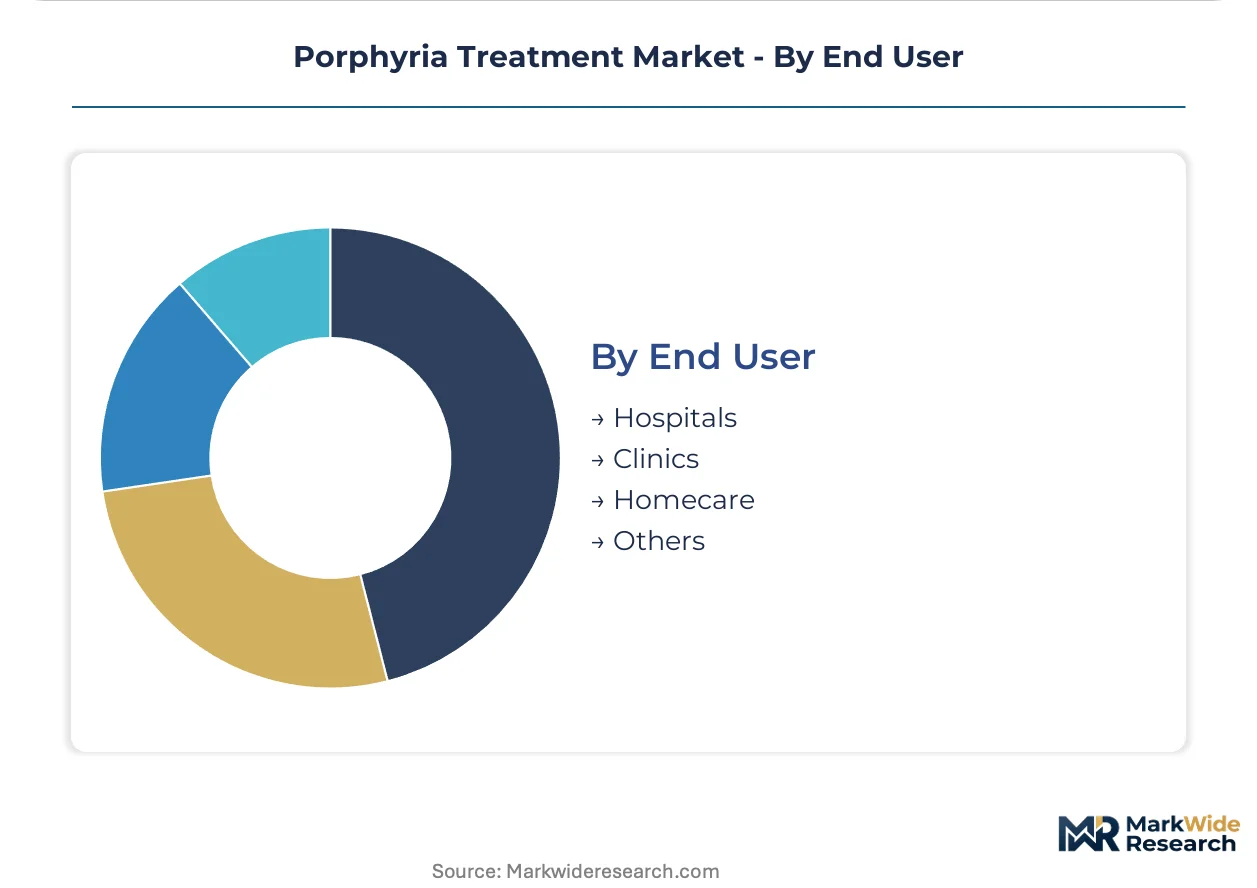
End User:
Customer type determines procurement channel complexity, with hospital concentration enabling group purchasing leverage versus fragmented homecare distribution.
- Hospitals:Tertiary care centers with dedicated porphyria specialist units coordinate emergency hemin stockpiling and RNAi therapy initiation, particularly in the United States, Germany, and Japan where national referral networks centralize complex case management.
- Homecare:Specialty pharmacy and home infusion providers capture margin from subcutaneous RNAi distribution, bypassing hospital formulary bottlenecks through direct-to-patient cold-chain logistics.
- Clinics:Outpatient specialist practices manage stable patients between acute episodes, with limited procedural revenue compared to hospital-based care.
- Others:Research institutions and compassionate use programs for investigational therapies outside commercial approval pathways.
Hospitals dominate current spend. Homecare providers represent the steepest expansion trajectory as administration decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as RNAi synthesis facility investments migrate toward jurisdictions offering streamlined GMP validation pathways and targeted rare disease tax incentives.
United States
FDA orphan drug exclusivity provisions accelerate clinical trial timelines for hepatic porphyria therapies, with seven-figure priority review vouchers compressing approval windows. The national referral network concentrates acute case management at tertiary centers in Boston, Baltimore, and San Francisco, where hospital procurement officers negotiate multi-year hemin supply agreements.
Germany
G-BA health technology assessment protocols determine reimbursement corridors for novel RNAi therapies, creating 18-24 month market access delays that manufacturers must navigate. Bavaria and North Rhine-Westphalia host centralized pharmacy committees aggregating demand across state-level hospital federations, driving price transparency pressures on single-source therapies.
Japan
PMDA Sakigake designation pathways compress regulatory review timelines for therapies addressing unmet hepatic porphyria needs, with priority consultation vouchers enabling early reimbursement dialogues. The Kanto region anchors specialist treatment center density, while Osaka-based hospital networks coordinate national referral pathways for acute neurovisceral attack management.
Switzerland
Swissmedic accelerated assessment frameworks attract RNAi developers seeking parallel European validation pathways, with Geneva and Basel hosting contract manufacturing organizations serving orphan drug sponsors. The country's bilateral recognition agreements with EMA streamline cross-border market access for therapies gaining Swiss approval.
United Kingdom
NICE single technology appraisal processes determine NHS England funding commitments for porphyria treatments, with highly specialized service specifications concentrating patient volumes at designated centers in London and Manchester. Post-Brexit regulatory divergence from EMA frameworks creates parallel submission requirements that extend market access timelines.
Porphyria Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue RNAi manufacturing scale-up and pharmacogenomic companion diagnostic integration. The market structure concentrates around three archetypes: integrated rare disease specialists with European distribution infrastructure, RNA interference platform developers with proprietary synthesis capabilities, and diversified pharmaceutical manufacturers leveraging hospital formulary relationships. Competitive moves center on multi-year API supply agreements with price adjustment clauses and direct-to-patient specialty pharmacy channel development.
Among RNA interference platform developers, Alnylam Pharmaceuticals anchors the preventive therapy segment through subcutaneous givosiran distribution. Recordati Rare Diseases exemplifies the rare disease specialist archetype, leveraging Mediterranean market access infrastructure. Mitsubishi Tanabe Pharma occupies a position within the East Asian hospital formulary tier, coordinating acute porphyria management protocols.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Recordati Rare Diseases |
| Teva Pharmaceutical Industries |
| Pfizer Inc. |
| Sanofi |
| Mitsubishi Tanabe Pharma |
| BioMarin Pharmaceutical |
| H. Lundbeck A/S |
| Clinuvel Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
German hospital federation purchasing consolidation is forcing API manufacturers to accept multi-year contracts with price adjustment clauses, compressing margins for hemin suppliers while RNAi developers capture premium positioning through single-source status.
Pricing Analysis
Input-cost pass-through from bovine hemoglobin sourcing volatility shapes hemin formulation pricing, with livestock disease outbreaks triggering automatic escalation clauses in hospital supply agreements. Three-tier pricing structure across premium RNAi preventive therapies, standard intravenous hemin formulations, and economy-tier supportive care separates givosiran from Panhematin from generic analgesic protocols. Pricing pressure stems from recombinant heme biosynthesis research threatening long-term hemin demand. Hospital procurement officers exhibit highest price sensitivity, while specialty pharmacy channels for subcutaneous RNAi demonstrate inelastic demand.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA Sakigake pathway are reshaping API sourcing toward local oligonucleotide synthesis partnerships, displacing pure import dependency for RNAi therapies. Hemin raw material sourcing concentrates in the United States, Argentina, and Ireland, drawing from bovine hemoglobin processing facilities tethered to livestock supply chains. Givosiran manufacturing rests on proprietary siRNA synthesis platforms and specialized cold-chain distribution infrastructure. Single-source vulnerability permeates the hemin API tier, where three manufacturers control global supply. Distribution runs through hospital pharmacy committees in acute care settings and specialty pharmacy networks for home-based RNAi administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The porphyria treatment market represents a late-cycle quality story where patient identification campaigns and newborn screening expansion are shifting demand toward precision-matched preventive therapies with premium reimbursement profiles.
For Market Incumbents: Extend formulary lock-in through multi-year hemin supply agreements with built-in price adjustment clauses before recombinant substitutes reach clinical validation. Deepen backward integration into bovine hemoglobin sourcing to defend against livestock disease disruption. Secure EMA Priority Medicines designation for pipeline RNAi candidates to compress reimbursement negotiation timelines.
For New Entrants and Emerging Players: The pricing gap between premium givosiran subscriptions and economy-tier supportive care creates white-space opportunity for mid-market prophylactic formulations. Target Brazil's ANVISA fast-track pathway for first-mover positioning in Latin American referral networks. Pursue pharmacogenomic companion diagnostic integration to enable precision patient stratification and justify premium positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with RNAi platform developers possessing proprietary synthesis capabilities and established specialty pharmacy distribution relationships. Five-to-ten year viability hinges on manufacturing scale-up execution and reimbursement corridor expansion. Watch for inflection signals in EMA health technology assessment body pricing decisions for novel hepatic porphyria therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | RNAi oligonucleotide synthesis facility investments exceeding $200M compress production costs and secure supply. |
| Regulatory Approval Pathway | EMA Priority Medicines designation accelerates assessment timelines and enables early reimbursement dialogues. |
| Long-term Supply Agreement | Multi-year hemin contracts with automatic price adjustment clauses protect hospital procurement from livestock volatility. |
| Pipeline Diversification | Gene therapy candidates targeting erythropoietic porphyria subtypes expand addressable populations beyond hepatic forms. |
| Direct-to-Patient Channel | Specialty pharmacy cold-chain distribution bypasses hospital formulary bottlenecks and captures margin from homecare expansion. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded the qualitative assessment, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary validation drew from SEC 10-K disclosures, hospital procurement databases, and national health technology assessment body publications. Bottom-up patient population modeling and top-down revenue triangulation converged on segment-level estimates.
Segmentation outputs across product type, administration route, indication, and end user dimensions informed the analytical framework over the projection horizon. CAGRs were derived from patient identification campaign expansion rates, reimbursement corridor negotiations, and manufacturing capacity buildout timelines. RNAi synthesis facility commissioning schedules and hemin API supplier validation cycles served as critical forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for recombinant heme biosynthesis would alter the outlook for intravenous hemin demand. Forecasts reflect assumptions regarding regulatory approval timelines, reimbursement negotiation outcomes, and supply chain resilience to livestock disease events. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market