
 Neuromuscular Disorders Treatment Market | 2026-2036
Neuromuscular Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neuromuscular Disorders Treatment Market Foresight
Outcome-based reimbursement for chronic neuromuscular management is realigning how pharmaceutical value gets captured across the patient journey. Biogen Inc. leverages its spinal muscular atrophy franchise to sustain recurring revenue from long-term therapy administration. Sarepta Therapeutics Inc. specializes in exon-skipping platforms for Duchenne muscular dystrophy, anchoring its pipeline to rare disease exclusivity. Pfizer Inc. competes through manufacturing scale that controls distribution costs for injectable biologics.
Neuromuscular disorders treatment encompasses pharmacological, biological, and device-based interventions targeting peripheral nerve, neuromuscular junction, and skeletal muscle pathologies, with gene replacement therapies requiring cold-chain logistics and specialized infusion centers. The primary purpose is to slow disease progression, preserve motor function, and reduce hospitalization frequency in degenerative conditions. Medications command the largest value share due to orphan drug pricing and chronic administration requirements, while infusion delivery modes are expanding fastest as monoclonal antibodies and enzyme replacement therapies displace oral small molecules. Hospitals remain the dominant end-user channel, though home care is gaining structural traction where subcutaneous formulations permit self-administration.
The FDA's accelerated approval and breakthrough therapy designations shape clinical trial investment and pre-market revenue expectations for developers. EMA's orphan drug framework and the EU's cross-border health technology assessment coordination influence parallel market access strategies. Stakeholders must monitor how CMS gene therapy payment models and state Medicaid carve-outs for million-dollar single-administration drugs reshape site-of-care economics and manufacturer contracting behavior.
Market Dynamics
Gene therapy reimbursement mechanics are compressing traditional pharmaceutical revenue cycles as payers demand outcomes-based contracts for single-administration treatments. Hospital networks must restructure capital allocation around infusion center buildouts and cold-chain infrastructure.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation shortens pre-market timelines for rare disease candidates. Developers gain earlier revenue recognition and reduced clinical trial costs.
- Exon-Skipping Platforms:Antisense oligonucleotide technology enables mutation-specific Duchenne muscular dystrophy interventions. Precision targeting expands addressable patient populations beyond one-size-fits-all biologics.
- Specialized Infusion Networks:United States hospital systems are constructing dedicated neuromuscular care units. Site-of-care expansion reduces patient travel burden and captures long-term therapy administration revenue.
Market Restraints
- Plasmid DNA Supply Concentration:Contract manufacturing organizations cluster raw material production in North America and Europe. Viral vector scarcity creates bottlenecks for adeno-associated virus-based gene therapies.
- Reimbursement Complexity:State Medicaid carve-outs for million-dollar single-administration drugs create administrative friction. Payer prior authorization requirements delay therapy initiation.
- Biologics Manufacturing Scale:Monoclonal antibody production requires stainless-steel bioreactor infrastructure with 18-24 month lead times. Capacity constraints limit batch output for chronic enzyme replacement therapies.
Strategic Opportunities
- Subcutaneous Formulation Expansion:Self-administration capability shifts site-of-care from hospital infusion centers to home care. Patient preference drives demand for needle-based delivery systems over intravenous lines.
- EMA Orphan Drug Exclusivity:Ten-year market protection in the European Union rewards rare disease pipeline investment. Parallel US-EU filings maximize regulatory efficiency.
- Artificial Intelligence-Enabled Patient Identification:Machine learning algorithms analyze electronic health records to flag undiagnosed spinal muscular atrophy cases. Earlier detection expands treatable populations.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Cell culture specialists and viral vector purification engineers command premium compensation. Workforce gaps delay facility commissioning and batch release timelines.
- Cold-Chain Logistics Integration:Ultra-low temperature storage requirements for adeno-associated virus vectors demand specialized third-party logistics partnerships. Temperature excursion risks threaten product integrity during distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuromuscular Disorders Treatment Market |
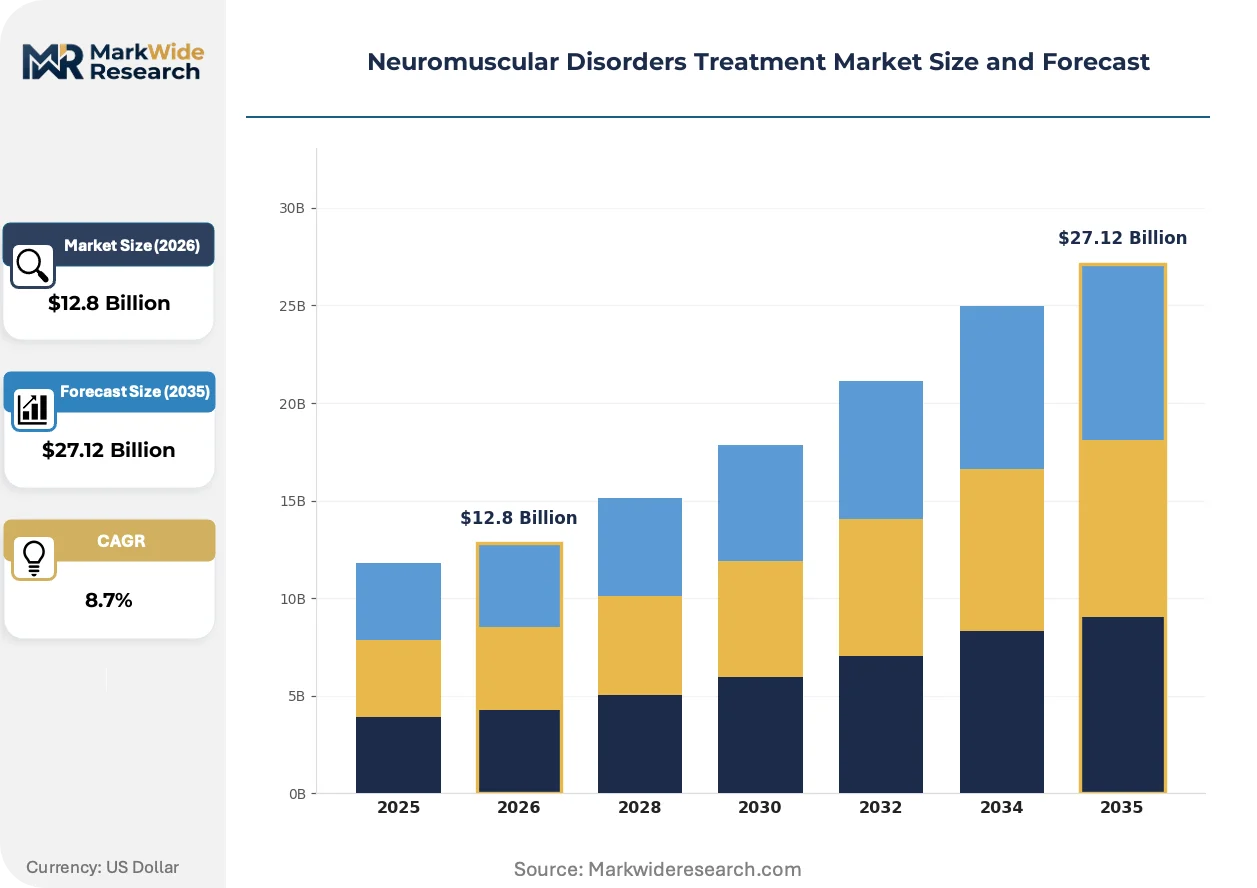
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Devices, Supplements Delivery Mode: Oral, Injection, Infusion, Inhalation End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Indication: Amyotrophic Lateral Sclerosis, Myasthenia Gravis, Muscular Dystrophy, Neuropathy |
| Companies Covered | Biogen Inc., Sarepta Therapeutics Inc., Pfizer Inc., Merck & Co. Inc., AstraZeneca Plc, Novartis AG, F. Hoffmann-La Roche Ltd., argenx SE, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuromuscular Disorders Treatment Market Shifts & Advancements
Antisense oligonucleotide chemistry advances are enabling mutation-specific interventions that bypass defective gene sequences entirely. Regulatory science and manufacturing technology are converging to compress development-to-commercialization timelines.
Next-generation exon-skipping chemistries with enhanced tissue penetration are electrifying Duchenne muscular dystrophy treatment paradigms. Sarepta Therapeutics and academic medical centers in the United States are advancing phosphorodiamidate morpholino oligomer formulations with improved skeletal muscle uptake. These molecular architectures are compressing the therapeutic window and enabling less frequent dosing schedules.
The FDA's breakthrough therapy designation is restructuring clinical investment priorities for rare neuromuscular indications. Sponsors gain rolling review privileges and intensive agency guidance that reduces regulatory uncertainty. Gene replacement therapy developers in the United States are prioritizing breakthrough-eligible candidates to secure earlier revenue recognition and favorable payer positioning.
Patient advocacy organizations are reshaping trial recruitment and endpoints selection through direct engagement with sponsors and regulators. Duchenne and spinal muscular atrophy foundations in the United States demand patient-reported outcome measures and functional mobility endpoints beyond biomarker surrogates. This stakeholder pressure is forcing protocol redesigns that accelerate regulatory submissions and expand label claims.
Neuromuscular Disorders Treatment Market Segmentation
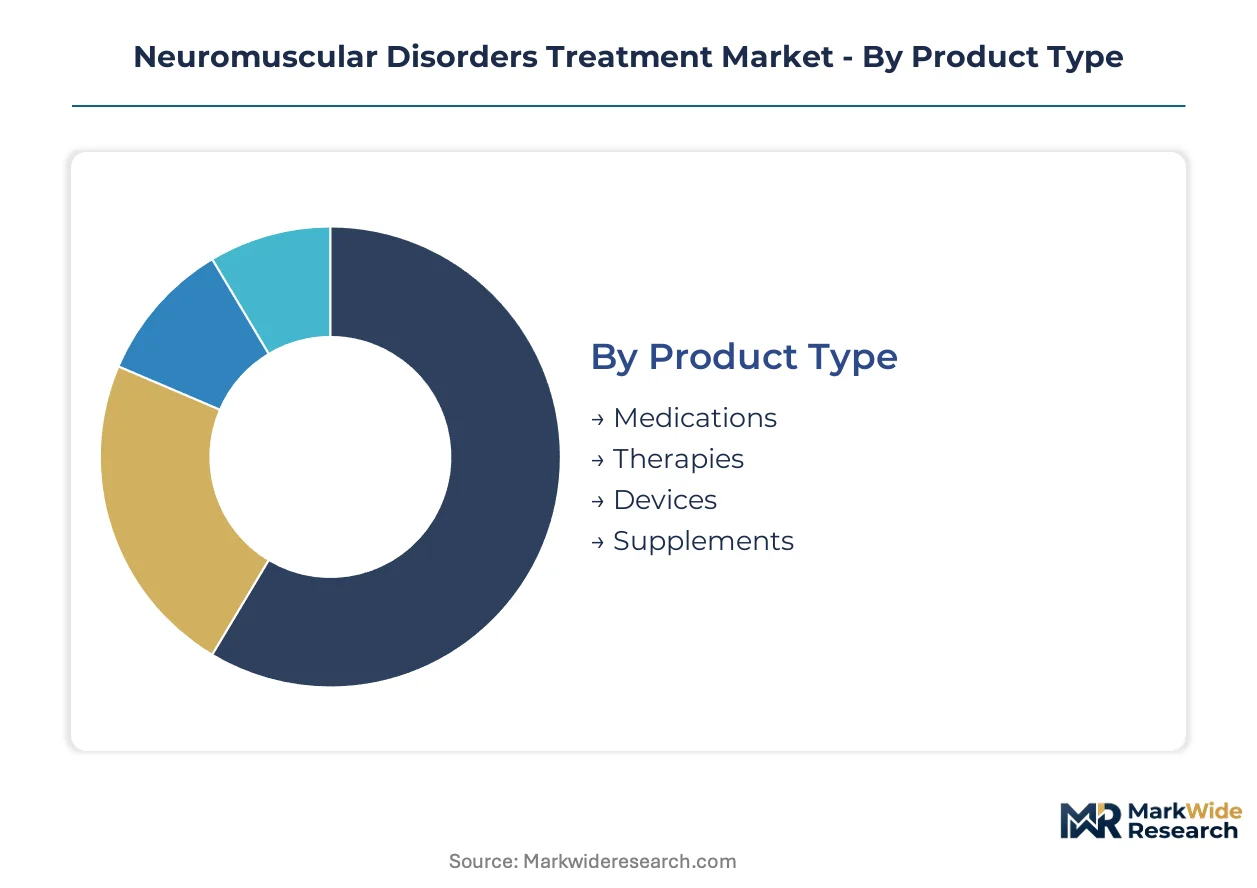
Neuromuscular disorders treatment demands precise patient stratification to match therapeutic modality with disease trajectory and care setting. Product-specific reimbursement pathways and site-of-care economics create divergent value capture opportunities across segment boundaries.
Product Type:
Upgrade cycles in neuromuscular care accelerate as gene therapies displace chronic maintenance regimens and next-generation antisense platforms replace first-generation small molecules.
- Medications:Small-molecule and biologic formulations targeting acetylcholinesterase inhibition, immunosuppression, or metabolic correction dominate prescription volume. United States hospital formularies prioritize FDA-approved orphan drugs with breakthrough therapy designation, driving concentration in academic medical centers with specialized neuromuscular units.
- Therapies:Gene replacement and exon-skipping interventions require single or episodic administration with curative intent. Cold-chain logistics and infusion center infrastructure constrain site selection, concentrating demand in tertiary care networks with viral vector handling capability.
- Devices:Ventilatory support, mobility assistance, and neuromuscular electrical stimulation equipment extend functional independence. Home care distributors capture recurring revenue from maintenance contracts and consumable replacement schedules.
- Supplements:Coenzyme Q10, creatine monohydrate, and amino acid formulations target mitochondrial myopathies and metabolic deficiencies. Direct-to-consumer channels and specialty pharmacy networks split distribution based on prescriber involvement requirements.
Volume placements concentrate in Medications; the faster expansion belongs to Therapies.
Delivery Mode:
Cost tier differentiation separates hospital-based administration from self-managed care, with reimbursement rates and patient out-of-pocket burden determining channel selection.
- Oral:Tablet and capsule formulations of pyridostigmine, corticosteroids, and metabolic cofactors enable chronic self-administration. Medicare Part D and commercial pharmacy benefit managers negotiate formulary placement based on generic substitution potential.
- Injection:Subcutaneous monoclonal antibodies and enzyme replacement therapies shift administration from infusion centers to home settings. Patient preference for needle-based devices over intravenous lines accelerates formulation development toward subcutaneous alternatives.
- Infusion:Intravenous gene therapies and immunoglobulins require specialized nursing supervision and adverse event monitoring. Hospital outpatient departments capture facility fees that home infusion cannot replicate for high-complexity biologics.
- Inhalation:Nebulized therapies for respiratory muscle weakness in ALS and muscular dystrophy address declining forced vital capacity. Pulmonary function testing requirements tie prescribing to specialized neuromuscular clinics with respiratory therapy integration.
Infusion captures the highest per-dose revenue; subcutaneous Injection gains share fastest as manufacturers prioritize patient-administered alternatives.
End User:
Customer type segmentation reflects divergent capital intensity and reimbursement mechanics across institutional and ambulatory settings.
- Hospitals:Academic medical centers and children's hospitals anchor complex care with multidisciplinary neuromuscular clinics. Gene therapy administration and clinical trial enrollment concentrate where institutional review boards and viral vector handling protocols are established.
- Clinics:Private neurology practices and community infusion centers manage chronic maintenance therapies. Prior authorization specialists and patient assistance program navigation determine operational viability for high-cost biologic administration.
- Home Care:Skilled nursing and durable medical equipment suppliers extend care into residential settings. Subcutaneous formulation availability and remote patient monitoring technology expand serviceable indications beyond traditional institutional boundaries.
- Rehabilitation Centers:Inpatient and outpatient physical therapy facilities focus on functional preservation and adaptive equipment training. Medicare prospective payment systems and commercial case rate contracts shape length-of-stay and intensity decisions.
Hospital networks retain the highest-acuity cases; Home Care climbs the fastest as subcutaneous delivery modes and remote monitoring reduce site-of-care requirements.
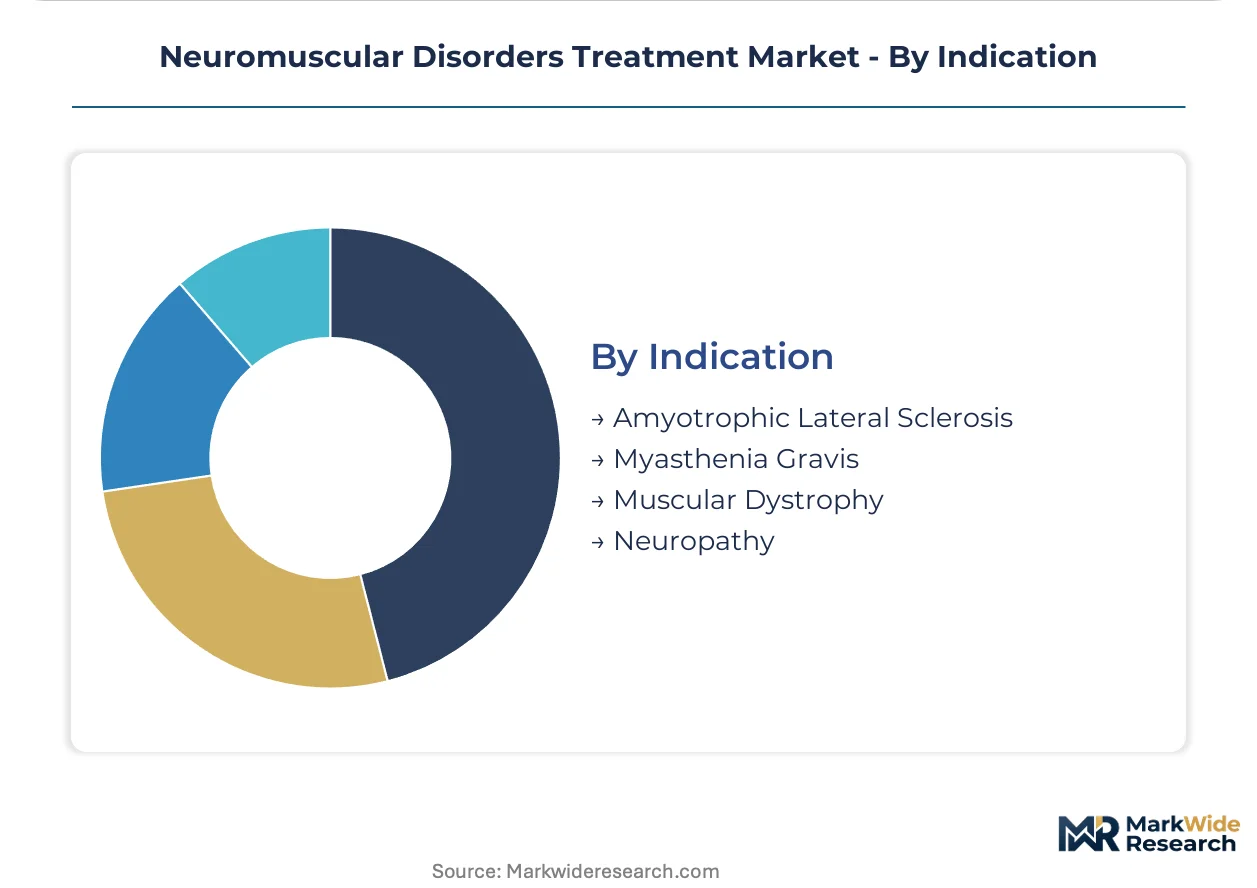
Indication:
Disease-specific prevalence and approved therapeutic options create distinct market development stages across neuromuscular conditions.
- Amyotrophic Lateral Sclerosis:Progressive motor neuron degeneration with limited disease-modifying options beyond riluzole and edaravone. FDA fast track and priority review designations attract development investment for antisense and gene silencing approaches targeting SOD1 and C9orf72 mutations.
- Myasthenia Gravis:Autoimmune neuromuscular junction disorder with established acetylcholinesterase inhibitor and immunosuppressive standards of care. FcRn antagonists and complement inhibitors are expanding the biologic-eligible population beyond refractory cases.
- Muscular Dystrophy:Heterogeneous genetic myopathies spanning Duchenne, Becker, and limb-girdle subtypes. Exon-skipping platforms and gene replacement programs target mutation-specific subpopulations with orphan drug exclusivity incentives.
- Neuropathy:Peripheral nerve disorders including Charcot-Marie-Tooth disease and chronic inflammatory demyelinating polyneuropathy. Intravenous immunoglobulin and subcutaneous immunoglobulin maintenance regimens generate chronic revenue streams with dosing interval optimization.
Muscular Dystrophy commands the most pipeline investment; Myasthenia Gravis is expanding most quickly as FcRn-targeted biologics broaden the addressable patient base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing concentrates in the United States and Switzerland while patient demand spreads across developed economies with established rare disease reimbursement frameworks. Consumption patterns diverge sharply between markets with million-dollar single-administration drug coverage and those reliant on chronic maintenance regimens. Regulatory pathway efficiency and payer infrastructure determine where developers prioritize commercial launches.
United States
FDA breakthrough therapy designations and CMS gene therapy payment models attract developers seeking accelerated revenue recognition. The Medicare Accelerated and Advance Payment Program supports hospital cash flow for high-cost biologic administration. Boston and San Francisco anchor the nation's gene therapy clinical trial density with specialized neuromuscular care units at academic medical centers.
Germany
EMA centralized marketing authorization and Germany's statutory health insurance system create predictable access for orphan drugs. The country's national pharmaceutical regulator enforces GMP standards for viral vector manufacturing that supply continental European demand. Munich and Heidelberg concentrate contract development and manufacturing organizations serving the EU gene therapy pipeline.
Japan
PMDA's sakigake designation system compresses review timelines for rare disease therapies targeting pediatric populations. METI's healthcare industrial strategy prioritizes domestic biologics manufacturing capacity to reduce import dependence. The Kanto region around Tokyo hosts the majority of clinical trial sites for spinal muscular atrophy and Duchenne muscular dystrophy interventions.
Switzerland
Swissmedic's alignment with EMA procedures enables parallel EU-Swiss filings for gene replacement therapies. The country's pharmaceutical cluster leverages legacy biologics expertise to expand into viral vector production. Basel and Zurich house manufacturing facilities that supply cold-chain dependent therapies across European hospital networks.
United Kingdom
NICE technology appraisals and NHS England's specialized commissioning framework determine reimbursement for million-pound single-administration treatments. The MHRA's post-Brexit regulatory autonomy permits tailored approval pathways for innovative modalities. London and Cambridge concentrate early-phase clinical research with academic medical center partnerships.
Neuromuscular Disorders Treatment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the neuromuscular disorders treatment landscape. Integrated biopharmaceutical companies with captive manufacturing capacity vie with development-stage firms outsourcing viral vector production to contract manufacturing organizations. Three archetypes dominate: gene therapy platform specialists, antisense oligonucleotide developers, and diversified biologics manufacturers with orphan drug franchises. Competitive moves center on manufacturing scale investments and outcomes-based payer contracting to secure market access for high-cost therapies.
Within the gene therapy platform tier, Biogen Inc. and Sarepta Therapeutics Inc. occupy positions defined by rare disease exclusivity and specialized infusion network partnerships. Pfizer Inc. represents the diversified biologics archetype with manufacturing scale advantages for injectable therapies. These three entities exemplify divergent strategic postures: platform depth versus therapeutic breadth versus production economics.
| Leading Market Players |
|---|
| Biogen Inc. |
| Sarepta Therapeutics Inc. |
| Pfizer Inc. |
| Merck & Co. Inc. |
| AstraZeneca Plc |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| argenx SE |
| AbbVie Inc. |
| Others |
Supply & Pricing Matrix
Payer consolidation around outcomes-based contracts for single-administration gene therapies is forcing manufacturers to restructure revenue recognition models and absorb more performance risk, which concentrates pricing power among developers with established viral vector manufacturing capabilities and cold-chain infrastructure.
Pricing Analysis
Price erosion across chronic maintenance therapies traces to biosimilar entry and formulary exclusion pressures from United States pharmacy benefit managers. Pricing stratifies across premium gene replacement interventions, standard biologic maintenance regimens, and economy small-molecule generics. Cost-down pressure on enzyme replacement therapies accelerates because Medicare Part D rebate reforms compress net realized prices. Academic medical centers with dedicated neuromuscular units exhibit lowest price sensitivity due to institutional prestige and trial enrollment incentives; community infusion centers face highest sensitivity from thin operating margins.
Supply Chain Analysis
Domestic-content mandates in the United States and European Union are reshaping sourcing for plasmid DNA and viral vector production, pressuring developers to qualify regional contract manufacturing organizations. Manufacturing gravity centers on the United States, Switzerland, and Germany for GMP viral vector facilities; plasmid DNA feeds from North American and European contract manufacturing organizations. Cold-chain logistics for adeno-associated virus vectors rests on specialized third-party partnerships with ultra-low temperature capabilities. Single-source vulnerability concentrates in plasmid DNA suppliers with limited qualified alternatives. Distribution runs through hospital outpatient departments and specialty pharmacy networks with temperature-controlled handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy reimbursement complexity and manufacturing capital intensity are driving consolidation, with smaller developers facing insurmountable barriers to commercial infrastructure buildout.
For Market Incumbents: Deploy manufacturing scale investments in viral vector capacity to capture contract manufacturing revenue from pipeline-stage competitors. Secure preferred site-of-care partnerships with academic medical centers building dedicated neuromuscular units to lock in administration volume. Backward integration into plasmid DNA production reduces exposure to contract manufacturing organization bottlenecks and supply concentration risk.
For New Entrants and Emerging Players: Subcutaneous formulation platforms offer a technology-first wedge to bypass hospital infusion center dependencies and capture home care channel growth. Target the chronic maintenance segment with biosimilar or improved-delivery alternatives to established enzyme replacement therapies, where payer price sensitivity creates entry openings. Pursue licensing partnerships with academic medical centers for patient identification algorithms that accelerate diagnosis and expand treatable populations.
For Investors and Strategic Acquirers: The window for entry favors developers with late-stage gene therapy assets and established regulatory relationships over early-discovery platforms. Long-term viability hinges on manufacturing asset ownership rather than pure research capability. Watch FDA breakthrough therapy designation grants as inflection indicators for acquisition timing and valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector facility investments in Basel and Boston capture contract manufacturing demand from pipeline-stage developers. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines and secures favorable payer positioning for rare disease candidates. |
| Pipeline Diversification | Exon-skipping platform expansion across Duchenne muscular dystrophy mutation subtypes extends orphan drug exclusivity horizons. |
| Hospital System Partnership | Preferred site-of-care agreements with academic medical centers lock in gene therapy administration volume and trial enrollment. |
| Reimbursement Strategy | Outcomes-based contracts with CMS and state Medicaid programs address payer resistance to million-dollar single-administration therapies. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from CMS Medicare data, GPO contracts, and SEC 10-K disclosures. Bottom-up patient population estimates and top-down revenue triangulation anchored market sizing.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment modality, delivery mode, site of care, and regional regulatory cluster. CAGRs were derived from epidemiological trend analysis, therapy penetration assumptions, and pricing trajectory assessments. Forecast inputs incorporated gene therapy launch sequencing and exon-skipping platform expansion timelines.
Several conditions sit outside the modeled scope, including regulatory approval delays, manufacturing facility commissioning setbacks, and payer coverage reversals for high-cost therapies. Forecasts reflect documented assumptions about patient identification rates and therapy persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market