
 Nephroblastoma Therapeutics Market | 2026-2036
Nephroblastoma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Nephroblastoma Therapeutics Market Foresight
Combination therapy bundling is restructuring how pediatric oncologists select nephroblastoma protocols, with multi-agent regimens increasingly replacing single-drug approaches. Bristol Myers Squibb leverages its immuno-oncology portfolio to compete in combination trial design. Pfizer anchors its position through sustained investment in pediatric oncology infrastructure. Merck & Co. differentiates via checkpoint inhibitor research directed at pediatric renal malignancies.
Nephroblastoma therapeutics comprise pharmaceutical and biologic interventions targeting Wilms tumor, a pediatric renal malignancy characterized by mutations in WT1, CTNNB1, or WTX genes, with treatment protocols typically spanning vincristine, dactinomycin, and doxorubicin combinations administered across risk-stratified regimens. Chemotherapy dominates current revenue pools as the backbone of first-line protocols, while immunotherapy represents the fastest-expanding segment as CAR-T and checkpoint inhibitor trials advance through pediatric oncology networks. Targeted therapy occupies a narrower but higher-margin position where druggable mutations permit precision intervention.
FDA pediatric study requirements under the Pediatric Research Equity Act shape trial enrollment mandates, while EMA's Paediatric Regulation drives parallel development obligations across European markets. The WHO Essential Medicines List inclusion of core nephroblastoma agents influences procurement patterns in low-resource settings. Stakeholders must monitor biomarker-driven trial readouts to anticipate which administration routes and treatment stages will shift toward precision protocols versus standard chemotherapy backbones.
Market Dynamics
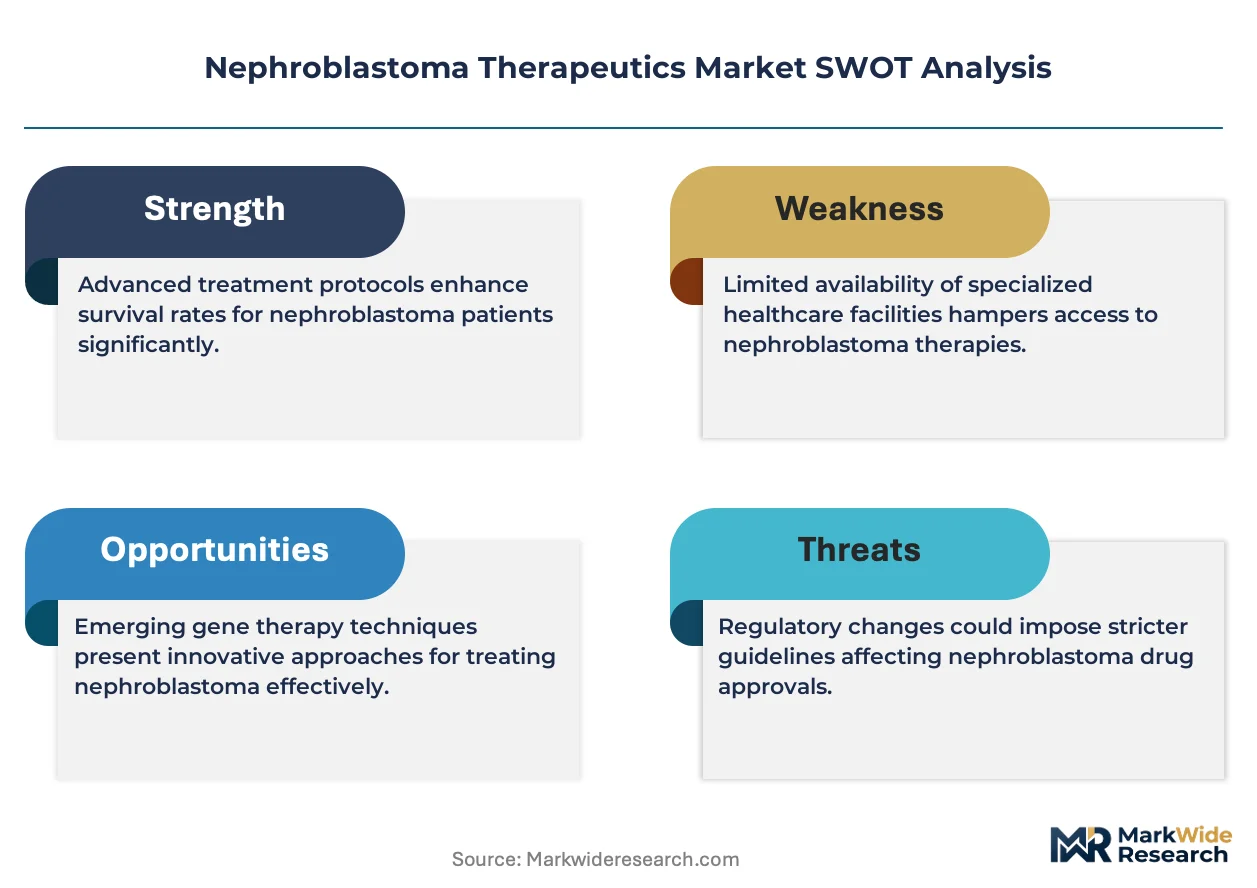
FDA pediatric study requirements under the Pediatric Research Equity Act are forcing oncology developers to redesign trial architectures around age-appropriate endpoints and biomarker stratification, compressing development timelines while elevating protocol complexity.
Growth Catalysts
- Pediatric Research Equity Act mandates:The FDA's binding study requirements for pediatric indications create guaranteed trial enrollment pools and accelerate regulatory pathway clarity for nephroblastoma drug candidates.
- CAR-T cell engineering advances:Chimeric antigen receptor T-cell platforms are migrating from hematologic malignancies toward solid pediatric tumors, opening new mechanistic avenues for WT1-targeted interventions.
- North American referral network densification:United States pediatric oncology centers are consolidating Wilms tumor expertise into regional hubs, concentrating patient volumes and enabling multi-center trial efficiency.
Market Restraints
- Small patient population economics:Nephroblastoma incidence of roughly 500 annual cases in the United States alone fragments commercial viability across therapeutic categories.
- Long-term toxicity liability:Anthracycline-induced cardiotoxicity and platinum-related nephrotoxicity in pediatric survivors create substantial post-marketing surveillance burdens and litigation exposure.
- EMA Paediatric Investigation Plan rigidity:European parallel development obligations impose fixed timelines that mismatch with mechanistic discovery cycles for rare pediatric malignancies.
Strategic Opportunities
- Liquid biopsy integration:Circulating tumor DNA monitoring for minimal residual disease detection is creating adjuvant therapy decision tools that could reshape risk stratification protocols.
- India's expanding pediatric oncology infrastructure:Regional cancer centers in Maharashtra and Tamil Nadu are building capacity for Wilms tumor surgery and chemotherapy administration, opening access expansion pathways.
- EMA orphan drug incentives:Pediatric use marketing authorization extensions and protocol assistance programs reduce regulatory friction for nephroblastoma-targeted development programs.
Industry Challenges
- Pediatric formulation manufacturing complexity:Age-appropriate dosing vehicles for infants and toddlers require specialized GMP capabilities that few contract manufacturers possess.
- Biomarker assay standardization gaps:WT1 immunohistochemistry and CTNNB1 sequencing protocols vary across cooperative group laboratories, complicating multi-site trial data integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephroblastoma Therapeutics Market |
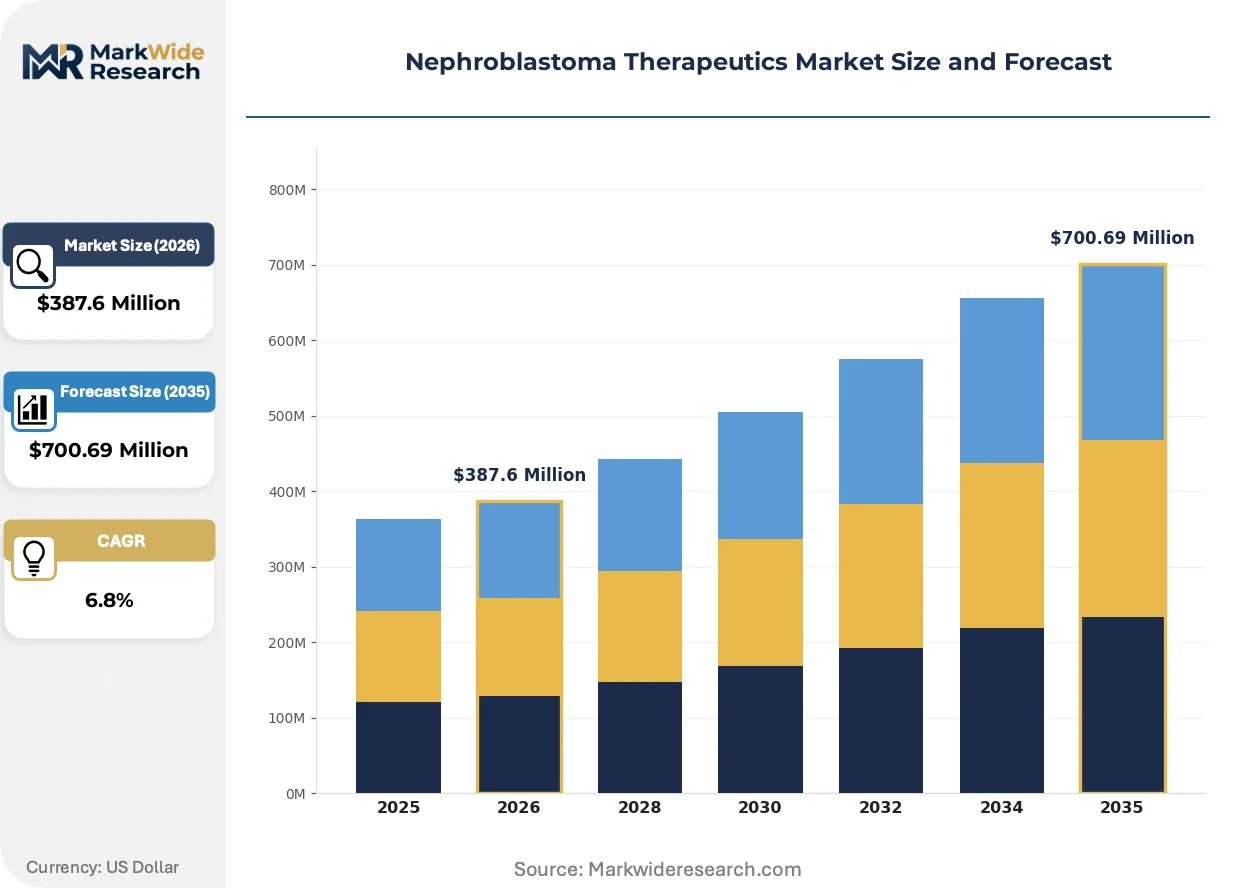
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy End User: Pediatric Hospitals, Oncology Clinics, Research Institutions, Home Healthcare Treatment Stage: Adjuvant Therapy, Neoadjuvant Therapy, Post-operative Therapy, Relapse Management Administration Route: Intravenous, Oral, Subcutaneous, Intra-arterial |
| Companies Covered | Bristol Myers Squibb, Pfizer, Merck & Co., Roche, Novartis, Sun Pharmaceutical Industries, Teva Pharmaceutical Industries, Cipla, Accord Healthcare Ireland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephroblastoma Therapeutics Market Shifts & Advancements
Combination protocol engineering is displacing sequential single-agent administration as the dominant treatment philosophy, with trial designers now optimizing drug-drug interaction profiles and sequencing algorithms rather than maximizing individual compound activity.
Checkpoint inhibitor platforms are absorbing investigator attention in relapsed and refractory nephroblastoma cohorts, with PD-1/PD-L1 blockade being tested alongside conventional backbones in Children's Oncology Group protocols. Pediatric oncology networks are enrolling these combinations at accelerating rates despite limited prior evidence in renal malignancies. The technology is absorbing capital from small-molecule targeted therapy budgets and compressing development timelines for immunotherapy-first strategies.
EMA's Paediatric Regulation amendment proposals are tightening the evidentiary standards for waivers and deferrals, forcing sponsors to front-load pediatric development planning. The industrial consequence is earlier engagement with pediatric formulation scientists and toxicologists, often before adult Phase II completion. High-risk Wilms tumor subtypes with LOH at chromosomes 1p and 16q are most affected, as sponsors now face mandatory pediatric study commitments for any renal malignancy program.
Academic medical centers are unbundling surgical and medical oncology services into discrete reimbursement categories, altering how hospitals contract for comprehensive Wilms tumor care. Children's hospitals are responding by forming integrated practice units that span diagnosis through survivorship. This restructuring is most visible in United States metropolitan markets where Medicaid managed care penetration has accelerated.
Nephroblastoma Therapeutics Market Segmentation
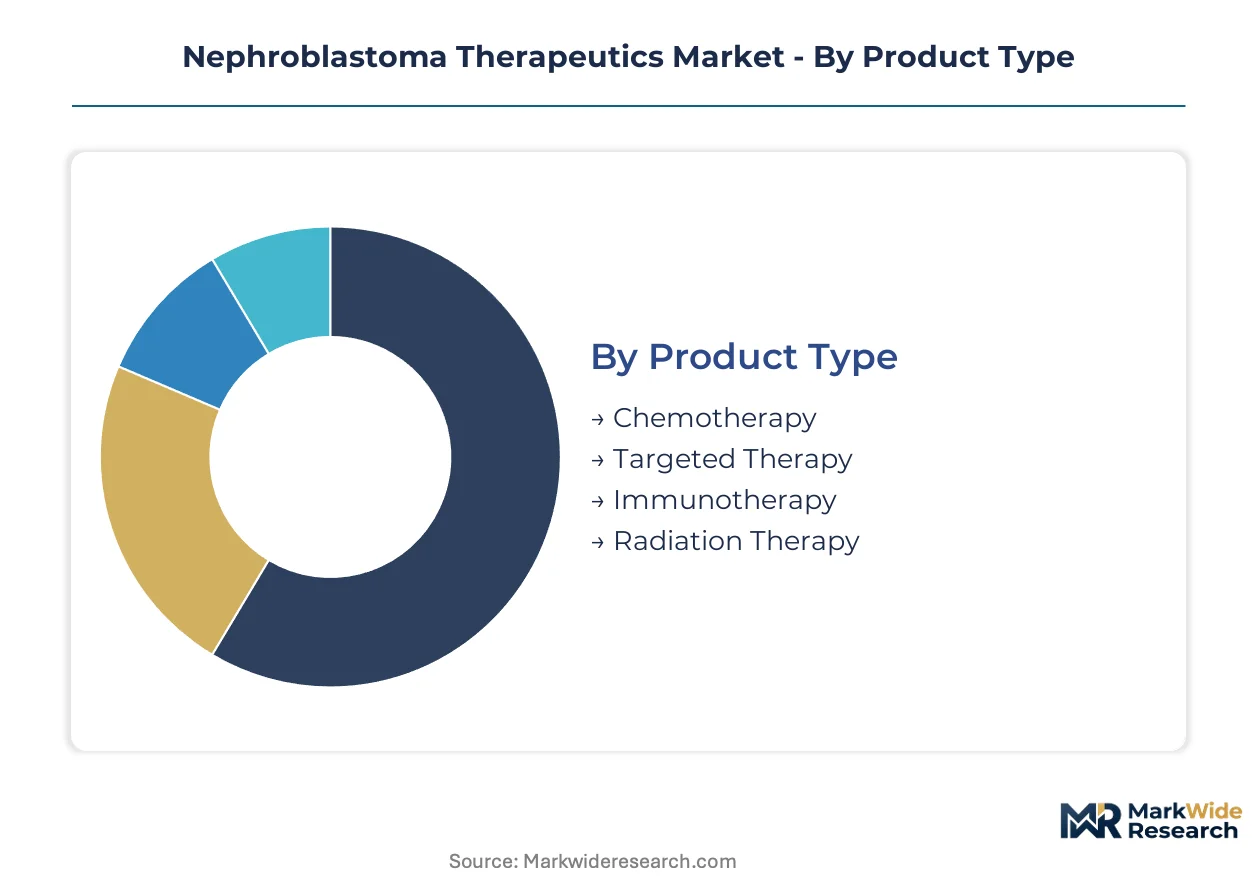
Segmentation in nephroblastoma therapeutics reflects divergent clinical priorities across treatment settings. Pediatric oncology networks allocate resources differently than adult cancer centers, while administration route selection hinges on patient age and vascular access feasibility.
Product Type:
Chemotherapy anchors volume deployment through established vincristine-dactinomycin-doxorubicin protocols, while immunotherapy commands premium positioning despite narrower current utilization.
- Chemotherapy:Multi-agent regimens combining vincristine, dactinomycin, and doxorubicin constitute the backbone of first-line nephroblastoma protocols across Children's Oncology Group trials. Demand concentrates in United States pediatric hospitals where risk-stratified dosing algorithms have achieved high completion rates, though anthracycline cardiotoxicity liability constrains long-term survivor monitoring costs.
- Immunotherapy:CAR-T cell platforms and checkpoint inhibitors are migrating from hematologic malignancies into solid pediatric tumor trials, with WT1-targeted constructs showing mechanistic promise in early-phase studies. Deployment is accelerating at academic medical centers with dedicated pediatric immuno-oncology units, driven by FDA pediatric study mandates that guarantee enrollment pools for novel mechanisms.
- Targeted Therapy:Precision interventions directed at CTNNB1 or WTX mutations occupy a higher-margin niche where druggable alterations permit biomarker-driven selection.
- Radiation Therapy:Adjuvant flank irradiation for high-risk histology remains confined to specialized centers with pediatric anesthesia capabilities and proton therapy access.
Mature deployment sits with Chemotherapy. Newer deployment is concentrated in Immunotherapy.
End User:
Institutional capabilities determine patient routing, with comprehensive care concentrating at centers maintaining surgical and medical oncology integration.
- Pediatric Hospitals:Tertiary children's hospitals with embedded pediatric surgery, oncology, and radiation therapy units capture the majority of nephroblastoma treatment episodes. Volume clusters at United States metropolitan centers with Medicaid managed care contracts and survivorship program infrastructure.
- Oncology Clinics:Community-based pediatric oncology practices handle chemotherapy administration for standard-risk patients in remission maintenance phases.
- Research Institutions:Academic medical centers with NCTN (National Clinical Trials Network) affiliation enroll patients in cooperative group protocols and early-phase investigator-initiated trials.
- Home Healthcare:Pediatric home infusion services support oral maintenance therapy and central line care for stable patients in rural catchment areas.
High-acuity care concentrates at Pediatric Hospitals. Protocol innovation is accelerating at Research Institutions.
Treatment Stage:
Timing of therapeutic intervention relative to surgery creates distinct resource intensity profiles across the care continuum.
- Adjuvant Therapy:Post-nephrectomy chemotherapy constitutes the standard-of-care backbone for favorable-histology disease, with duration stratified by stage and molecular risk features.
- Neoadjuvant Therapy:Pre-operative chemotherapy for bilateral Wilms tumor or massive unilateral disease enables parenchymal-sparing surgery at high-volume pediatric urology centers.
- Post-operative Therapy:Intensified regimens for anaplastic histology or lymph node involvement require inpatient monitoring at centers with pediatric intensive care capabilities.
- Relapse Management:Salvage protocols incorporating novel agents or radiation are restricted to centers with phase I/II trial access and stem cell transplant infrastructure.
Standard-risk deployment dominates Adjuvant Therapy. Experimental access is expanding fastest in Relapse Management.
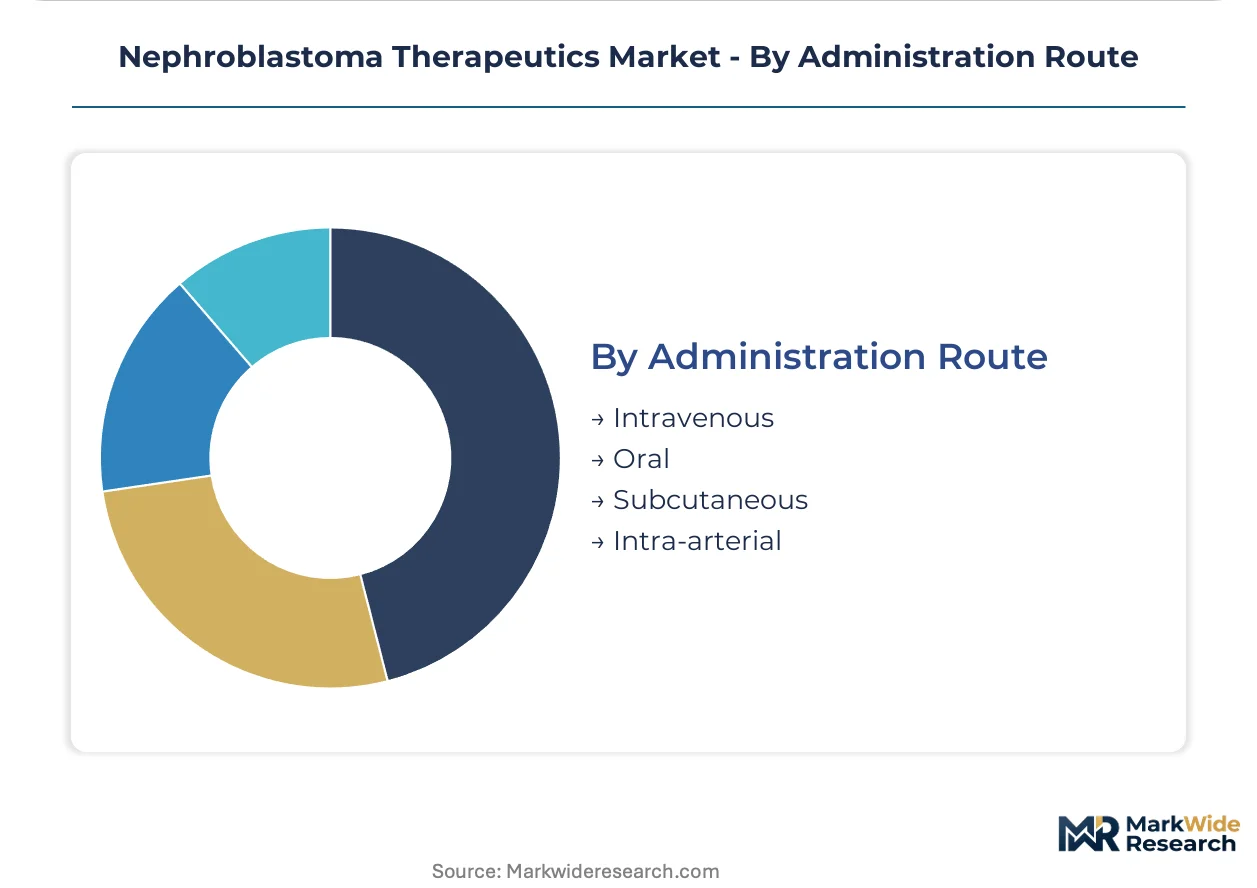
Administration Route:
Vascular access and age-appropriate formulation availability shape route selection across infant and toddler populations.
- Intravenous:Central venous access devices enable continuous infusion of vesicant chemotherapy agents, with implantable ports preferred for long-duration protocols in young children.
- Oral:Age-appropriate liquid formulations of maintenance agents reduce hospital visit burden, though palatability and bioavailability variability complicate infant dosing.
- Subcutaneous:Limited application for supportive care agents such as growth factors, constrained by body surface area calculations in small pediatric patients.
- Intra-arterial:Highly specialized delivery for unresectable hepatic metastases or pre-operative tumor embolization at centers with pediatric interventional radiology expertise.
Established practice centers on Intravenous delivery. Oral alternatives are gaining traction in maintenance phases to reduce treatment burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial density concentrates in the United States while manufacturing scale distributes across India and Europe. Patient recruitment pools and regulatory precedent create divergent investment returns across geographies.
United States
Pediatric oncology referral networks at St. Jude Children's Research Hospital and Children's Hospital of Philadelphia drive protocol enrollment velocity. FDA pediatric study requirements under PREA guarantee trial participation pools for nephroblastoma drug candidates. Boston and New York metropolitan areas concentrate immuno-oncology trial infrastructure for relapsed Wilms tumor cohorts.
Germany
Academic medical centers in Heidelberg and Berlin maintain high-volume Wilms tumor surgery programs with integrated chemotherapy protocols. EMA Paediatric Investigation Plans mandate parallel pediatric development for renal malignancy programs. The German Childhood Cancer Registry provides longitudinal outcome data that shapes European treatment guidelines.
India
Regional cancer centers in Maharashtra and Tamil Nadu are expanding pediatric nephroblastoma surgical capacity amid rising diagnosis rates. CDSCO streamlined approval pathways for oncology drugs accelerate access to generic chemotherapy agents. Mumbai and Chennai clusters concentrate pediatric oncology fellowship training programs.
United Kingdom
Great Ormond Street Hospital and Royal Marsden NHS Foundation Trust anchor national Wilms tumor treatment protocols. NHS England specialized commissioning frameworks concentrate high-complexity cases at designated pediatric cancer centers. London and Manchester metropolitan areas host the majority of early-phase pediatric oncology trials.
Japan
Pediatric cancer centers in Tokyo and Osaka participate in international cooperative group trials for high-risk nephroblastoma subtypes. PMDA pediatric drug development incentives include priority review vouchers for rare pediatric disease indications. The Japanese Pediatric Oncology Group maintains independent histopathology review capabilities for Wilms tumor classification.
Nephroblastoma Therapeutics Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with immuno-oncology platforms. Market concentration is moderate, with established oncology portfolios providing trial infrastructure advantages over specialized entrants. Two strategic archetypes dominate: integrated pharmaceutical conglomerates leveraging pediatric regulatory mandates, and generic manufacturers capturing chemotherapy volume in emerging markets. Competitive moves center on pediatric formulation partnerships and cooperative group trial sponsorships.
Among the integrated pharmaceutical conglomerates, Bristol Myers Squibb, Pfizer, and Merck & Co. occupy positions defined by immuno-oncology research commitments and pediatric trial infrastructure investments. These companies exemplify the archetype of leveraging broad oncology portfolios to secure cooperative group relationships. Generic specialists including Sun Pharmaceutical Industries and Teva Pharmaceutical Industries represent volume-driven positioning in chemotherapy supply, particularly across emerging market pediatric oncology programs.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Pfizer |
| Merck & Co. |
| Roche |
| Novartis |
| Sun Pharmaceutical Industries |
| Teva Pharmaceutical Industries |
| Cipla |
| Accord Healthcare Ireland |
| Others |
Supply & Pricing Matrix
FDA pediatric study requirements under PREA are forcing sponsors to front-load pediatric formulation development costs, compressing supplier margins for age-appropriate dosing vehicles while elevating procurement premiums for specialized GMP capabilities that few contract manufacturers possess.
Pricing Analysis
Margin tightening in chemotherapy supply reflects anthracycline cardiotoxicity liability and post-marketing surveillance burdens that elevate total cost of ownership for pediatric oncology buyers. Three-tier pricing structure across branded originator, authorized generic, and commodity generic levels stratifies procurement decisions at United States children's hospitals versus emerging market regional centers. Cost-down pressure on immuno-oncology agents accelerates because CAR-T manufacturing complexity and patient-specific production models constrain economies of scale. Pediatric hospitals with integrated survivorship programs exhibit lowest price sensitivity; community oncology clinics in Medicaid-managed networks demonstrate highest sensitivity to per-dose procurement costs.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for pharmaceutical manufacturing are reshaping active pharmaceutical ingredient sourcing patterns, with Maharashtra and Tamil Nadu regional cancer centers prioritizing locally compounded chemotherapy agents. API production concentrates in India, China, and Switzerland, with vincristine and dactinomycin feedstocks drawing from fermentation-based alkaloid extraction and bacterial culture processes. Single-source vulnerability for WT1-targeted biologic constructs hinges on specialized cold-chain logistics between CAR-T manufacturing facilities and pediatric infusion centers. Distribution runs through hospital-centric procurement networks with limited wholesale intermediation, anchored by GPO contracts at major United States children's hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA pediatric study requirements under PREA erect substantial compliance barriers that favor established players with dedicated pediatric regulatory affairs infrastructure, transforming market entry into a cost-of-compliance calculation rather than purely clinical merit.
For Market Incumbents: Extend cooperative group trial sponsorships to lock in protocol design influence at Children's Oncology Group and SIOP networks, insulating against emerging immuno-oncology specialists attempting trial enrollment capture. Deepen pediatric formulation partnerships with specialized GMP contract manufacturers to secure capacity allocation priority as domestic-content rules tighten. Anchor position through backward integration into biomarker assay standardization to resolve WT1 immunohistochemistry protocol variation across multi-site trials.
For New Entrants and Emerging Players: Rural pediatric oncology clinics in United States Medicaid expansion states represent an underserved buyer archetype with limited access to centralized trial infrastructure, offering white-space entry through telemedicine-enabled protocol support and decentralized chemotherapy administration. India's expanding regional cancer centers in secondary cities present parallel access expansion pathways through CDSCO streamlined approval leveraging. Pursue licensing arrangements for generic chemotherapy agents with pediatric liquid formulation capabilities rather than novel mechanism development.
For Investors and Strategic Acquirers: The window for entry favors platform technology specialists with WT1-targeted CAR-T assets or liquid biopsy minimal residual disease detection capabilities, as these address structural gaps in relapse management protocols. Long-term viability hinges on regulatory exclusivity duration and pediatric use marketing authorization extension potential under EMA orphan drug frameworks. Watch biomarker-driven trial readouts for anaplastic histology subtypes as inflection indicators for precision protocol adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Partnership | Secures GMP capacity for age-appropriate dosing vehicles at limited qualified manufacturers. |
| Cooperative Group Trial Sponsorship | Locks protocol design influence at Children's Oncology Group and SIOP networks. |
| Liquid Biopsy Integration | Creates adjuvant therapy decision tools reshaping risk stratification protocols. |
| EMA Orphan Drug Application | Accesses pediatric use marketing authorization extensions and protocol assistance programs. |
| Regional Cancer Center Capacity Build | Captures volume growth in Maharashtra and Tamil Nadu pediatric oncology infrastructure expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pediatric oncology trial investigators, hospital pharmacy directors, and regulatory affairs specialists at pharmaceutical sponsors. FDA PREA submission databases, EMA Paediatric Investigation Plan registries, and ClinicalTrials.gov enrollment records provided structured protocol tracking. Bottom-up patient volume estimates across United States, German, Indian, and Japanese pediatric cancer centers triangulated against top-down pharmaceutical revenue disclosures.
Reconciliation of patient enrollment velocity, drug pricing disclosures, and regional procurement pattern data informed the analytical framework across the projection horizon. Segmentation dimensions spanned product type, end user institution class, treatment stage timing, and administration route feasibility, with regional regulatory clusters modeled separately. CAGRs derived from slope analysis of historical protocol adoption curves and forward projection of immunotherapy trial enrollment acceleration. Forecast inputs incorporated biomarker assay standardization progress and domestic-content manufacturing incentive uptake.
Revisions become necessary when EMA Paediatric Regulation amendment timelines accelerate, when WT1-targeted CAR-T trials report unexpected toxicity profiles, or when India's PLI scheme pharmaceutical manufacturing incentives expand eligibility. Forecasts reflect documented assumptions regarding referral network densification rates and cooperative group protocol amendment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Germ Cell Tumors Market