
 Italy Aesthetic Devices Market | 2026-2036
Italy Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Aesthetic Devices Market Foresight
The EU Green Deal is restructuring procurement criteria across Italian healthcare networks, compelling aesthetic device suppliers to demonstrate lifecycle sustainability credentials. Allergan leverages its established dermal filler manufacturing footprint to sustain volume leadership in injectable categories. Galderma anchors its competitive position through specialized hyaluronic acid formulations tailored to Mediterranean skin profiles. El.En. dominates the domestic laser segment with in-house production of solid-state and diode platforms.
Italy aesthetic devices encompass electromechanical and consumable systems engineered for cutaneous modification, typically operating at wavelengths between 532 nm and 10,600 nm with pulse durations calibrated to selective photothermolysis parameters. These systems serve clinical and commercial settings for non-surgical appearance alteration. Laser devices occupy the largest revenue pool given their capital intensity and recurring maintenance contracts, while LED technology represents the fastest-expanding category as home-use protocols gain traction among younger demographics. Fillers command premium positioning in clinic settings where physician-administered protocols justify higher price points per treatment cycle.
Italy's national pharmaceutical regulator, AIFA, oversees device registration alongside notified bodies administering CE marking under the EU Medical Device Regulation, tightening market access for non-compliant manufacturers. The EU AI Act introduces additional scrutiny for algorithmic diagnostic modules embedded in next-generation skin analysis platforms. Stakeholders must weigh regulatory compliance investments against the accelerating shift toward AI-integrated treatment planning systems.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines while simultaneously elevating capital requirements for notified body certifications, forcing importers to consolidate distribution partnerships or exit entirely.
Growth Catalysts
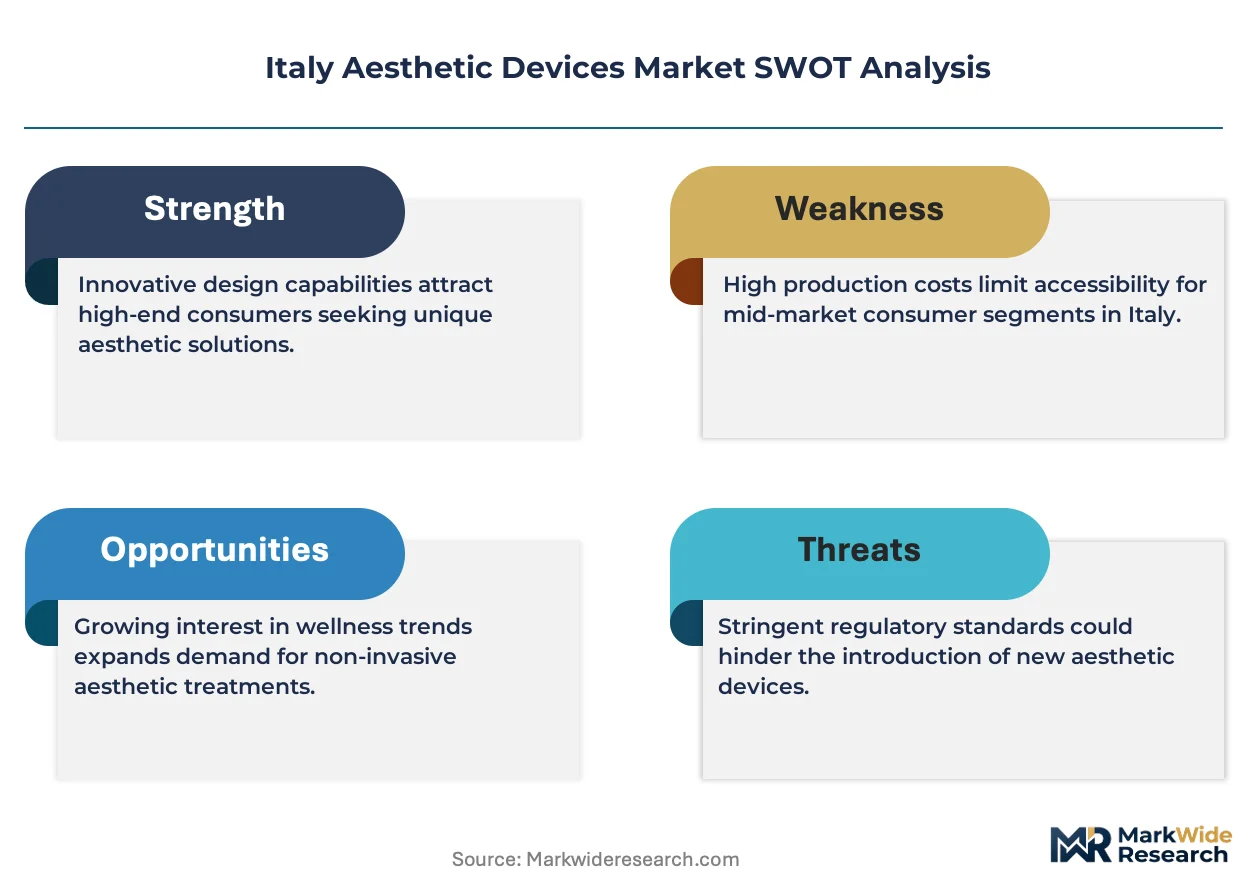
- EU Green Deal procurement mandates:Italian healthcare networks now require lifecycle sustainability documentation for capital equipment purchases, advantaging suppliers with verified carbon footprint data.
- Home-use LED protocols:Younger demographics in Milan and Turin are adopting at-home skin treatment devices, expanding the addressable consumer base beyond clinic-dependent procedures.
- AIFA fast-track pathways:Italy's national pharmaceutical regulator has streamlined registration for devices demonstrating substantial equivalence to existing CE-marked platforms.
Market Restraints
- Notified body capacity bottlenecks:EU MDR implementation has reduced the number of accredited certification bodies, extending lead times for new market entrants by 12-18 months.
- Imported component dependency:Solid-state laser crystals and precision optical assemblies concentrate sourcing from German and Swiss suppliers, exposing margins to euro-franc volatility.
- Technical limitation in skin typing:Algorithmic diagnostic modules struggle with Fitzpatrick skin type V-VI accuracy, restricting addressable populations in southern Italian clinics.
Strategic Opportunities
- Sicily and Campania clinic penetration:Southern Italy exhibits device density ratios 40% below Lombardy levels, presenting whitespace for regional distributor partnerships.
- EU AI Act compliance premium:Early certification of algorithmic treatment planning modules under the incoming framework commands pricing power in premium clinic segments.
- Consumable subscription models:Hyaluronic acid filler practices in Rome are piloting direct-to-clinic replenishment contracts, locking in recurring revenue streams.
Industry Challenges
- Laser technician certification gaps:Aesthetic medicine training programs in Italian universities have not scaled to match device installation rates, constraining treatment throughput.
- Legacy EMR integration friction:Next-generation skin analysis platforms require custom API development to connect with established clinic management systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Aesthetic Devices Market |
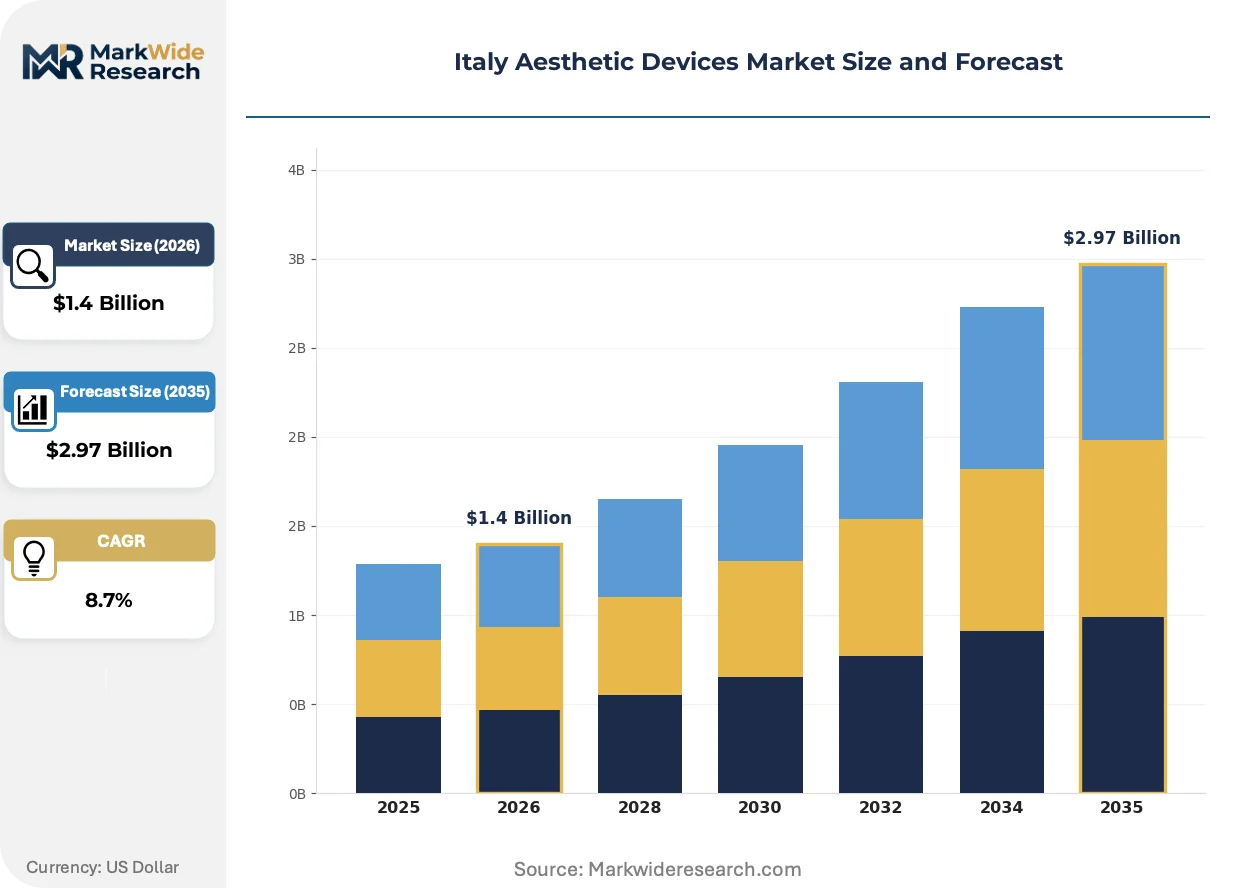
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Fillers, Microdermabrasion Equipment, Chemical Peels Technology: Non-invasive, Surgical, LED Technology, Ultrasound End User: Clinics, Hospitals, Beauty Salons, Home Users Application: Aging Treatment, Skin Rejuvenation, Hair Removal, Body Contouring |
| Companies Covered | Allergan, Galderma, Lumenis, Alma Lasers, El.En., Merz Pharma, Candela Medical, Cynosure, AbbVie, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Aesthetic Devices Market Shifts & Advancements
Algorithmic treatment planning is displacing physician-dependent protocols across northern Italian clinic networks, while regulatory pressure on embedded AI systems is accelerating compliance investment cycles.
Fractional laser technology is converging with real-time thermal monitoring sensors to enable dynamic energy delivery adjustment during ablative procedures. Dermatology clinics in Milan are deploying these hybrid platforms for acne scar revision protocols. The convergence is compressing treatment session counts while elevating per-procedure pricing power.
The EU AI Act introduces conformity assessment requirements for machine learning modules embedded in diagnostic imaging devices. Manufacturers must now document algorithmic training data provenance and performance validation across diverse skin phototypes. Italian notified bodies are prioritizing review queues for platforms demonstrating Mediterranean-population clinical evidence.
Younger patients in Turin and Bologna are bypassing traditional clinic channels entirely, purchasing home-use LED masks through direct-to-consumer platforms. This channel disintermediation is forcing established distributors to unbundle professional-grade devices from consumable service contracts. The shift is most visible in the 25-35 demographic segment, where treatment frequency exceeds clinic accessibility.
Italy Aesthetic Devices Market Segmentation
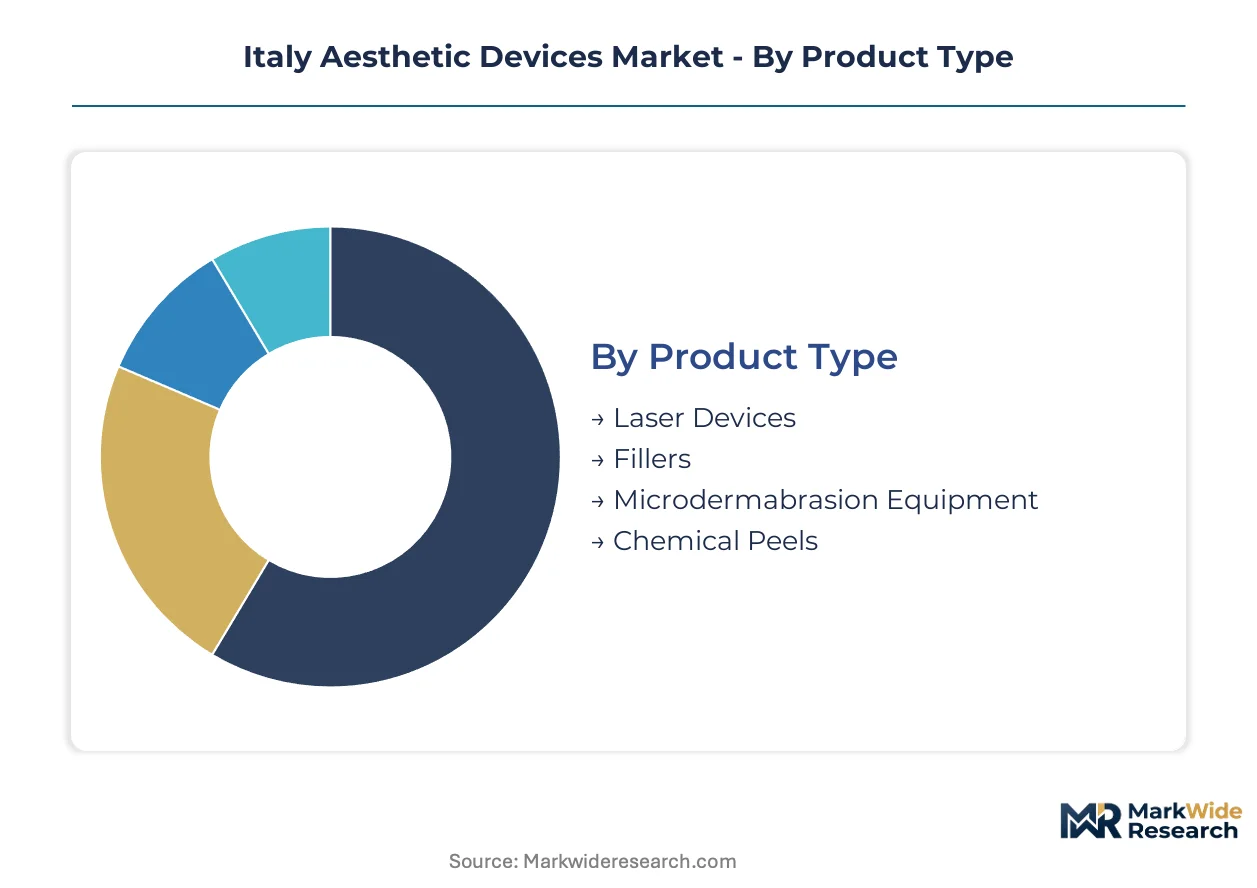
Segmentation in Italy's aesthetic devices market reveals how regulatory complexity, technology maturity, and treatment setting economics reshape procurement priorities across distinct buyer profiles. Understanding these divides exposes where CE marking burdens concentrate and where home-use protocols are bypassing traditional clinical channels.
Product Type:
Laser devices and injectable fillers carry the heaviest notified body scrutiny under EU MDR, requiring clinical evidence dossiers that microdermabrasion equipment and superficial peels largely escape.
- Laser Devices:Solid-state and diode platforms operating at 532 nm to 10,600 nm wavelengths dominate capital expenditure budgets in Milan dermatology clinics. Demand concentrates in northern Italy's private clinic corridor, where recurring maintenance contracts and technician certification requirements create high switching costs for established installations.
- Fillers:Hyaluronic acid and biostimulatory formulations command premium per-treatment economics in physician-administered settings. Rome and Milan practices are piloting direct-to-clinic replenishment subscriptions, locking recurring revenue through consumable dependency rather than device ownership.
- Microdermabrasion Equipment:Crystal and diamond-tip systems serve entry-level aesthetic services in Campania and Sicily beauty salons with lower regulatory barriers.
- Chemical Peels:Superficial to medium-depth acid formulations occupy price-sensitive segments where AIFA registration pathways remain streamlined.
Laser devices sit at the top of the volume ranking, with LED-integrated home protocols climbing the fastest.
Technology:
Technology choice in Italian clinics increasingly tracks patient throughput economics, with non-invasive modalities allowing higher daily treatment volumes than surgical alternatives requiring anesthesia protocols.
- Non-invasive:Radiofrequency and intense pulsed light platforms enable same-day return to work, driving adoption in Turin and Bologna practices serving working-age demographics. These systems bypass the facility certification requirements that constrain surgical suite investments.
- Surgical:Liposuction and ablative laser systems retain dominance in body contouring applications where single-session efficacy justifies higher per-procedure pricing and recovery downtime.
- LED Technology:Home-use masks at 415 nm and 633 nm wavelengths are disintermediating clinic channels among Milan's 25-35 demographic.
- Ultrasound:Microfocused and high-intensity platforms serve skin tightening applications with intermediate invasiveness profiles.
Non-invasive technology holds the largest installed base, though LED platforms are expanding most quickly through direct-to-consumer distribution.
End User:
End-user economics in Italy diverge sharply between reimbursed hospital settings and cash-pay private clinics, with beauty salons occupying a regulatory gray zone that AIFA scrutiny is gradually formalizing.
- Clinics:Dermatology and aesthetic medicine practices in Lombardy and Lazio concentrate device procurement, leveraging patient volume to amortize capital intensity across high-margin injectable and laser protocols.
- Hospitals:Public and private hospital aesthetic departments operate under constrained capital budgets, prioritizing multi-application platforms that serve both reconstructive and cosmetic indications.
- Beauty Salons:Campania and Sicily establishments are expanding service menus into device-based treatments, though technician certification gaps limit treatment complexity.
- Home Users:Younger demographics in northern Italian cities are bypassing clinical channels entirely for LED masks and microcurrent devices.
Clinics command the highest revenue concentration, with home users gaining share fastest through e-commerce channel expansion.
Application:
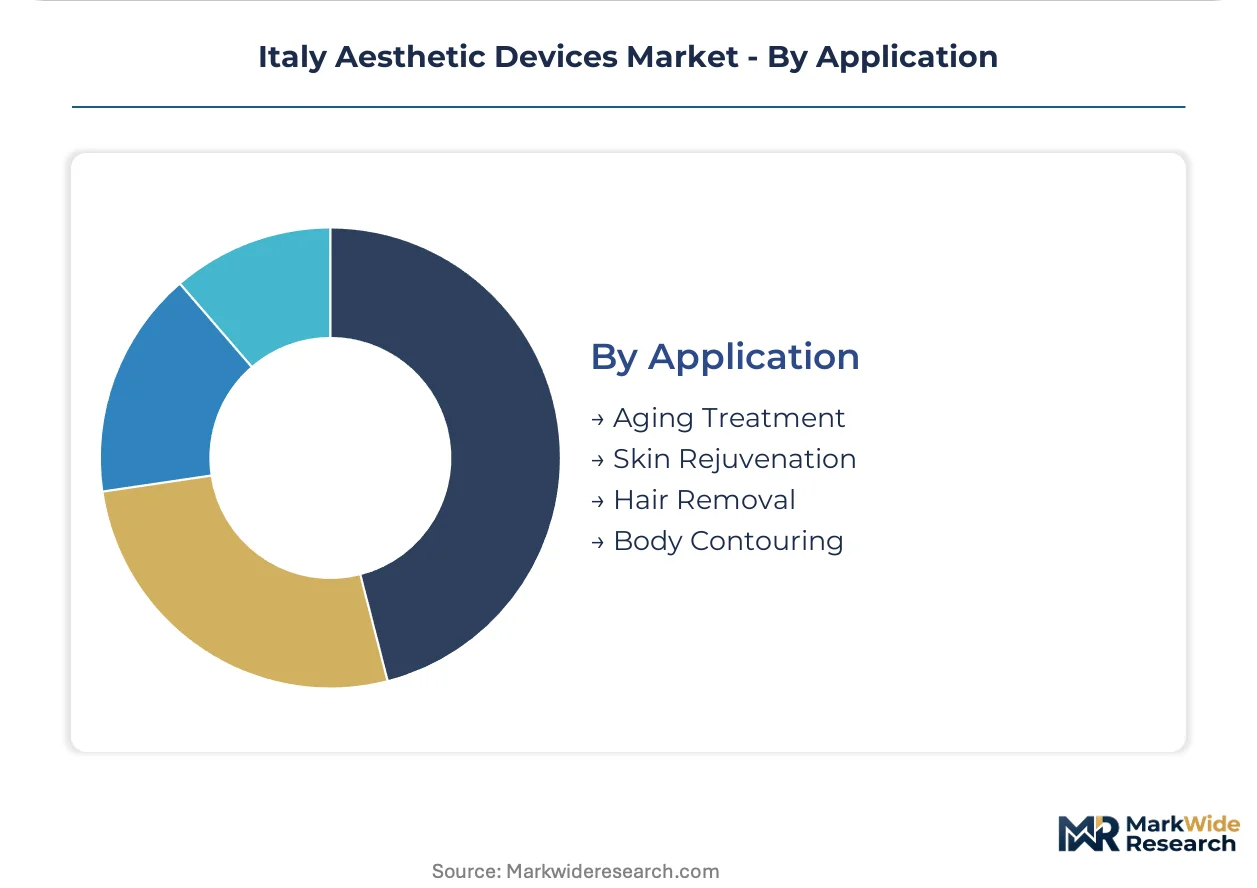
Application demand in Italy correlates with demographic aging patterns in the north and sun damage prevalence across Mediterranean coastal populations, reshaping regional device specialization.
- Aging Treatment:Injectable neuromodulators and volumizing fillers target facial rhytides and volume loss in Rome and Milan practices serving patients over 45. These protocols justify premium pricing through physician administration requirements and temporary yet repeatable treatment cycles.
- Skin Rejuvenation:Fractional laser and chemical peel protocols address photodamage across Fitzpatrick skin types I-IV prevalent in northern Italian populations, though algorithmic diagnostic modules struggle with type V-VI accuracy in southern clinics.
- Hair Removal:Diode and alexandrite laser platforms serve persistent demand across all regions with high treatment frequency economics.
- Body Contouring:Cryolipolysis and radiofrequency systems target localized adiposity in post-pregnancy and weight-loss patient segments.
Aging treatment captures the largest procedure volume, with body contouring applications showing the steepest expansion trajectory among younger patient cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aesthetic devices industry traces its European commercial origins to Italian laser engineering clusters established in Florence during the 1980s, where El.En. pioneered solid-state platform development that later diffused across Mediterranean markets. Northern Italy's manufacturing heritage continues to shape procurement patterns and technology standards throughout the peninsula.
Lombardy
Milan's dermatology corridor concentrates the highest device density ratios nationwide, with private clinics amortizing capital-intensive laser platforms across high-margin injectable protocols. AIFA's streamlined registration pathways for CE-marked equivalents accelerate procurement cycles for established suppliers. The metropolitan cluster is expanding fractional laser installations for acne scar revision, compressing treatment session counts while elevating per-procedure pricing.
Piedmont
Turin practices serve working-age demographics demanding same-day return protocols, driving radiofrequency and intense pulsed light adoption over surgical alternatives. The EU Green Deal's lifecycle sustainability mandates now filter capital equipment purchases through verified carbon footprint documentation requirements. Device distributors here are piloting direct-to-consumer LED mask channels that bypass traditional clinic intermediaries.
Lazio
Rome's aesthetic medicine practices concentrate aging treatment demand among patients over 45, with neuromodulator and volumizing filler cycles justifying premium physician-administered pricing. The EU AI Act's conformity assessment requirements are elevating compliance investment for algorithmic diagnostic modules. Central Italian clinics are deploying hybrid fractional laser platforms with real-time thermal monitoring for dynamic energy adjustment.
Sicily
Palermo and Catania beauty salons are expanding into device-based treatments, though technician certification gaps constrain treatment complexity relative to northern counterparts. AIFA scrutiny is gradually formalizing regulatory coverage for salon-grade equipment previously operating in gray zones. Southern Italy exhibits 40% lower device density than Lombardy, presenting whitespace for regional distributor partnerships targeting Campania and Sicily expansion.
Veneto
Verona and Padua clinics are adopting LED-integrated home-use protocols for younger demographics seeking treatment frequencies exceeding clinic accessibility. The EU MDR's notified body capacity bottlenecks extend lead times for new market entrants by 12-18 months, advantaging incumbent suppliers with established certification dossiers. Northeastern practices are piloting consumable subscription models for hyaluronic acid replenishment contracts.
Italy Aesthetic Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology certification spectrum, with CE-marked laser platforms commanding pricing power that unbranded salon equipment cannot replicate. The vendor base stratifies into three tiers: multinational pharmaceutical-device hybrids with integrated filler portfolios, specialized laser engineering houses with captive optical component production, and regional distributors unbundling professional devices from service contracts. Consolidation pressure concentrates among importers facing EU MDR compliance cost escalation, while domestic manufacturers exploit in-house production of solid-state crystals to defend margin structures. The dominant competitive moves are backward integration into precision optical assembly supply and algorithmic treatment planning module certification under incoming AI governance frameworks.
Within the pharmaceutical-device hybrid tier, AbbVie (through its Allergan unit) and Galderma occupy positions sustained by dermal filler manufacturing footprints and specialized hyaluronic acid formulations respectively. El.En., the Florence-based engineering house, anchors the domestic laser segment through in-house production of solid-state and diode platforms. These three exemplify how vertical control over consumable supply or critical component fabrication determines competitive durability under tightening regulatory scrutiny.
| Leading Market Players |
|---|
| Allergan |
| Galderma |
| Lumenis |
| Alma Lasers |
| El.En. |
| Merz Pharma |
| Candela Medical |
| Cynosure |
| AbbVie |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement mandates across Italian healthcare networks now require lifecycle sustainability documentation for capital equipment purchases, compelling aesthetic device suppliers to restructure sourcing around verified carbon footprint data and elevating compliance costs that concentrate pricing power among incumbent CE-marked manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Italy aesthetic devices landscape, with CE marking tier and after-sales service bundling serving as primary price differentiation drivers. Premium laser platforms command sustained pricing power through recurring maintenance contracts and technician certification dependencies, while economy-tier salon equipment faces cost compression from direct-to-consumer LED mask disintermediation. Hospital purchasing committees exhibit highest price sensitivity due to constrained capital budgets, whereas private Milan clinics demonstrate lowest sensitivity where per-procedure margins absorb equipment premiums.
Supply Chain Analysis
Reverse logistics flows for laser platform refurbishment and consumable replenishment contracts now anchor distributor profitability models across northern Italian clinic networks. Solid-state laser crystals and precision optical assemblies draw from German and Swiss suppliers, creating single-source vulnerability exposure for Italian manufacturers dependent on euro-franc volatility. Distribution runs through authorized distributor partnerships serving Lombardy and Lazio clinic corridors, with direct-to-consumer channels bypassing traditional intermediaries for home-use LED protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Italy's aesthetic devices market rests on consumable subscription economics displacing capital-sale dependency, with hyaluronic acid replenishment contracts and AI-integrated treatment planning modules driving premium-tier pricing power.
For Market Incumbents: Acquire algorithmic diagnostic module certification assets under the EU AI Act framework to preempt regulatory compliance premiums. Consolidate threatened distribution partnerships facing EU MDR cost escalation, while capturing technician certification program capacity to constrain competitor installation throughput. For New Entrants and Emerging Players: Begin with Sicily and Campania clinic penetration where device density ratios trail Lombardy levels by substantial margins. Target beauty salon regulatory formalization whitespace through streamlined AIFA registration pathways, deploying direct-to-clinic consumable subscription models to bypass capital-intensive device competition. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized laser engineering houses possessing captive optical component production and established CE marking dossiers. Long-term viability across the analysis window favors domestic manufacturers with backward integration into solid-state crystal supply, with early EU AI Act certification completion serving as the critical inflection signal for premium positioning capture.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Algorithmic Certification | Early conformity assessment completion commands pricing power in Milan premium clinic segments. |
| Consumable Subscription Model Deployment | Direct-to-clinic hyaluronic acid replenishment contracts lock recurring revenue streams against capital-sale volatility. |
| Southern Regional Distributor Partnership | Campania and Sicily whitespace exploitation addresses 40% device density deficit versus Lombardy benchmarks. |
| Technician Certification Program Scale-Up | University-aligned training capacity expansion removes treatment throughput constraints limiting platform utilization. |
| Legacy EMR API Integration Development | Custom connectivity solutions accelerate next-generation skin analysis platform deployment timelines in established clinics. |
Research Methodology
Coverage spans Italy's northern private clinic corridor, central hospital networks, and southern salon markets, with primary inputs from each. The analysis combines interviews with dermatology clinic directors, biomedical engineers, hospital purchasing committee members, and aesthetic device distributors with secondary validation through AIFA registration databases, EU MDR notified body filings, and Italian customs trade records. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models technology type, end-user setting, application category, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from installed base growth curves, replacement cycle assumptions, and consumable attachment rate trajectories specific to laser maintenance contracts and filler replenishment frequencies.
Several conditions sit outside the modeled scope, including unforeseen EU MDR implementation delays, abrupt euro-franc exchange rate movements affecting optical component sourcing, and algorithmic diagnostic accuracy breakthroughs for Fitzpatrick skin type V-VI populations. Practitioners should monitor notified body capacity expansion announcements and AIFA fast-track pathway revision triggers for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Handpiece Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Flow Diverters Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Implantable Drug Eluting Devices Market