
 Germany Spinal Surgery Devices Market | 2026-2036
Germany Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Spinal Surgery Devices Market Foresight
Titanium is consolidating its position as the dominant biomaterial in German spinal implant manufacturing, displacing legacy stainless steel systems due to superior osseointegration properties and reduced artifact interference in postoperative MRI imaging. Globus Medical leverages advanced additive manufacturing capabilities to produce patient-specific titanium interbody cages. B. Braun Aesculap anchors its competitive position through deep integration with German hospital procurement networks. Stryker Corporation differentiates via proprietary navigation platforms paired with its implant portfolios.
Germany spinal surgery devices encompass instrumented systems for spinal stabilization, decompression, and correction, typically fabricated from titanium alloys or polyetheretherketone composites and sterilized for single-use or reprocessed deployment in operating theater environments. Spinal fusion systems dominate current revenue flows, though minimally invasive surgery technologies are capturing disproportionate growth as ambulatory surgical capacity expands in German orthopedic clinics. Robotic surgery platforms command concentrated investment from capital budgets, while traditional surgery modalities retain volume leadership in trauma applications across public hospital systems.
The EU Medical Device Regulation (MDR) and Germany's Federal Institute for Drugs and Medical Devices (BfArM) impose escalating clinical documentation burdens on implantable spinal device manufacturers, directly shaping product development timelines and market access pathways. CE marking requirements under MDR Annex VIII now mandate sustained post-market surveillance for Class III spinal implants, compelling manufacturers to restructure quality management systems. Stakeholders must monitor reimbursement negotiations between German statutory health insurers and device suppliers, as these determinations will dictate which technology tiers achieve routine coverage.
Market Dynamics
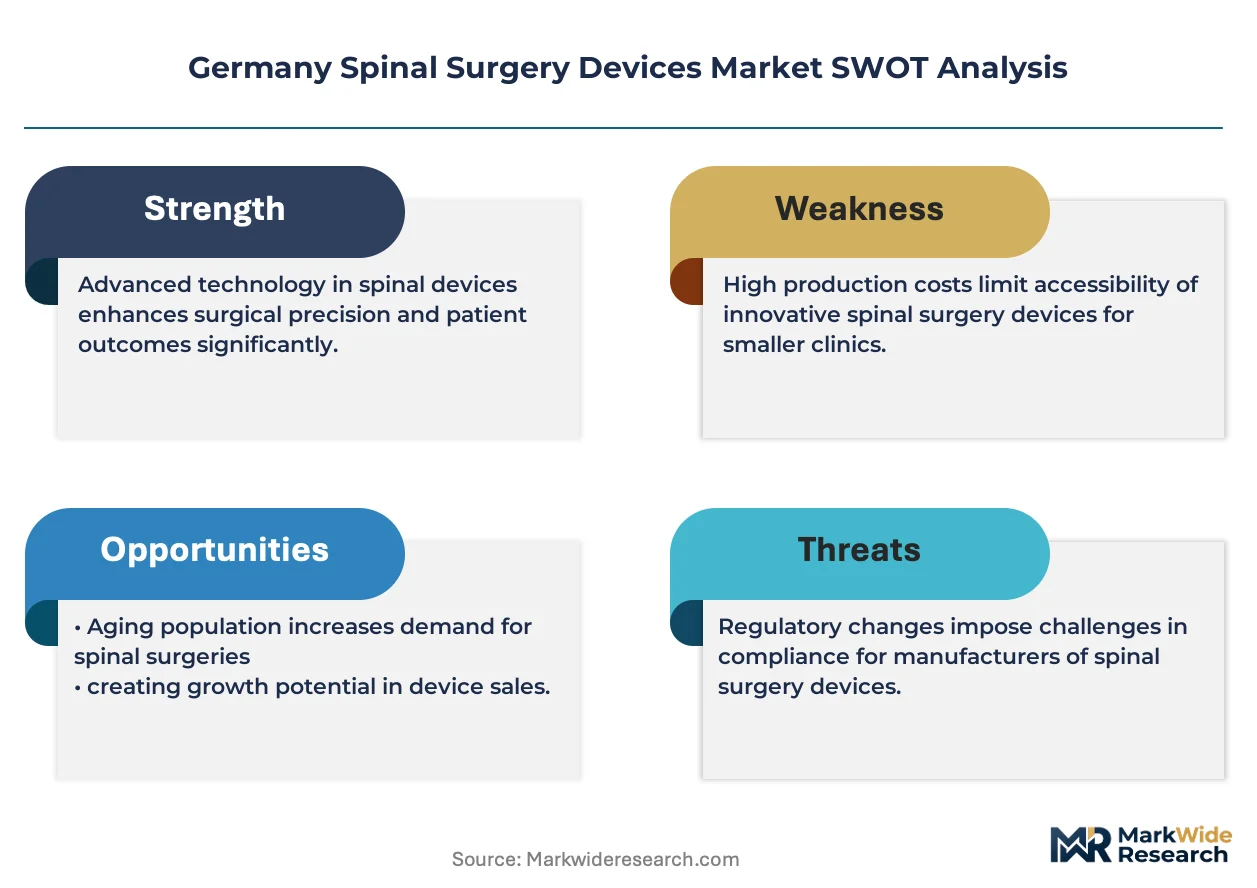
The EU Medical Device Regulation (MDR) is compressing product development timelines while simultaneously elevating clinical evidence thresholds for implantable spinal systems, forcing manufacturers to restructure quality management systems around sustained post-market surveillance obligations.
Growth Catalysts
- EU MDR Annex VIII compliance:Class III spinal implants now require enhanced clinical documentation, creating competitive moats for established manufacturers with robust quality infrastructure.
- Titanium alloy osseointegration:Superior bone-bonding properties and reduced MRI artifact interference drive conversion from legacy stainless steel systems in university hospital networks.
- Ambulatory surgical expansion:Orthopedic clinics across Bavaria and North Rhine-Westphalia are building dedicated spinal procedure capacity outside traditional hospital settings.
Market Restraints
- Raw material concentration:Medical-grade titanium sponge supply concentrates among a limited pool of certified European smelters, exposing manufacturers to input cost volatility.
- BfArM documentation burdens:Germany's Federal Institute for Drugs and Medical Devices imposes iterative review cycles that extend market access timelines for novel implant designs.
- Polyetheretherketone substitution threat:Radiolucent PEEK interbody cages compete directly with titanium in specific fusion procedures where postoperative imaging clarity is prioritized.
Strategic Opportunities
- Additive manufacturing integration:Patient-specific titanium cage production via advanced 3D printing enables anatomical matching previously impossible with standard implant geometries.
- Robotic navigation convergence:Pairing implant portfolios with proprietary surgical planning software creates bundled value propositions for capital-intensive hospital investments.
- Statutory health insurance negotiations:Reimbursement determinations by German sickness funds will dictate which technology tiers achieve routine coverage versus premium out-of-pocket positioning.
Industry Challenges
- CE marking timeline compression:MDR transition deadlines force simultaneous re-certification of legacy product portfolios alongside new development pipelines.
- Biomaterials engineering talent scarcity:Specialized expertise in titanium alloy surface modification and PEEK composite optimization concentrates within limited academic and industrial research clusters.
- Legacy system integration friction:Navigation platforms and robotic systems must interface with heterogeneous hospital IT infrastructure and imaging equipment from multiple vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Spinal Surgery Devices Market |
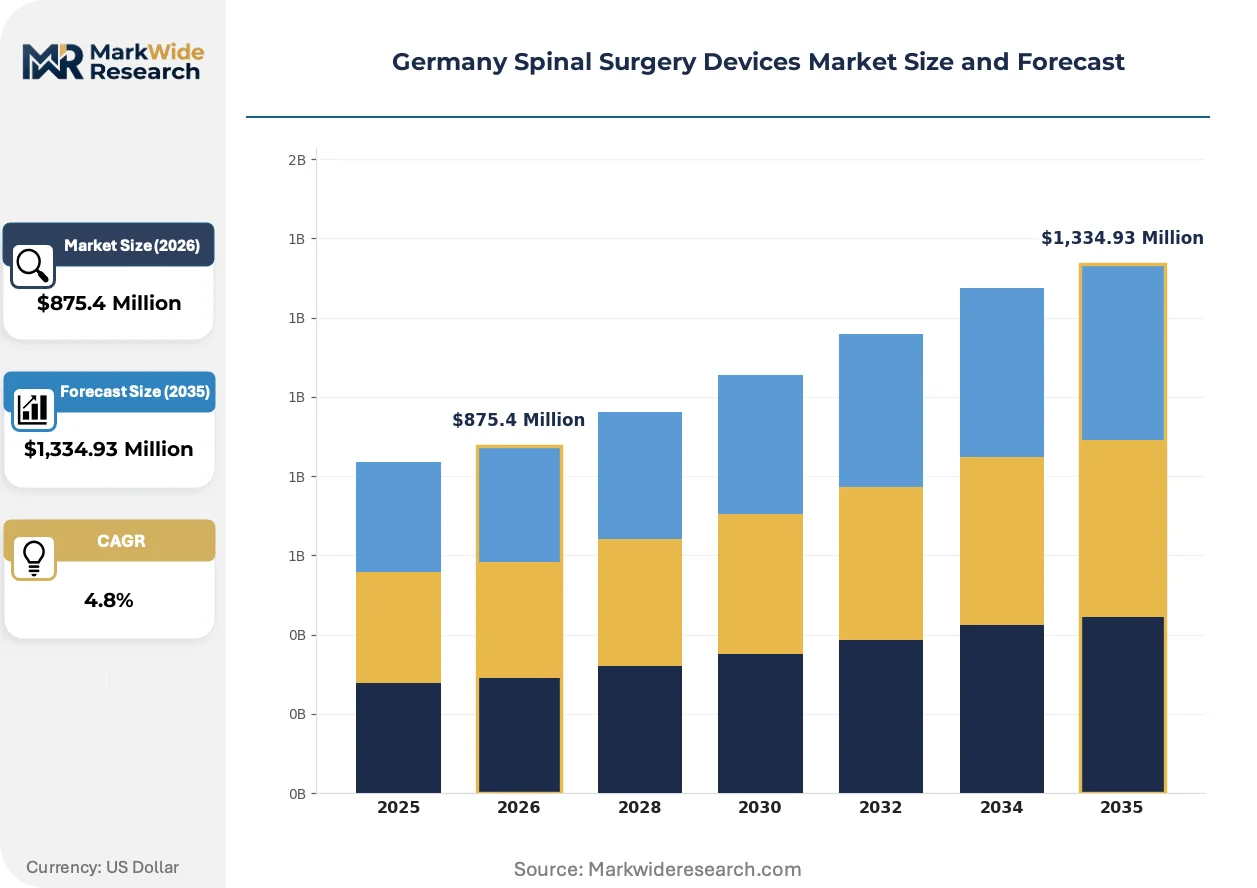
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,334.93 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion, Discectomy, Spinal Implant, Vertebroplasty Technology: Robotic Surgery, 3D Navigation, Minimally Invasive Surgery, Traditional Surgery End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Neurology Centers Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Globus Medical, Zimmer Biomet Holdings Inc, Medtronic PLC, Joimax GmbH, Alphatec Spine Inc., Stryker Corporation, NuVasive, Inc., B. Braun Aesculap, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Spinal Surgery Devices Market Shifts & Advancements
Minimally invasive surgical techniques are compressing procedure recovery timelines while simultaneously demanding specialized instrument miniaturization and enhanced intraoperative imaging capabilities from device manufacturers.
Additive manufacturing of patient-specific titanium interbody cages is overtaking conventional machining for complex anatomical reconstructions. University hospital networks in Bavaria now specify 3D-printed implants for revision fusion cases involving significant bone loss. This technology is enabling geometric complexity that improves load distribution and accelerates osseointegration compared to standard cage designs.
MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection from implanted patients. Manufacturers must now fund registry participation and adverse event reporting infrastructure that was previously voluntary. Spinal fusion systems face the steepest compliance burdens given their Class III designation and long-term implantation profiles.
Hospital procurement departments are consolidating vendor relationships around full-procedure portfolios rather than discrete implant categories. German statutory health insurers increasingly reference these bundled contracts in reimbursement negotiations. This concentration is most visible in North Rhine-Westphalia's university hospital networks, where single-source agreements now cover implant, instrument, and navigation platform provision.
Germany Spinal Surgery Devices Market Segmentation
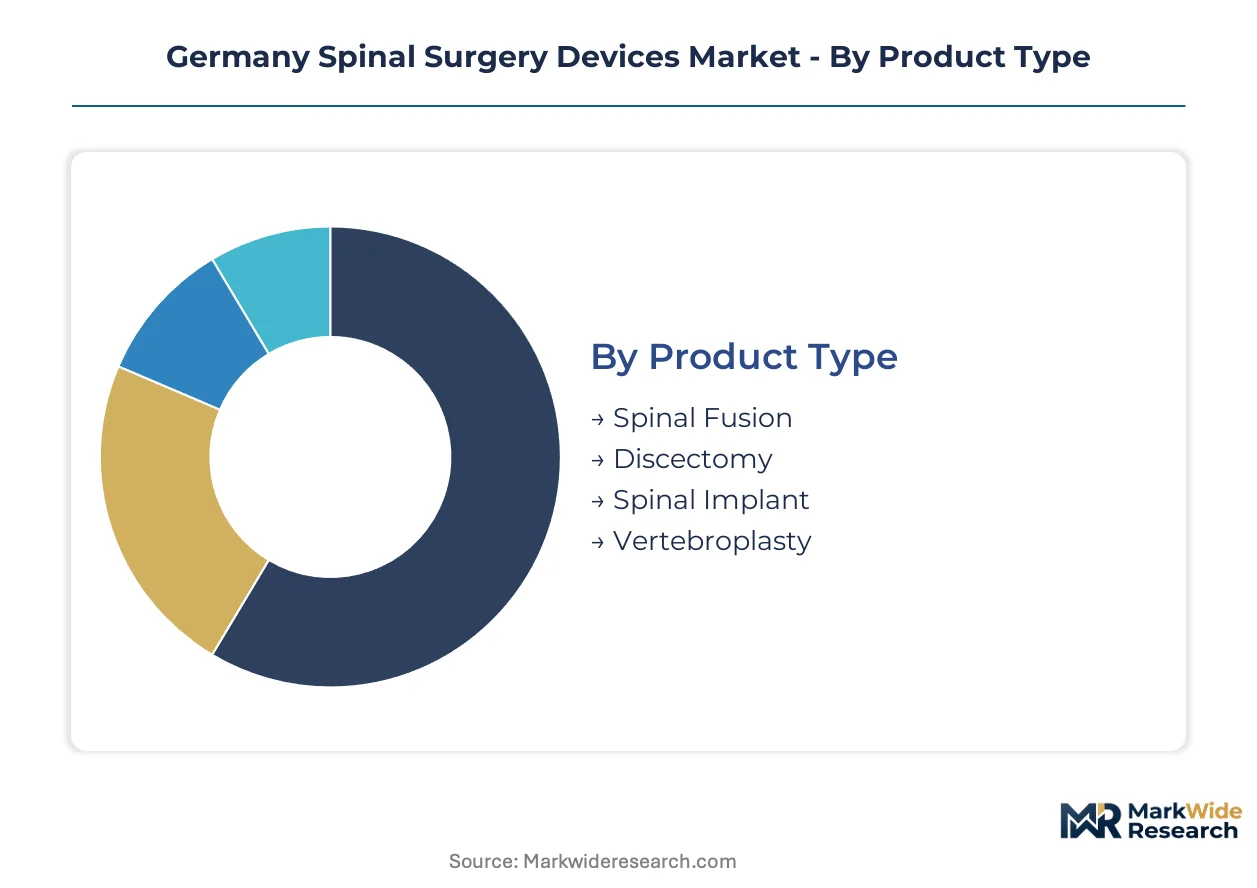
Segmentation in the German spinal surgery devices market reveals how procurement power, clinical evidence requirements, and reimbursement pathways concentrate demand across specific technology tiers and care settings. Understanding these divisions exposes where MDR compliance costs and titanium supply constraints reshape competitive access.
Product Type:
Supply concentration in medical-grade titanium sponge and specialized PEEK composite manufacturing tilts competitive advantage toward product categories with the most demanding material specifications and longest regulatory track records.
- Spinal Fusion:Instrumented systems combining pedicle screws, rods, and interbody cages fabricated from titanium alloys or PEEK composites. University hospital networks in Bavaria and North Rhine-Westphalia drive procurement volume for these Class III implants under MDR Annex VIII surveillance obligations.
- Spinal Implant:Standalone devices including artificial discs, expandable cages, and dynamic stabilization systems. Demand clusters in revision procedures where osseointegration performance determines reoperation rates and long-term reimbursement justification.
- Discectomy:Instruments for nucleus pulposus removal and decompression.
- Vertebroplasty:Bone cement delivery systems for compression fracture stabilization.
Today's leader: Spinal Fusion. Tomorrow's challenger: Spinal Implant.
Technology:
Capital intensity and software validation requirements stratify the vendor landscape, with navigation and robotic platforms demanding hospital IT integration capabilities that smaller manufacturers cannot sustain.
- Traditional Surgery:Open approaches with direct visualization and manual instrumentation. Public hospital systems retain volume leadership here, constrained by capital budget limitations and trauma case urgency that precludes setup time for advanced platforms.
- Minimally Invasive Surgery:Percutaneous and tubular retractor techniques reducing tissue disruption. Orthopedic clinics across Bavaria are expanding dedicated spinal procedure capacity outside traditional hospital settings, capturing disproportionate growth.
- Robotic Surgery:Computer-assisted platforms with preoperative planning and intraoperative guidance. BfArM software validation requirements extend market access timelines for novel systems.
- 3D Navigation:Real-time imaging overlay systems for screw placement accuracy.
Traditional Surgery commands current volume. Minimally Invasive Surgery is climbing the fastest as ambulatory capacity expands.
End User:
Procurement consolidation around full-procedure portfolios favors end users with sufficient case volume to justify exclusive vendor relationships and bundled contract structures.
- Hospitals:Primary site for complex deformity correction and trauma stabilization. North Rhine-Westphalia's university hospital networks now operate under single-source agreements covering implant, instrument, and navigation platform provision.
- Orthopedic Clinics:Dedicated spinal procedure units building capacity outside hospital systems. These facilities prioritize minimally invasive techniques with compressed recovery timelines that support same-day discharge protocols.
- Rehabilitation Centers:Postoperative recovery and functional restoration services.
- Neurology Centers:Specialized care for spinal cord and nerve root pathologies.
Hospitals anchor procurement volume. Orthopedic Clinics represent the steepest expansion trajectory as statutory health insurance negotiations shift reimbursement toward outpatient settings.
Application:
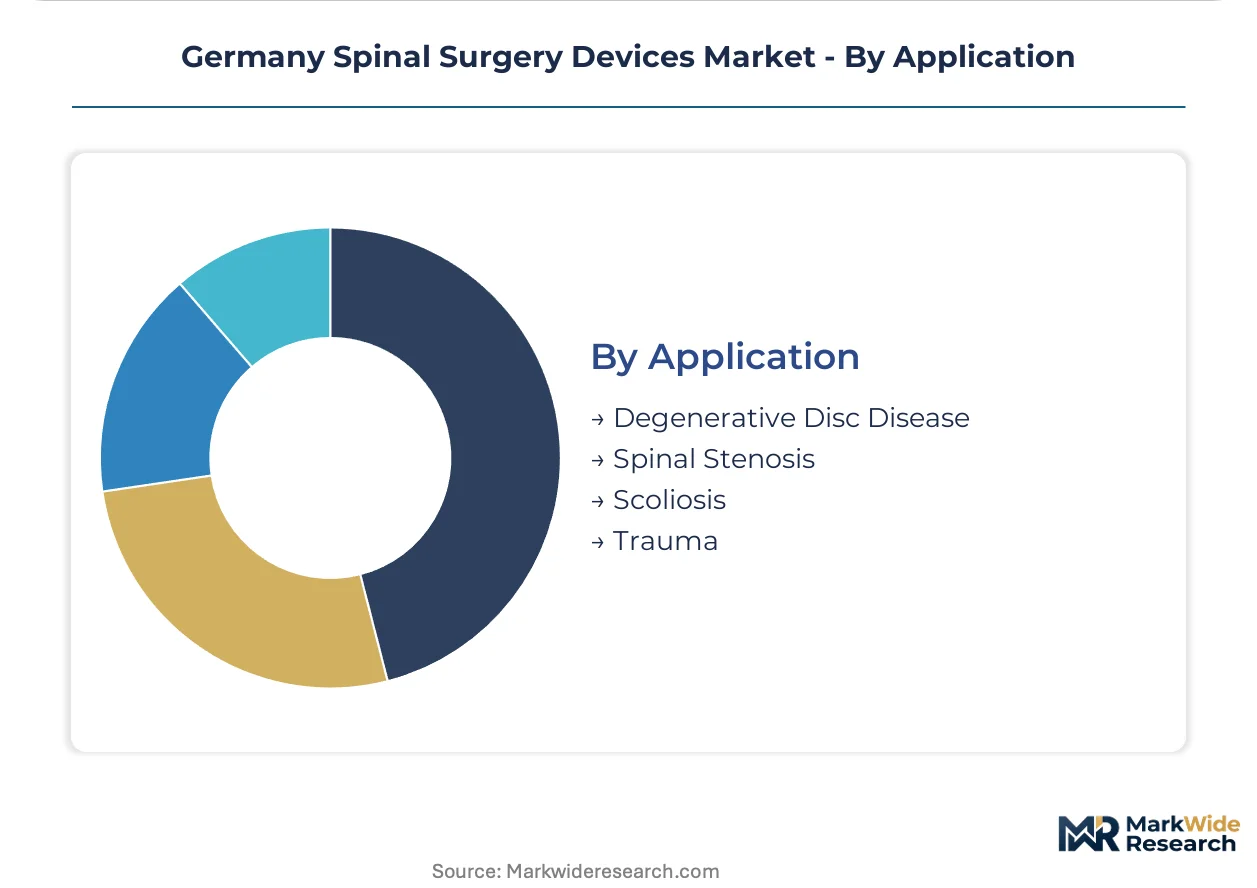
Clinical indication severity and patient age demographics determine reimbursement tier placement and technology selection, with degenerative conditions dominating procedure volume.
- Degenerative Disc Disease:Age-related disc breakdown requiring decompression or fusion. This indication captures the largest procedure volume across German statutory health insurance-covered interventions.
- Spinal Stenosis:Canal narrowing with neural compression. Minimally invasive decompression techniques are displacing open laminectomy in ambulatory surgical settings where recovery compression drives competitive differentiation.
- Scoliosis:Deformity correction in adolescent and adult populations.
- Trauma:Acute fracture stabilization and spinal cord injury management.
Degenerative Disc Disease leads procedure counts. Spinal Stenosis is gaining share fastest as minimally invasive techniques mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's university hospital networks anchor procurement volume for spinal fusion systems, while North Rhine-Westphalia's single-source vendor agreements reshape competitive access across German care settings.
Bavaria
University hospital networks in Munich and Erlangen drive demand for Class III titanium implants under MDR Annex VIII surveillance. BfArM's iterative review cycles extend market access timelines for novel cage designs manufactured via additive processes. The Nuremberg medical technology corridor concentrates additive manufacturing capabilities for patient-specific interbody devices.
North Rhine-Westphalia
Single-source procurement agreements covering implant, instrument, and navigation platforms now dominate Cologne and Düsseldorf hospital systems. Statutory health insurance negotiations between regional sickness funds and device suppliers determine reimbursement tiers for robotic surgery platforms. The Ruhr industrial basin hosts specialized titanium alloy surface modification research clusters serving implant manufacturers.
Baden-Württemberg
Orthopedic clinics in Stuttgart and Karlsruhe expand ambulatory spinal procedure capacity outside traditional hospital infrastructure. EU MDR post-market surveillance obligations mandate systematic clinical follow-up data collection from implanted patients in Tübingen's university medical center. The region's precision engineering heritage supports instrument miniaturization for minimally invasive techniques.
Hesse
Frankfurt's statutory health insurance headquarters influence national reimbursement determinations for premium implant tiers. BfArM documentation requirements for software validation extend market access timelines for navigation platforms seeking CE marking. The Darmstadt materials science cluster concentrates PEEK composite optimization expertise competing with titanium in specific fusion procedures.
Berlin-Brandenburg
Charité Berlin's trauma departments retain volume leadership in emergency spinal stabilization requiring traditional open approaches. Federal procurement frameworks negotiated in the capital shape hospital vendor consolidation patterns nationwide. The Adlershof technology park hosts biomedical engineering startups developing robotic navigation convergence technologies.
Germany Spinal Surgery Devices Market Competitive Landscape
Global majors compete with regional champions across procurement network depth and regulatory compliance infrastructure, producing a tiered structure where established manufacturers with robust quality management systems capture disproportionate share. Consolidation concentrates around full-procedure portfolio vendors capable of bundling implant, instrument, and navigation platform provision. Three archetypes dominate: integrated multinationals with proprietary navigation software, specialized spinal device pure-plays leveraging additive manufacturing differentiation, and diversified medtech conglomerates anchoring hospital procurement relationships through broad surgical portfolios. Competitive moves center on M&A to fill technology gaps and strategic partnerships with university hospitals for clinical evidence generation under MDR requirements.
Among Germany-based manufacturers, B. Braun Aesculap occupies a position exemplifying deep hospital procurement network integration, while Joimax GmbH represents the specialized minimally invasive instrumentation archetype. Globus Medical and Stryker Corporation anchor the multinational tier with bundled implant-navigation offerings. These four entities illustrate how competitive positioning stratifies across regulatory compliance scale, manufacturing technology specialization, and geographic procurement proximity.
| Leading Market Players |
|---|
| Globus Medical |
| Zimmer Biomet Holdings Inc |
| Medtronic PLC |
| Joimax GmbH |
| Alphatec Spine Inc. |
| Stryker Corporation |
| NuVasive, Inc. |
| B. Braun Aesculap |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Biomedical engineering talent clusters in the Ruhr industrial basin and Tübingen's university corridor concentrate specialized titanium alloy surface modification expertise, creating labor-cost differentials that widen pricing spreads between premium patient-specific implants and standard catalog devices.
Pricing Analysis
Medical-grade titanium sponge pass-through from certified European smelters directly compresses margins at the standard-tier implant level. Pricing stratifies across premium, standard, and economy tiers, with CE marking under MDR Annex VIII and additive manufacturing complexity as primary differentiation drivers. Pricing pressure stems from statutory health insurance reimbursement negotiations that cap allowable charges for fusion procedures. Orthopedic clinics building ambulatory capacity exhibit highest price sensitivity, while university hospital networks in Bavaria prioritize osseointegration performance over cost.
Supply Chain Analysis
Medical-grade titanium sponge supply rests on a concentrated pool of certified European smelters in Germany, France, and Italy, with PEEK composite feedstock drawing from specialized polymer processors in Switzerland and the Netherlands. Critical dependencies include titanium alloy ingots, radiolucent PEEK blanks, and precision-machined instrumentation. Single-source vulnerability concentrates in additive manufacturing powder certification, where qualified suppliers remain limited. Distribution runs through hospital procurement networks and GPO contracts, with direct-to-clinic channels expanding for minimally invasive instrument sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany spinal surgery devices market represents a late-cycle quality story where MDR compliance infrastructure and clinical evidence depth separate viable competitors from marginal players, with demand shifting decisively toward titanium implants demonstrating superior long-term osseointegration data.
For Market Incumbents: Cement market position by acquiring additive manufacturing powder certification capabilities to secure titanium supply continuity, while deepening software validation resources to accelerate BfArM navigation platform approvals. PEEK substitution in lumbar fusion and emerging robotic navigation pure-plays threaten premium positioning. Vertical integration into patient-specific cage production preserves margin against commoditization.
For New Entrants and Emerging Players: Specialized orthopedic clinics in Baden-Württemberg offer the most penetrable channel, as these facilities seek differentiated minimally invasive instrument sets outside established hospital procurement networks. Target ambulatory spinal stenosis decompression with disposable tubular retractor systems that bypass capital-intensive robotic platform competition. Partner with statutory health insurance regional funds for early reimbursement pathway establishment.
For Investors and Strategic Acquirers: Diversified medtech conglomerates with existing hospital procurement relationships are the most active acquirers in this space, seeking to fill spinal navigation software gaps. The five-to-ten-year viability window favors targets with established MDR quality management systems and university hospital clinical data partnerships. Watch BfArM software validation backlog clearance rates as the inflection signal for robotic platform market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Annex VIII Compliance Infrastructure | CE marking for Class III implants under BfArM oversight creates sustainable competitive moats against undercapitalized rivals. |
| Additive Manufacturing Integration | Patient-specific titanium cage production via 3D printing enables anatomical matching impossible with standard geometries. |
| University Hospital Clinical Partnerships | Systematic follow-up data collection satisfies MDR post-market surveillance obligations for long-term implant registries. |
| Navigation Platform Software Validation | BfArM approval for robotic surgery systems enables bundled implant-instrument-platform contracts in North Rhine-Westphalia. |
| Statutory Health Insurance Reimbursement Strategy | Negotiations with regional sickness funds determine which technology tiers achieve routine versus premium out-of-pocket coverage. |
Research Methodology
Multiple input streams — structured interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; regulatory filings with BfArM and EMA MDR databases; and hospital procurement contract records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from statutory health insurance reimbursement determinations, university hospital implant registry data, and titanium alloy trade flow documentation.
Historical volume trajectories were cross-referenced against panel input from spinal device commercial executives to establish analytical framework parameters across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user setting, and application indication, with CAGRs derived from procedure volume elasticity to demographic aging patterns and ambulatory surgical capacity expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDR implementation enforcement consistency, titanium sponge supply disruptions, and statutory health insurance reimbursement tier restructuring. A small set of named triggers — BfArM software validation timeline shifts, additive manufacturing powder qualification expansions, and regional sickness fund contract consolidation patterns — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Composite Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Global Concussion Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Hemorrhage Control System Market