
 Global Single-Use Medical Device Reprocessing Market | 2026-2036
Global Single-Use Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single-Use Medical Device Reprocessing Market Foresight
Buyer concentration among hospital systems and integrated delivery networks is hardening across North America and Western Europe. Medline Industries leverages its distribution infrastructure to secure long-term reprocessing contracts with multi-hospital networks. Stryker Corporation anchors its position through proprietary device collection and tracking systems that lock in recurring reprocessing volumes. Innovative Health competes by specializing exclusively in electrophysiology catheter reprocessing, a narrow niche with high customer switching costs.
Single-use medical device reprocessing encompasses the validated cleaning, functional testing, sterilization, and repackaging of devices originally manufactured for one patient use, subject to strict bioburden reduction and material integrity protocols. The process typically achieves sterility assurance levels of 10^-6 while preserving dimensional tolerances within original manufacturer specifications for flexible polymers and stainless-steel components. Catheters and endoscopes within the product type dimension generate the deepest margin pools due to high original equipment costs and established validation pathways. Hydrogen peroxide plasma and ethylene oxide technologies lead the technology dimension for heat-sensitive polymer devices, while steam sterilization dominates simpler metallic instruments with lower reprocessing complexity.
The FDA regulates reprocessed devices as medical devices requiring 510(k) clearance with substantial equivalence demonstrations, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations across European markets. Japan's PMDA maintains a parallel approval track that demands in-country performance testing for reprocessed device categories. Stakeholders must monitor how divergence between FDA predicate device policies and EU MDR clinical evaluation requirements reshapes viable geographic expansion strategies for reprocessing service providers.
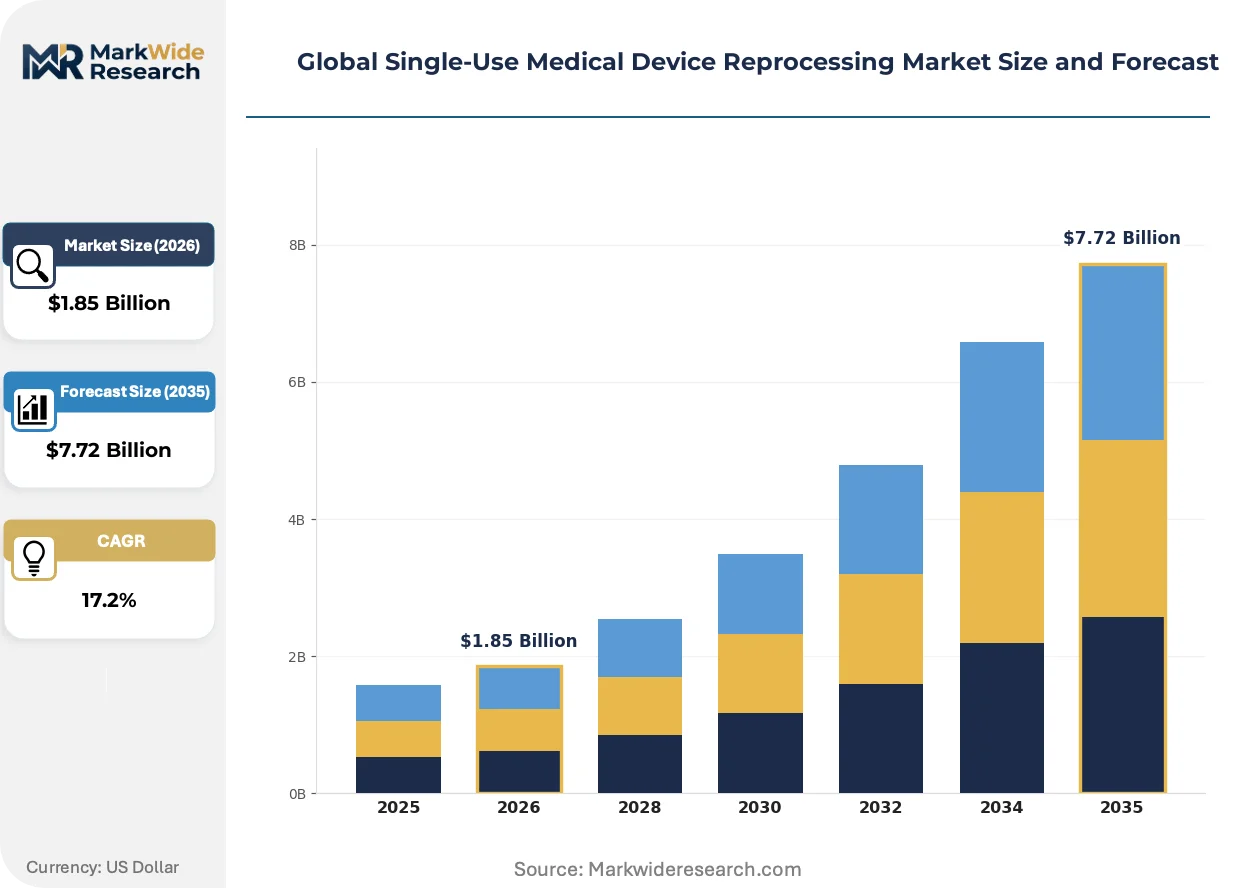
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously locking in multi-year reprocessing contracts that favor scale operators with validated sterilization infrastructure across multiple device categories.
Growth Catalysts
- Medicare reimbursement compression:Tightening DRG-based payments in the United States are forcing hospital systems to reduce per-procedure supply costs through catheter and endoscope reprocessing programs.
- EU MDR post-market surveillance mandates:Stricter clinical evidence requirements for new device approvals in Europe are extending replacement cycles and sustaining demand for validated reprocessed alternatives.
- Hydrogen peroxide plasma sterilization:Advances in low-temperature sterilization technology are expanding reprocessable device categories to heat-sensitive polymer instruments previously excluded from programs.
Market Restraints
- Original equipment manufacturer lock-in:Device makers embed proprietary connectors and materials that complicate third-party reprocessing validation and increase switching costs for hospital systems.
- Polymer supply concentration:Specialized medical-grade polymers for catheter manufacturing concentrate among a limited supplier base in Germany and the United States, creating input cost volatility for reprocessors.
- FDA 510(k) predicate drift:Evolving substantial equivalence standards for reprocessed devices are extending clearance timelines and raising regulatory compliance expenditures for service providers.
Strategic Opportunities
- Japan PMDA in-country testing requirements:The parallel approval track for reprocessed devices creates first-mover advantage for operators establishing localized sterilization and validation capabilities.
- Electrophysiology catheter specialization:Narrow-focus reprocessing for high-value cardiac catheters offers margin expansion through premium pricing and dedicated service-level agreements with electrophysiology labs.
- Integrated delivery network centralized contracting:Multi-hospital systems in the United States are consolidating reprocessing procurement, creating volume concentration opportunities for vendors with national logistics infrastructure.
Industry Challenges
- Bioburden validation technician scarcity:The specialized microbiology and materials science expertise required for FDA-compliant sterility assurance testing outpaces available training program output.
- Legacy hospital inventory system integration:Reprocessing service providers must engineer custom data interfaces with disparate hospital ERP platforms to enable real-time device tracking and recall management.
- Ethylene oxide emission compliance:EPA and state-level air quality regulations are restricting sterilization facility siting and requiring costly abatement technology upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single-Use Medical Device Reprocessing Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.72 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Catheters, Surgical Instruments, Respiratory Devices, Dialysis Equipment Technology: Steam Sterilization, Ethylene Oxide, Hydrogen Peroxide Plasma, Radiation, Ultraviolet Light Application: Minimally Invasive Surgery, Diagnostic Procedures, Hemodialysis, Respiratory Therapy, Wound Care End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialized Clinics, Long-Term Care Facilities |
| Companies Covered | Medline Industries, SureTek Medical, Stryker Corporation, NEScientific, Arjo Group, Johnson & Johnson, Innovative Health, Cardinal Health, Vanguard AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single-Use Medical Device Reprocessing Market Shifts & Advancements
Reprocessing technology is converging with digital traceability systems that track individual devices through multiple use cycles, creating audit-ready documentation chains that satisfy both internal quality protocols and external regulatory scrutiny.
Radio-frequency identification tagging is unifying device-level tracking with hospital inventory management systems. Cardiac catheterization labs in integrated delivery networks are deploying RFID-enabled collection containers that automatically log device returns. This unifying infrastructure is compressing reconciliation cycles from weeks to hours while reducing loss rates for high-value electrophysiology instruments.
Japan's PMDA has tightened in-country performance testing protocols for reprocessed devices entering its market. The regulator now requires localized sterilization validation studies that duplicate FDA submissions rather than accepting foreign data packages. Electrophysiology catheter reprocessors targeting Japanese electrophysiology departments must establish domestic testing partnerships or captive facilities to maintain market access.
Consolidated procurement functions within United States hospital systems are displacing department-level purchasing autonomy. Materials management executives now negotiate enterprise-wide reprocessing contracts that standardize vendor selection across cardiology, gastroenterology, and urology service lines. This concentration is most visible in the Southeast and Midwest regions where regional health systems have absorbed independent community hospitals.
Global Single-Use Medical Device Reprocessing Market Segmentation
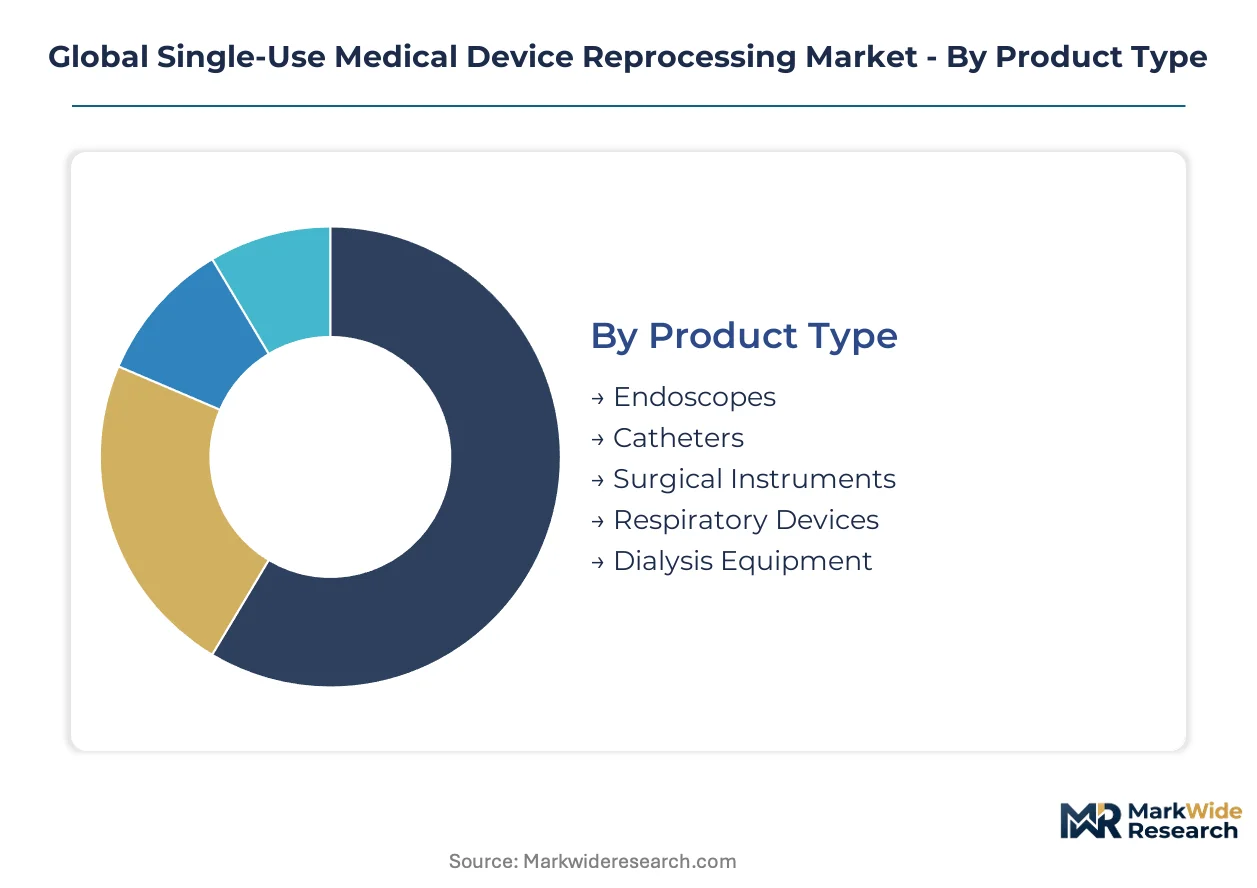
Device reprocessing economics vary sharply across clinical applications and sterilization modalities. Procurement managers prioritize segments with established validation pathways and highest original equipment replacement costs.
Product Type:
Hospital systems differentiate procurement strategies based on device complexity and FDA clearance history for reprocessed alternatives.
- Endoscopes:Flexible gastrointestinal and bronchoscopy instruments require specialized cleaning brushes and channel flow validation. Demand clusters in United States integrated delivery networks seeking to offset per-procedure costs amid Medicare reimbursement compression for colonoscopy and EGD services.
- Catheters:Electrophysiology and cardiovascular catheter reprocessing commands premium pricing through dedicated service-level agreements. Cardiac catheterization labs in Germany and Japan contract for validated functional testing that preserves electrical signal integrity across polymer substrates.
- Surgical Instruments:Metallic graspers and trocars suit steam sterilization with lower reprocessing complexity.
- Respiratory Devices:Ventilator circuits and nebulizers face bioburden challenges from mucosal contamination.
- Dialysis Equipment:Bloodline sets and dialyzers require specialized endotoxin testing protocols.
Catheters lead volumes today; endoscopes are gaining share fastest.
Technology:
Sterilization modality selection hinges on device material thermal tolerance and cycle throughput requirements.
- Hydrogen Peroxide Plasma:Low-temperature sterilization enables reprocessing of heat-sensitive polymer devices previously excluded from programs. United States ambulatory surgery centers deploy plasma systems for flexible endoscope terminals where ethylene oxide siting restrictions apply.
- Ethylene Oxide:Deep polymer penetration capabilities sustain dominance for long-lumen catheters and complex instrument assemblies. EPA emission regulations in California and Texas are restricting new facility permits and forcing abatement technology upgrades.
- Steam Sterilization:Metallic instrument reprocessing dominates simpler surgical tools with established 10^-6 sterility assurance levels.
- Radiation:Gamma and electron beam applications concentrate in industrial-scale reprocessing facilities.
- Ultraviolet Light:Surface disinfection applications expand for non-critical device categories.
Ethylene oxide leads volumes today; hydrogen peroxide plasma is climbing the fastest.
Application:
Clinical procedure volume and reimbursement rates determine reprocessing program prioritization across service lines.
- Minimally Invasive Surgery:Laparoscopic and arthroscopic instrument reprocessing achieves highest utilization rates through standardized tray configurations. United States hospital systems in the Southeast region consolidate procurement across absorbed community hospitals to capture volume discounts.
- Diagnostic Procedures:Endoscopy and cardiac catheterization drive recurring reprocessing demand with predictable case volumes. Japanese electrophysiology departments require PMDA-compliant in-country validation studies for reprocessed catheter alternatives.
- Hemodialysis:Chronic treatment schedules create steady device consumption patterns.
- Respiratory Therapy:Critical care utilization fluctuates with seasonal respiratory illness patterns.
- Wound Care:Negative pressure therapy devices present emerging reprocessing opportunities.
Minimally invasive surgery leads volumes today; diagnostic procedures show the steepest expansion trajectory.
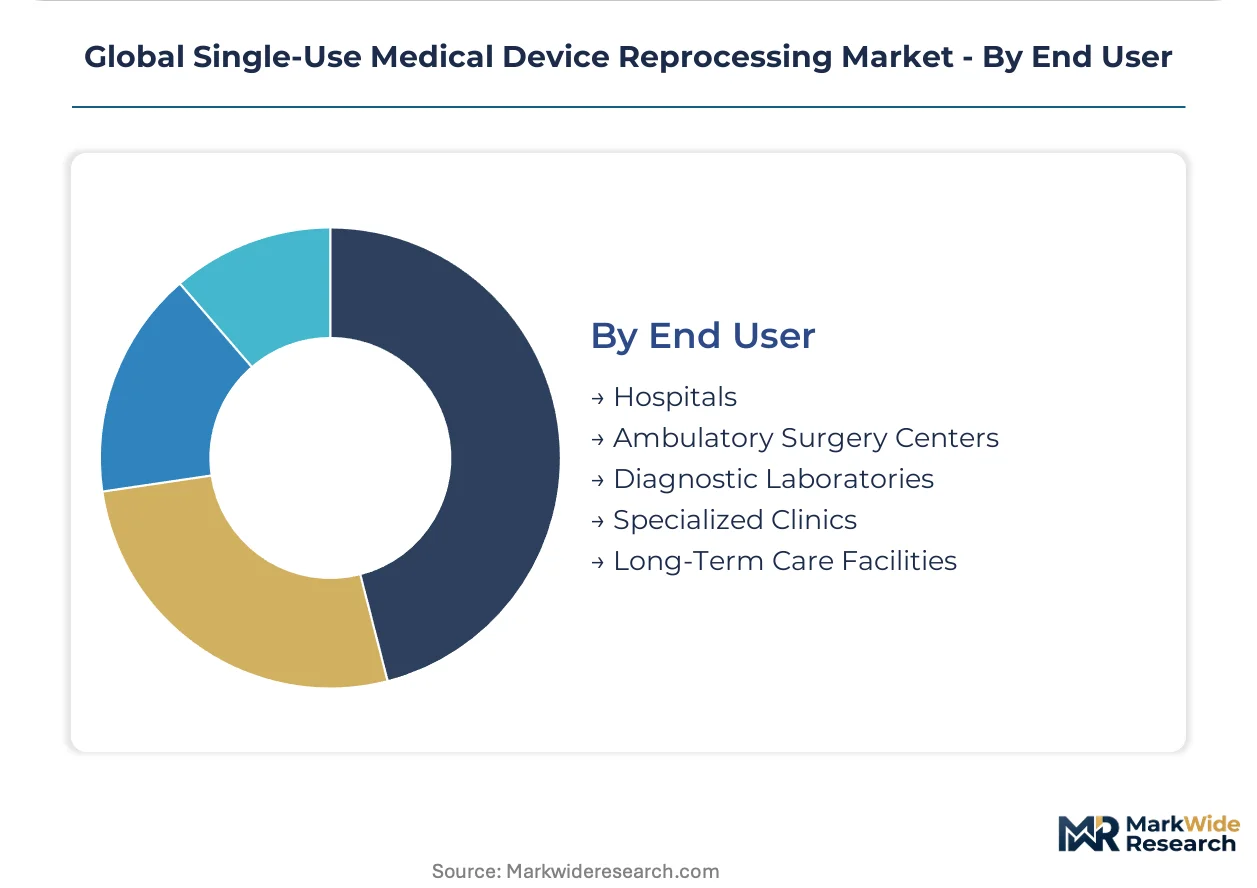
End User:
Facility scale and case complexity shape reprocessing infrastructure investment and vendor contract structures.
- Hospitals:Integrated delivery networks negotiate centralized multi-year contracts covering cardiology, gastroenterology, and urology service lines. Medline Industries and Stryker Corporation compete for enterprise-wide agreements with national logistics infrastructure requirements.
- Ambulatory Surgery Centers:Freestanding facilities prioritize compact sterilization systems with rapid cycle turnaround. Hydrogen peroxide plasma installations bypass ethylene oxide regulatory burdens in United States metropolitan markets.
- Diagnostic Laboratories:Specimen collection device reprocessing remains limited by contamination risk protocols.
- Specialized Clinics:Dialysis centers and cardiac catheterization labs concentrate high-value device categories.
- Long-Term Care Facilities:Respiratory device reprocessing expands with ventilator-dependent patient populations.
Hospitals lead volumes today; ambulatory surgery centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microbiology technicians and materials scientists cluster in the United States, Germany, and Japan, anchoring the three dominant regulatory jurisdictions for validated reprocessing protocols.
United States
Integrated delivery networks in the Southeast and Midwest consolidate procurement across absorbed community hospitals, driving centralized reprocessing contracts at scale. The FDA's evolving 510(k) substantial equivalence standards extend clearance timelines for reprocessed catheters and endoscopes. Greater Boston hosts validation laboratories serving electrophysiology catheter reprocessors with sterility assurance testing.
Germany
Hospital systems prioritize EU MDR-compliant reprocessed alternatives as stricter clinical evidence requirements extend replacement cycles for new device approvals. The country's national pharmaceutical regulator enforces post-market surveillance obligations that reshape quality assurance protocols. The Baden-Württemberg industrial corridor concentrates specialized polymer suppliers for catheter manufacturing inputs.
Japan
PMDA's tightened in-country performance testing protocols demand localized sterilization validation studies rather than foreign data acceptance. Electrophysiology departments in Tokyo and Osaka require domestic testing partnerships for reprocessed catheter market access. The Kanto region anchors captive validation facilities serving multinational reprocessing service providers.
United Kingdom
NHS procurement consolidation favors vendors with validated sterilization infrastructure across multiple device categories amid reimbursement compression. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR clinical evaluation requirements post-Brexit transition. London and the Southeast concentrate hospital system headquarters negotiating enterprise-wide reprocessing agreements.
Canada
Health Canada maintains parallel approval tracks for reprocessed devices that reference FDA 510(k) clearances with supplementary domestic documentation. Provincial health authorities in Ontario and Quebec consolidate reprocessing procurement for cardiac catheterization and endoscopy services. The Toronto-Waterloo corridor hosts validation partnerships serving US-based reprocessors seeking northward expansion.
Global Single-Use Medical Device Reprocessing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates among scale operators with multi-category validation capabilities. Hospital procurement consolidation favors vendors with national logistics infrastructure and established FDA clearance histories. Three archetypes dominate: diversified medical supply distributors, device manufacturers with captive reprocessing divisions, and narrow-focus catheter specialists. Competitive moves center on multi-year contract lock-ins with integrated delivery networks and geographic expansion through localized sterilization partnerships.
Within the diversified distribution tier, Medline Industries and Cardinal Health occupy positions anchored by enterprise-wide procurement relationships with multi-hospital systems. Stryker Corporation exemplifies the device-manufacturer-with-captive-reprocessing archetype, leveraging proprietary tracking systems to secure recurring volumes. Innovative Health sits within the narrow-specialist tier, concentrating exclusively on electrophysiology catheter reprocessing to capture premium pricing through dedicated service-level agreements.
| Leading Market Players |
|---|
| Medline Industries |
| SureTek Medical |
| Stryker Corporation |
| NEScientific |
| Arjo Group |
| Johnson & Johnson |
| Innovative Health |
| Cardinal Health |
| Vanguard AG |
| Others |
Supply & Pricing Matrix
Integrated delivery network procurement consolidation in the United States is forcing reprocessing service providers to absorb cost compression while maintaining FDA-validated sterility assurance protocols, compressing margins and driving selective capacity investments near hospital system clusters.
Pricing Analysis
Capacity additions in the United States and Germany are reshaping price floors for validated catheter reprocessing as hydrogen peroxide plasma sterilization infrastructure expands. Contract-based long-term offtake agreements dominate, with price differentiation anchored in FDA 510(k) clearance tier and volume scale across multi-hospital networks. Cost compression in standard-tier reprocessing is intensifying because Medicare DRG reimbursement compression limits pass-through pricing. Ambulatory surgery centers exhibit highest price sensitivity; electrophysiology labs demonstrate lowest sensitivity due to dedicated service-level agreement premiums.
Supply Chain Analysis
FDA 510(k) clearance and EU MDR CE marking requirements gate supply participation, concentrating validated reprocessing capacity among operators with multi-jurisdiction quality management systems. Manufacturing inputs cluster in Germany, the United States, and Japan for specialized medical-grade polymers, stainless-steel instrument substrates, and ethylene oxide sterilization equipment. Raw material dependencies center on polyurethane catheter materials, hydrogen peroxide sterilant formulations, and sterilization packaging films. Single-source vulnerability concentrates in German polymer suppliers serving catheter reprocessors. Distribution runs through hospital system central sterile supply departments and third-party logistics networks serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use medical device reprocessing functions as a margin-expansion story where Medicare reimbursement compression creates permanent demand for cost-down alternatives, while electrophysiology catheter specialization unlocks premium-tier pricing power.
For Market Incumbents: Anticipate regulatory divergence between FDA predicate device policies and EU MDR clinical evaluation requirements by securing parallel validation capabilities in both jurisdictions. Defensive positioning demands backward integration into polymer supply relationships and captive sterilization capacity additions in the Southeast United States to lock in integrated delivery network contracts. Hydrogen peroxide plasma technology investments represent the priority capability lever against ethylene oxide siting restrictions. For New Entrants and Emerging Players: Capture white-space opportunity in Japanese electrophysiology catheter reprocessing by establishing PMDA-compliant in-country testing partnerships before multinational incumbents localize. The ambulatory surgery center segment offers the most penetrable entry point given compact sterilization system demand and bypass of ethylene oxide regulatory burdens. A direct hospital system contracting approach with RFID-enabled device tracking integration accelerates credibility building. For Investors and Strategic Acquirers: Asymmetric upside sits with narrow-focus catheter specialists possessing dedicated electrophysiology lab relationships and proprietary functional testing protocols. Long-term viability hinges on regulatory moat durability across FDA, EU MDR, and PMDA jurisdictions rather than pure scale economics. Watch for hydrogen peroxide plasma sterilization technology maturation as inflection indicator for heat-sensitive polymer device category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance unlocks commercial contracts with Medicare-reimbursed hospital systems. |
| CE Marking Pathway | EU MDR compliance enables access to German hospital procurement consolidations. |
| Hospital System Partnership | Multi-year agreements with integrated delivery networks secure recurring reprocessing volumes. |
| Software Companion Development | RFID-enabled device tracking satisfies FDA traceability requirements and reduces loss rates. |
| Reimbursement Strategy | Alignment with Medicare DRG compression trends positions reprocessed alternatives as cost-standard. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement executives, biomedical engineering directors, GPO contracts managers, and reprocessing service provider operations leads with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement contract registries, and EU MDR notified body certification records. Bottom-up device-level volume modeling and top-down market sizing triangulated across sterilization modality capacity estimates and hospital system contract disclosure patterns.
Historical reference periods anchored the forecast window through validated reprocessing program adoption curves and catheter replacement cycle analysis. Segmentation dimensions spanned product type complexity tier, sterilization technology thermal tolerance class, clinical application procedure volume, and end-user facility scale. CAGRs derived from procedure growth trajectories, reimbursement compression elasticity estimates, and regulatory approval timeline patterns across FDA, EU MDR, and PMDA jurisdictions.
Regulatory clearance delays, polymer supply disruptions, and hospital system merger integration failures are the dominant revision risks to modeled adoption trajectories. Forecasts reflect documented assumptions regarding sterility assurance protocol acceptance and integrated delivery network procurement centralization momentum. A model refresh is warranted upon material change in FDA substantial equivalence demonstration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ Care Market
Medical Devices
Hearing Loop Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Casting Devices Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
MRI Coils Market
Medical Devices
Dermal Allograft Market
Medical Devices
Medical Face Shield Market
Medical Devices
Europe Sternal Closure Systems Market