
 Global Over-The-Wire Micro-Guide Catheter Market | 2026-2036
Global Over-The-Wire Micro-Guide Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Over-The-Wire Micro-Guide Catheter Market Foresight
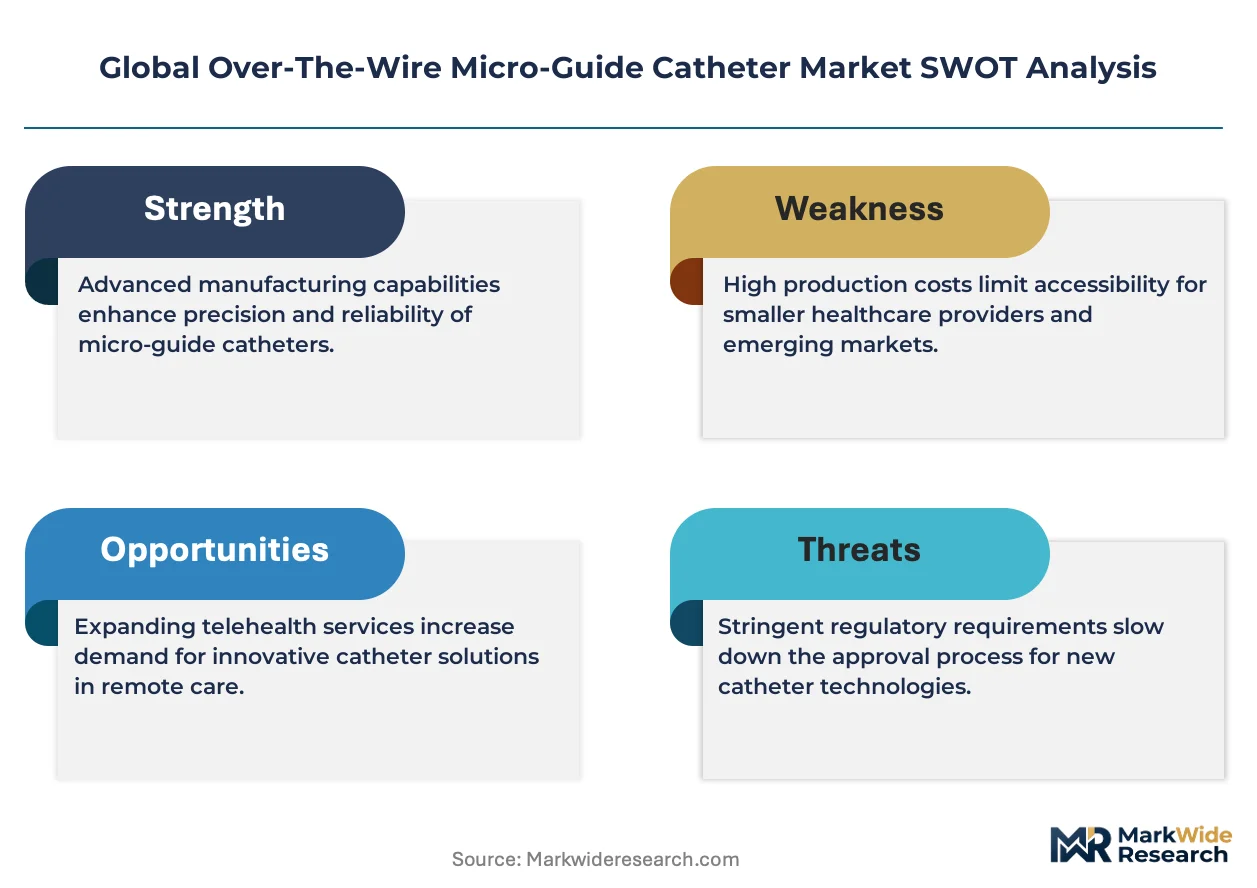
EU MDR is broadening the cost-of-entry calculus for micro-guide catheter manufacturers seeking European market access. Boston Scientific Corporation leverages its vertically integrated manufacturing footprint to sustain compliance economies across multiple regulatory jurisdictions. Medtronic anchors its competitive position through deep specialization in torque-controlled delivery architectures. Terumo Corporation navigigates Japan's PMDA framework while extending its hydrophilic coating expertise into European and North American channels.
Over-the-wire micro-guide catheters are slender, torque-responsive delivery devices typically constructed from braided stainless steel or nitinol-reinforced polymer shafts with distal radiopaque markers, designed to traverse tortuous vasculature and enable precise placement of guidewires, stents, or embolic agents during minimally invasive procedures. Hydrophilic coated variants command premium positioning due to reduced friction coefficients in complex anatomical navigation, while cardiovascular interventions represent the dominant application segment with established reimbursement pathways. Neurovascular procedures represent the fastest-growing application area as stroke intervention protocols expand across tertiary care networks. Single-lumen configurations remain the volume backbone, though multi-lumen designs are gaining traction in hybrid therapeutic procedures requiring simultaneous device delivery.
FDA 510(k) clearance requirements, EU MDR technical documentation mandates, and Japan PMDA quality management system inspections collectively shape product development timelines, clinical evidence thresholds, and post-market surveillance obligations for manufacturers. ISO 13485 certification serves as the foundational quality management predicate across all three jurisdictions, with notified body capacity constraints in Europe creating extended review queues. Stakeholders must monitor regulatory divergence between FDA's evolving predicate device policies and EU MDR's stricter clinical evaluation requirements, as this friction will determine which product portfolios achieve synchronized multi-regional launches versus sequential market entry patterns.
Market Dynamics
EU MDR technical documentation mandates and FDA 510(k) predicate device policy divergence are compressing product development timelines while forcing manufacturers to maintain parallel regulatory workstreams across jurisdictions.
Growth Catalysts
- Japan PMDA quality management inspections:Accelerated approval pathways for hydrophilic-coated delivery systems are expanding catheter adoption in Tokyo and Osaka cardiovascular intervention networks.
- Stroke intervention protocol expansion:Tertiary care networks across Germany and the United States are building dedicated neurovascular suites requiring specialized micro-guide catheter inventories.
- Nitinol-reinforced polymer shaft technology:Enhanced torque responsiveness is enabling navigation through increasingly tortuous peripheral vasculature previously deemed inaccessible.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply chains concentrate in limited foundry operations, exposing manufacturers to input volatility and long-lead procurement cycles.
- EU MDR notified body capacity constraints:Extended review queues in European technical documentation assessment are delaying market entry for new catheter variants by 12-18 months.
- Reusable catheter reprocessing systems:Cost-conscious hospital systems in select markets are extending device lifecycle through third-party reprocessing, compressing replacement demand for single-use units.
Strategic Opportunities
- Multi-lumen hybrid therapeutic designs:Simultaneous guidewire and embolic agent delivery is opening procedural applications in complex cardiac interventions previously requiring sequential catheter exchanges.
- India's CDSCO medical device registration pathway:Streamlined import licensing for Class C cardiovascular devices is creating first-mover positioning for hydrophilic-coated catheter portfolios.
- ISO 13485:2016 quality management convergence:Unified certification standards across FDA, PMDA, and EU MDR jurisdictions are enabling synchronized multi-regional product launches from single manufacturing footprints.
Industry Challenges
- Polymer extrusion process engineering talent:Specialized expertise in braided shaft manufacturing with consistent wall thickness tolerances remains concentrated among veteran technicians approaching retirement.
- Distal radiopaque marker integration:Sub-millimeter precision placement of platinum-iridium bands during automated assembly requires capital-intensive vision systems and validation protocols.
- Legacy guidewire compatibility certification:Ensuring torque transmission fidelity across third-party wire portfolios demands extensive bench testing and clinical correlation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Over-The-Wire Micro-Guide Catheter Market |
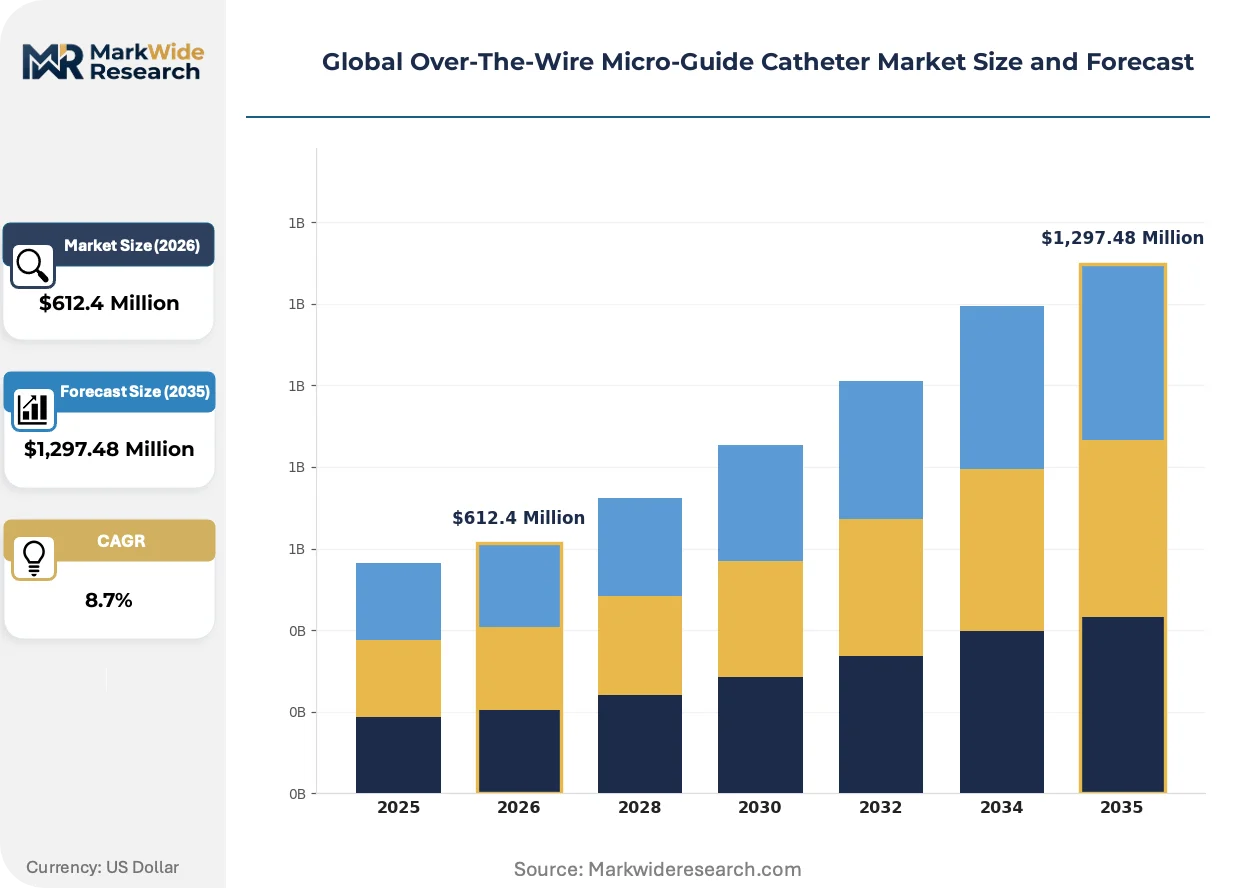
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic Coated, Non-Coated, Multi-Lumen, Single-Lumen, Torque Control Application: Cardiovascular Interventions, Neurovascular Procedures, Peripheral Vascular Access, Urology, Gastroenterology End User: Cardiac Cath Labs, Neuro Intervention Centers, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories Deployment Mode: Disposable, Reusable, Sterile Packed, Non-Sterile Packed, Preloaded |
| Companies Covered | Boston Scientific Corporation, Medtronic, Merit Medical Systems, Terumo Corporation, Cardinal Health, Penumbra, Stryker, Asahi Intecc, Lumend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Over-The-Wire Micro-Guide Catheter Market Shifts & Advancements
Material science advances and regulatory pathway fragmentation are simultaneously expanding procedural capabilities and complicating commercialization timelines for catheter manufacturers.
Electrospun nanofiber surface coatings are reducing friction coefficients in tortuous anatomical navigation without compromising structural integrity. Cardiac catheterization laboratories in Germany and Japan are adopting these variants for chronic total occlusion procedures. This surface engineering is electrifying competitive differentiation as premium positioning shifts from coating durability to navigational precision metrics.
EU MDR's stricter clinical evaluation requirements are diverging from FDA's evolving predicate device policies for 510(k) submissions. Manufacturers now face asynchronous evidence generation demands, with European notified bodies requiring prospective clinical data where U.S. pathways still accept substantial equivalence arguments. Neurovascular application segments bear the heaviest documentation burden as MDR classifies these devices at higher risk tiers.
Hospital procurement departments are consolidating catheter purchasing through integrated delivery networks and group purchasing organizations. Independent cardiac catheterization suites are losing direct supplier relationships as distribution channels compress toward centralized contracting. This concentration is most pronounced across United States metropolitan hospital systems where IDN penetration exceeds seventy percent of cardiovascular device spending.
Global Over-The-Wire Micro-Guide Catheter Market Segmentation
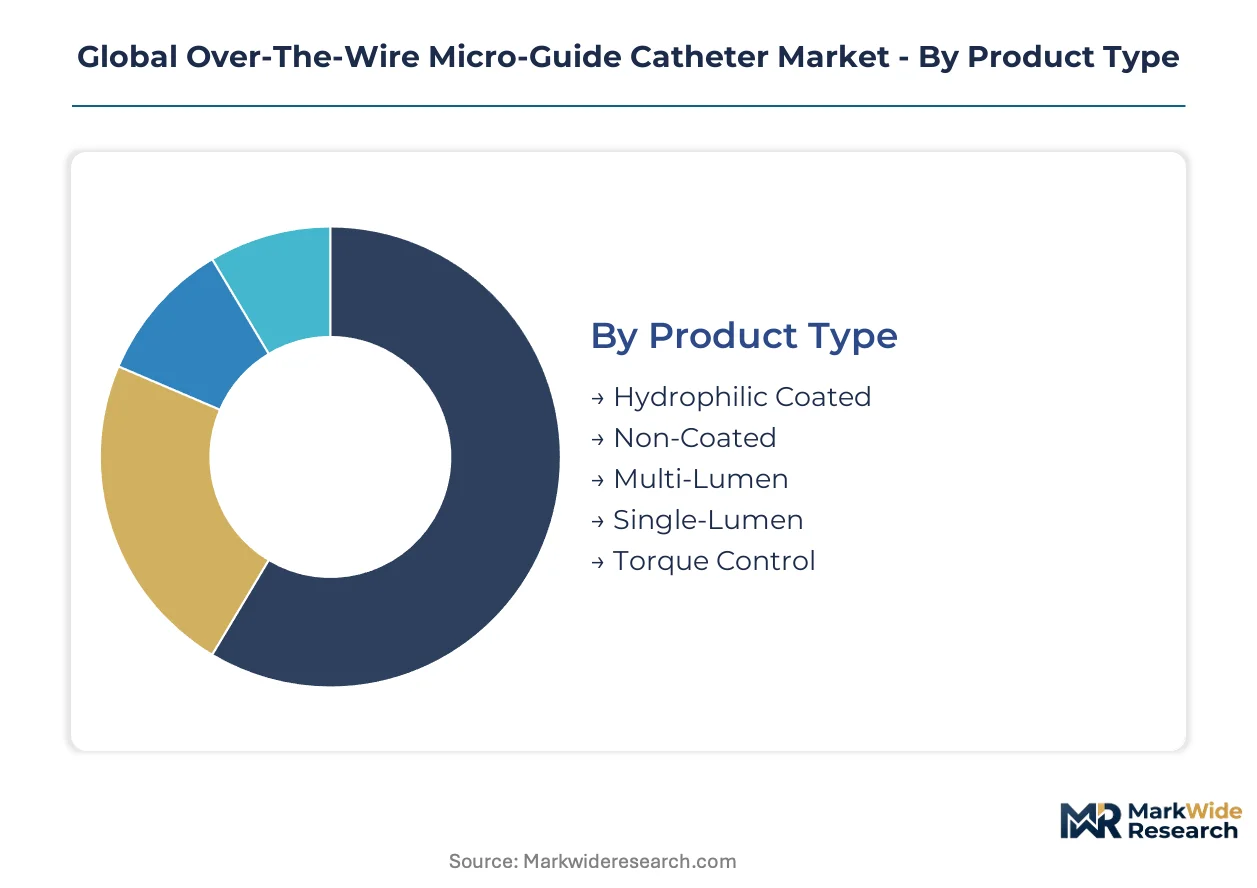
Over-the-wire micro-guide catheter purchasing patterns diverge sharply across clinical settings and procedural complexity tiers. Product specifications, coating technologies, and sterility requirements map directly to reimbursement pathways and capital equipment constraints in target facilities.
Product Type:
Cost tier and procedural complexity separate buyers in this category, with premium hydrophilic systems commanding dedicated procurement budgets.
- Hydrophilic Coated:Polyvinylpyrrolidone or polyethylene oxide surface layers reduce friction coefficients for tortuous vascular navigation. Tokyo and Osaka cardiovascular networks specify these variants for chronic total occlusion procedures, with PMDA accelerated pathways reinforcing hospital preference.
- Torque Control:Braided stainless steel or nitinol-reinforced shafts deliver rotational fidelity for guidewire manipulation in complex anatomies. German interventional cardiology suites prioritize these architectures for precision stent delivery, driven by EU MDR documentation requirements favoring established torque-responsive designs.
- Non-Coated:Standard polymer constructions serve cost-sensitive procurement channels without hydrophilic surface treatment.
- Multi-Lumen:Parallel lumens enable simultaneous device delivery in hybrid therapeutic interventions.
- Single-Lumen:Conventional single-channel designs remain the procedural workhorse across high-volume catheterization networks.
Volume sits with single-lumen configurations; growth tilts toward hydrophilic coated variants.
Application:
Reimbursement maturity and protocol expansion rates create divergent demand profiles across clinical specialties.
- Cardiovascular Interventions:Established CPT and DRG reimbursement codes support catheter utilization in coronary and structural heart procedures. United States cardiac catheterization networks maintain dedicated inventory for diagnostic angiography and percutaneous coronary intervention, with hydrophilic systems penetrating chronic total occlusion sub-specialties.
- Neurovascular Procedures:Mechanical thrombectomy protocol expansion across tertiary care networks drives specialized micro-guide catheter demand. German stroke centers and United States comprehensive stroke centers are building dedicated neurointerventional suites, with EU MDR higher risk tier classifications elevating clinical evidence requirements for new entrants.
- Peripheral Vascular Access:Below-the-knee and femoropopliteal interventions utilize smaller-diameter catheter platforms.
- Urology:Endourological procedures employ modified catheter geometries for renal access applications.
- Gastroenterology:Biliary and pancreatic interventions represent a niche deployment channel with specialized tip configurations.
Cardiovascular interventions anchor current procurement volumes; neurovascular procedures are climbing the fastest.
End User:
Capital equipment intensity and case throughput determine catheter specification and contract structure.
- Cardiac Cath Labs:Hospital-based and freestanding facilities with fixed angiography systems drive bulk purchasing through integrated delivery networks. United States metropolitan hospital systems concentrate over seventy percent of cardiovascular device spending through centralized IDN contracts, compressing direct supplier relationships.
- Neuro Intervention Centers:Tertiary referral hubs with biplane fluoroscopy require specialized inventory for stroke and aneurysm interventions. Japan's designated stroke centers and Germany's comprehensive stroke networks are expanding dedicated neurovascular suite construction.
- Ambulatory Surgical Centers:Lower-acuity settings with streamlined procedure mixes favor disposable preloaded configurations.
- Specialty Clinics:Office-based labs with limited fluoroscopy utilize smaller catheter formats for diagnostic applications.
- Diagnostic Laboratories:Non-interventional imaging centers require basic guidewire delivery capabilities without therapeutic features.
Cardiac cath labs dominate installed base; neuro intervention centers represent the steepest expansion trajectory.
Deployment Mode:
Sterility assurance level and reprocessing economics shape procurement decisions across facility types.
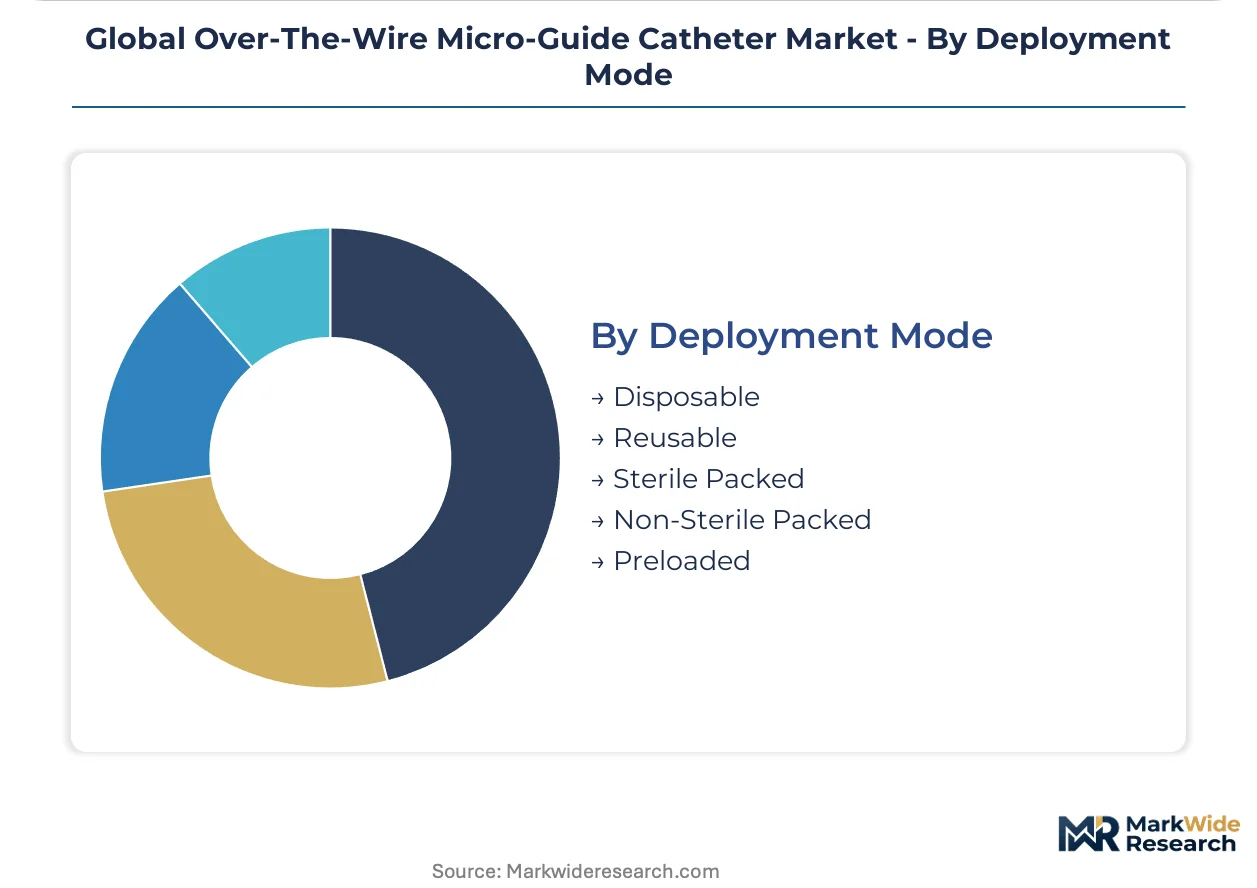
- Disposable:Single-use configurations eliminate reprocessing liability and align with FDA 510(k) cleared sterilization validations. United States hospital systems facing Joint Commission scrutiny favor disposable units to reduce infection control documentation burdens.
- Sterile Packed:Gamma or ethylene oxide terminal sterilization supports immediate use in operating room and catheterization lab environments. EU MDR technical documentation mandates for sterile medical devices are extending validation timelines for manufacturers seeking European market access.
- Reusable:Third-party reprocessing systems extend device lifecycle in cost-conscious hospital systems, compressing replacement demand.
- Non-Sterile Packed:Bulk non-sterile configurations require facility-level sterilization before deployment.
- Preloaded:Factory-integrated guidewire systems reduce procedural preparation time in high-throughput settings.
Disposable units command current volume; sterile packed configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's medical device parks in Gujarat and Karnataka are concentrating catheter manufacturing investments through tax abatements and streamlined customs processing.
United States
Integrated delivery networks in metropolitan hospital systems concentrate over seventy percent of cardiovascular device procurement through centralized contracting. FDA 510(k) predicate device policies sustain faster clearance timelines for torque-responsive catheter designs compared to European pathways. The Texas Medical Center in Houston and Cleveland Clinic cardiovascular networks maintain dedicated inventory for chronic total occlusion procedures.
Germany
Comprehensive stroke centers in Bavaria and North Rhine-Westphalia are expanding dedicated neurointerventional suite construction. EU MDR notified body capacity constraints extend technical documentation review timelines by twelve to eighteen months for new catheter variants. The Mannheim and Heidelberg university hospital clusters anchor interventional cardiology training networks that standardize hydrophilic-coated system specifications.
Japan
Designated stroke centers in Tokyo and Osaka are accelerating PMDA quality management inspections for hydrophilic-coated delivery systems. METI medical device industry support programs subsidize domestic manufacturing automation for nitinol-reinforced shaft production. The Kobe biomedical device cluster houses specialized polymer extrusion facilities serving catheter OEMs.
India
CDSCO streamlined import licensing for Class C cardiovascular devices is attracting first-mover catheter portfolios into Delhi-NCR and Mumbai hospital networks. Andhra Pradesh and Telangana medical device parks offer ten-year tax holidays for catheter assembly operations. Hyderabad's pharmaceutical manufacturing ecosystem is extending into cardiovascular device contract sterilization services.
Switzerland
Swissmedic's alignment with EU MDR technical documentation standards enables synchronized European market access from Lake Geneva manufacturing zones. Precision polymer processing expertise in the Jura Arc supports sub-millimeter catheter shaft tolerances for neurovascular applications. The Zurich cardiovascular research corridor connects university hospitals with catheter prototyping facilities.
Global Over-The-Wire Micro-Guide Catheter Market Competitive Landscape
United States producers anchor the premium-tier segment through integrated delivery network contracting power; Japanese specialists hold differentiated positioning in hydrophilic coating architectures. The vendor base concentrates among diversified cardiovascular device conglomerates and focused catheter engineering houses. Three archetypes dominate: diversified medtech conglomerates with catheter divisions, specialized interventional access manufacturers, and Asian precision component suppliers. Competitive moves center on backward integration into nitinol foundry relationships and sterile packaging capacity expansion.
Among diversified medtech conglomerates, Boston Scientific Corporation and Medtronic exemplify the integrated manufacturing archetype, while Terumo Corporation occupies a distinct position bridging Japanese domestic market density with European and North American regulatory navigation. These three entities represent contrasting geographic centers of gravity—Massachusetts-based, Minnesota-based, and Tokyo-based respectively—each sitting within different quality management system inspection frameworks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Merit Medical Systems |
| Terumo Corporation |
| Cardinal Health |
| Penumbra |
| Stryker |
| Asahi Intecc |
| Lumend |
| Others |
Supply & Pricing Matrix
Polymer extrusion process engineering talent concentrated in Japan's Kobe biomedical device cluster and Switzerland's Jura Arc feeds labor-cost differentials that separate premium hydrophilic-coated catheter pricing from standard non-coated tiers.
Pricing Analysis
Short-lead-time premiums for nitinol-reinforced shafts command price escalation against spot inventory discounts for single-lumen configurations nearing expiration. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating technology and torque responsiveness certification. Pricing pressure stems from third-party reprocessing systems extending device lifecycle in cost-conscious United States hospital systems. Ambulatory surgical centers exhibit highest price sensitivity; comprehensive stroke centers in Germany and Japan show lowest sensitivity due to dedicated neurovascular procurement budgets.
Supply Chain Analysis
Nitinol superelastic alloy supply rests on limited foundry operations in Japan, Germany, and the United States. Braided stainless steel wire, platinum-iridium radiopaque marker bands, and hydrophilic polymer coatings constitute critical component dependencies. Single-source vulnerability concentrates in Japanese specialty nitinol producers exposed to METI export licensing protocols. Distribution runs through integrated delivery networks and group purchasing organizations compressing direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over nitinol foundry relationships and sterile packaging capacity determines margin sustainability against reprocessing competition.
For Market Incumbents: Extend backward integration into nitinol alloy supply through long-term offtake agreements with Japanese or German foundries. Secure dedicated sterile packaging capacity ahead of EU MDR validation queue expansion. Reprocessing system penetration in United States IDNs threatens replacement demand for single-use units; counter with disposable preloaded configurations reducing procedural preparation time. For New Entrants and Emerging Players: Begin with India's CDSCO streamlined Class C import licensing pathway for hydrophilic-coated portfolios entering Delhi-NCR and Mumbai hospital networks. Target neurovascular application segments in German comprehensive stroke centers where EU MDR higher risk tier classifications elevate clinical evidence barriers for established competitors. Partner with Hyderabad contract sterilization providers to bypass capital-intensive packaging infrastructure. For Investors and Strategic Acquirers: The window for entry favors specialized catheter engineering houses with ISO 13485:2016 certification spanning FDA, PMDA, and EU MDR jurisdictions. Long-term viability hinges on synchronized multi-regional launch capability from single manufacturing footprints. Watch PMDA accelerated approval pathway expansions for hydrophilic-coated systems as inflection signal for Japanese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitinol Supply | Captive alloy sourcing insulates against foundry concentration risk in Japan and Germany. |
| CE Marking Pathway Investment | EU MDR technical documentation capacity secures European market entry ahead of notified body queue delays. |
| Hospital System Partnership | Direct relationships with Texas Medical Center and Cleveland Clinic networks bypass IDN contracting compression. |
| Software Companion Development | Torque feedback integration with fluoroscopy systems differentiates precision navigation offerings. |
| Reimbursement Strategy | Mechanical thrombectomy CPT code alignment drives neurovascular catheter procurement in United States stroke centers. |
Research Methodology
FDA 510(k) clearance databases, EU MDR technical documentation filings, and PMDA quality management inspection records formed the secondary backbone. Primary interviews with interventional cardiologists, neurovascular surgeons, hospital purchasing committee members, and GPO contracts managers validated procedural adoption patterns and procurement decision frameworks. Bottom-up catheter shipment estimates triangulated against top-down cardiovascular intervention procedure volumes across the analysis window.
Historical trendline analysis of hydrophilic-coated versus non-coated product mix informed segmentation-level growth trajectories. Modeling incorporated product type, application specialty, end-user facility tier, and deployment mode sterility requirements as core dimensions. CAGR derivation weighted regulatory pathway divergence between FDA predicate policies and EU MDR clinical evaluation mandates. Forecast inputs included nitinol raw material lead time fluctuations and notified body capacity utilization rates.
Underlying measurement precision varies by segment; cardiovascular intervention volumes carry tighter precision than emerging neurovascular application estimates. Forecasts reflect assumptions regarding PMDA accelerated pathway continuity and EU MDR notified body queue resolution. Regulatory divergence, reimbursement code revisions, and reprocessing system adoption rates constitute primary forecast revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Elderly and Disabled Assistive Devices Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Patellar Implant Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Mechanical Thrombectomy Devices Market