
 Spinal Machined Bone Allograft Market | 2026-2036
Spinal Machined Bone Allograft Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Machined Bone Allograft Market Analytics
The FDA's updated tissue guidance is rebalancing the cost-of-entry calculus for new allograft processors, requiring enhanced donor screening and validated sterilization documentation. Medtronic leverages its vertically integrated tissue supply chain to sustain margin advantages across hospital accounts. LifeNet Health anchors its position through proprietary processing technologies that differentiate output quality. MTF Biologics competes via nonprofit tissue banking relationships that control access to donor networks.
Spinal machined bone allograft comprises precisely milled human bone tissue, typically shaped into strips, dowels, or structural spacers with defined cortical thickness and porosity parameters, used to provide osteoconductive scaffolding and mechanical support during spinal fusion. Cancellous allografts lead volume due to their superior osteointegration properties in interbody fusion applications, while composite allografts represent the fastest-expanding category as surgeons seek combined cortical-cancellous constructs that optimize both immediate stability and biological remodeling. Cortical allografts command premium positioning in trauma surgery where load-bearing capacity determines selection, and irradiation sterilization dominates method selection despite ongoing debate over dose thresholds and biomechanical preservation.
The FDA oversees tissue processing standards through 21 CFR Part 1271, while the American Association of Tissue Banks publishes voluntary accreditation benchmarks that shape procurement criteria for hospital value analysis committees. State-level tissue bank licensure requirements, particularly in New York and Florida, add compliance layers that filter processor participation. Stakeholders must monitor evolving sterilization validation requirements and surgeon training program expansion as dual levers that will determine competitive positioning in the next phase of market development.
Market Dynamics
FDA's updated tissue guidance is compressing processor margins while hospital consolidation centralizes procurement power, forcing allograft suppliers to absorb compliance costs or cede accounts to vertically integrated competitors.
Growth Catalysts
- Outpatient surgical migration:Ambulatory surgery centers in the United States are expanding spinal fusion capacity, creating pull-through demand for pre-shaped cortical constructs that reduce operative time.
- 21 CFR Part 1271 harmonization:The FDA's unified tissue framework is standardizing quality documentation, enabling mid-tier processors to compete for integrated delivery network contracts previously locked by incumbent suppliers.
- Demographic compression:Aging populations in Japan and Germany are accelerating degenerative disc disease caseloads, expanding the addressable patient pool for interbody fusion procedures.
Market Restraints
- Donor tissue scarcity:Voluntary donation rates in the United States plateaued, constraining raw material availability and elevating per-unit acquisition costs for independent processors.
- Irradiation dose thresholds:Biomechanical degradation at sterilization levels above 2.5 Mrad limits terminal sterilization adoption, forcing reliance on aseptic processing with higher failure rates.
- Synthetic graft substitution:PEEK and titanium interbody cages from Stryker and Zimmer Biomet are capturing price-sensitive volume in posterior lumbar fusion, compressing allograft share in mechanical applications.
Strategic Opportunities
- Composite construct innovation:Cortical-cancellous hybrid spacers are penetrating cervical fusion, commanding premium positioning through dual-phase remodeling kinetics.
- State tissue bank licensure:New York and Florida's elevated processing standards are creating regulatory moats for compliant processors willing to absorb certification overhead.
- Surgeon training expansion:Cadaveric workshops sponsored by academic medical centers in Texas and California are accelerating technique adoption among community spine surgeons.
Industry Challenges
- Sterilization validation timelines:FDA 510(k) clearance for novel terminal sterilization methods requires 18-24 month validation cycles, delaying product launches and freezing R&D pipelines.
- Donor network fragmentation:Nonprofit tissue banks control 70% of recovered tissue, forcing commercial processors into dependency relationships with uneven supply commitment.
- Biomechanical testing standardization:Absence of unified ASTM protocols for machined allograft compressive strength creates procurement uncertainty and value analysis committee rejection risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Machined Bone Allograft Market |
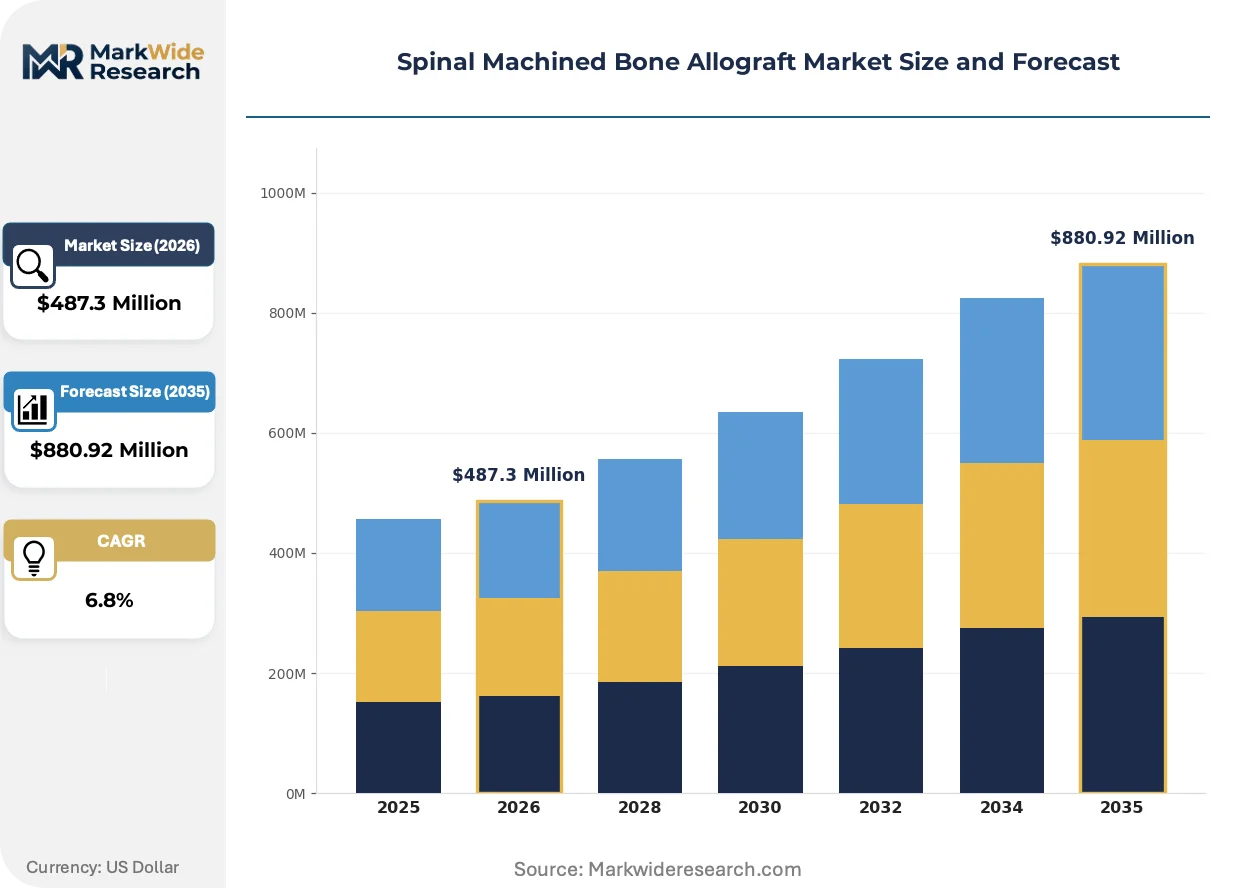
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cancellous Allografts, Cortical Allografts, Combined Allografts, Composite Allografts End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Orthopedic Clinics Application: Spinal Fusion, Trauma Surgery, Revision Surgery, Scoliosis Treatment Sterilization Method: Irradiation, Chemical, Heat, Gas Plasma |
| Companies Covered | Medtronic, DePuy Synthes, Globus Medical, LifeNet Health, MTF Biologics, Stryker, Zimmer Biomet, AlloSource, RTI Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Machined Bone Allograft Market Evolving Landscape
Processing automation and point-of-care customization are converging to reshape how machined allografts move from recovery to implantation, compressing traditional supply chain intermediaries.
Decellularization protocols are advancing rapidly. Aseptic processing suites at LifeNet Health and MTF Biologics are deploying enzymatic detergents that strip cellular material while preserving osteoinductive protein content. Academic medical centers in Massachusetts and North Carolina are piloting these constructs in anterior cervical discectomy. This technology is decentralizing sterilization capacity from centralized irradiation facilities toward processor-controlled cleanrooms.
The FDA's 2023 tissue guidance revision tightens donor screening documentation and mandates electronic batch records. Processors must now validate chain-of-custody systems back to recovery organizations. Small regional banks in the Midwest are consolidating or exiting as compliance costs exceed revenue, concentrating viable supply among multi-state networks with dedicated quality infrastructure.
Hospital value analysis committees are unbundling implant procurement from surgeon preference. Integrated delivery networks in Florida and Texas are standardizing allograft specifications across member hospitals, forcing suppliers into sole-source or dual-source contracts with volume commitments. This compression eliminates discretionary purchasing and rewards processors with validated sterilization documentation and geographic proximity to distribution hubs.
Spinal Machined Bone Allograft Market Segmentation
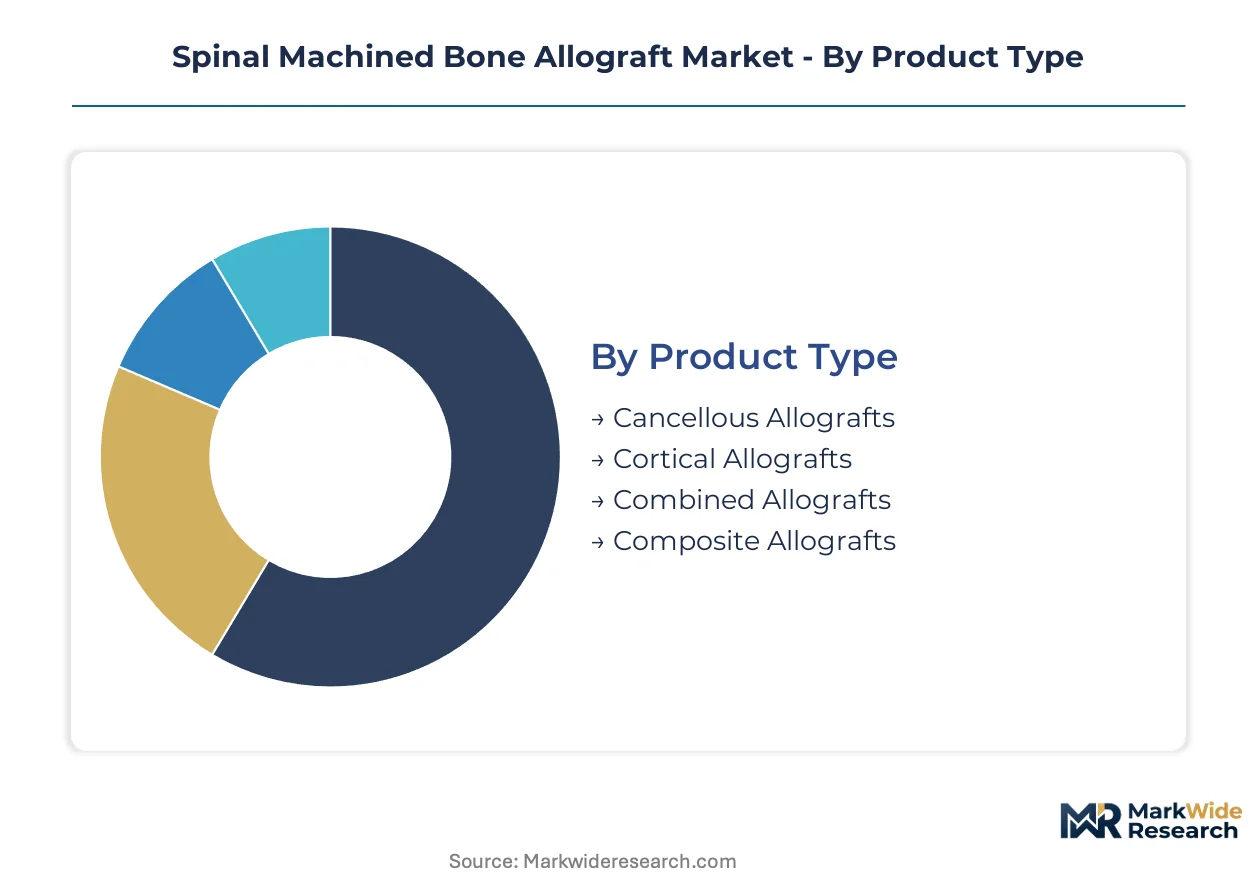
Segmentation in the spinal machined bone allograft market reveals how clinical requirements diverge across surgical settings and sterilization protocols. Procurement committees weight osteointegration speed against mechanical load-bearing capacity differently by procedure type.
Product Type:
Cancellous constructs dominate procedural volume while composite variants capture premium positioning through dual-phase performance.
- Cancellous Allografts:These porous trabecular bone constructs feature interconnected marrow spaces that accelerate vascular infiltration and cellular colonization. Demand concentrates in lumbar interbody fusion procedures at ambulatory surgery centers in Florida and Texas, driven by outpatient migration requiring faster biological incorporation. Mature deployment sits with cancellous allografts. Newer deployment is concentrated in composite allografts.
- Composite Allografts:Engineered cortical-cancellous laminates combine immediate structural rigidity with progressive remodeling kinetics. Surgeons in academic medical centers across California and Massachusetts are adopting these for cervical corpectomy reconstruction where load-bearing and fusion must coexist.
- Cortical Allografts:Dense cortical bone segments provide maximum compressive strength for trauma applications requiring structural continuity.
- Combined Allografts:Intraoperative mixing of cortical and cancellous particulate allows surgeon-customized density gradients.
Mature deployment sits with cancellous allografts. Newer deployment is concentrated in composite allografts.
End User:
Facility reimbursement structures and case complexity determine which settings drive allograft consumption.
- Hospitals:Inpatient spinal fusion programs at integrated delivery networks in the United States manage complex deformity corrections and multi-level constructs. Value analysis committees at these institutions standardize specifications across member facilities, consolidating procurement volume.
- Surgical Centers:Freestanding ambulatory facilities in Texas and Florida perform single-level decompressions with pre-shaped dowels that reduce operative time. Medicare reimbursement shifts favoring same-day discharge are accelerating allograft demand here.
- Orthopedic Clinics:Physician-owned practices coordinate preoperative planning and postoperative monitoring without direct implant procurement.
- Rehabilitation Facilities:Post-acute settings manage recovery protocols but do not select implant materials.
Procurement authority clusters with hospitals. Volume expansion is accelerating in surgical centers.
Application:
Procedure invasiveness and bone defect size create distinct mechanical and biological requirements.
- Spinal Fusion:Interbody, posterolateral, and intertransverse fusion techniques require machined allografts shaped to specific disc space heights and lordotic angles. Degenerative disc disease caseloads in aging populations across Japan and Germany are expanding the addressable pool for these procedures.
- Trauma Surgery:Burst fractures and vertebral body collapse demand load-bearing cortical struts with documented compressive strength. Irradiation dose thresholds above 2.5 Mrad degrade biomechanical properties, constraining sterilization options for these applications.
- Revision Surgery:Pseudarthrosis corrections and implant removals present hostile biological environments with compromised vascularity.
- Scoliosis Treatment:Pediatric and adolescent deformity correction requires long-segment constructs with predictable resorption rates.
Spinal fusion represents the established volume base. Revision surgery is gaining share fastest as prior fusion cohorts age.
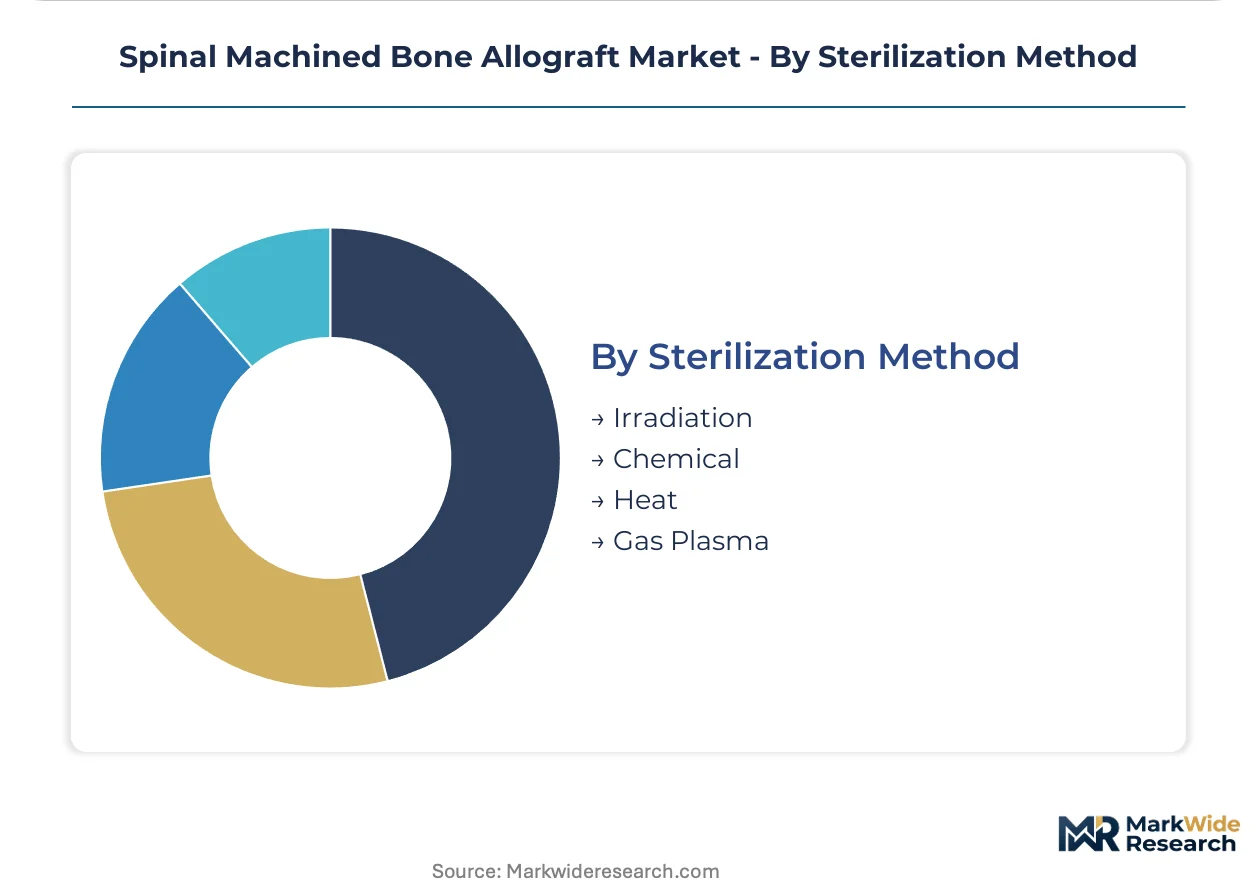
Sterilization Method:
Terminal sterilization choices trade biomechanical preservation against microbial safety assurance.
- Irradiation:Gamma and electron beam sterilization at 1.5-2.5 Mrad doses dominates method selection despite ongoing debate over collagen cross-linking and brittle failure risk. FDA validation requirements for dose mapping extend clearance timelines.
- Chemical:Ethylene oxide and hydrogen peroxide vapor penetrate complex geometries without thermal damage. Aseptic processing suites at major tissue banks deploy these methods for temperature-sensitive protein preservation.
- Heat:Dry and moist heat methods see limited application due to denaturation of osteoinductive factors at sterilization temperatures.
- Gas Plasma:Low-temperature hydrogen peroxide plasma offers rapid cycle times with minimal residual toxicity, though penetration depth constraints limit use to surface-sterilized constructs.
Irradiation anchors current practice. Gas plasma is climbing the fastest as processors seek alternatives to dose-dependent biomechanical degradation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Dubai Healthcare City are concentrating tissue processing infrastructure and distribution hubs for machined allograft products. These zones offer streamlined customs clearance and tax incentives that attract multinational suppliers establishing regional fulfillment centers. The geographic spread of regulatory frameworks creates distinct compliance environments across major markets.
United States
Hospital consolidation into integrated delivery networks in Texas and Florida is centralizing procurement decisions for spinal fusion procedures. The FDA's 21 CFR Part 1271 framework mandates electronic batch records and enhanced donor screening documentation that elevates compliance costs. Academic medical centers in Massachusetts and North Carolina pilot advanced decellularization protocols for anterior cervical applications.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia are expanding degenerative disc disease caseloads requiring interbody fusion. The EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on tissue-based implants than predecessor directives. Processing facilities in Baden-Württemberg specialize in precision-milled cortical constructs for trauma reconstruction.
Japan
Metropolitan Tokyo and Osaka prefectures concentrate spine surgery volume as population aging accelerates faster than European benchmarks. The PMDA enforces pharmaceutical-level manufacturing standards on tissue processors through the Act on Regulation of Human Cloning Techniques. Regional tissue banks in Kansai coordinate donor recovery networks serving western Honshu surgical centers.
Australia
The Therapeutic Goods Administration (TGA) maintains distinct biologicals framework separate from device regulations, creating specialized registration pathways. Sydney and Melbourne hospital networks drive demand for pre-shaped cortical dowels in ambulatory spinal procedures. Tissue processors in New South Wales leverage proximity to Asia-Pacific shipping lanes for export distribution.
United Arab Emirates
Dubai Healthcare City free zone infrastructure attracts tissue bank operators serving Gulf Cooperation Council markets with consolidated logistics. The Ministry of Health and Prevention (MOHAP) regulates human tissue importation through centralized licensing of approved international suppliers. Surgical tourism flows into Abu Dhabi and Dubai facilities generate demand for premium composite allograft constructs.
Spinal Machined Bone Allograft Market Competitive Landscape
United States producers anchor the premium tier through vertically integrated tissue supply chains; European specialists hold differentiated positions in precision processing technologies. Market structure concentrates among five to seven entities controlling donor network access and validated sterilization capacity. Three archetypes dominate: nonprofit tissue banks with donor recovery control, commercial processors with proprietary processing IP, and diversified orthopedic conglomerates with captive distribution. Competitive moves center on backward integration into donor recovery organizations and geographic expansion through state tissue bank licensure acquisitions.
Within the nonprofit tissue bank tier, LifeNet Health and MTF Biologics exemplify organizations leveraging proprietary processing technologies and established donor relationships to secure supply continuity. Among diversified orthopedic conglomerates, Medtronic occupies a position representing vertical integration from tissue recovery through hospital distribution. These entities anchor competitive positioning through distinct control points: donor network access, sterilization validation documentation, or integrated delivery network contracting scale.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Globus Medical |
| LifeNet Health |
| MTF Biologics |
| Stryker |
| Zimmer Biomet |
| AlloSource |
| RTI Surgical |
| Others |
Value Network & Pricing Analysis
Integrated delivery network standardization of allograft specifications across member hospitals forces suppliers into volume-commitment contracts, compressing spot-market premiums and rewarding processors with validated sterilization documentation and geographic proximity to distribution hubs.
Pricing Analysis
Lead-time-driven pricing stratification separates premium-tier constructs with sub-48-hour availability from discounted spot inventory carrying longer fulfillment cycles. Three-tier pricing structure across premium, standard, and economy levels tracks FDA validation tier, with 21 CFR Part 1271-compliant processors commanding sustained premiums. Cost compression in the mid-tier intensifies because hospital value analysis committees unbundle implant procurement from surgeon preference, elevating price sensitivity among independent ambulatory surgery centers while academic medical centers remain least sensitive due to bundled reimbursement structures.
Supply Chain Analysis
FDA 510(k) clearance and state tissue bank licensure in New York and Florida gate processor participation, filtering supply toward multi-state networks with dedicated quality infrastructure. Tissue recovery concentrates in the United States, with secondary processing capacity in Germany and Japan serving regional demand. Raw material supply draws from voluntary donor networks, aseptic processing suites, and irradiation facilities. Single-source vulnerability runs through nonprofit tissue banks controlling donor recovery. Distribution runs through integrated delivery network central warehouses and specialized medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over donor recovery organizations determines supply continuity and margin defense against synthetic graft substitution.
For Market Incumbents: Deepen backward integration into donor recovery organizations to secure raw material access against nonprofit tissue bank fragmentation. Expand state tissue bank licensure acquisitions in Florida and New York to build regulatory moats. Prioritize decellularization protocol R&D to differentiate from PEEK and titanium interbody cages capturing mechanical applications. For New Entrants and Emerging Players: Launch via ambulatory surgery center direct contracts in Texas and Florida, bypassing incumbent-locked integrated delivery networks. Target the gas plasma sterilization segment as the most penetrable niche, where alternative terminal methods are climbing fastest. Pursue composite construct innovation for cervical fusion applications where premium positioning remains achievable. For Investors and Strategic Acquirers: The window for entry favors processors with validated electronic batch record systems and existing state licensure. Long-term viability rests on consolidation plays among regional Midwest banks exiting due to compliance cost burdens. Watch FDA sterilization validation timeline compression as the inflection signal determining competitive attrition rates.| Strategic Initiative | Industry Significance |
|---|---|
| Donor Recovery Network Acquisition | Backward integration into tissue recovery organizations secures supply continuity against voluntary donation rate plateaus. |
| State Tissue Bank Licensure Expansion | Certification in New York and Florida creates regulatory moats that filter processor participation. |
| Decellularization Protocol Development | Enzymatic detergent processing preserves osteoinductive proteins while decentralizing sterilization capacity. |
| Hospital System Partnership | Integrated delivery network sole-source contracts eliminate discretionary purchasing and lock volume commitments. |
| Surgeon Training Program Sponsorship | Cadaveric workshops at Texas and California academic centers accelerate technique adoption among community spine surgeons. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, state tissue bank licensure expansions, and integrated delivery network contract awards anchored the trend analysis, supplemented by interviews with tissue bank operations directors, hospital value analysis committee chairs, orthopedic spine surgeons, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 21 CFR Part 1271 guidance documents, CMS Medicare reimbursement databases, hospital procurement records, and American Association of Tissue Banks accreditation reports. Bottom-up processor capacity estimates and top-down procedure volume projections were triangulated.
Input-output matrices modeled supply-side constraints against demand-pull from ambulatory surgery center expansion and demographic compression across Japan and Germany. Segmentation dimensions included product type, end-user facility tier, application invasiveness, and sterilization method. CAGRs were derived from procedure volume elasticity to reimbursement shifts and processor capacity expansion rates. Forecast inputs incorporated donor recovery rates and decellularization technology adoption curves.
Donor tissue availability shocks, sterilization validation timeline extensions, and synthetic graft substitution acceleration are the dominant revision risks. Forecasts reflect assumptions about regulatory stability and reimbursement parity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
IV Fluid Monitoring Device Market