
 Baby Thermometer Market | 2026-2036
Baby Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Thermometer Market Analysis
Pediatric clinic procurement is recalibrating around bulk non-contact thermometer contracts, shifting volume away from individual parent purchases. OMRON Corporation leverages its hospital-grade calibration standards to anchor institutional contracts across East Asian health networks. Kinsa Inc. competes through smartphone-integrated fever tracking that extends consumer engagement beyond the point of sale. Philips dominates premium infrared segments in European maternity wards through CE-marked precision engineering.
A baby thermometer measures body temperature in infants through conductive, radiant, or electronic sensing methods, typically achieving clinical accuracy within ±0.1°C via infrared tympanic or temporal artery detection. These devices serve fever monitoring in home care and clinical triage settings where speed and non-invasiveness protect vulnerable neonatal physiology. Infrared thermometers lead the product type landscape due to their no-touch operational profile in infectious disease protocols, while smart thermometers represent the fastest-growing technology segment as Bluetooth-enabled data logging reshapes parent-physician communication. Digital thermometers retain volume dominance in price-sensitive pharmacy channels where battery longevity and display clarity sustain repeat purchases.
The FDA enforces Class II medical device controls over infrared baby thermometers, mandating 510(k) premarket notification for accuracy claims that directly shapes manufacturer R&D budgets. EMA's Medical Device Regulation imposes post-market surveillance obligations across European Economic Area states, compelling exporters to maintain vigilance reporting systems. China's NMPA requires domestic registration for thermometer sales through hospital procurement platforms, creating a compliance gateway for foreign manufacturers. Stakeholders must monitor evolving software-as-medical-device classifications as app-connected thermometers trigger additional regulatory scrutiny.
Market Dynamics
The FDA's tightened 510(k) accuracy thresholds for infrared thermometers are compressing R&D timelines while China's NMPA hospital procurement gateways filter out uncertified suppliers, creating a dual-regulatory squeeze that favors manufacturers with existing clinical validation infrastructure.
Growth Catalysts
- Suburban pediatric clinic expansion:Non-contact screening protocols are multiplying across outpatient corridors in China's tier-two cities and India's satellite maternity centers, generating institutional bulk orders that outpace individual consumer purchases.
- Bluetooth-enabled fever tracking:Smartphone-integrated data logging is rewriting parent-physician communication workflows, extending device utility beyond point-of-sale into longitudinal health monitoring ecosystems.
- EMA Medical Device Regulation:Post-market surveillance obligations across European Economic Area states are accelerating quality investments that differentiate CE-marked precision engineering in maternity ward procurement.
Market Restraints
- Indium gallium arsenide sensor concentration:Infrared detector supply chains cluster among specialized Japanese and German component fabricators, exposing thermometer assemblers to input bottlenecks and price volatility.
- Calibration infrastructure gaps:Blackbody reference standards for clinical-grade accuracy require capital-intensive metrology labs that smaller manufacturers cannot replicate, freezing out price-competitive entrants.
- Mercury thermometer substitution limits:WHO phase-out mandates for mercury-containing devices have already saturated replacement demand in developed markets, narrowing organic growth vectors to birth-rate-dependent regions.
Strategic Opportunities
- Provincial Chinese maternity hubs:Birth rate stabilization in tier-two cities concentrates demand in hospital procurement platforms where NMPA registration creates defensible competitive moats for early entrants.
- Software-as-medical-device convergence:App-connected thermometers triggering additional FDA scrutiny also open recurring revenue streams through subscription-based fever analytics and pediatric telehealth integration.
- Pharmacy channel digitization:E-commerce direct-to-parent distribution is compressing traditional retail markups while enabling real-time inventory matching to regional outbreak patterns.
Industry Challenges
- Clinical validation timeline compression:FDA 510(k) premarket notification cycles for accuracy claims now overlap with product refresh schedules, forcing simultaneous engineering and regulatory submission workflows.
- Multi-jurisdiction vigilance reporting:EMA post-market surveillance obligations require parallel adverse event tracking systems that strain quality management infrastructure at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Thermometer Market |
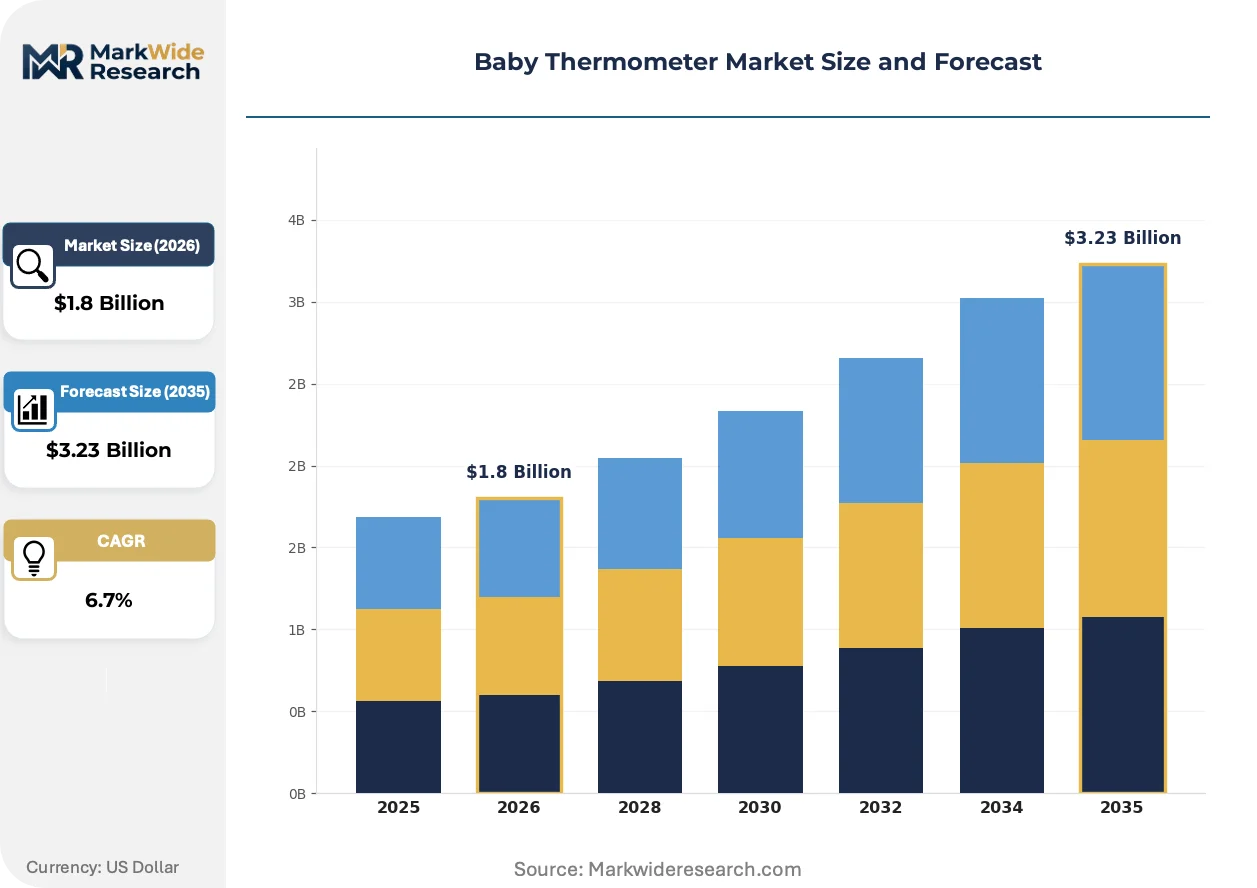
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Glass Thermometers, Ear Thermometers Technology: Contact, Non-Contact, Smart Thermometers, Flexible Sensors End User: Parents, Hospitals, Clinics, Pediatricians Distribution Channel: Online Retail, Pharmacies, Hypermarkets, Specialty Stores |
| Companies Covered | Procter & Gamble, Kinsa Inc., B. Braun SE, Microlife Corporation, Exergen Corporation, Geratherm Medical AG, OMRON Corporation, Koninklijke Philips N.V., VAVA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Thermometer Market Emerging Trajectories
Sensor miniaturization and wireless protocol standardization are converging to transform thermometer hardware from isolated measurement tools into connected health nodes, embedding these devices within broader pediatric care ecosystems.
Infrared temporal artery detection is rewriting fever assessment protocols in neonatal intensive care units. The technology eliminates probe insertion trauma while maintaining ±0.1°C clinical accuracy. European maternity wards are adopting these sensors at accelerated pace, compressing demand for conductive measurement methods.
EMA's Medical Device Regulation imposes post-market surveillance obligations across European Economic Area states. Manufacturers must maintain vigilance reporting systems that track device performance in real-world use. Exporters to Germany, France, and the Netherlands face the steepest compliance ramps, with CE-marked precision engineering becoming a non-negotiable procurement filter.
Parent purchasing behavior is fragmenting across channel types. Hospital discharge gift sets now bundle thermometers with infant care kits, displacing standalone retail purchases. This pattern concentrates most visibly in China's provincial maternity hospitals, where institutional procurement platforms dominate volume allocation and individual pharmacy sales stagnate.
Baby Thermometer Market Segmentation
Baby thermometer procurement splits sharply between institutional buyers demanding FDA 510(k) or CE-marked precision and price-sensitive parents prioritizing speed and connectivity. Manufacturers must engineer for divergent validation standards across these segments.
Product Type:
FDA Class II controls apply variably across this category, with infrared variants facing the strictest accuracy thresholds while glass thermometers operate under legacy exemption frameworks.
- Infrared Thermometers:These devices detect radiant heat from temporal arteries or tympanic membranes using indium gallium arsenide sensors. Hospital procurement in China's tier-two maternity hubs concentrates demand for units with blackbody-calibrated ±0.1°C precision. NMPA registration creates entry barriers that favor established clinical validation infrastructure.
- Digital Thermometers:Electronic conductive sensors with liquid crystal displays dominate pharmacy channel volume through battery longevity and sub-$20 price points. India's satellite maternity centers and suburban US clinics sustain replacement cycles.
- Ear Thermometers:Tympanic infrared probes require disposable lens filters for infection control in clinical settings.
- Glass Thermometers:Mercury-free alternatives retain niche demand in rural pharmacies where electronic calibration infrastructure remains sparse.
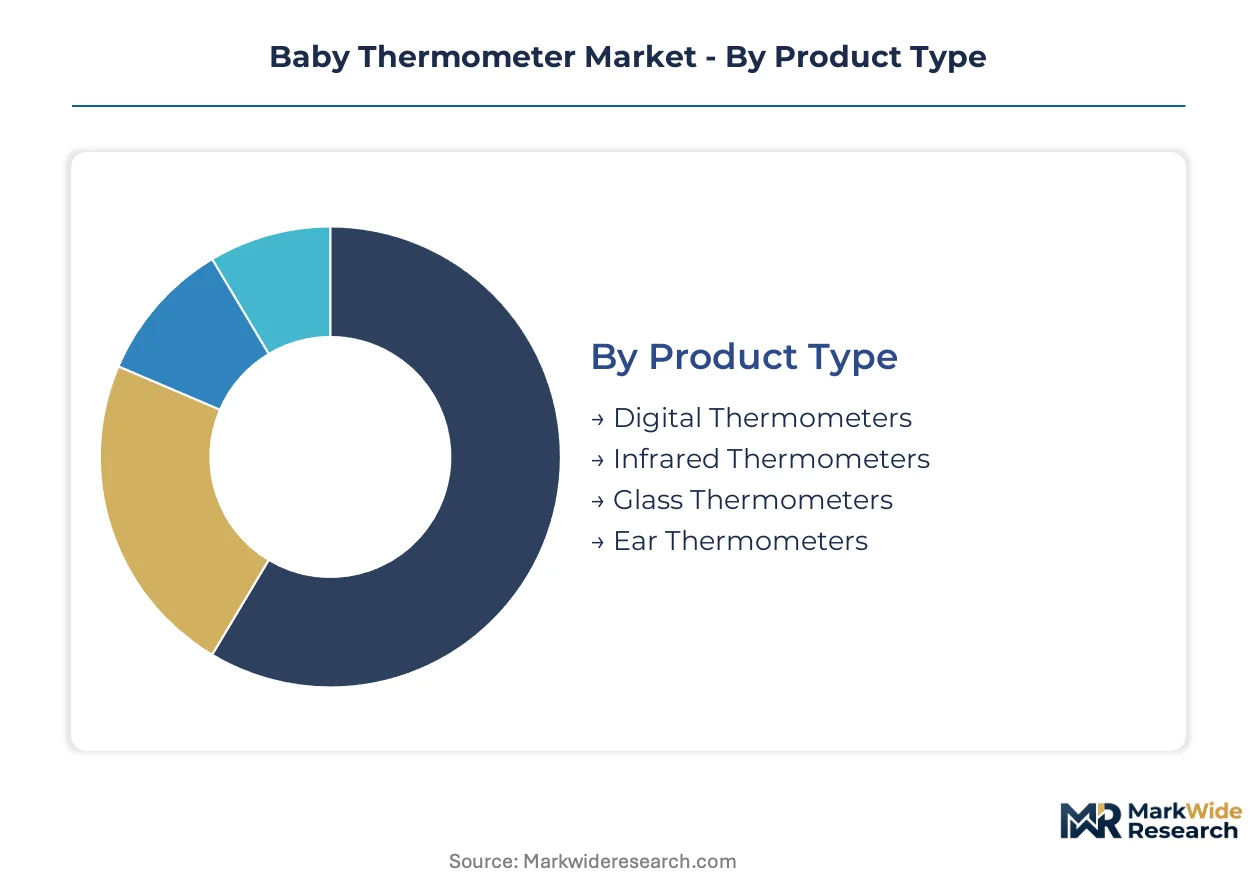
Digital thermometers sit at the top of the volume ranking, with infrared thermometers climbing the fastest.
Technology:
Cost stratification separates premium-connected systems from commodity measurement tools, with software-as-medical-device classifications adding compliance layers to higher tiers.
- Smart Thermometers:Bluetooth-enabled data logging pairs with smartphone apps for longitudinal fever tracking. Kinsa Inc. and similar vendors monetize through subscription analytics and pediatric telehealth integration. FDA scrutiny of app-connected claims extends validation timelines but opens recurring revenue streams.
- Non-Contact:Temporal artery scanning eliminates probe trauma in neonatal intensive care units. European maternity wards accelerate adoption as EMA post-market surveillance obligations elevate CE-marked engineering premiums.
- Contact:Traditional conductive methods retain dominance in price-sensitive pharmacy channels.
- Flexible Sensors:Wearable patch formats enable continuous monitoring during sleep.
Contact technology retains the broadest installed base, while smart thermometers gain share fastest through ecosystem lock-in effects.
End User:
Application context dictates accuracy requirements and procurement authority, with clinical buyers enforcing certification standards that exclude consumer-grade alternatives.
- Hospitals:Neonatal intensive care units and maternity wards mandate ISO 80601-2-56 compliant infrared temporal artery systems. China's provincial hospital procurement platforms concentrate volume through NMPA-registered suppliers.
- Clinics:Suburban pediatric outpatient corridors in India and China's tier-two cities drive bulk non-contact screening contracts. Institutional purchasing displaces individual parent acquisitions.
- Pediatricians:Private practice requirements split between clinical-grade validation and workflow convenience.
- Parents:Home care settings prioritize speed, smartphone integration, and retail accessibility over metrological precision.
Hospitals command the highest per-unit pricing tier, with clinics expanding volume most aggressively through protocol standardization.
Distribution Channel:
Customer type concentration varies by channel, with institutional procurement bypassing retail entirely while direct-to-parent e-commerce compresses traditional markup structures.
- Online Retail:Amazon and Tmall direct-to-parent distribution enables real-time inventory matching to regional outbreak patterns. Smartphone-integrated brands leverage digital-native marketing to bypass pharmacy shelf competition.
- Pharmacies:CVS, Walgreens, and China's CR Pharmacy chains sustain digital thermometer volume through foot traffic and emergency purchase behavior. Battery replacement and display clarity drive repeat brand loyalty.
- Hypermarkets:Walmart and Carrefour bundle thermometers with infant care gift sets in developing markets.
- Specialty Stores:Mothercare and Buy Buy Baby curate premium infrared segments for first-time parent demographics.
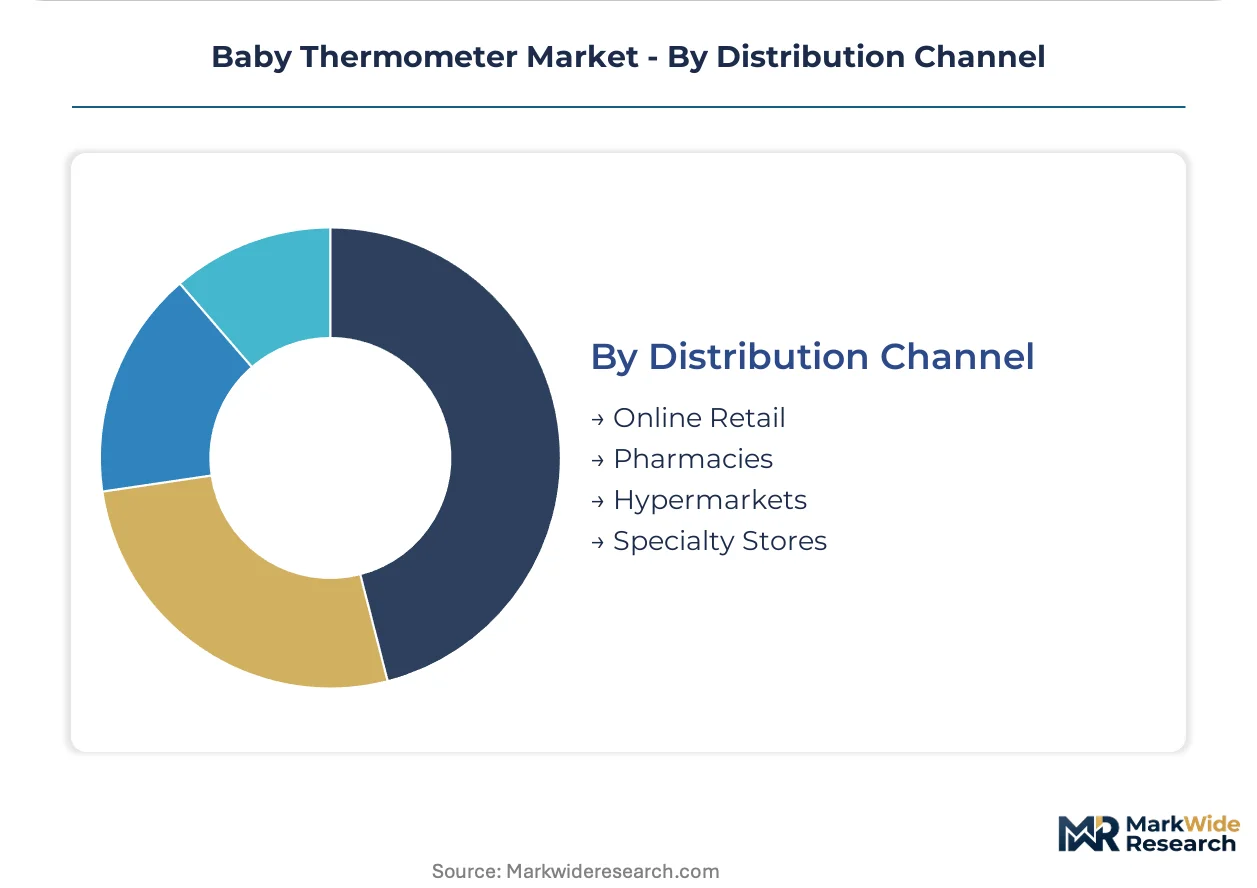
Pharmacies maintain the deepest volume penetration, with online retail expanding most quickly through pandemic-accelerated habit formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical engineering talent clusters in Germany, Japan, and the United States anchor precision thermometer development, while manufacturing scale concentrates in Chinese provincial hubs and Mexican border maquiladoras.
United States
FDA 510(k) premarket notification cycles compress product development timelines for infrared accuracy claims. The agency's tightened thresholds force simultaneous engineering and regulatory submission workflows. Boston's medical device corridor hosts validation infrastructure serving neonatal intensive care unit procurement.
China
NMPA hospital procurement gateways in tier-two cities filter out uncertified suppliers as birth rates stabilize in provincial maternity hubs. The regulator's domestic registration requirements create compliance moats for early entrants. Shenzhen's electronics manufacturing base supplies sensor assembly for temporal artery detection systems.
Germany
EMA Medical Device Regulation post-market surveillance obligations accelerate quality investments across European Economic Area exports. CE-marked precision engineering dominates maternity ward procurement decisions. Baden-Württemberg's metrology labs anchor blackbody calibration standards for clinical-grade accuracy.
Japan
PMDA oversight of indium gallium arsenide sensor fabrication concentrates supply chains among specialized component producers. METI industrial standards shape infrared detector specifications for neonatal applications. Tokyo-Yokohama medical device clusters integrate sensor miniaturization with wireless protocol development.
India
CDSCO medical device rules phase in quality management system requirements for thermometer imports. Satellite maternity centers in suburban corridors drive bulk non-contact screening contracts. Bangalore's health technology startups pair smartphone integration with pharmacy channel digitization.
Baby Thermometer Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification strata. The vendor base stratifies between hospital-grade precision engineering and price-sensitive consumer electronics. Three archetypes dominate: diversified health technology conglomerates with calibration infrastructure, connected-device specialists monetizing software ecosystems, and regional assemblers serving pharmacy volume channels. Competitive moves concentrate on M&A for regulatory compliance capabilities and strategic partnerships for sensor supply security.
Among diversified health technology conglomerates, OMRON Corporation and Koninklijke Philips N.V. exemplify the validation-heavy institutional contracting archetype. Kinsa Inc. occupies a distinct position within the connected-device specialist tier. These three anchors illustrate how FDA 510(k) infrastructure and smartphone ecosystem integration represent divergent but defensible competitive moats.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kinsa Inc. |
| B. Braun SE |
| Microlife Corporation |
| Exergen Corporation |
| Geratherm Medical AG |
| OMRON Corporation |
| Koninklijke Philips N.V. |
| VAVA |
| Others |
Supply Flow & Price Mechanics
China's NMPA hospital procurement gateways in tier-two maternity hubs are filtering out uncertified suppliers, forcing manufacturers to absorb blackbody calibration infrastructure costs that reshape price floors across institutional and retail tiers.
Pricing Analysis
Capacity additions in Shenzhen and Dongguan are reshaping price floors for digital thermometer assembly, compressing margins in sub-$20 pharmacy channels while FDA 510(k) validation investments sustain premium tiers for infrared clinical units. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked precision engineering from smartphone-integrated connected devices and commodity conductive sensors. Cost compression in standard-tier digital units is intensifying because battery and display component costs fluctuate with electronics demand cycles. Pharmacy channel parents exhibit highest price sensitivity, while neonatal intensive care unit procurement committees prioritize accuracy certification over unit economics.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Osaka, and Stuttgart anchor hub-and-spoke patterns for thermometer assembly and component sourcing. Indium gallium arsenide sensor fabrication concentrates in Japan and Germany, while final assembly draws from China's electronics manufacturing base and Mexican border maquiladoras serving North American retail. Blackbody reference standards, liquid crystal displays, and Bluetooth module components constitute critical input dependencies. Single-source vulnerability in specialized infrared detector supply exposes assemblers to input bottlenecks. Distribution runs through hospital procurement platforms, pharmacy chains, and direct-to-parent e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baby thermometer market functions as a regulatory compounder where FDA 510(k) accuracy threshold tightening continuously elevates validation barriers that institutional buyers demand.
For Market Incumbents: Deploy backward integration into indium gallium arsenide sensor supply to secure input access against Japanese and German fabricator concentration. Anchor hospital-grade calibration infrastructure as a defensive moat against emerging connected-device specialists threatening premium positioning. Control NMPA-registered distribution channels in China's provincial maternity hubs before protocol standardization freezes out late entrants. For New Entrants and Emerging Players: Pharmacy chain private label partnerships offer the most penetrable vector for volume entry without FDA 510(k) timeline exposure. Target India's satellite maternity centers and suburban outpatient corridors where bulk non-contact screening contracts outpace individual consumer purchases. Monetize smartphone-integrated fever tracking through subscription analytics rather than competing on hardware margins. For Investors and Strategic Acquirers: Asymmetric upside sits with connected-device specialists possessing FDA-cleared software-as-medical-device pathways and established pediatric telehealth integration. Five-to-ten-year viability favors vendors combining clinical validation infrastructure with recurring revenue ecosystems over pure hardware assemblers. Watch for NMPA registration completion rates in China's tier-two cities as inflection indicators for institutional market access.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accuracy threshold compliance unlocks neonatal intensive care unit procurement contracts. |
| CE Marking Pathway | EMA post-market surveillance obligations differentiate precision engineering in European maternity wards. |
| Hospital System Partnership | NMPA-registered supply agreements in China's tier-two cities concentrate volume allocation. |
| Software Companion Development | Bluetooth-enabled fever tracking extends engagement into subscription-based pediatric telehealth ecosystems. |
| Reimbursement Strategy | Insurance coding for remote patient monitoring accelerates connected thermometer adoption in home care settings. |
Methodological Framework
Direct dialogue with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and pharmacy category buyers grounded qualitative insights in procurement workflow realities. Secondary validation drew from FDA 510(k) premarket notification databases, EMA vigilance reporting systems, NMPA registration filings, and hospital procurement platform records. Bottom-up and top-down triangulation cross-checked sensor shipment volumes against institutional contract announcements and retail channel inventory data.
Bottom-up modeling aggregated unit economics across product type, technology tier, end-user application, and distribution channel segments. Top-down validation referenced macro birth rate trajectories, infectious disease protocol adoption curves, and regulatory enforcement intensity across the analysis window. CAGRs emerged from segmented growth rate blending weighted by procurement volume concentration in China's provincial hubs and India's suburban corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA enforcement consistency, indium gallium arsenide supply availability, and software-as-medical-device classification evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radial Compression Devices Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Wheelchair and Components Market
Medical Devices
North America C-Arms Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Knee Braces Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Vortex Mixer Market
Medical Devices
North America Laser Hair Removal Market
Medical Devices
Disposable Thermometer Market