
 Acute Coronary Syndrome (ACS) Market | 2026-2036
Acute Coronary Syndrome (ACS) Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Coronary Syndrome (ACS) Market Analysis
The gap between premium biologic antiplatelet therapies and commodity statin generics is repositioning how hospitals allocate pharmacy budgets across ACS treatment protocols. Sanofi leverages its integrated cardiovascular portfolio to sustain formulary presence in European emergency departments. Daiichi Sankyo anchors its position through specialized anticoagulant R&D intensity in Asian markets.
Acute Coronary Syndrome encompasses a spectrum of clinical conditions including unstable angina and myocardial infarction, characterized by sudden reduction of blood flow to the heart requiring immediate restoration through pharmacological or mechanical intervention. The condition demands rapid administration of antiplatelet agents and beta-blockers to stabilize hemodynamics and prevent further cardiac damage. Antiplatelet agents command the deepest margin pools due to patent-protected novel agents and mandatory dual-therapy protocols, while angioplasty and stenting technologies lead procedural volume growth as cath lab infrastructure expands. Emergency services represent the fastest-growing end user segment as pre-hospital ECG networks and mobile thrombolysis protocols compress door-to-balloon times.
FDA, EMA, and PMDA frameworks govern clinical trial endpoints, manufacturing quality, and post-market surveillance for ACS therapies across their respective jurisdictions, with each regulator tightening cardiovascular outcome study requirements for novel antiplatelet approvals. These standards directly shape development costs and market access timelines for manufacturers seeking multi-region launches. Stakeholders must monitor evolving dual-antiplatelet therapy duration guidelines and regional cath lab reimbursement policies to anticipate shifts in procedural and pharmaceutical demand.
Market Dynamics
Door-to-balloon time compression protocols are restructuring emergency cardiac care economics. Cath lab networks in the United States, Germany, and Japan now mandate pre-hospital ECG transmission, forcing pharmaceutical procurement to synchronize with interventional workflow redesign.
Growth Catalysts
- FDA cardiovascular outcome study mandates:Novel antiplatelet therapies face tightened evidentiary thresholds, accelerating differentiation among development pipelines and rewarding sponsors with robust mortality data packages.
- Mobile thrombolysis protocols:Emergency medical services in Japan and Germany deploy field-administered fibrinolytics, expanding the addressable patient window before hospital arrival.
- Dual-antiplatelet therapy standardization:Cardiology societies in the United States publish duration guidelines that lock in 12-month minimums, cementing volume commitments for branded agents.
Market Restraints
- Statin generic commoditization:Patent cliff erosion of high-potency statins compresses pharmacy budget headroom, forcing trade-offs against premium antiplatelet agents in hospital formularies.
- Cath lab reimbursement variance:Germany's DRG recalibration and Japan's fee schedule revisions create unpredictable procedure economics, deterring infrastructure expansion in secondary markets.
- Biologic antiplatelet manufacturing complexity:Monoclonal antibody production requires single-use bioreactor capacity concentrated among CMOs in Switzerland and Ireland, exposing supply continuity risk.
Strategic Opportunities
- Pre-hospital diagnostic networks:Underpenetrated emergency services in France and Spain lack integrated ECG-to-cath lab transmission, creating first-mover advantage for platform vendors.
- Artificial intelligence-ECG interpretation:Machine learning algorithms trained on population-specific arrhythmia patterns are converging with cloud telemetry to reduce false-positive STEMI activations.
- Japan's PMDA Sakigake designation:Expedited review pathways for breakthrough cardiovascular therapies compress regulatory timelines, rewarding early Japan-centric development strategies.
Industry Challenges
- Interventional cardiologist workforce density:Rural regions in the United States and eastern Germany face 24-hour cath lab coverage gaps, limiting protocol adherence despite infrastructure investment.
- Legacy EHR interoperability:Pre-hospital ECG data formats fragment across ambulance providers and receiving hospitals, corrupting door-to-balloon measurement integrity.
- Antiplatelet resistance testing standardization:Lack of consensus on platelet function assay thresholds for therapy modification creates clinical inertia and formulary stagnation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Coronary Syndrome (ACS) Market |
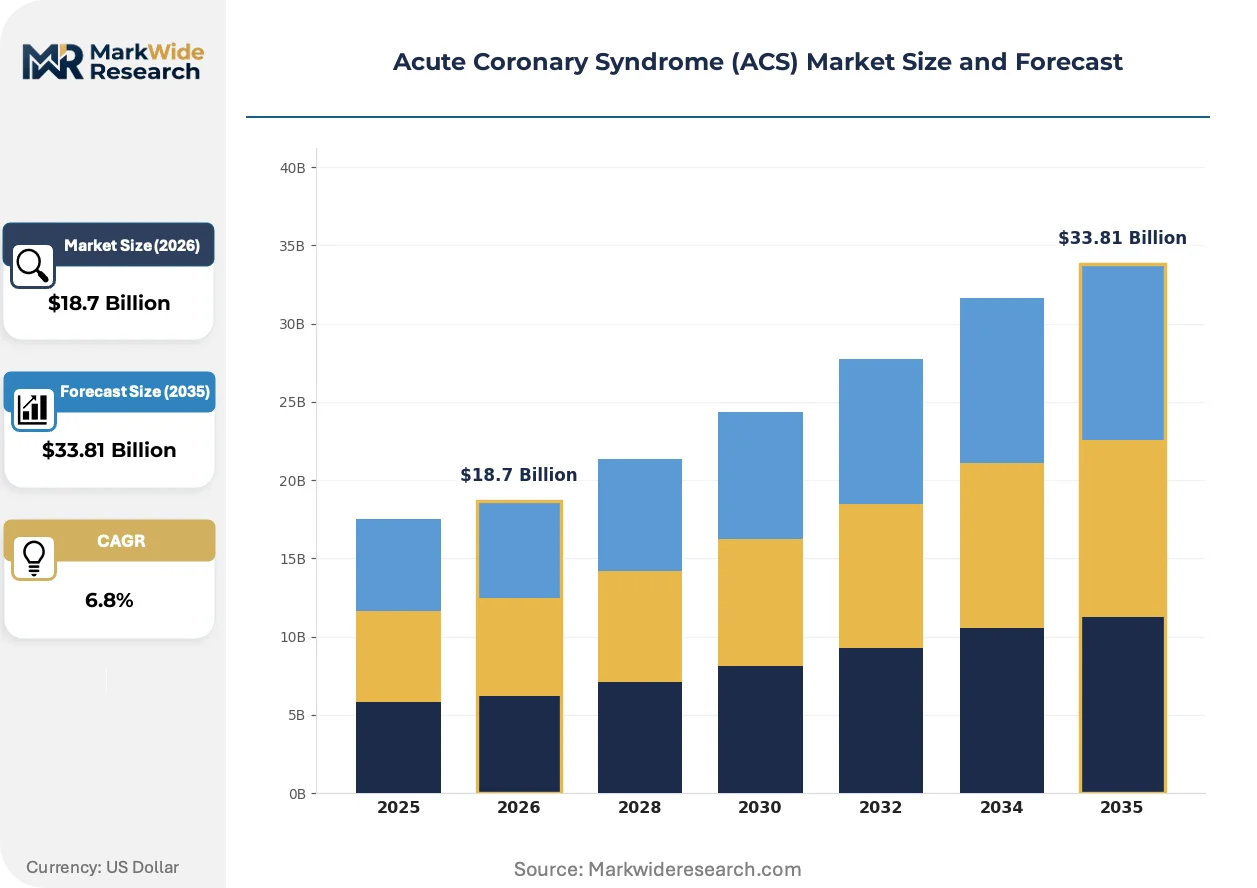
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiplatelet Agents, Beta-Blockers, ACE Inhibitors, Statins Technology: Angioplasty, Stenting, Thrombolysis, Coronary Artery Bypass End User: Hospitals, Clinics, Cardiovascular Centers, Emergency Services Delivery Mode: Intravenous, Oral, Transdermal, Inhalation |
| Companies Covered | Sanofi, Novartis, AstraZeneca, Eli Lilly, Amgen, Pfizer, Merck, Daiichi Sankyo, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Coronary Syndrome (ACS) Market Emerging Trajectories
High-sensitivity troponin assays and AI-enabled risk stratification are compressing diagnostic timelines. These tools are reallocating treatment decisions from emergency departments to paramedic field units.
High-sensitivity troponin I and T assays detect myocardial injury at nanogram-per-liter thresholds, enabling rule-out protocols within one hour of presentation. Emergency departments in the United States and Germany are adopting these platforms to discharge low-risk patients rapidly. This diagnostic precision is overtaking traditional 6-hour serial testing sequences, compressing ED length-of-stay metrics and reallocating bed capacity.
EMA's Medical Device Regulation (MDR) intensifies post-market surveillance for software-as-medical-device ECG algorithms. Manufacturers must submit periodic safety update reports and maintain technical documentation for AI training data provenance. Cardiac diagnostic platforms with embedded machine learning face recertification costs that favor established vendors with regulatory affairs scale.
Integrated pharmacy-benefit managers in the United States are contracting directly with cardiovascular centers for episode-based reimbursement. These arrangements bundle antiplatelet drug costs with procedural fees, displacing traditional fee-for-service dispensing. The model concentrates volume among health systems with captive specialty pharmacy infrastructure, visible in Medicare Advantage penetration markets like Florida and Arizona.
Acute Coronary Syndrome (ACS) Market Segmentation
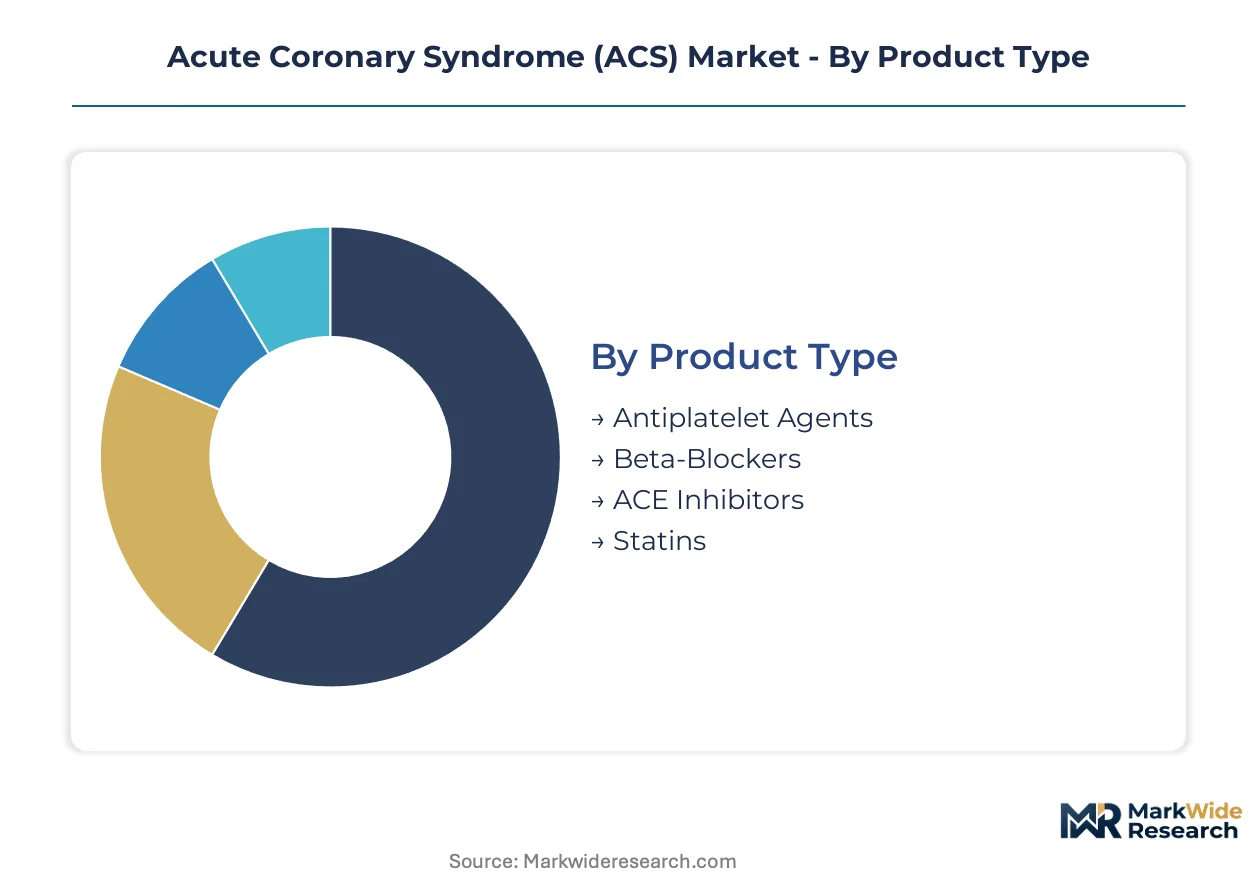
Pharmaceutical procurement in ACS care operates through distinct budgetary lanes: acute intervention drugs command premium formulary slots, while maintenance therapies face generic compression. Technology segmentation separates catheter-based revascularization from pharmacological reperfusion, each with diverging capital intensity and reimbursement profiles.
Product Type:
Hospital pharmacy committees allocate spend based on patent protection duration and outcome study data packages.
- Antiplatelet Agents:P2Y12 inhibitors and glycoprotein IIb/IIIa antagonists form mandatory dual-therapy protocols. United States cardiovascular centers lock in 12-month branded commitments through society guideline adherence. These agents capture the deepest margin pools due to interventional workflow integration.
- Statins:High-potency formulations face patent cliff erosion, compressing pharmacy budget headroom. German hospital formularies now trade off statin generic savings against antiplatelet premium positioning.
- Beta-Blockers:Post-infarction hemodynamic stabilization with carvedilol and metoprolol succinate.
- ACE Inhibitors:Ramipril and enalapril for ventricular remodeling prevention in secondary prevention protocols.
Volume sits with statins; growth tilts toward antiplatelet agents.
Technology:
Procedure economics hinge on cath lab infrastructure density and interventionalist workforce availability.
- Angioplasty:Percutaneous transluminal coronary angioplasty with balloon catheter systems enables rapid revascularization. Japan's emergency networks deploy mobile units with pre-hospital ECG transmission to compress door-to-balloon times. This modality leads procedural volume growth as cardiac catheterization laboratory networks expand.
- Thrombolysis:Fibrinolytic agents administered in field settings extend the therapeutic window before hospital arrival. German emergency medical services integrate mobile protocols with helicopter transport systems.
- Stenting:Drug-eluting and bare-metal stent deployment following balloon predilation.
- Coronary Artery Bypass:Surgical revascularization for multi-vessel disease and failed PCI cases.
Volume concentrates in angioplasty; stenting climbs fastest on DES platform upgrades.
End User:
Care site selection determines regulatory pathway complexity and procurement contract structure.
- Emergency Services:Pre-hospital thrombolysis and ECG transmission networks reallocate treatment decisions from hospital doors to paramedic field units. United States municipalities in Florida and Arizona contract directly with integrated pharmacy-benefit managers for episode-based reimbursement. This segment expands most quickly on mobile diagnostic platform deployment.
- Hospitals:Academic medical centers anchor interventional volume through 24-hour cath lab coverage and STEMI receiving center designation.
- Cardiovascular Centers:Dedicated cardiac facilities with captive specialty pharmacy infrastructure.
- Clinics:Outpatient settings for stable post-ACS monitoring and medication management.
Volume rests with hospitals; emergency services gain share fastest on pre-hospital network buildout.
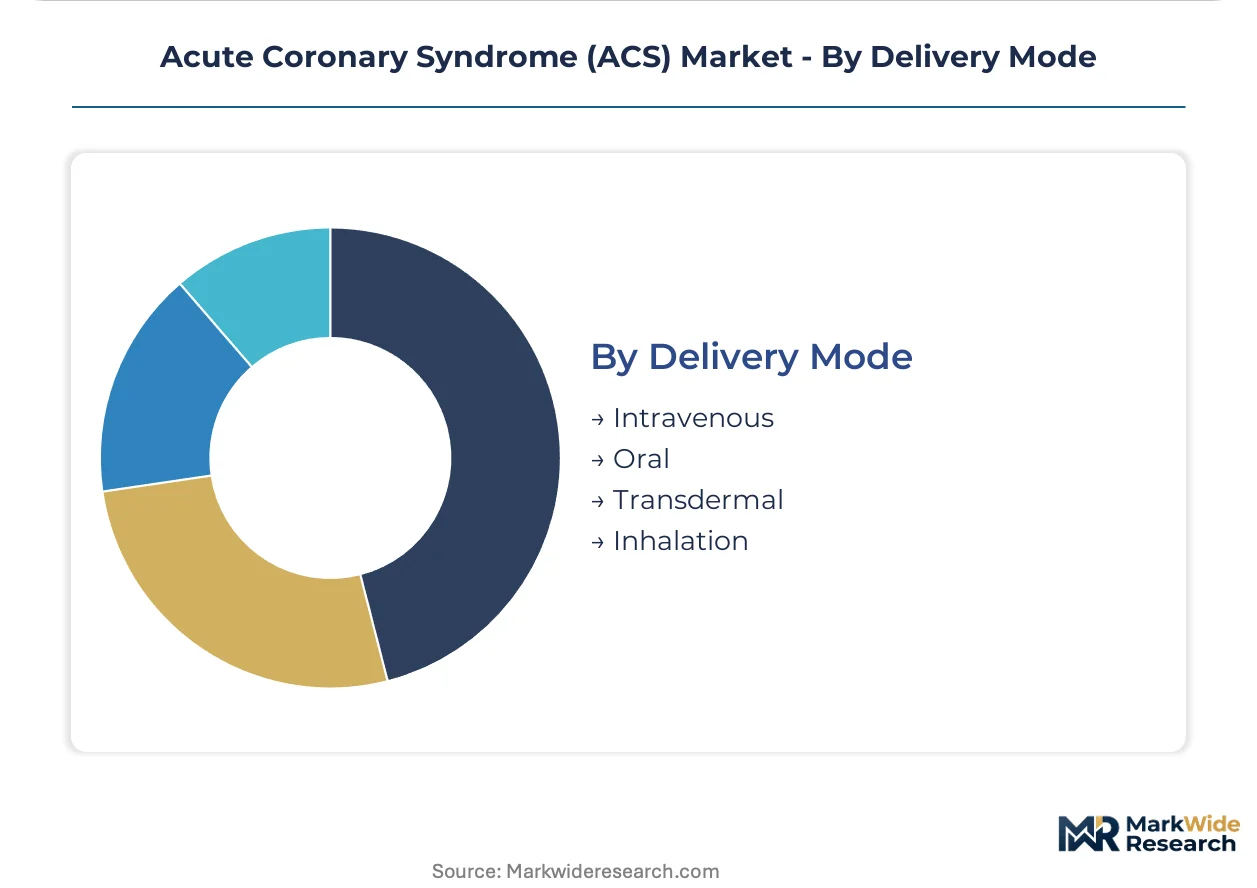
Delivery Mode:
Administration route selection balances onset speed against patient compliance and monitoring requirements.
- Intravenous:Immediate bioavailability for critical hemodynamic stabilization in cath lab and emergency department settings. United States protocols mandate IV glycoprotein IIb/IIIa inhibitors during high-risk PCI procedures.
- Oral:Maintenance-phase P2Y12 inhibition with clopidogrel, prasugrel, or ticagrelor enables outpatient transition.
- Transdermal:Nitroglycerin patches for angina symptom control in stable patients.
- Inhalation:Supplemental oxygen delivery and experimental nitric oxide protocols.
Volume sits with oral formulations; intravenous expands fastest on interventional procedure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors ACS interventional volume through its density of academic medical centers with 24-hour cath lab coverage and STEMI receiving center designation.
United States
Medicare Advantage penetration in Florida and Arizona drives episode-based reimbursement contracting between integrated pharmacy-benefit managers and cardiovascular centers. FDA cardiovascular outcome study mandates tighten evidentiary thresholds for novel antiplatelet approvals. The Southeast corridor scales mobile thrombolysis protocols with pre-hospital ECG transmission networks.
Germany
DRG recalibration creates unpredictable procedure economics for cath lab infrastructure expansion in secondary markets. EMA's Medical Device Regulation intensifies post-market surveillance requirements for AI-enabled ECG algorithms. Bavaria's emergency medical services integrate helicopter transport with field-administered fibrinolytics.
Japan
PMDA's Sakigake designation compresses regulatory timelines for breakthrough cardiovascular therapies, rewarding early Japan-centric development strategies. METI funding accelerates mobile diagnostic platform deployment across rural prefectures. The Kanto region concentrates specialized anticoagulant R&D intensity through dedicated cardiac emergency networks.
France
Underpenetrated emergency services lack integrated ECG-to-cath lab transmission, creating first-mover advantage for platform vendors. ANSM oversight governs clinical trial endpoints for ACS therapies within national jurisdiction. The Île-de-France region hosts monoclonal antibody production capacity concentrated among contract manufacturing organizations.
Switzerland
Single-use bioreactor capacity for biologic antiplatelet manufacturing concentrates among contract manufacturing organizations, exposing supply continuity risk. Swissmedic frameworks govern manufacturing quality and post-market surveillance. The Basel region anchors European emergency department formulary presence through integrated cardiovascular portfolio positioning.
Acute Coronary Syndrome (ACS) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across patent protection duration and outcome study data package robustness. Antiplatelet agents with interventional workflow integration capture deeper margin pools than statin generics facing patent cliff erosion. Three archetypes dominate: integrated pharmaceutical portfolios with emergency department formulary lock-in, specialized anticoagulant R&D shops with regional regulatory expertise, and biologic manufacturing specialists with single-use bioreactor capacity. Competitive moves concentrate on strategic partnerships for pre-hospital diagnostic network integration and portfolio diversification into AI-enabled risk stratification tools.
Within the integrated portfolio tier, Sanofi and Bristol Myers Squibb occupy positions shaped by emergency department formulary presence and society guideline adherence. Daiichi Sankyo exemplifies the specialized R&D archetype through its concentration on anticoagulant development intensity in Asian markets. These three entities represent distinct competitive vectors: formulary integration, regional regulatory optimization, and manufacturing scale.
| Leading Market Players |
|---|
| Sanofi |
| Novartis |
| AstraZeneca |
| Eli Lilly |
| Amgen |
| Pfizer |
| Merck |
| Daiichi Sankyo |
| Bristol Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Integrated pharmacy-benefit managers in Florida and Arizona anchor episode-based reimbursement contracting, locking cardiovascular centers into value-based pricing models that bundle procedural fees with antiplatelet drug costs. This buyer concentration compresses margin flexibility for manufacturers while rewarding health systems with captive specialty pharmacy infrastructure.
Pricing Analysis
Value-based pricing tied to door-to-balloon time performance anchors United States cardiovascular center contracts. Three-tier pricing structure across premium novel antiplatelets, standard branded maintenance therapies, and economy statin generics separates margin pools by patent protection duration. Cost compression in the statin tier intensifies because patent cliff erosion forces hospital formulary committees to trade generic savings against antiplatelet premium positioning. Emergency services procurement shows highest price sensitivity due to municipal budget constraints, while interventional cardiology units demonstrate lowest sensitivity given outcome-study-driven guideline adherence.
Supply Chain Analysis
Dual-sourcing requirements for monoclonal antibody production mandate qualification of contract manufacturing organizations across Switzerland and Ireland, exposing biologic antiplatelet supply continuity to single-use bioreactor capacity constraints. Raw material dependencies center on recombinant protein media, sterile filtration assemblies, and temperature-controlled logistics infrastructure. Single-source vulnerability concentrates in Swiss CMO capacity for glycoprotein IIb/IIIa inhibitor production. Distribution runs through hospital pharmacy committees and integrated specialty pharmacy networks with direct-to-cath lab cold chain protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use bioreactor capacity scarcity props pricing for biologic antiplatelet agents, constraining volume expansion until manufacturing scale materializes.
For Market Incumbents: Anticipate formulary displacement from AI-enabled risk stratification tools by embedding machine learning algorithms into emergency department workflow platforms. Consolidate position through backward integration into pre-hospital ECG transmission networks, securing data continuity from paramedic field units through cath lab activation. Priority lever rests on society guideline adherence locking in 12-month dual-antiplatelet therapy commitments. For New Entrants and Emerging Players: Telemedicine platforms for rural cath lab coverage represent the most penetrable white-space target, addressing interventional cardiologist workforce density gaps in eastern Germany and the United States Southeast. Underpenetrated emergency services in France and Spain offer second-tier opportunity through ECG-to-cath lab transmission infrastructure buildout. Go-to-market angle centers on cloud-based AI-ECG interpretation with population-specific arrhythmia training data. For Investors and Strategic Acquirers: The window for entry favors specialized anticoagulant R&D shops with PMDA Sakigake pathway experience and regional regulatory optimization capabilities. Long-term viability hinges on five-to-ten year patent runway for novel antiplatelet mechanisms with interventional workflow integration. Signal to watch is Japan's METI funding acceleration for mobile diagnostic platform deployment across rural prefectures.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-hospital Diagnostic Network Integration | Platform vendors capturing ECG-to-cath lab transmission contracts in France and Spain gain first-mover data advantages. |
| PMDA Sakigake Designation Pursuit | Expedited cardiovascular therapy review compresses regulatory timelines for sponsors with Japan-centric development strategies. |
| AI-ECG Algorithm Certification | EMA MDR compliance for software-as-medical-device platforms favors established vendors with regulatory affairs scale. |
| Single-use Bioreactor Capacity Expansion | CMOs in Switzerland and Ireland alleviating monoclonal antibody manufacturing bottlenecks secure biologic antiplatelet supply continuity. |
| Episode-based Reimbursement Contracting | Integrated pharmacy-benefit managers in Medicare Advantage markets bundle drug costs with procedural fees, displacing fee-for-service dispensing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with interventional cardiologists, hospital formulary directors, emergency medical services procurement leads, and cardiovascular center pharmacy managers. FDA 510(k) submissions, EMA marketing authorization applications, PMDA Sakigake designations, and GPO contract databases provided validation triangulation. Bottom-up modeling of antiplatelet agent volumes and top-down cross-check against cath lab procedure counts ensured consistency.
Granularity-level modeling disaggregated the analysis window by product type, technology modality, end-user care site, and delivery route, with regional regulatory cluster as an additional dimension. CAGRs derived from slope-log regression on segment-level volume trajectories, calibrated against historical approval-to-peak sales curves for cardiovascular therapies. Forecast inputs incorporated PMDA review timeline compression rates and DRG recalibration frequency in Germany.
The model holds under stable regulatory pathway timelines; deviation in FDA cardiovascular outcome study stringency or Japan's METI funding acceleration would shift volume trajectories. Forecasts reflect assumptions on dual-antiplatelet therapy duration guideline stability and cath lab reimbursement parity across markets. A model refresh is warranted upon material change in biologic antiplatelet manufacturing capacity expansion or AI-ECG algorithm MDR recertification costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Heart Transplant Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Ticagrelor Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Global Atrial Fibrillation Market