
 Nitric Oxide Management Systems Market | 2026-2036
Nitric Oxide Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Nitric Oxide Management Systems Market Analytics
The capital-intensity divergence between integrated gas suppliers and device-centric specialists is redrawing competitive boundaries in nitric oxide management. Mallinckrodt Pharmaceuticals leverages its pharmaceutical-grade manufacturing infrastructure to sustain vertical control over drug-device combinations. Linde plc anchors its position through captive supply of medical-grade nitric oxide gas across hospital networks. Beyond Air competes with portable generation systems that eliminate cylinder logistics for emerging care settings.
Nitric oxide management systems encompass equipment and consumables for generating, delivering, and monitoring inhaled nitric oxide at therapeutic concentrations typically ranging from 5 to 80 parts per million, with integrated safety interlocks preventing nitrogen dioxide formation above 2 ppm. These systems serve primarily to treat persistent pulmonary hypertension and hypoxic respiratory failure in neonatal and adult critical care. Delivery equipment commands the dominant product position due to recurring consumable attach rates and regulatory validation requirements, while monitoring systems represent the fastest-expanding category as real-time nitrogen dioxide sensing becomes standard. Photometric technology leads the installed base for its established accuracy profile, though electrochemical platforms gain traction in portable and home care configurations.
FDA 510(k) clearance requirements and EPA emissions standards for vented medical gases shape product development timelines and geographic market access for nitric oxide management systems. The EU MDR and F-Gas Regulation impose additional compliance burdens on European market entry, particularly for systems using synthetic gas cylinders. Stakeholders must weigh the pace of portable generator adoption against entrenched cylinder-based economics in their capital allocation and partnership decisions.
Market Dynamics
Portable nitric oxide generation technology is decomposing the cylinder-based supply model that has dominated acute care for three decades, forcing incumbents to reconfigure their installed base strategies and service revenue architectures.
Growth Catalysts
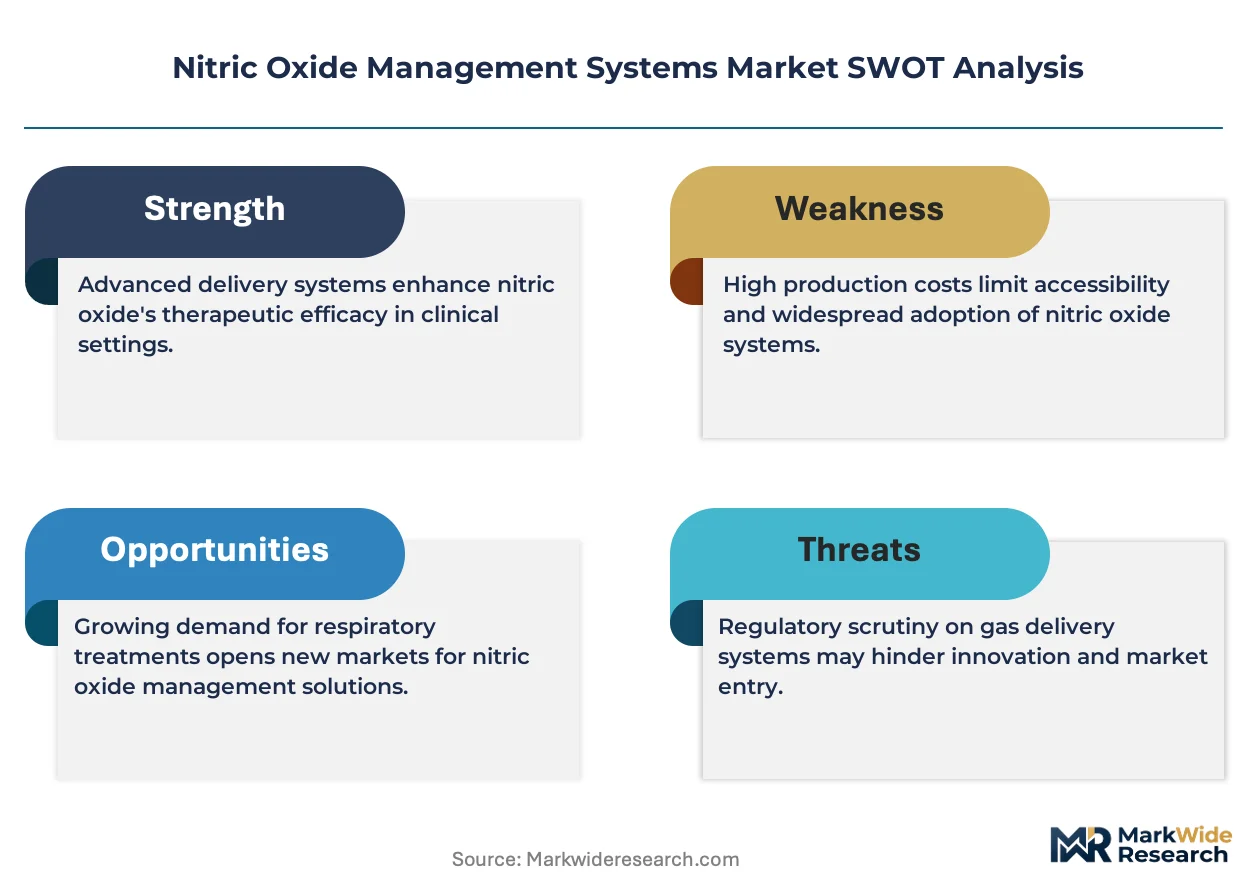
- FDA 510(k) pathway streamlining:Expedited review timelines for predicate-device submissions accelerate commercialization of next-generation delivery systems, particularly for neonatal indications.
- Integrated gas suppliers:Captive production of pharmaceutical-grade nitric oxide enables bundled contracting across hospital networks, reducing procurement friction for multi-site health systems.
- Real-time nitrogen dioxide sensing:Photometric and electrochemical monitoring modules achieve standard-of-care status in critical care protocols, driving replacement cycles for legacy delivery platforms.
Market Restraints
- Medical-grade gas supply concentration:North American production of pharmaceutical-grade nitric oxide concentrates among three integrated suppliers, creating vulnerability to facility-level disruptions.
- EU F-Gas Regulation compliance costs:Synthetic cylinder systems face phasedown requirements for high-global-warming-potential propellants, forcing reformulation investments.
- Electrochemical sensor drift:Portable monitoring platforms exhibit calibration degradation under high-humidity conditions, limiting deployment confidence outside controlled environments.
Strategic Opportunities
- Home respiratory care expansion:Portable generator miniaturization opens chronic pulmonary hypertension management beyond hospital walls, though reimbursement pathways remain underdeveloped.
- Japan's PMDA priority review vouchers:Pediatric rare disease designations for nitric oxide indications accelerate approval timelines and market access for novel delivery modalities.
- Electrochemical-photometric hybrid architectures:Convergent sensing technologies enable redundant safety interlocks, addressing liability concerns that have slowed portable adoption.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in gas-phase therapeutic delivery system design concentrates among legacy device manufacturers, constraining startup scaling.
- Legacy ventilator integration complexity:Proprietary communication protocols between established critical care platforms and third-party nitric oxide modules create interoperability friction.
- EPA emissions permitting timelines:Vent gas abatement system approvals for high-volume academic medical centers extend facility commissioning by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitric Oxide Management Systems Market |
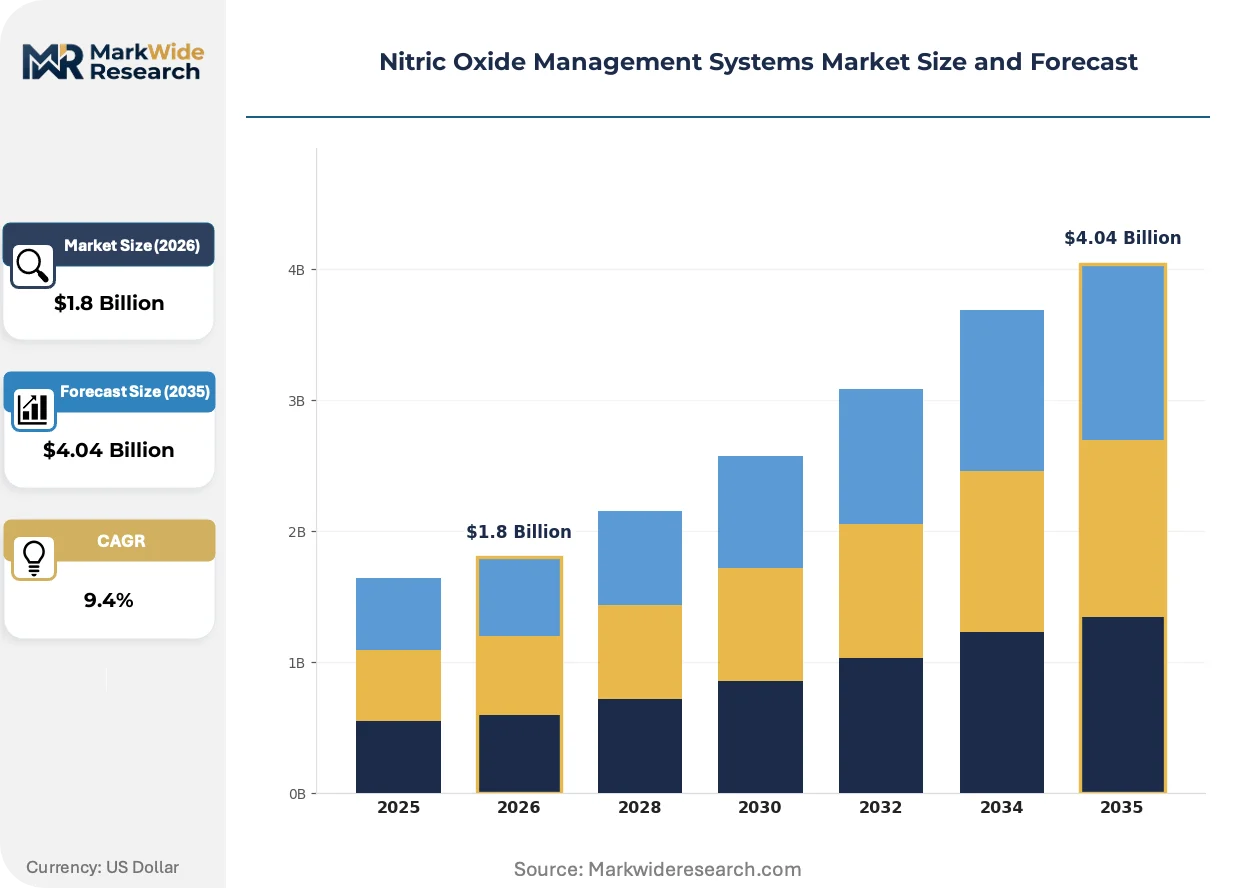
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressors, Analyzers, Delivery Equipment, Monitoring Systems End User: Hospitals, Clinics, Home Care, Specialty Centers Technology: Electrochemical, Photometric, Fluorescence, Luminol Application: Respiratory Care, Heart Surgery, Intensive Care, Clinical Research |
| Companies Covered | Mallinckrodt Pharmaceuticals, VERO Biotech, Getinge AB, Linde plc, Air Liquide Healthcare, Beyond Air, International Biomedical, Bellerophon Therapeutics, SLE Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitric Oxide Management Systems Market Evolving Landscape
Electrochemical sensing miniaturization and cloud-connected safety monitoring are converging to enable point-of-care nitric oxide delivery outside traditional critical care infrastructure.
Portable electrochemical generation technology is decomposing the capital-intensive cylinder logistics model that has anchored hospital supply contracts since the 1990s. Rural emergency departments and transport medicine units adopt these systems fastest, drawn by elimination of compressed gas handling requirements and reduced storage footprint. The structural consequence is compressing service revenue pools for incumbent gas suppliers while opening subscription-based monitoring revenue for device-centric competitors.
EPA emissions standards for vented medical gases are tightening abatement requirements for nitrogen dioxide exhaust from nitric oxide delivery systems. Academic medical centers in California and Texas face retrofit deadlines that accelerate capital replacement cycles for aging delivery platforms. High-volume neonatal intensive care units respond by specifying integrated catalytic converters in new equipment procurements, shifting vendor evaluation criteria toward total cost of ownership rather than acquisition price alone.
Buying committees at consolidated health systems now unbundle device procurement from gas supply contracts, reversing decades of bundled purchasing. Group purchasing organizations lose leverage as direct manufacturer relationships offer transparent pricing and predictive maintenance analytics. This pattern concentrates in the southeastern United States, where hospital system consolidation has created super-regional buyers with sufficient volume to justify dedicated supply agreements.
Nitric Oxide Management Systems Market Segmentation
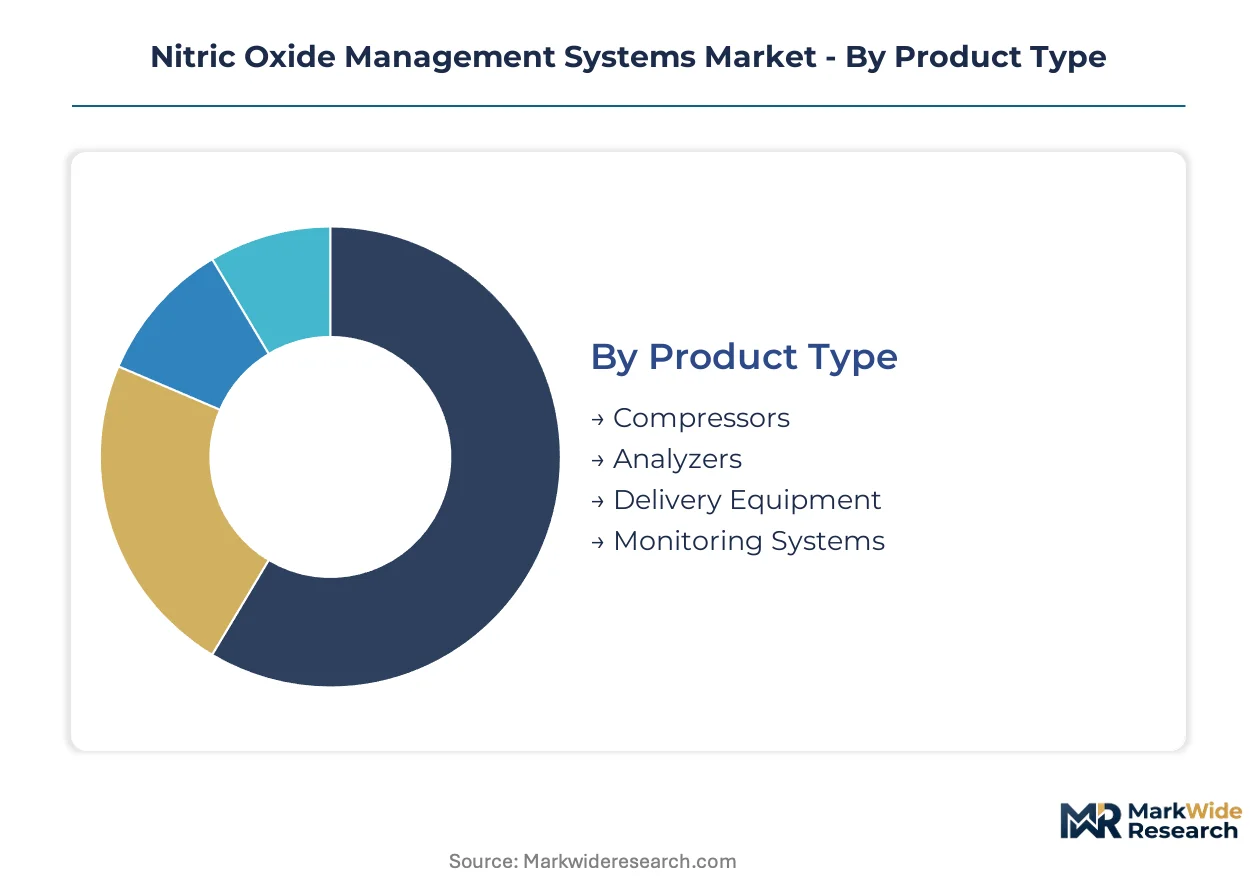
Segmentation in nitric oxide management systems reveals where portable generation technology is compressing legacy revenue pools and where integrated safety monitoring commands premium positioning. Product type and technology splits expose the deepest fault lines between cylinder-dependent incumbents and device-centric challengers.
Product Type:
Portable electrochemical generators pose the most acute substitution threat to cylinder-based delivery equipment, forcing incumbents to defend service contracts and installed base relationships.
- Delivery Equipment:Integrated nitric oxide delivery platforms combine gas flow control, blender modules, and safety interlocks to maintain therapeutic concentrations between 5-80 ppm. Neonatal intensive care units in academic medical centers drive replacement demand as EPA emissions standards tighten vent gas abatement requirements. Cylinder logistics contracts still dominate procurement, though portable alternatives erode attach rates for consumable tubing and calibration gases.
- Monitoring Systems:Real-time nitrogen dioxide sensing modules prevent toxic byproduct accumulation above 2 ppm through photometric or electrochemical detection. Critical care protocols in U.S. hospitals now mandate continuous NO2 monitoring, accelerating displacement of legacy delivery platforms lacking integrated sensors. Electrochemical miniaturization enables transport and emergency department deployment previously closed to photometric benchtop units.
- Analyzers:Standalone validation instruments verify gas concentration accuracy for regulatory compliance and quality assurance.
- Compressors:Medical-grade air compression units support cylinder-based delivery infrastructure in facilities without central gas supply.
Delivery equipment anchors the volume base while monitoring systems gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from emerging outpatient and home care configurations with divergent reimbursement profiles.
- Hospitals:Acute care facilities deploy integrated delivery platforms across neonatal intensive care, cardiac surgery recovery, and general critical care units. FDA 510(k) clearance requirements and Joint Commission accreditation standards shape procurement specifications, favoring established vendors with predicate device histories. Consolidated health systems in the southeastern United States increasingly unbundle device procurement from gas supply contracts.
- Home Care:Portable generator miniaturization enables chronic pulmonary hypertension management outside institutional settings. Reimbursement pathways through Medicare durable medical equipment channels remain underdeveloped, constraining volume despite clinical efficacy demonstrations. Patient selection criteria focus on stable, compliant individuals with adequate caregiver support.
- Clinics:Outpatient respiratory services adopt compact delivery systems for diagnostic bronchoprovocation and therapeutic administration.
- Specialty Centers:Cardiac catheterization laboratories and pulmonary hypertension clinics require precise flow control for procedure-specific indications.
Hospitals concentrate procurement volume while home care expands most quickly pending reimbursement clarity.
Technology:
Technology selection tracks application environment constraints, with photometric accuracy traded against electrochemical portability across care settings.
- Photometric:Ultraviolet absorption spectroscopy achieves reference-grade accuracy for nitrogen dioxide quantification in controlled critical care environments. Established installed bases in U.S. academic medical centers resist displacement due to protocol familiarity and calibration infrastructure investment. EPA emissions monitoring for vent gas abatement systems relies on photometric validation for regulatory compliance documentation.
- Electrochemical:Solid-state sensor miniaturization enables battery-powered operation for transport medicine and rural emergency departments. Humidity sensitivity and calibration drift under field conditions limit deployment confidence outside temperature-controlled environments. Hybrid architectures combining electrochemical primary sensing with photometric redundancy address liability concerns slowing portable adoption.
- Fluorescence:Chemiluminescence detection methods serve specialized research applications requiring trace-level sensitivity.
- Luminol:Chemical reaction-based detection supports point-of-care screening with reduced capital requirements.
Photometric platforms dominate installed value while electrochemical configurations climb the fastest on portability demand.
Application:
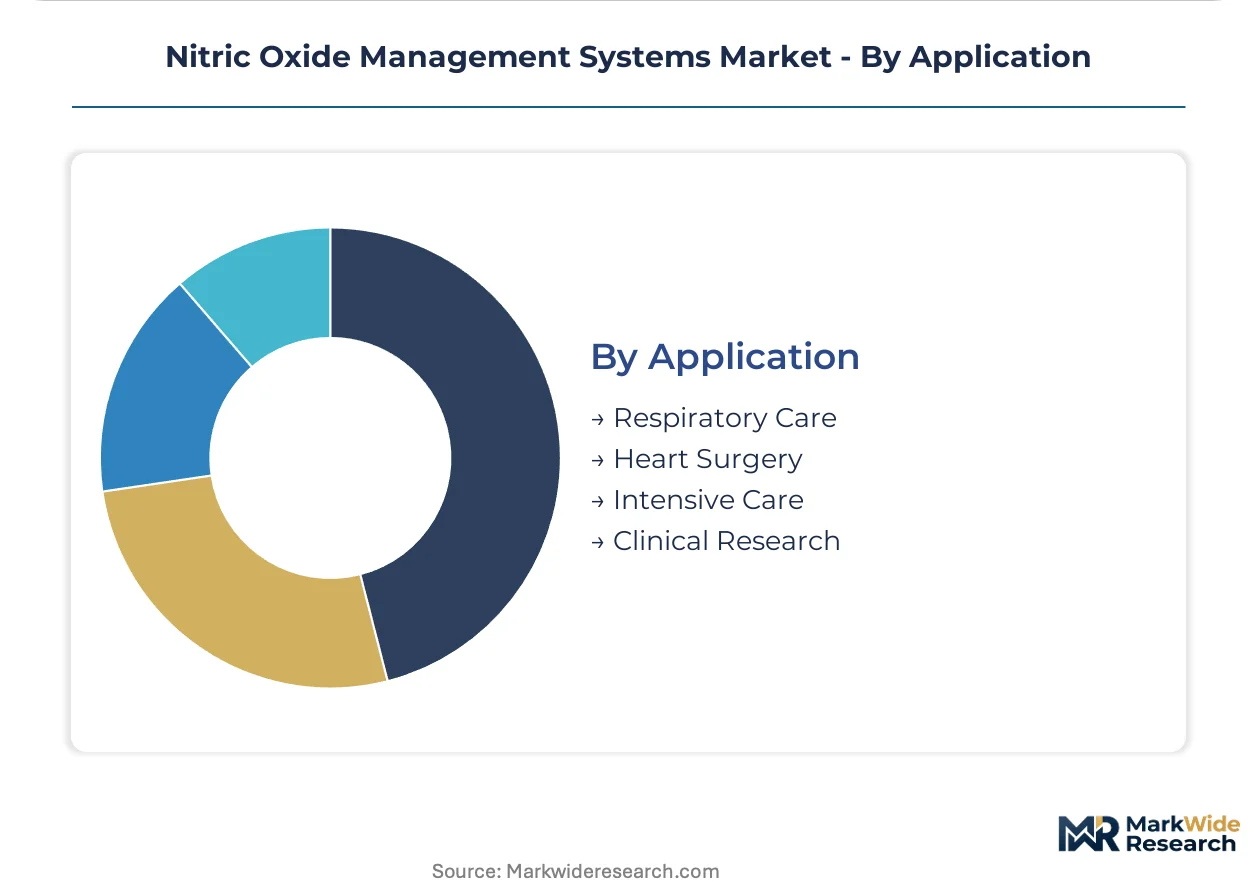
Application segmentation aligns with regulatory approval pathways and clinical evidence requirements, with respiratory indications holding the deepest validation history.
- Respiratory Care:Inhaled nitric oxide for persistent pulmonary hypertension of the newborn represents the most established indication with comprehensive safety and efficacy documentation. FDA labeling for hypoxic respiratory failure in term and near-term neonates supports standardized dosing protocols across U.S. hospital systems. Adult acute respiratory distress syndrome applications expand through off-label utilization and institutional review board protocols.
- Intensive Care:Broad-spectrum critical care deployment spans post-operative cardiac surgery, bridge-to-transplant support, and severe pneumonia management. Protocol heterogeneity across institutions complicates outcomes standardization and payer coverage determination. Real-time monitoring integration becomes mandatory as sicker patients receive therapy outside specialized neonatal units.
- Heart Surgery:Cardiopulmonary bypass-associated pulmonary hypertension responds to intraoperative and postoperative nitric oxide administration.
- Clinical Research:Mechanistic studies of nitric oxide biology in sepsis, transplantation, and vascular regulation drive specialized analyzer demand.
Respiratory care anchors the volume base while intensive care gains share at the steepest rate on monitoring technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity, accepting premium positioning for integrated safety systems, while procurement teams in India and Southeast Asia prioritize capital efficiency over monitoring sophistication.
United States
Academic medical centers in California and Texas drive replacement demand as EPA emissions deadlines for vent gas abatement approach. FDA 510(k) pathway streamlining accelerates predicate-device approvals for neonatal delivery systems. The Research Triangle in North Carolina concentrates clinical trial activity for portable generator validation.
Germany
Industrial gas infrastructure and precision engineering capabilities support high-specification hospital installations. EU MDR and F-Gas Regulation compliance requirements favor integrated suppliers with captive pharmaceutical-grade production. The Rhine-Ruhr metropolitan region anchors procurement decision-making for consolidated European health systems.
Japan
PMDA priority review vouchers for pediatric rare disease indications accelerate approval timelines for novel delivery modalities. METI industrial policy supports domestic manufacturing of miniaturized electrochemical sensors. The Kanto region surrounding Tokyo concentrates neonatal intensive care capacity and associated equipment procurement.
China
Hospital construction in tier-two cities expands addressable demand for cylinder-based delivery platforms. NMPA regulatory harmonization with international standards reduces approval friction for multinational device submissions. The Yangtze River Delta clusters medical device distribution and service infrastructure.
India
Price-sensitive procurement in public sector hospitals favors basic delivery equipment without integrated monitoring. CDSCO medical device rules create compliance thresholds that filter out non-specialized suppliers. Metropolitan centers in Maharashtra and Karnataka concentrate private hospital investment capable of absorbing premium-tier systems.
Nitric Oxide Management Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with gas suppliers commanding bundled contract economics while device-centric challengers erode attach rates through portable alternatives. Three archetypes dominate: pharmaceutical-grade manufacturers with backward integration into delivery platforms, industrial gas majors leveraging captive supply networks, and miniaturization specialists attacking cylinder logistics. Consolidated health systems increasingly unbundle procurement, while EPA compliance deadlines force accelerated replacement cycles.
Within the integrated pharmaceutical tier, Mallinckrodt Pharmaceuticals and VERO Biotech occupy positions defined by vertical control over drug-device combinations. Linde plc exemplifies the industrial gas archetype through captive medical-grade production. Beyond Air represents the portable generation challengers eliminating cylinder infrastructure for emerging care settings.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| VERO Biotech |
| Getinge AB |
| Linde plc |
| Air Liquide Healthcare |
| Beyond Air |
| International Biomedical |
| Bellerophon Therapeutics |
| SLE Ltd. |
| Others |
Value Network & Pricing Analysis
Portable electrochemical generator substitution for cylinder-based delivery simultaneously redistributes supply geography toward miniaturized manufacturing hubs and compresses pricing power for incumbent gas suppliers. FDA 510(k) pathway streamlining accelerates predicate-device approvals, eroding the regulatory moat that historically protected premium positioning for integrated pharmaceutical-grade manufacturers.
Pricing Analysis
After-sales service contracts and recurring consumable attach rates drive lifetime value for established delivery equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with integrated nitrogen dioxide monitoring from basic cylinder-based units. Pricing pressure stems from portable generator commoditization in transport medicine segments. Rural emergency departments exhibit highest price sensitivity, while academic medical centers in California and Texas accept premium positioning for EPA-compliant abatement systems.
Supply Chain Analysis
Just-in-time cylinder logistics dominate hospital procurement, though strategic stockpiling of pharmaceutical-grade nitric oxide concentrates among three North American integrated suppliers creates vulnerability to facility-level disruptions. Supply draws from captive production in the United States, Germany, and Japan, with sensor miniaturization components sourcing from East Asian electronics manufacturing. Single-source vulnerability concentrates in medical-grade gas synthesis. Distribution runs through consolidated health system direct agreements and group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) predicate device histories and EPA emissions compliance documentation create switching costs that protect incumbent installed bases.
For Market Incumbents: Shield service revenue pools by embedding predictive maintenance analytics into cylinder logistics contracts. Deepen backward integration into pharmaceutical-grade gas production to defend margin position against portable generator substitution. Prioritize catalytic converter integration for California and Texas academic medical center retrofit deadlines.
For New Entrants and Emerging Players: Anchor in rural emergency departments and transport medicine units where cylinder handling logistics create acute pain points. Target home respiratory care configurations pending Medicare durable medical equipment reimbursement pathway development. Pursue hospital system pilot programs demonstrating total cost of ownership superiority over cylinder-based economics.
For Investors and Strategic Acquirers: The market sits at a substitution phase that favors miniaturization specialists with electrochemical sensor platforms. Long-term viability hinges on reimbursement infrastructure maturation for chronic pulmonary hypertension management outside institutional settings. Acquisition targets should demonstrate portable generator clinical validation and FDA 510(k) clearance progress. Watch PMDA priority review voucher utilization in Japan as inflection indicator for pediatric rare disease designation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Device Clearance | Accelerates commercialization timelines for neonatal delivery system innovations. |
| EPA Emissions Abatement Retrofit | Forces capital replacement cycles at high-volume academic medical centers. |
| Portable Generator Miniaturization | Enables point-of-care deployment beyond traditional critical care infrastructure. |
| Hospital System Direct Contracting | Erodes group purchasing organization leverage through transparent pricing. |
| Electrochemical-Photometric Hybrid Sensing | Addresses liability concerns slowing portable adoption in transport medicine. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and critical care clinicians and refined through secondary validation. Primary fieldwork drew from FDA 510(k) submission databases, EPA emissions permitting records, hospital procurement contract registries, and medical device adverse event reporting systems. Bottom-up equipment unit economics and top-down health system capital expenditure triangulation anchored market sizing.
Variance decomposition across product type, technology platform, end-user configuration, and geographic regulatory cluster shaped analytical framework construction. CAGRs were derived from installed base replacement cycle analysis and emerging application penetration curves. Modeled inputs incorporated EPA compliance deadline schedules, PMDA priority review voucher award patterns, and Medicare reimbursement pathway development status.
Decision-makers should treat outputs as directional under assumptions of stable FDA review timelines and cylinder logistics cost structures; material deviation would warrant model refresh. Revision becomes warranted when portable generator clinical evidence crosses reimbursement threshold or EPA emissions enforcement intensity shifts materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Chronic Respiratory Diseases Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Emphysema Treatment Market