
 Europe Acute Coronary Syndrome Market | 2026-2036
Europe Acute Coronary Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acute Coronary Syndrome Market Foresight
Emergency department protocols across Western European hospitals is recalibrating ACS triage and intervention workflows. AstraZeneca leverages its antiplatelet portfolio to anchor positions in high-volume cardiac centers. Sanofi competes through sustained R&D intensity in anticoagulant formulations. Pfizer dominates oral beta blocker distribution across integrated hospital networks.
Acute Coronary Syndrome encompasses a spectrum of cardiac ischemic conditions including unstable angina and myocardial infarction, diagnosed through elevated cardiac troponins and characteristic electrocardiographic changes requiring immediate revascularization or pharmacological intervention. Antiplatelet agents command the largest revenue pool within product type segmentation due to dual-therapy mandates post-percutaneous coronary intervention. Intravenous delivery modes capture premium pricing in inpatient settings where rapid therapeutic onset is critical, while telehealth care settings represent the fastest-expanding channel as remote cardiac monitoring protocols gain clinical acceptance.
EMA regulatory frameworks govern pharmaceutical approval pathways for novel ACS therapeutics, while the EU Medical Device Regulation imposes stringent clinical evidence requirements on coronary stent manufacturers seeking CE marking. REACH compliance additionally shapes material selection in device coatings and drug-eluting polymer matrices. Stakeholders must monitor evolving MDR transition timelines and national reimbursement divergence across EU member states to optimize market access sequencing.
Market Dynamics
The EU Medical Device Regulation is compressing stent certification timelines while hospital emergency departments accelerate ACS protocol standardization across Western Europe, creating a bifurcation between established manufacturers with clinical data reserves and entrants facing evidence generation bottlenecks.
Growth Catalysts
- Dual-antiplatelet therapy mandates:Post-PCI pharmacological protocols in German and French cardiac centers drive sustained demand for combination regimens. EMA guidelines reinforce extended treatment durations.
- Telehealth cardiac monitoring:Remote patient surveillance platforms in the United Kingdom expand post-discharge care continuity. NHS digital transformation programs accelerate reimbursement alignment.
- Bioresorbable scaffold innovation:Polymer-based vascular restoration technologies advance through controlled-release coating refinement. REACH compliance frameworks govern material biocompatibility standards.
Market Restraints
- MDR clinical evidence requirements:CE marking pathways for drug-eluting stents demand expanded patient follow-up data. Smaller device manufacturers face capital constraints for pivotal trials.
- Heparin supply concentration:Anticoagulant active pharmaceutical ingredient production clusters in limited European manufacturing sites. Geopolitical friction exposes inventory vulnerability.
- Generic beta blocker substitution:Oral cardiovascular therapy commoditization compresses branded pricing power. Hospital formularies prioritize cost-minimized procurement.
Strategic Opportunities
- Eastern European hospital modernization:Polish and Romanian cardiac catheterization laboratory expansion programs create infrastructure deployment demand. EU cohesion funds finance equipment acquisition.
- AI-integrated ECG interpretation:Machine learning diagnostic algorithms converge with portable monitoring hardware. Emergency department triage acceleration protocols validate clinical utility.
- CSRD sustainability disclosure:Corporate sustainability reporting mandates favor manufacturers with carbon-transparent supply chains. ESG-linked procurement criteria penetrate hospital purchasing.
Industry Challenges
- Interventional cardiologist workforce gaps:Percutaneous coronary intervention specialization training programs face enrollment constraints. Retirement waves in France and Germany intensify staffing pressure.
- Legacy health information system integration:Telehealth platform interoperability with hospital electronic medical records requires custom interface development. Data standardization delays fragment implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acute Coronary Syndrome Market |
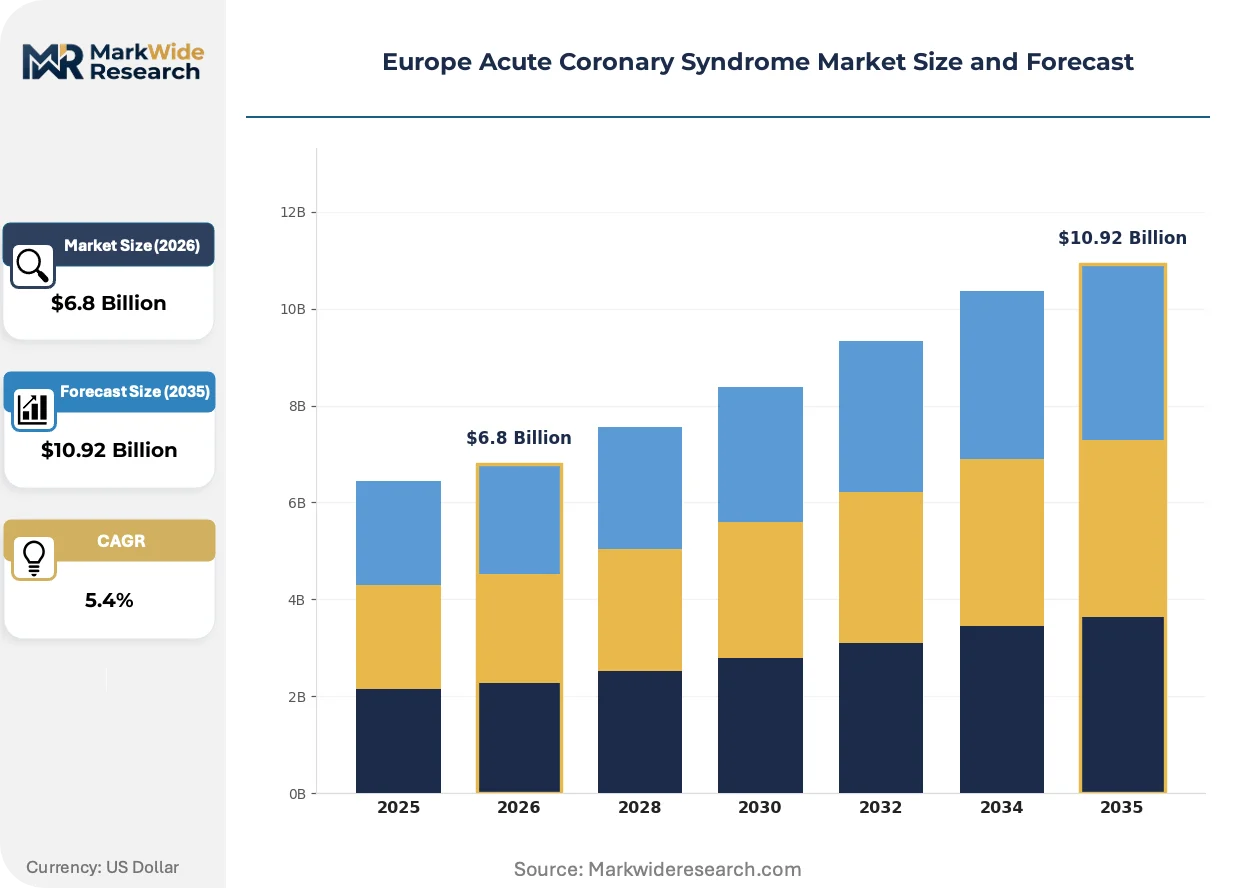
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Antiplatelet Agents, Anticoagulants, Beta Blockers Delivery Mode: Oral, Intravenous, Sublingual, Transdermal End User: Hospitals, Cardiology Clinics, Emergency Departments, Homecare Care Setting: Inpatient, Outpatient, Telehealth, Rehabilitation |
| Companies Covered | Pfizer, Merck, AstraZeneca, Johnson & Johnson, Boehringer Ingelheim, Sanofi, Bristol Myers Squibb, Daiichi Sankyo, Novartis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acute Coronary Syndrome Market Shifts & Advancements
Digital diagnostic integration and polymer science advances are restructuring how acute coronary syndrome is detected, treated, and monitored across European care pathways. Three developments warrant particular attention.
High-sensitivity cardiac troponin assays are overtaking conventional biomarker thresholds in emergency department triage protocols. Swedish and Dutch hospital networks have adopted next-generation diagnostic platforms that compress time-to-diagnosis intervals. This technology is enabling same-day discharge protocols for low-risk patients while reallocating catheterization laboratory capacity toward confirmed acute cases.
The EU Medical Device Regulation transition timeline extension has modified stent manufacturer commercialization strategies. MDR Article 120 transitional provisions now govern legacy device market continuity while new entrants face intensified notified body scrutiny. Coronary intervention product categories with limited predicate equivalence are experiencing the most pronounced regulatory friction and certification backlog accumulation.
Hospital procurement consortia are consolidating cardiovascular device purchasing across integrated delivery networks. French regional hospital groups and English NHS foundation trusts are centralizing antiplatelet and anticoagulant tender processes. This concentration is most visible in Germany, where university hospital alliances negotiate multi-year supply agreements that displace fragmented vendor relationships.
Europe Acute Coronary Syndrome Market Segmentation
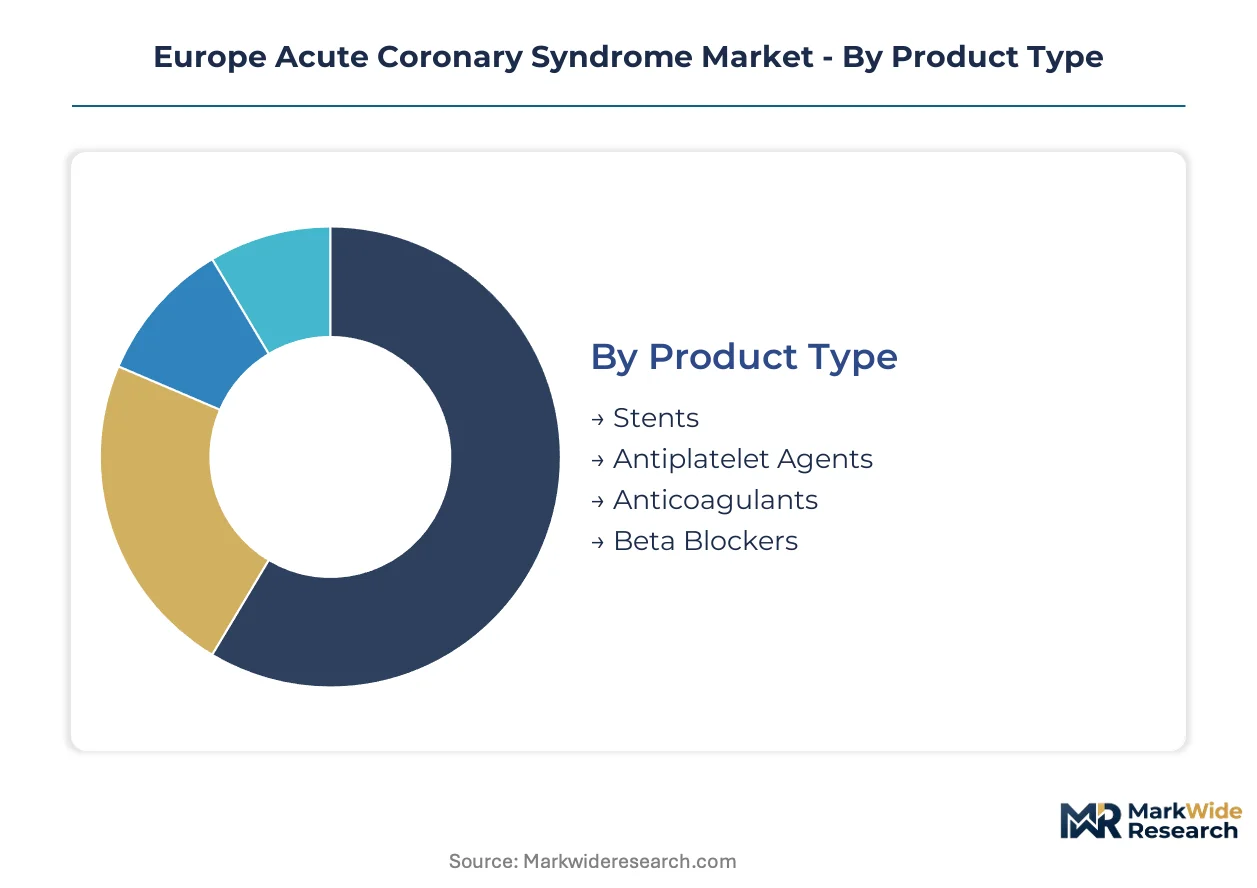
European ACS therapeutics fragment across four intersecting dimensions that determine pricing power, regulatory pathway, and channel access. Manufacturers configure portfolio strategy around product type concentration, delivery mode urgency, and care setting migration patterns.
Product Type:
Biomaterial composition and pharmacological mechanism define competitive differentiation across the therapeutic spectrum.
- Stents:Metallic and polymer-based vascular scaffolds deliver mechanical revascularization with drug-eluting coatings that suppress neointimal proliferation. German and French cardiac centers concentrate demand for next-generation bioresorbable platforms as MDR compliance timelines compress legacy device commercialization.
- Antiplatelet Agents:P2Y12 inhibitors and aspirin combinations constitute dual-therapy protocols mandated post-percutaneous coronary intervention. Hospital formularies in the United Kingdom prioritize generic substitution where EMA guidelines permit, eroding branded pricing power in oral formulations.
- Anticoagulants:Heparin derivatives and direct oral anticoagulants interrupt thrombin generation in acute ischemic settings. Manufacturing concentration at limited European API sites exposes supply continuity risk under geopolitical friction.
- Beta Blockers:Cardioselective and non-selective adrenergic antagonists reduce myocardial oxygen demand in post-infarction management. Procurement consortia across NHS foundation trusts and German university hospital alliances drive commoditization pressure.
Antiplatelet agents lead on scale; bioresorbable stent innovation leads on momentum.
Delivery Mode:
Pharmacokinetic urgency and care setting infrastructure determine route selection and margin structure.
- Intravenous:Rapid therapeutic onset in catheterization laboratories and emergency departments commands premium pricing. Inpatient settings across Western European hospital networks absorb volume concentration where time-to-intervention protocols dominate clinical decision-making.
- Oral:Extended-release and immediate-release formulations enable post-discharge maintenance therapy. Pharmacy benefit managers in France and Germany negotiate tender-based procurement that compresses branded margins.
- Sublingual:Buccal absorption bypasses first-pass hepatic metabolism for rapid nitrate delivery in angina episodes. Emergency medical services and pre-hospital care networks in the United Kingdom deploy auto-injector formats.
- Transdermal:Patch-based delivery systems sustain steady-state plasma concentrations for chronic angina management. Homecare reimbursement fragmentation across EU member states constrains volume expansion.
Intravenous delivery leads on scale; transdermal platforms lead on momentum.
End User:
Clinical acuity and intervention capability shape purchasing authority and technical specification requirements.
- Hospitals:Integrated cardiovascular centers with catheterization laboratory capacity anchor stent and intravenous anticoagulant procurement. University hospital alliances in Germany consolidate multi-year supply agreements that displace fragmented vendor relationships.
- Cardiology Clinics:Outpatient diagnostic and stable patient management concentrates oral therapy dispensing. French regional hospital groups centralize antiplatelet tender processes across affiliated ambulatory networks.
- Emergency Departments:High-sensitivity troponin protocols and rapid revascularization pathways drive anticoagulant and intravenous antiplatelet demand. Swedish and Dutch hospital networks compress time-to-diagnosis intervals through next-generation diagnostic platform adoption.
- Homecare:Post-discharge monitoring and chronic therapy administration expands with remote patient surveillance platform integration. NHS digital transformation programs accelerate reimbursement alignment for telehealth-enabled cardiac monitoring.
Hospitals lead on scale; emergency departments lead on momentum.
Care Setting:
Reimbursement architecture and patient risk stratification govern site-of-care migration.
- Inpatient:Acute revascularization, hemodynamic stabilization, and intensive monitoring concentrate high-acuity intervention. German DRG-based reimbursement sustains revenue intensity for complex PCI procedures.
- Outpatient:Stable angina management and post-ACS follow-up shift to ambulatory settings under cost containment pressure. French clinic networks absorb volume as hospital-at-home programs expand eligibility.
- Telehealth:Remote ECG interpretation and patient-reported symptom surveillance gain clinical acceptance through NHS digital transformation and Dutch integrated care experiments. AI-integrated diagnostic algorithms validate emergency department triage acceleration protocols.
- Rehabilitation:Structured exercise and risk factor modification programs reduce recurrent event probability. Cardiac rehabilitation reimbursement varies across EU member state benefit structures.
Inpatient settings lead on scale; telehealth platforms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German cardiac catheterization laboratory network anchors European ACS intervention capacity, with university hospital alliances in Munich and Berlin driving protocol standardization across Western Europe.
Germany
Dual-antiplatelet therapy mandates in Bavarian and North Rhine-Westphalian cardiac centers sustain demand for combination regimens post-PCI. EMA guidelines reinforce extended treatment durations through national reimbursement alignment. The Munich-Berlin corridor concentrates bioresorbable scaffold clinical trials as MDR transition timelines compress legacy device commercialization.
United Kingdom
NHS digital transformation programs accelerate telehealth cardiac monitoring reimbursement across English foundation trusts. High-sensitivity troponin assays in London and Manchester emergency departments compress time-to-diagnosis intervals. The Midlands and North England absorb volume as hospital-at-home programs expand post-discharge eligibility.
France
French regional hospital groups centralize antiplatelet and anticoagulant tender processes across Île-de-France and Auvergne-Rhône-Alpes. ANSM pharmacovigilance frameworks govern post-market surveillance of novel antithrombotic agents. The Lyon cardiac cluster advances AI-integrated ECG interpretation through emergency department triage acceleration protocols.
Sweden
Swedish hospital networks adopted next-generation diagnostic platforms enabling same-day discharge protocols for low-risk ACS patients. REACH compliance frameworks govern material biocompatibility standards in coronary stent coatings. The Stockholm-Uppsala medical corridor reallocates catheterization laboratory capacity toward confirmed acute cases through biomarker-driven triage.
Poland
Polish cardiac catheterization laboratory expansion programs create infrastructure deployment demand through EU cohesion fund financing. Warsaw and Krakow academic medical centers absorb Western European protocol transfer for emergency department ACS standardization. Regional hospital modernization concentrates procurement authority for cardiovascular device purchasing consortia.
Europe Acute Coronary Syndrome Market Competitive Landscape
Portfolio diversification dominates the current landscape as pharmaceutical manufacturers recalibrate around dual-therapy mandates and device makers navigate MDR evidence requirements. The vendor base clusters into three tiers: integrated pharmaceutical-device conglomerates with clinical data reserves, mid-cap anticoagulant specialists facing API supply concentration risk, and generic beta blocker manufacturers competing on hospital formulary cost minimization. Strategic archetypes include antiplatelet portfolio anchors, bioresorbable scaffold innovators, and telehealth platform integrators. M&A activity and strategic partnerships concentrate among firms seeking vertical control over drug-eluting polymer supply chains.
Among Anglo-Swedish pharmaceutical manufacturers, AstraZeneca occupies a position exemplifying antiplatelet portfolio anchoring in high-volume cardiac centers. Sanofi represents sustained R&D intensity in anticoagulant formulations within the French-based tier. Pfizer sits within the scale-driven segment of oral beta blocker distribution across integrated hospital networks. These three entities illustrate divergent strategic responses to EMA regulatory frameworks and national reimbursement divergence.
| Leading Market Players |
|---|
| Pfizer |
| Merck |
| AstraZeneca |
| Johnson & Johnson |
| Boehringer Ingelheim |
| Sanofi |
| Bristol Myers Squibb |
| Daiichi Sankyo |
| Novartis |
| Others |
Supply & Pricing Matrix
Bioresorbable scaffold manufacturing transitions from conventional metallic platforms to polymer-based vascular restoration technologies, simultaneously elevating R&D cost burdens for device makers and concentrating production capability among REACH-compliant European coating specialists with validated drug-eluting polymer matrices.
Pricing Analysis
Input-cost pass-through from heparin active pharmaceutical ingredient concentration at limited European manufacturing sites elevates anticoagulant pricing volatility, while dual-antiplatelet therapy mandates in German and French cardiac centers sustain premium positioning for P2Y12 inhibitors against generic substitution pressure. Three-tier pricing structure across premium bioresorbable scaffolds, standard drug-eluting stents, and economy metallic platforms reflects MDR certification tier differentiation. Price differentiation stems from CE marking pathway complexity and volume scale procurement by hospital consortia. Cost compression in oral beta blockers intensifies because NHS foundation trusts and German university hospital alliances prioritize tender-based cost minimization. Cardiology clinics exhibit highest price sensitivity for maintenance therapies; catheterization laboratories remain least sensitive for acute intervention products.
Supply Chain Analysis
Single-source vulnerability sits with heparin API production clustering in Spain and Italy alongside antiplatelet active pharmaceutical ingredient manufacturing in Ireland and Switzerland. Coronary stent metallic substrates draw from German precision engineering suppliers and polymer coating materials from Dutch specialty chemical producers. REACH compliance restrictions on drug-eluting polymer biocompatibility standards create regulatory friction for coating material qualification. Distribution runs through hospital procurement consortia across French regional hospital groups and English NHS foundation trusts, consolidating vendor relationships into multi-year supply agreements that displace fragmented purchasing patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on bioresorbable scaffold premium-tier adoption offsetting generic commoditization in oral cardiovascular therapies, with MDR transition timelines compressing legacy device commercialization windows.
For Market Incumbents: Lock in catheterization laboratory relationships through extended dual-antiplatelet therapy protocol partnerships that anchor formulary positioning against generic substitution threats. Deepen backward integration into drug-eluting polymer supply chains to secure REACH-compliant coating material continuity as regulatory scrutiny intensifies. Prioritize AI-integrated ECG interpretation platform development to capture telehealth reimbursement alignment through NHS digital transformation programs. For New Entrants and Emerging Players: EU Medical Device Regulation Article 120 transitional provisions in Germany and France open a window for bioresorbable scaffold innovators with clinical data reserves to establish positions before legacy device market continuity expires. Target Polish and Romanian cardiac catheterization laboratory expansion programs financed through EU cohesion funds as the most penetrable geography. Pursue hospital system partnership go-to-market angles with Warsaw and Krakow academic medical centers transferring Western European ACS protocol standardization. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap anticoagulant specialists facing API supply concentration risk and generic beta blocker manufacturers competing on hospital formulary cost minimization. Five-to-ten year viability favors integrated pharmaceutical-device conglomerates with clinical data reserves and vertical control over drug-eluting polymer supply chains. Watch MDR notified body certification backlog accumulation as the inflection indicator for stent manufacturer competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 120 compliance governs bioresorbable scaffold commercialization timelines across German and French cardiac centers. |
| Hospital System Partnership | University hospital alliances in Munich and Berlin consolidate multi-year supply agreements displacing fragmented vendor relationships. |
| Backward Integration | In-house production of drug-eluting polymer matrices secures REACH-compliant coating material qualification continuity. |
| Software Companion Development | AI-integrated ECG interpretation validates emergency department triage acceleration protocols in Swedish hospital networks. |
| Reimbursement Strategy | NHS digital transformation programs accelerate telehealth cardiac monitoring alignment across English foundation trusts. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and clinical trial registry monitoring — were reconciled through primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from EMA submission documents, CE marking databases, NHS procurement records, and hospital financial disclosures. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Historical procedure volume trajectories were cross-referenced against expert panel inputs on protocol adoption timelines across the projection horizon. Segmentation dimensions encompassed product type, delivery mode, end user, and care setting migration patterns. CAGRs were derived from fitted growth curves calibrated to reimbursement alignment events and regulatory transition milestones. Forecast inputs incorporated MDR implementation timelines and EU cohesion fund disbursement schedules for Eastern European infrastructure expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MDR transition timeline extensions and geopolitical friction affecting heparin API supply continuity. Forecasts reflect documented assumptions on telehealth reimbursement parity achievement and bioresorbable scaffold clinical evidence generation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Global Statin Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market