
 Cardiac Safety Services Market | 2026-2036
Cardiac Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Safety Services Market Analysis
Cardiac safety talent is bifurcating between electrophysiology specialists and data science generalists, constraining capacity at mid-tier contract research organizations while unlocking AI-enabled scale at top-tier platforms. Laboratory Corporation of America Holdings leverages its central laboratory network to anchor integrated safety testing workflows across Phase I-III trials. Medpace sustains competitive density through therapeutic specialization in oncology-cardiology crossover studies where cardiac toxicity monitoring commands premium pricing.
Cardiac safety services encompass the design, execution, and regulatory documentation of cardiovascular risk assessment protocols for investigational drugs and medical devices, incorporating continuous ECG waveform analysis, cardiac imaging biomarker quantification, and statistical modeling of QT interval prolongation to satisfy FDA and EMA submission requirements. Electrocardiogram monitoring occupies the largest revenue pool due to its mandatory inclusion in virtually all drug development programs, while wearable devices within the technology dimension represent the fastest-expanding segment as pharmaceutical sponsors seek decentralized trial architectures. Cloud-based platforms concentrate margin accretion through subscription-based analytics licensing that reduces per-study labor intensity.
FDA's ICH E14 Q&A updates and EMA's Committee for Medicinal Products for Human Use guidance collectively elevate the evidentiary bar for cardiac safety dossiers, compelling sponsors to expand outsourcing rather than maintain in-house electrophysiology cores. HIPAA and GDPR data residency requirements constrain vendor selection for multinational trials, favoring providers with dual-continent server infrastructure and certified quality management systems. Stakeholders must monitor evolving regulatory acceptance of digital biomarkers from wearable sensors as these technologies challenge the primacy of traditional 12-lead ECG in future safety guidelines.
Market Dynamics
Cardiac safety services face structural compression as FDA and EMA tighten evidentiary standards for QT prolongation studies, forcing sponsors to outsource complex electrophysiology work rather than maintain internal capabilities. This regulatory ratchet concentrates demand among vendors with certified central laboratories and statistical modeling expertise.
Growth Catalysts
- ICH E14 Q&A Revisions:Updated FDA and EMA guidance expands mandatory thorough QT study requirements for small molecules, compelling biopharmaceutical sponsors to procure specialized cardiac safety monitoring services.
- Oncology-Cardiology Crossover:Immuno-oncology agents with known cardiotoxicity profiles require intensive ECG surveillance, creating sustained demand for integrated safety testing across Phase I-III trials.
- Wearable Sensor Integration:Continuous cardiac monitoring through patch-based devices enables decentralized trial architectures, reducing site burden while capturing richer ambulatory data.
Market Restraints
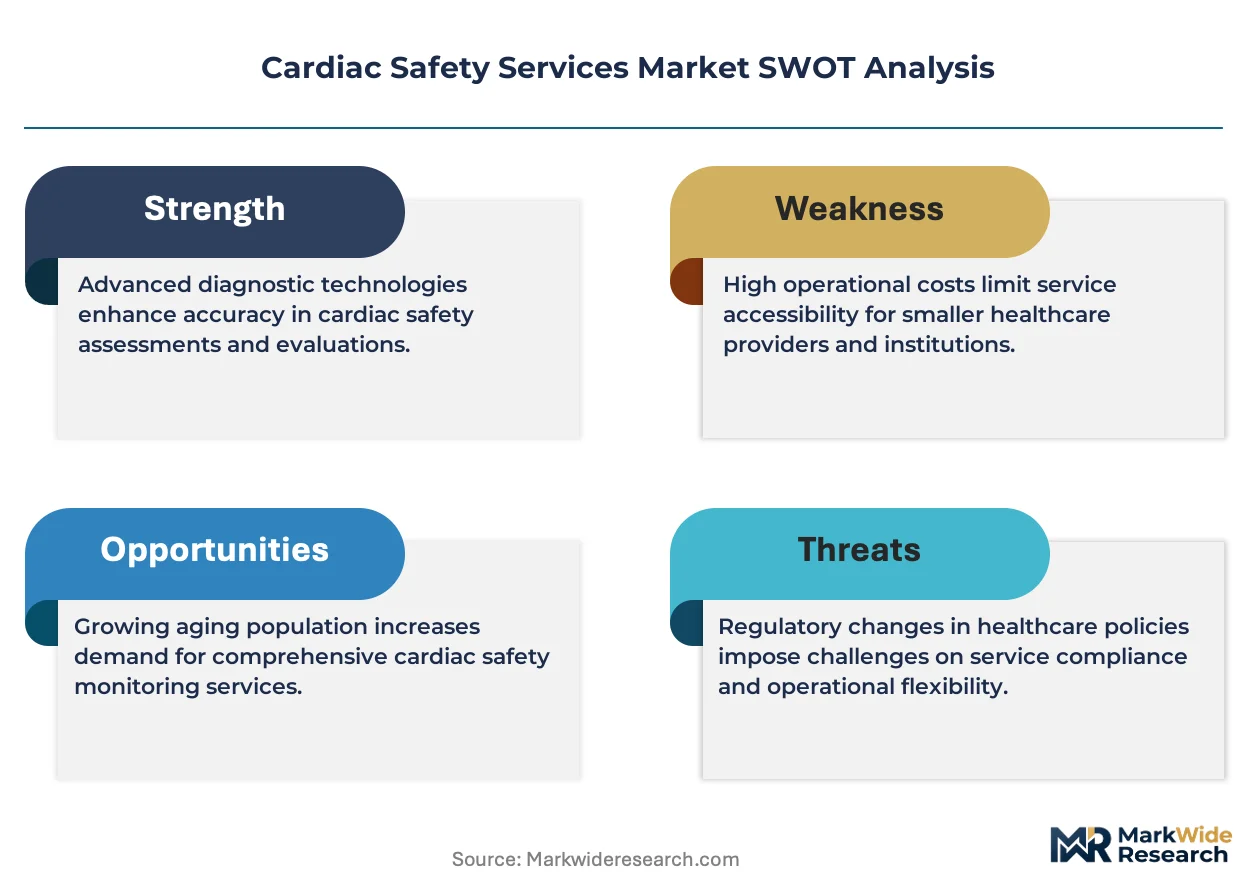
- Electrophysiologist Scarcity:Qualified cardiac safety specialists command premium compensation, constraining workforce expansion at mid-tier contract research organizations.
- Data Residency Compliance:HIPAA and GDPR server-location mandates fragment vendor selection, disqualifying providers lacking dual-continent infrastructure.
- Legacy ECG Hardware Depreciation:Capital-intensive 12-lead systems face accelerated obsolescence as cloud-based analytics platforms reduce per-study labor intensity.
Strategic Opportunities
- Digital Biomarker Acceptance:FDA pilot programs evaluating wearable-derived QT metrics could validate algorithmic cardiac safety assessment, displacing traditional Holter monitoring.
- Asia-Pacific Expansion:Japan's PMDA and China's NMPA are harmonizing ICH E14 standards, opening procurement pathways for Western safety service providers.
- Subscription Analytics Licensing:Cloud platforms can capture recurring revenue through software-as-a-service models that reduce sponsor dependence on per-study contracting.
Industry Challenges
- AI Validation Requirements:Machine learning algorithms for automated ECG interpretation lack standardized regulatory pathways, delaying deployment in submission-grade safety studies.
- Interoperability Friction:Wearable device data formats remain proprietary, forcing vendors to maintain expensive multi-platform integration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Safety Services Market |
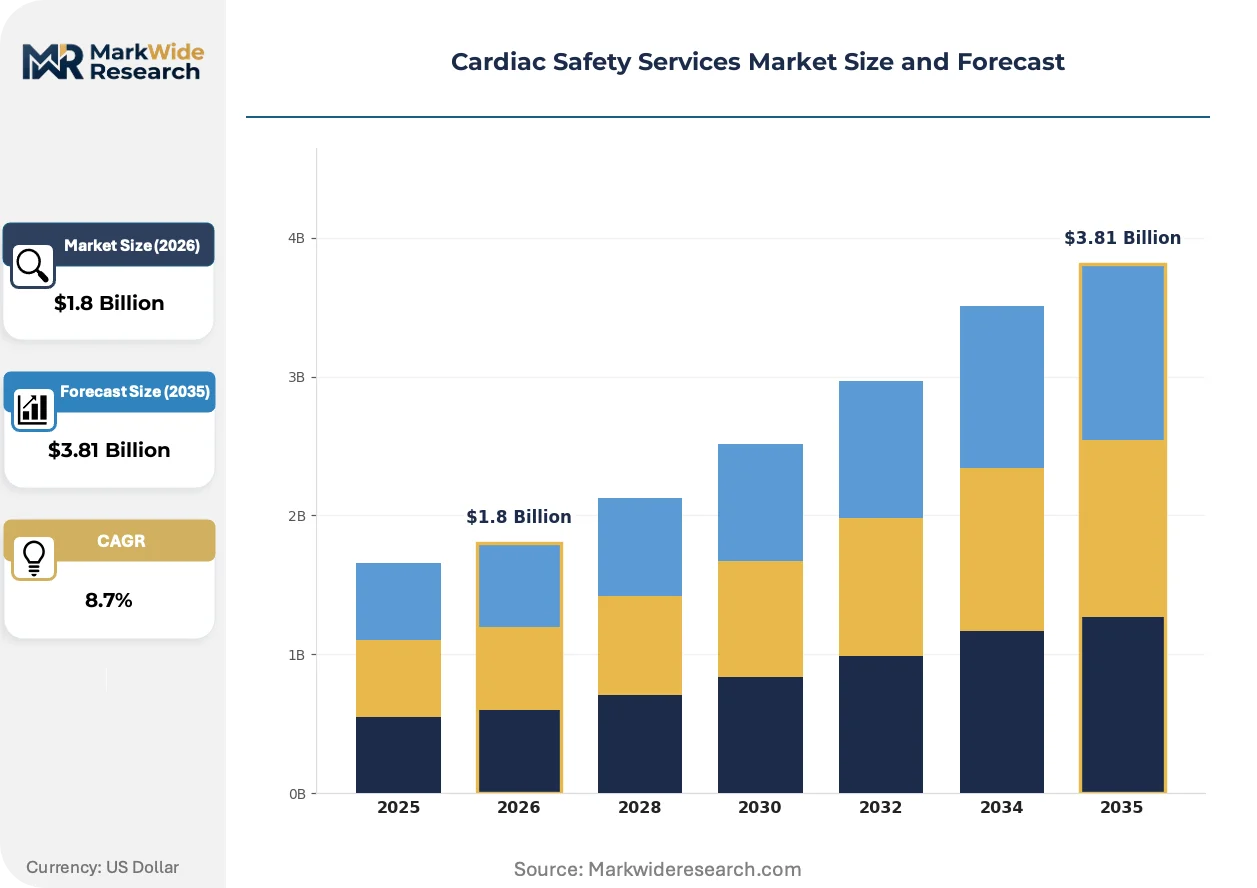
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electrocardiogram Monitoring, Holter Monitoring, Cardiac Imaging, Cardiac Event Monitoring Technology: Wearable Devices, Telemonitoring Systems, Digital Health Solutions, Cloud-based Platforms End User: Clinical Research Organizations, Pharmaceutical Companies, Hospitals, Diagnostic Labs Application: Drug Trials, Device Evaluation, Patient Monitoring, Risk Assessment |
| Companies Covered | Laboratory Corporation of America Holdings, Medpace, Koninklijke Philips N.V., Clario, IQVIA, Ncardia, Certara, Eurofins Scientific, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Safety Services Market Emerging Trajectories
Wearable cardiac monitoring hardware is compressing study timelines while cloud analytics platforms restructure how sponsors procure safety services. These shifts are redistributing value from labor-intensive ECG reading toward algorithmic interpretation and decentralized data capture.
Patch-based ambulatory monitors are replacing Holter recorders in Phase II-III trials. Pharmaceutical sponsors in immuno-oncology and gene therapy programs are adopting these devices for 30-day continuous monitoring. The technology is miniaturizing hardware footprints while expanding enrollment to homebound patients previously excluded from site-based studies.
FDA's draft guidance on digital health technologies for drug development is formalizing pathways for wearable-derived cardiac endpoints. This policy shift elevates evidentiary requirements for algorithm validation while creating compliance burdens for sponsors unfamiliar with software-as-medical-device frameworks. Oncology trials with cardiotoxicity signals are most affected, with sponsors accelerating vendor qualification for digital biomarker platforms.
Buyers are unbundling safety testing from full-service clinical research contracts. Mid-sized biotechnology firms now procure standalone ECG core laboratories and statistical consulting, bypassing traditional integrated CRO relationships. This pattern concentrates in the United States, where sponsor finance teams scrutinize line-item outsourcing decisions with greater granularity than European counterparts.
Cardiac Safety Services Market Segmentation
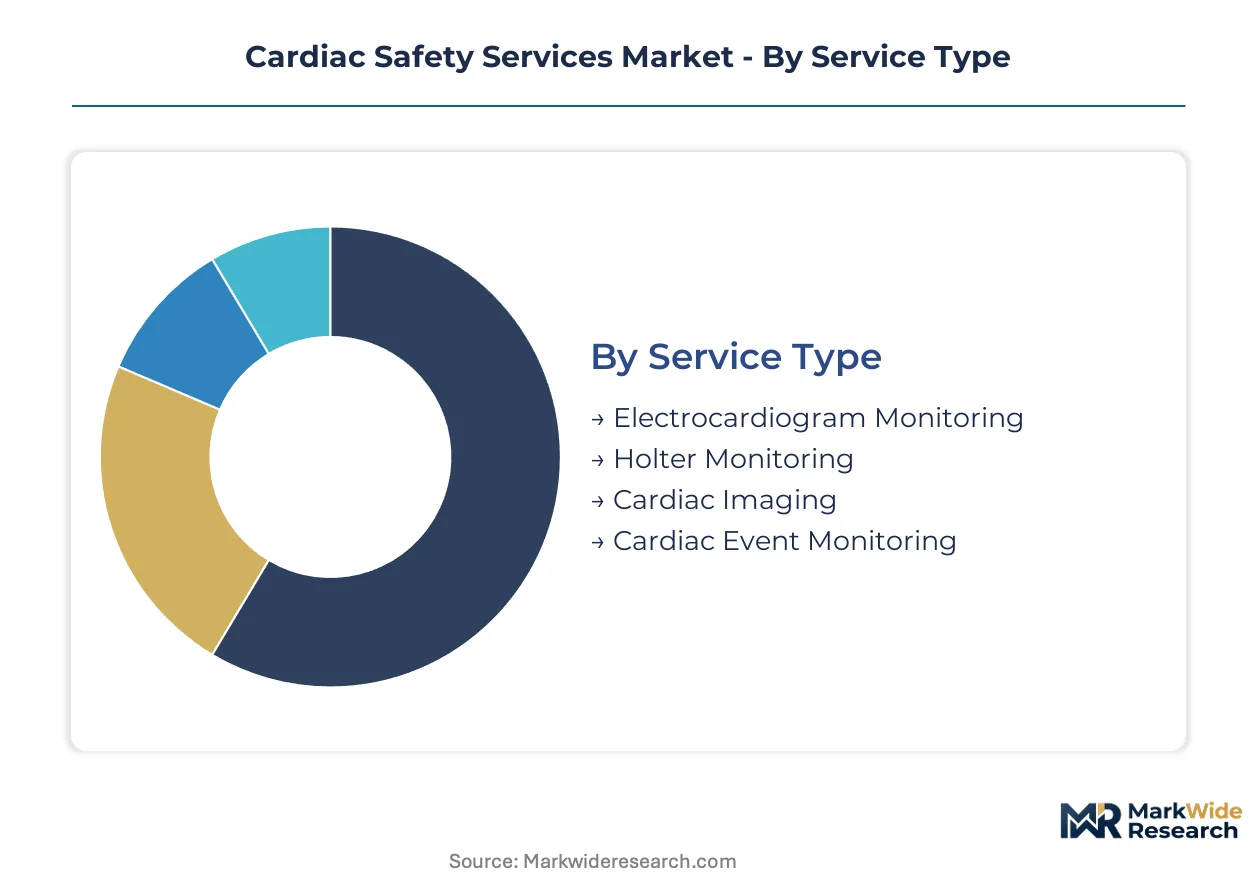
Cardiac safety service procurement fragments across four distinct dimensions, each reflecting divergent technical requirements and buyer sophistication. Service type and technology dimensions exhibit the most acute substitution pressures as digital platforms displace legacy hardware.
Service Type:
Substitution pressure intensifies most acutely in continuous monitoring segments where patch-based wearables erode traditional recorder economics.
- Electrocardiogram Monitoring:Standard 12-lead ECG acquisition and centralized interpretation remains mandatory for FDA submission-grade thorough QT studies. Pharmaceutical sponsors in the United States procure these services most intensively, though labor-intensive waveform reading faces margin compression from algorithmic alternatives.
- Holter Monitoring:Ambulatory 24-48 hour continuous recording captures transient arrhythmias during drug exposure windows. Demand concentrates among oncology-cardiology crossover trials where cardiotoxicity surveillance requires extended observation periods beyond standard clinic visits.
- Cardiac Imaging:Echocardiography and cardiac MRI quantification assess structural toxicity from novel biologics.
- Cardiac Event Monitoring:Patient-activated and auto-triggered devices capture symptomatic episodes during at-home trial participation.
Electrocardiogram monitoring anchors the volume base while cardiac imaging gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive hardware deployments from recurring software subscriptions.
- Wearable Devices:Patch-based ambulatory monitors enable 30-day continuous data capture with patient-borne hardware. Clinical research organizations adopt these most aggressively for decentralized trial architectures that reduce site visit burden.
- Cloud-based Platforms:Subscription analytics licensing reduces per-study labor intensity through algorithmic ECG interpretation and centralized data lakes. HIPAA and GDPR server-location mandates favor providers with dual-continent infrastructure.
- Telemonitoring Systems:Real-time transmission links patients to centralized monitoring centers during acute drug exposure phases.
- Digital Health Solutions:Integrated software-hardware combinations bundle device management with regulatory documentation workflows.
Cloud-based platforms command the highest margin expansion trajectory while wearable devices capture volume growth fastest.
End User:
Customer type determines procurement sophistication, with biotechnology firms unbundling services that large pharmaceutical sponsors historically purchased through integrated contracts.
- Pharmaceutical Companies:Large sponsors maintain captive electrophysiology cores for Phase I studies while outsourcing Phase II-III surveillance to specialized vendors. Internal resource constraints intensify outsourcing for complex oncology and gene therapy programs.
- Clinical Research Organizations:Full-service CROs procure standalone ECG core laboratories to complement their service menus, particularly for sponsor-requested cardiac safety add-ons.
- Diagnostic Labs:Hospital-affiliated laboratories seek entry into clinical trial services through ECG interpretation partnerships.
- Hospitals:Academic medical centers with embedded research units require safety monitoring for investigator-initiated trials.
Pharmaceutical companies dominate current procurement value while clinical research organizations expand their service integration most rapidly.
Application:
Regulatory stringency varies sharply across use cases, with drug trials demanding the most exhaustive documentation.
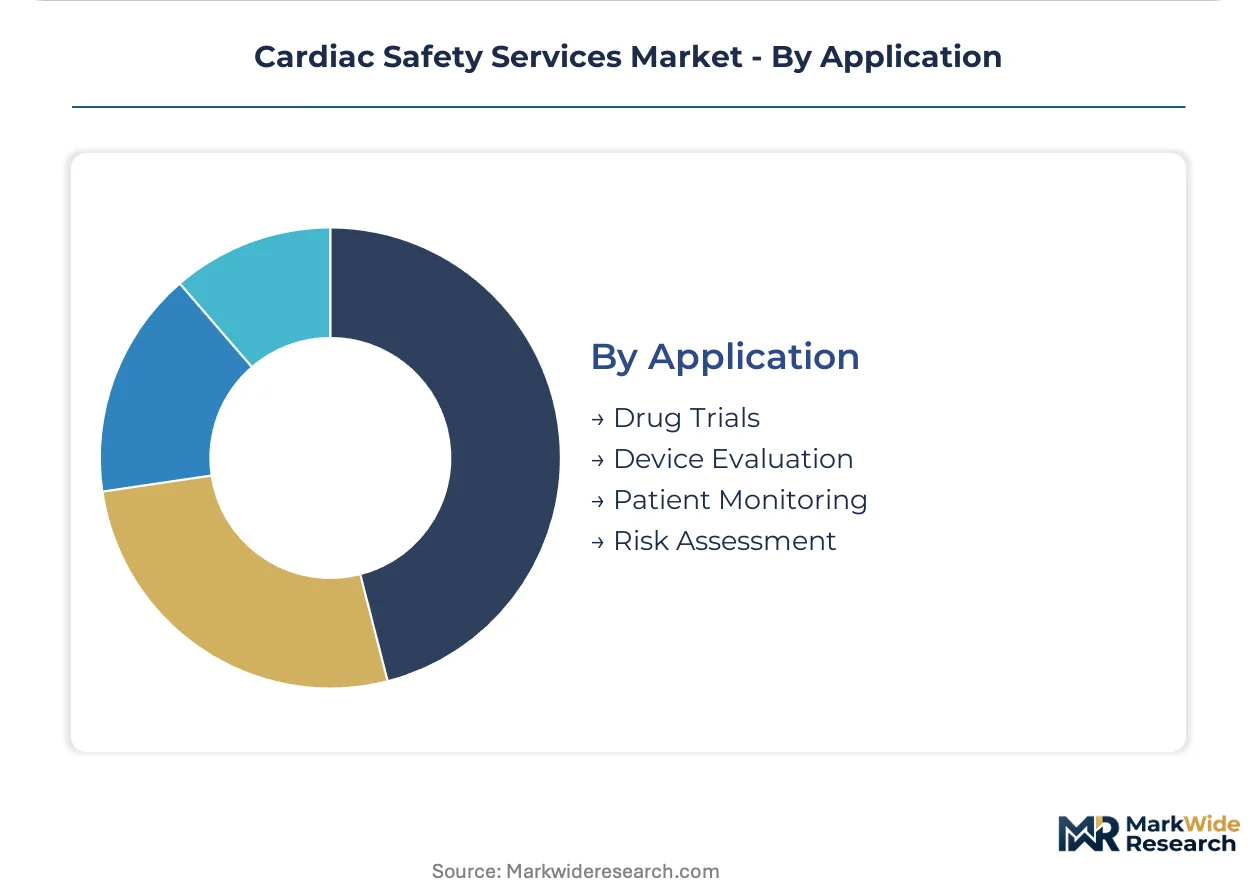
- Drug Trials:ICH E14-compliant thorough QT studies and oncology cardiotoxicity surveillance constitute the revenue core. FDA guidance revisions expand mandatory ECG requirements for small molecules and biologics alike.
- Device Evaluation:Implantable cardiac device trials require specialized electrophysiology expertise for arrhythmia induction protocols.
- Patient Monitoring:Post-market safety surveillance extends observation beyond controlled trial settings.
- Risk Assessment:Preclinical cardiac safety profiling informs go-no-go decisions before human dosing.
Drug trials generate the dominant revenue share while device evaluation applications demonstrate the most rapid regulatory harmonization across FDA and EMA standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's ICH E14 guidance anchors the United States as the dominant geography, though EMA standards in Europe and harmonization initiatives in Asia-Pacific are redistributing procurement patterns across multiple regulatory jurisdictions.
United States
Pharmaceutical sponsors in Massachusetts and North Carolina drive intensive ECG core laboratory procurement for oncology-cardiology crossover trials. FDA's 2023 ICH E14 Q&A revisions expanded mandatory thorough QT study requirements for small molecules. The Boston-Cambridge biotech corridor concentrates demand for integrated safety testing across Phase I-III programs.
Germany
EMA's Committee for Medicinal Products for Human Use guidance elevates evidentiary requirements for cardiac safety dossiers submitted from Frankfurt and Munich-based sponsors. Germany's national pharmaceutical regulator enforces strict adherence to ICH E14 statistical modeling standards. The Rhine-Main biopharma cluster generates sustained demand for centralized ECG interpretation services.
Japan
PMDA harmonization with ICH E14 standards is opening procurement pathways for Western safety service providers serving Tokyo and Osaka sponsors. Japan's national pharmaceutical regulator now accepts FDA-compliant thorough QT study designs for domestic submissions. The Kanto region's dense concentration of clinical research organizations intensifies competition for cardiac safety contracts.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for London and Cambridge sponsors running multinational trials. The UK's national pharmaceutical regulator maintains EMA-aligned cardiac safety standards while developing independent guidance. The Golden Triangle biotech cluster sustains demand for specialized electrophysiology monitoring services.
China
NMPA adoption of ICH E14 protocols is accelerating outsourcing by Shanghai and Beijing-based pharmaceutical firms previously reliant on in-house safety cores. China's national pharmaceutical regulator now mandates centralized ECG analysis for novel biologics submissions. The Yangtze River Delta biopharma hub is emerging as a procurement center for integrated cardiac safety services.
Cardiac Safety Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated central laboratory networks competing against specialized electrophysiology boutiques. The market structure concentrates around three tiers: full-service contract research organizations with captive safety units, standalone ECG core laboratories, and technology platforms offering algorithmic interpretation. Laboratory Corporation of America Holdings exemplifies the integrated archetype, while Medpace represents therapeutic specialization models. Dominant competitive moves include geographic expansion into Asia-Pacific markets and portfolio diversification into wearable-derived digital biomarkers.
Within the integrated laboratory tier, Laboratory Corporation of America Holdings and Eurofins Scientific occupy positions anchored by central laboratory networks that bundle cardiac safety testing with broader clinical trial services. Medpace exemplifies the therapeutic specialization archetype, with competitive positioning concentrated in oncology-cardiology crossover studies where cardiac toxicity monitoring commands premium pricing. IQVIA represents the data-scaling archetype, leveraging global trial infrastructure to capture multi-regulatory jurisdiction contracts.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Medpace |
| Koninklijke Philips N.V. |
| Clario |
| IQVIA |
| Ncardia |
| Certara |
| Eurofins Scientific |
| Charles River Laboratories |
| Others |
Supply Flow & Price Mechanics
Per-study contracting with volume-commitment clauses locks in supply access for pharmaceutical sponsors while anchoring price visibility across multi-phase trial programs. This structure concentrates procurement leverage among large biotechnology firms in the United States that can guarantee minimum ECG core laboratory throughput.
Pricing Analysis
Price spreads between United States and Western European cardiac safety services reach substantial multiples due to FDA submission-grade certification premiums and HIPAA-compliant infrastructure costs. The dominant pricing model rests on project-based fees for thorough QT studies with SaaS-tiered analytics subscriptions layered for ongoing surveillance. Price differentiation hinges on FDA 21 CFR Part 11 validation tier and therapeutic specialization depth. Cost compression in standard ECG interpretation is intensifying because algorithmic platforms reduce per-read labor intensity. Mid-tier biotechnology firms exhibit highest price sensitivity, while oncology-focused sponsors with cardiotoxicity liabilities accept premium positioning.
Supply Chain Analysis
Strategic stockpiling of certified electrophysiologist capacity dominates over just-in-time staffing as qualified cardiac safety specialists command premium compensation and extended recruitment cycles. Supply concentrates in the United States, Germany, and Japan where regulatory expertise clusters around FDA, EMA, and PMDA jurisdictions. Raw material dependencies include ECG electrode manufacturing, cloud server infrastructure, and proprietary wearable sensor hardware. Single-source vulnerability runs through concentrated electrophysiologist labor pools. Distribution feeds from centralized core laboratories to decentralized trial sites through HIPAA-compliant data transmission networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac safety services function as a service-attach opportunity where cloud-based analytics licensing expands faster than hardware deployment, with subscription revenue multiples exceeding traditional per-study margins.
For Market Incumbents: Secure electrophysiologist talent pools through exclusive employment arrangements and training pipeline investments. Defensive consolidation should target standalone ECG core laboratories in the Boston-Cambridge corridor to preempt competitive density. AI-enabled algorithmic interpretation platforms pose substitution threats that demand accelerated regulatory validation pathways. For New Entrants and Emerging Players: Differentiate on wearable-derived digital biomarker expertise as FDA pilot programs validate algorithmic QT assessment. White-space targets include Asia-Pacific expansion serving PMDA and NMPA harmonization, and mid-sized biotechnology firms unbundling safety testing from full-service CRO contracts. Direct sales to sponsor finance teams with line-item procurement authority offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors platforms with dual-continent infrastructure and certified quality management systems. Long-term viability across the next decade hinges on digital biomarker acceptance displacing traditional Holter monitoring. Acquisition targets should display therapeutic specialization in oncology-cardiology crossover studies. The signal to watch is FDA draft guidance formalizing wearable-derived cardiac endpoints as submission-grade evidence.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA 21 CFR Part 11 validation unlocks submission-grade ECG core laboratory status for thorough QT studies. |
| Platform Integration | Cloud-based analytics licensing reduces per-study labor intensity while capturing recurring SaaS revenue streams. |
| Geographic Expansion | Asia-Pacific entry leverages PMDA and NMPA ICH E14 harmonization to access Japan and China sponsor procurement. |
| Acquisition of Specialist Firm | Oncology-cardiology crossover expertise commands premium pricing in immuno-oncology cardiotoxicity surveillance. |
| Strategic Partnership | Wearable device manufacturer alliances enable 30-day continuous monitoring for decentralized trial architectures. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, ECG core laboratory directors, and clinical research organization procurement managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA guidance documents, EMA submissions, ClinicalTrials.gov records, and ICH E14 Q&A revisions. Bottom-up service-type segmentation triangulated against top-down pharmaceutical R&D expenditure patterns.
Sensitivity analysis across regulatory scenario variants tested forecast robustness over the projection horizon. Segmentation dimensions modeled include service type, technology platform, end-user archetype, and therapeutic application area. CAGRs derived from regression analysis of historical outsourcing penetration rates and regulatory mandate expansion timelines. Forecast inputs incorporated electrophysiologist workforce growth constraints and wearable sensor adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained ICH E14 enforcement intensity or accelerated digital biomarker validation would require recalibration. Forecasts reflect assumptions regarding regulatory harmonization pace and sponsor outsourcing preference stability. Revision becomes warranted when FDA guidance on wearable-derived endpoints crosses formal adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Ischemia Market
Cardiovascular
Vasculitis Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Hypercholesterolemia Drugs Market