
 Ticagrelor Market | 2026-2036
Ticagrelor Market Size, Share, and Industry Trends Forecast 2026-2036
Ticagrelor Market Outlook
FDA bioequivalence standards for narrow therapeutic index drugs is decoupling manufacturing scale from market access for generic entrants. AstraZeneca leverages its originator data packages to sustain brand loyalty in acute care settings. Sun Pharmaceutical Industries anchors its position through backward integration into active pharmaceutical ingredient production. Bayer competes via established hemostasis portfolios that create cross-selling opportunities with institutional buyers.
Ticagrelor is a cyclopentyltriazolopyrimidine antiplatelet agent functioning as a reversible P2Y12 receptor antagonist with a plasma half-life of approximately seven hours, manufactured through multi-step organic synthesis requiring stereoselective catalysis. The compound inhibits adenosine diphosphate-mediated platelet aggregation to reduce thrombotic events in patients with acute coronary syndromes or prior myocardial infarction. Tablet formulations dominate current revenue pools given their suitability for outpatient chronic therapy, while intravenous delivery modes command premium positioning in periprocedural hospital use. Therapy areas spanning myocardial infarction and stroke prevention represent the fastest-expanding application segments as guidelines broaden eligibility criteria.
The FDA, EMA, and national pharmacovigilance frameworks collectively shape approval timelines, label expansions, and risk evaluation requirements for antiplatelet therapies across major markets. These regulators mandate cardiovascular outcome trials and bleeding-risk monitoring protocols that directly influence prescriber confidence and formulary placement decisions. Stakeholders must monitor evolving guideline recommendations from cardiology societies and their interplay with payer prior-authorization criteria to anticipate volume shifts between branded and generic formulations.
Market Dynamics
Generic bioequivalence pathways for narrow therapeutic index drugs are decoupling manufacturing scale from market access, fragmenting pricing power across acute care and chronic therapy segments.
Growth Catalysts
- Hospital protocol standardization:Acute coronary syndrome treatment algorithms in tertiary care centers embed oral antiplatelet therapy into percutaneous coronary intervention workflows, embedding volume commitments into institutional purchasing.
- EMA centralized procedure expansions:Mutual recognition pathways accelerate label harmonization across European member states, compressing time-to-reimbursement for new indications.
- Stereoselective catalysis maturation:Advances in chiral synthesis reduce active pharmaceutical ingredient production costs, enabling cost-competitive generic entry without compromising enantiomeric purity.
Market Restraints
- Platinum group metal volatility:Palladium and rhodium price swings in stereoselective hydrogenation catalysts transmit directly to batch economics, compressing margin predictability for contract manufacturers.
- Bleeding risk surveillance mandates:FDA-required risk evaluation and mitigation strategies impose ongoing pharmacovigilance burdens that scale disproportionately for smaller generic entrants.
- Prasugrel substitution pressure:Alternative P2Y12 inhibitors with established generic availability capture price-sensitive chronic therapy volumes in outpatient settings.
Strategic Opportunities
- Stroke prevention label expansion:Emerging cerebrovascular indication approvals would unlock neurology prescriber networks currently underserved by cardiology-focused sales infrastructure.
- Specialty pharmacy direct distribution:Bypassing wholesale intermediaries to serve integrated delivery networks captures formulary influence and real-world data generation capabilities.
- Japan's post-PCI guideline revisions:PMDA alignment with Western dual antiplatelet therapy durations extends addressable patient-years in an aging, procedure-intensive market.
Industry Challenges
- Stereochemistry analytical talent scarcity:Chiral method development and validation expertise concentrates among legacy teams at originator firms, constraining quality control scaling for new entrants.
- Legacy hemostasis portfolio integration:Cross-selling antiplatelet agents alongside coagulation monitoring devices requires retraining acute care sales forces accustomed to single-molecule detailing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ticagrelor Market |
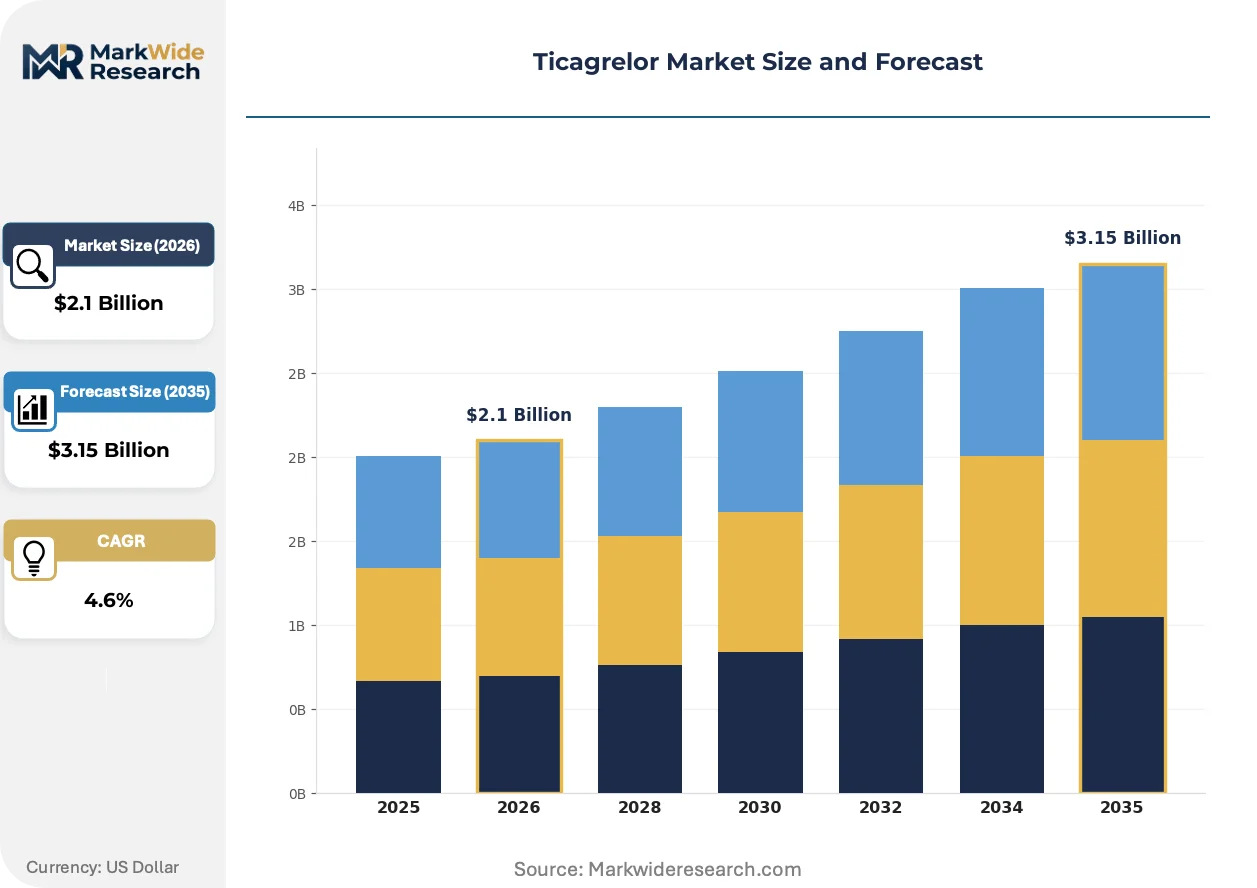
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injection, Oral Solution, Extended Release End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Pharmacies Therapy Area: Cardiovascular Diseases, Stroke Prevention, Myocardial Infarction, Atrial Fibrillation Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Merck KGaA, Sun Pharmaceutical Industries, AstraZeneca, Johnson & Johnson, Bayer, Pfizer, Eli Lilly, Roche, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ticagrelor Market Strategic Shifts
Oral antiplatelet therapy is bifurcating into precision-dosed acute formulations and convenience-optimized chronic regimens, with delivery technology and regulatory science determining competitive mobility between these domains.
Extended-release tablet platforms incorporating pH-dependent polymer coatings are electrifying bioavailability optimization for patients with proton pump inhibitor co-therapy. Hospital pharmacy committees in the United States are prioritizing these formulations for periprocedural protocols where gastric acid suppression is standard. The technology is compressing differentiation windows between originator and enhanced-generic offerings by raising baseline efficacy expectations.
REACH registration requirements for pharmaceutical intermediates are tightening documentation burdens for European contract manufacturers supplying chiral building blocks. ECHA substance evaluation protocols now mandate extended environmental fate studies for synthetic byproducts previously exempt under grandfathered dossiers. German and Dutch active pharmaceutical ingredient producers are responding by consolidating synthesis steps in-house to control data package integrity.
Institutional procurement committees are consolidating antiplatelet purchasing through integrated delivery network formularies, displacing individual physician preference as the primary volume determinant. Cardiovascular service line administrators in United States health systems now negotiate multi-year sole-source agreements tied to quality outcome metrics. This concentration is most visible in the southeastern states where hospital system consolidation has proceeded fastest.
Ticagrelor Market Segmentation
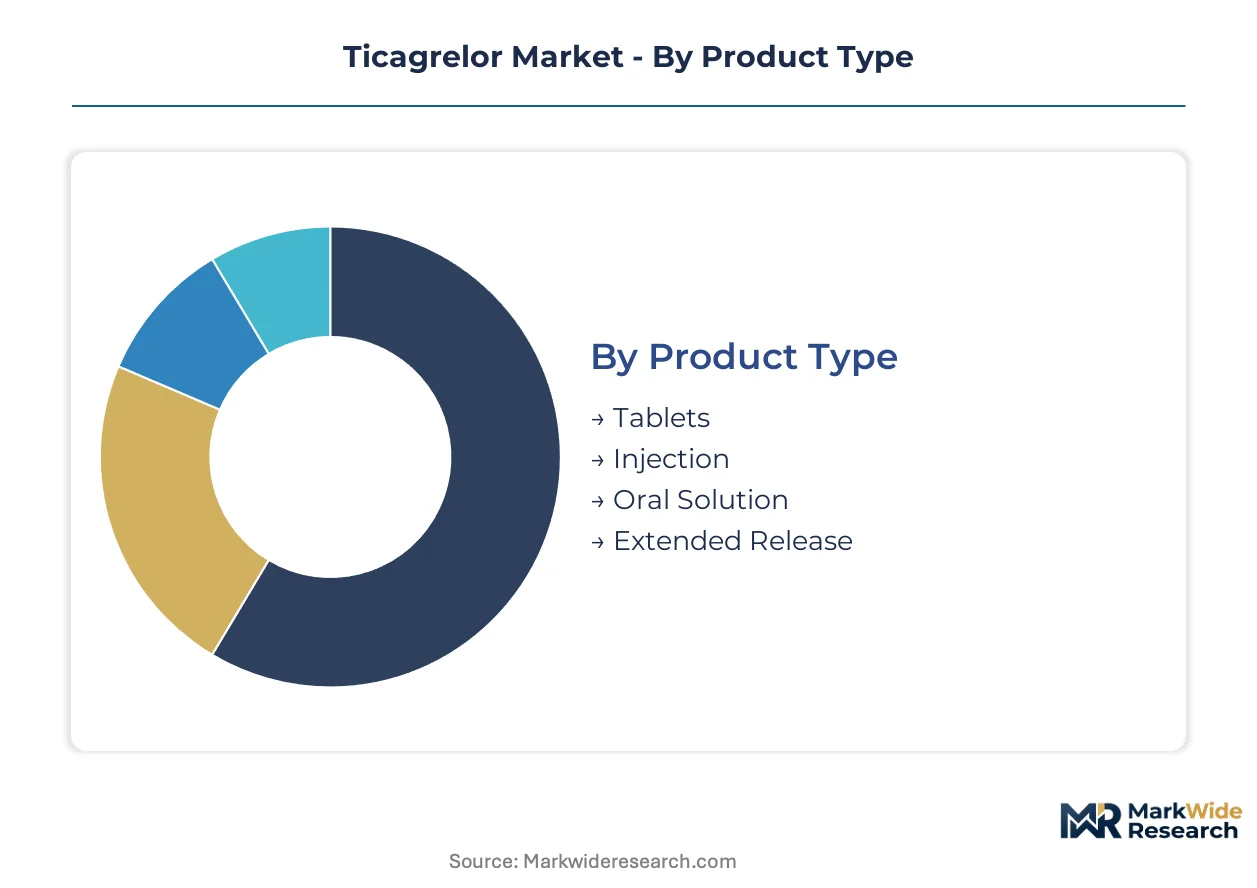
Ticagrelor's market structure reflects divergent clinical workflows across acute intervention and chronic maintenance settings. Formulation choices and delivery modes map directly to prescriber specialty, reimbursement tier, and institutional procurement authority.
Product Type:
Buyers differentiate primarily by therapy duration and care setting transition requirements.
- Tablets:Film-coated immediate-release formulations containing ticagrelor and mannitol enable outpatient chronic therapy with twice-daily dosing flexibility. Demand concentrates in United States specialty pharmacy networks serving post-discharge myocardial infarction patients where 12-month dual antiplatelet protocols are standard.
- Injection:Lyophilized powder for intravenous reconstitution delivers loading doses during percutaneous coronary intervention when oral absorption is compromised. Hospital catheterization laboratories in tertiary care centers anchor volume as procedural standardization embeds antiplatelet therapy into STEMI protocols.
- Oral Solution:Liquid formulations serve dysphagic patients and pediatric populations requiring dose titration unavailable in fixed-strength tablets.
- Extended Release:Polymer-matrix tablets with pH-dependent coatings optimize bioavailability for proton pump inhibitor co-therapy patients. German hospital pharmacy committees prioritize these for periprocedural protocols where gastric acid suppression is routine.
Tablets lead volumes today; extended release formulations are gaining share fastest.
End User:
Procurement authority and formulary control determine competitive access across institutional hierarchies.
- Hospitals:Integrated delivery networks negotiate sole-source agreements tied to cardiovascular outcome metrics. Southeastern United States health systems concentrate purchasing through service line administrators displacing individual physician preference.
- Outpatient Clinics:Cardiology practices manage chronic therapy initiation and monitoring with prescription authority constrained by payer prior-authorization criteria.
- Ambulatory Surgical Centers:Limited procedural volume restricts antiplatelet stocking to emergency reversal protocols rather than elective intervention workflows.
- Specialty Pharmacies:Direct distribution bypasses wholesale intermediaries capturing formulary influence and real-world data generation capabilities for integrated delivery networks.
Hospitals dominate absolute consumption; specialty pharmacies are expanding share most rapidly.
Therapy Area:
Guideline expansion and label harmonization reshape addressable patient populations across cardiovascular and cerebrovascular indications.
- Cardiovascular Diseases:Broad acute coronary syndrome indication anchors reimbursement with dual antiplatelet therapy durations varying by stent type and bleeding risk stratification.
- Stroke Prevention:Emerging cerebrovascular approvals would unlock neurology prescriber networks currently underserved by cardiology-focused sales infrastructure. Japanese post-PCI guideline revisions extending therapy durations signal expansion potential in aging populations.
- Myocardial Infarction:Secondary prevention protocols drive chronic therapy volumes with generic substitution pressure most acute in price-sensitive outpatient settings.
- Atrial Fibrillation:Off-label use persists where oral anticoagulation is contraindicated though regulatory clarity remains pending.
Cardiovascular diseases command current volumes; stroke prevention shows steepest expansion trajectory.
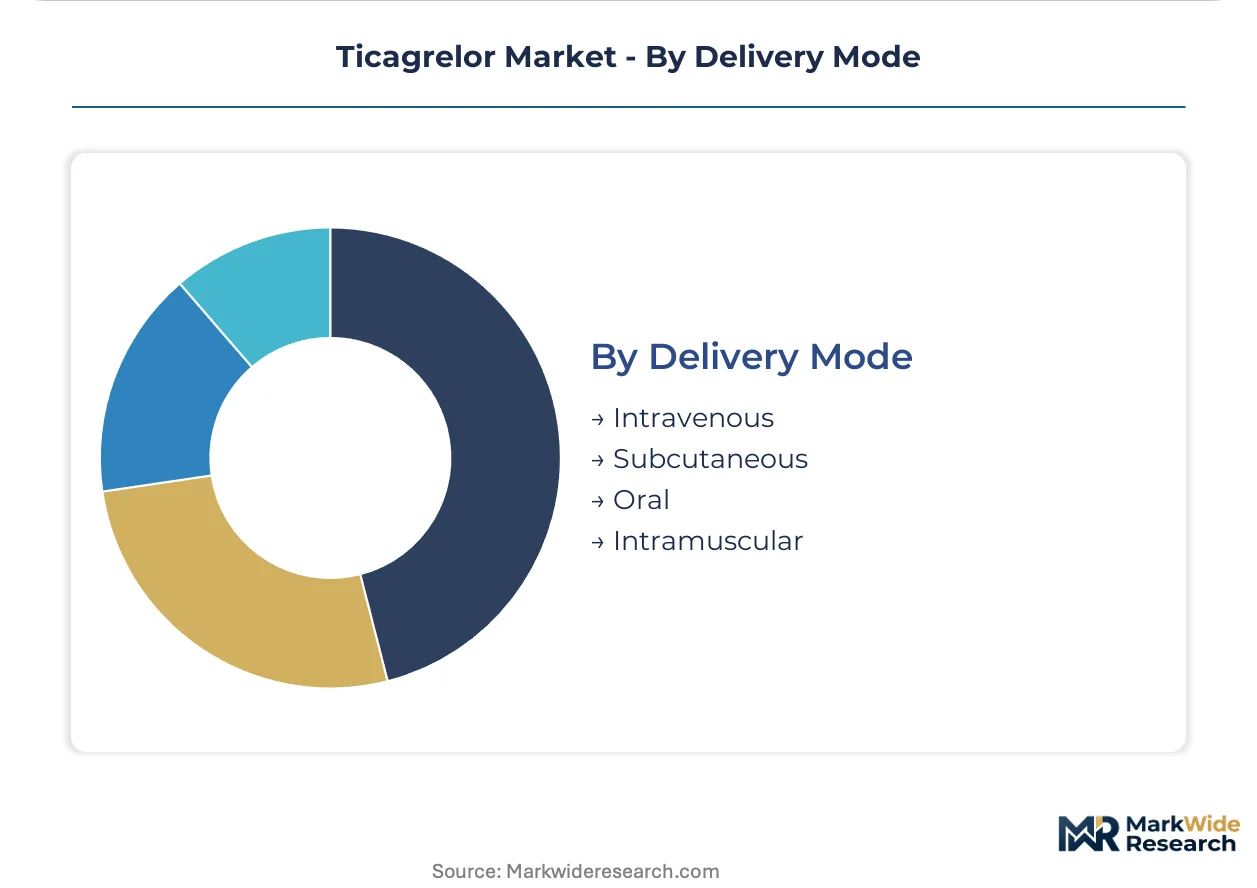
Delivery Mode:
Pharmacokinetic requirements and procedural context dictate route selection with regulatory science determining competitive mobility.
- Intravenous:Rapid onset during percutaneous coronary intervention when oral absorption is unreliable. United States catheterization laboratories standardize loading dose protocols.
- Subcutaneous:Limited applicability for antiplatelet agents given platelet inhibition kinetics and bioavailability requirements.
- Oral:Chronic maintenance therapy default with tablet and solution formulations serving distinct patient capabilities.
- Intramuscular:No established role in antiplatelet therapy given bleeding risk and absorption variability.
Oral delivery anchors chronic volumes; intravenous modes capture premium procedural positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular pharmacology specialists cluster around major academic medical centers and contract manufacturing hubs in five countries where antiplatelet therapy protocols are most entrenched.
United States
Integrated delivery networks in the southeastern states concentrate hospital purchasing through service line administrators. FDA bioequivalence standards for narrow therapeutic index drugs create asymmetric compliance burdens between originator and generic manufacturers. Boston and Research Triangle Park anchor pharmacovigilance operations supporting REMS-mandated bleeding risk surveillance.
Germany
Hospital pharmacy committees prioritize extended-release formulations for periprocedural protocols with routine gastric acid suppression. ECHA substance evaluation protocols under REACH now mandate extended environmental fate studies for synthetic byproducts. The Rhine-Ruhr and Bavarian chemical corridors consolidate chiral synthesis steps in-house to control data package integrity for API intermediates.
Japan
Aging demographics and procedure-intensive cardiology practice drive dual antiplatelet therapy volume. PMDA alignment with Western post-PCI guideline revisions extends therapy durations and addressable patient-years. The Kanto region around Tokyo concentrates specialty pharmacy distribution serving integrated delivery networks with direct formulary influence.
India
Cost-competitive generic manufacturing scales through backward integration into active pharmaceutical ingredient production. CDSCO harmonization with ICH guidelines accelerates abbreviated new drug application approvals for complex molecules. Hyderabad and Ahmedabad host contract research organizations developing stereoselective catalysis capabilities for chiral method validation.
Switzerland
Precision pharmaceutical manufacturing concentrates around Basel and the Lake Geneva corridor serving European hospital networks. Swissmedic maintains stringent pharmacovigilance requirements that reinforce quality differentiation for originator data packages. The country's hemostasis device clusters create cross-selling infrastructure with institutional antiplatelet buyers.
Ticagrelor Market Competitive Environment
The competitive structure tilts toward originator-defense archetypes sustained by regulatory data packages and acute care formulary embedding. Market concentration remains moderate with tiered positioning across hospital procurement, specialty pharmacy distribution, and outpatient chronic therapy channels. Three archetypes dominate: originator firms leveraging legacy trial data, vertically integrated generic manufacturers with captive API supply, and diversified hemostasis portfolio players exploiting cross-selling synergies. Competitive mobility depends on stereochemistry analytical capabilities and REMS compliance infrastructure rather than manufacturing scale alone.
Among originator-defense specialists, AstraZeneca exemplifies sustained brand loyalty through acute care protocol embedding. Sun Pharmaceutical Industries anchors the vertically integrated generic tier with backward integration into chiral API production. Bayer occupies a cross-selling position where hemostasis device portfolios create institutional bundling opportunities with antiplatelet procurement committees.
| Leading Market Players |
|---|
| Merck KGaA |
| Sun Pharmaceutical Industries |
| AstraZeneca |
| Johnson & Johnson |
| Bayer |
| Pfizer |
| Eli Lilly |
| Roche |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Palladium and rhodium price indices on the London Metal Exchange cascade through stereoselective hydrogenation catalyst costs into three distinct pricing tiers for ticagrelor formulations. Contract manufacturers pass commodity volatility to acute care buyers through quarterly price adjustment clauses, while chronic therapy segments absorb cost compression via generic substitution.
Pricing Analysis
Bundled device-and-drug agreements dominate hospital procurement, whereas unbundled API supply contracts serve outpatient generic substitution. Three-tier pricing structure across originator brands, enhanced generics with pH-dependent coatings, and economy-grade tablets segments buyers by formulary tier and reimbursement access. Pricing pressure stems from prasugrel substitution in price-sensitive chronic maintenance settings. Ambulatory surgical centers exhibit highest price sensitivity; tertiary catheterization laboratories show lowest due to protocol-embedded volume commitments.
Supply Chain Analysis
Cold-chain logistics costs for lyophilized intravenous formulations exceed tablet distribution by an order of magnitude, compressing margin structures for hospital-bound supply. API production concentrates in India, Germany, and Switzerland, drawing from platinum-group metal catalysts, chiral auxiliary reagents, and mannitol excipients. Single-source vulnerability in stereoselective catalysis expertise constrains quality control scaling. Distribution runs through specialty pharmacy direct channels for integrated delivery networks and wholesale intermediaries for independent cardiology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ticagrelor market compounds steadily as hospital protocol standardization embeds volume into institutional purchasing cycles with limited elasticity.
For Market Incumbents: Anchor formulary position through REMS compliance infrastructure that smaller generic entrants cannot replicate at scale. Deepen backward integration into chiral API production to buffer platinum-group metal cost volatility. Prioritize extended-release formulation patents as differentiation levers against economy-tier substitution pressure from prasugrel generics. For New Entrants and Emerging Players: Telehealth platforms serving post-discharge myocardial infarction patients represent the most penetrable channel for chronic therapy initiation. Neurology prescriber networks for stroke prevention indications remain underserved by cardiology-focused incumbents. Pursue specialty pharmacy direct distribution partnerships to bypass wholesale intermediaries and capture real-world data generation capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated generic manufacturers possessing captive chiral synthesis capabilities and FDA bioequivalence validation track records for narrow therapeutic index drugs. The five-to-ten year viability window favors acquisition targets with institutional REMS infrastructure and hospital GPO contract access. Monitor FDA generic approval velocity for complex molecules as the primary inflection signal for competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | FDA-mandated bleeding risk surveillance creates compliance moats that scale disproportionately against smaller entrants. |
| Chiral API Backward Integration | In-house stereoselective catalysis production buffers platinum-group metal price volatility and secures enantiomeric purity control. |
| Extended-Release Formulation Development | pH-dependent polymer coatings capture periprocedural hospital protocols where proton pump inhibitor co-therapy is standard. |
| Specialty Pharmacy Direct Distribution | Bypassing wholesale intermediaries captures formulary influence and real-world evidence generation for integrated delivery networks. |
| Stroke Prevention Label Expansion | Neurology indication approvals unlock prescriber networks currently underserved by cardiology-focused sales infrastructure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, hospital procurement managers, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up volume modeling and top-down market sizing triangulated across these sources to establish baseline figures.
Historical reference periods anchored the forecast window through trend extrapolation and driver elasticity modeling across the projection horizon. Segmentation dimensions included formulation type, delivery mode, therapy area, end-user setting, and regional regulatory cluster. CAGRs derived from volume trajectory analysis incorporating hospital protocol adoption rates, generic approval timelines, and guideline revision schedules as primary inputs.
The model assumes a particular technology adoption path for extended-release tablet platforms; alternative pathways for intravenous-to-oral switching protocols would alter the outlook. Forecasts reflect assumptions about EMA centralized procedure timelines and FDA bioequivalence standards that may shift with regulatory science evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Statin Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Venous Thromboembolism Treatment Market