
 Chronic Heart Failure Market | 2026-2036
Chronic Heart Failure Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Heart Failure Market Analysis
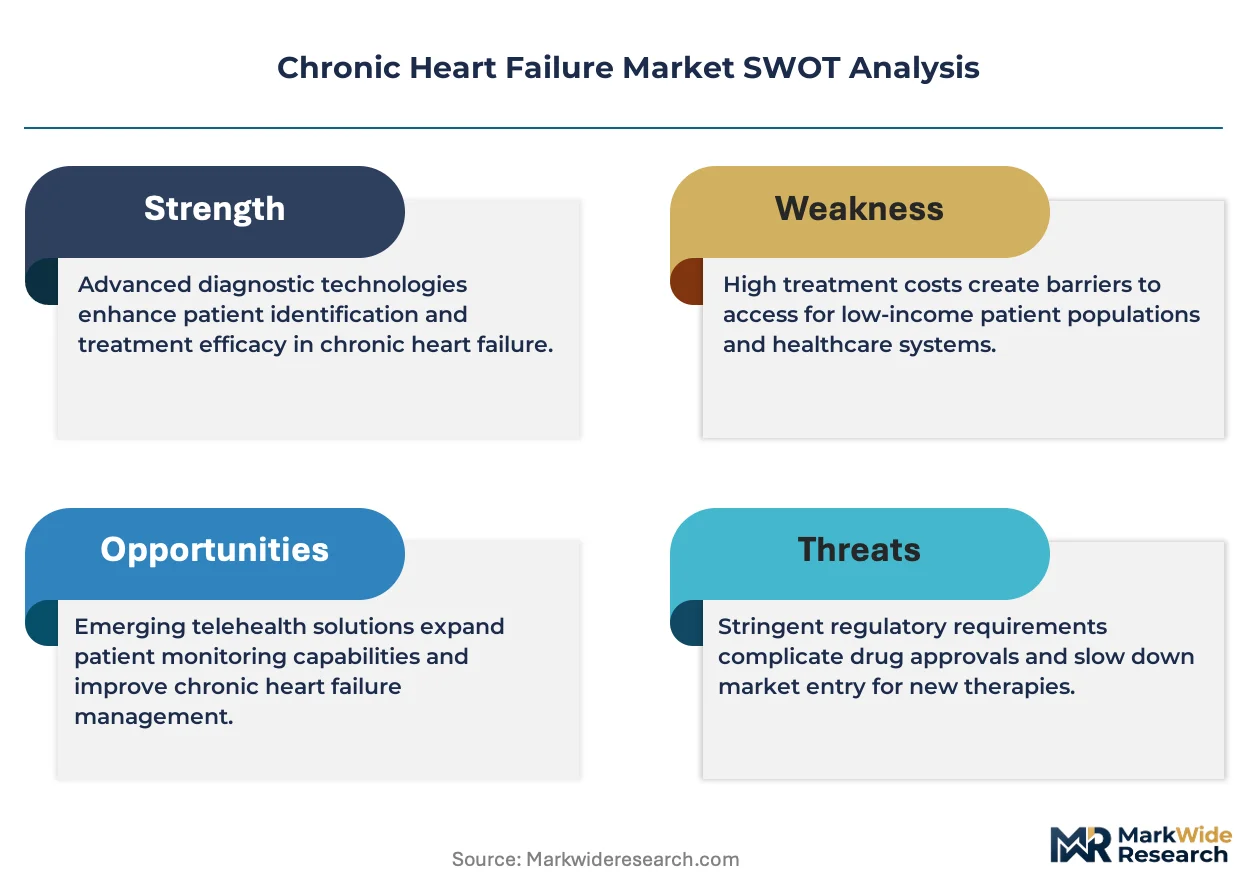
Buyer concentration among integrated hospital networks is realigning procurement decisions for chronic heart failure therapies toward formulary standardization and volume contracting. Novartis AG leverages its entrenched cardiovascular portfolio to sustain preferential positioning within these consolidated purchasing structures. Abbott Laboratories anchors its competitive stance through device-drug synergies spanning cardiac rhythm management and hemodynamic monitoring. Boehringer Ingelheim International GmbH differentiates via deep specialization in the cardiorenal metabolic axis, an area of intensifying clinical focus.
Chronic heart failure denotes a progressive clinical syndrome characterized by the heart's inability to pump sufficient blood to meet metabolic demands, typically quantified by reduced ejection fraction below 40 percent or preserved ejection fraction with elevated filling pressures. The condition demands sustained pharmacologic intervention, device-based circulatory support, or surgical correction to prevent decompensation and mortality. Beta Blockers and ACE Inhibitors occupy mature, high-volume positions within medication management protocols, while Ventricular Assist Devices and Cardiac Resynchronization Therapy represent faster-expanding therapy area segments driven by mechanical circulatory support advances and electrophysiology refinements. Home Healthcare channels are gaining structural importance as payors push cost-containing site-of-care shifts away from inpatient stays.
The FDA governs premarket approval and post-market surveillance for pharmaceuticals and implantable devices, with its Breakthrough Therapy designation shortening development timelines for novel heart failure modalities. Reimbursement frameworks administered by CMS directly shape prescribing behavior and site-of-care decisions across the United States. Stakeholders must monitor evolving value-based care contracts and real-world evidence requirements that will determine market access for next-generation therapies and interventional devices.
Market Dynamics
Integrated hospital networks are consolidating procurement authority into centralized pharmacy and therapeutics committees, forcing manufacturers to negotiate system-wide formularies rather than individual physician preferences. This structural concentration is compressing pricing flexibility and elevating real-world evidence requirements for market access.
Growth Catalysts
- FDA Breakthrough Therapy designation:The accelerated approval pathway compresses development timelines for novel heart failure modalities, enabling earlier commercialization of transformative therapies.
- Remote patient monitoring platforms:Cardiology practices are integrating hemodynamic sensors with electronic health records to enable proactive decompensation detection and reduce emergency admissions.
- Medicare reimbursement expansion:CMS coverage determinations for cardiac resynchronization therapy and ventricular assist devices are widening patient eligibility for device-based interventions.
Market Restraints
- Biologic input cost volatility:Recombinant protein production and monoclonal antibody manufacturing face raw material price instability that squeezes margin structures for biologic heart failure therapies.
- Specialized implantable device foundry concentration:Precision machining and biocompatible coating capabilities cluster among a limited supplier base in Germany and Switzerland, creating supply vulnerability.
- Technical limitation of preserved ejection fraction therapies:The absence of mortality-reducing pharmacologic options for HFpEF patients restricts addressable market expansion despite high prevalence.
Strategic Opportunities
- Home healthcare channel expansion:Skilled nursing facilities and home infusion services are capturing site-of-care shifts driven by Medicare's Hospital at Home waivers and readmission penalty programs.
- Cardiorenal metabolic axis convergence:SGLT2 inhibitors are absorbing indications across diabetes, chronic kidney disease, and heart failure, creating cross-specialty prescribing opportunities.
- Japan's geriatric reimbursement incentives:METI and PMDA fast-track designations for elderly-appropriate dosing regimens open premium positioning for age-optimized formulations.
Industry Challenges
- Electrophysiologist and heart failure specialist scarcity:Device implantation and advanced heart failure program expansion outpaces fellowship training pipeline output, constraining procedural volume growth.
- Legacy electronic health record integration complexity:Proprietary data architectures at major hospital systems impede seamless integration of remote monitoring dashboards and predictive analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Heart Failure Market |
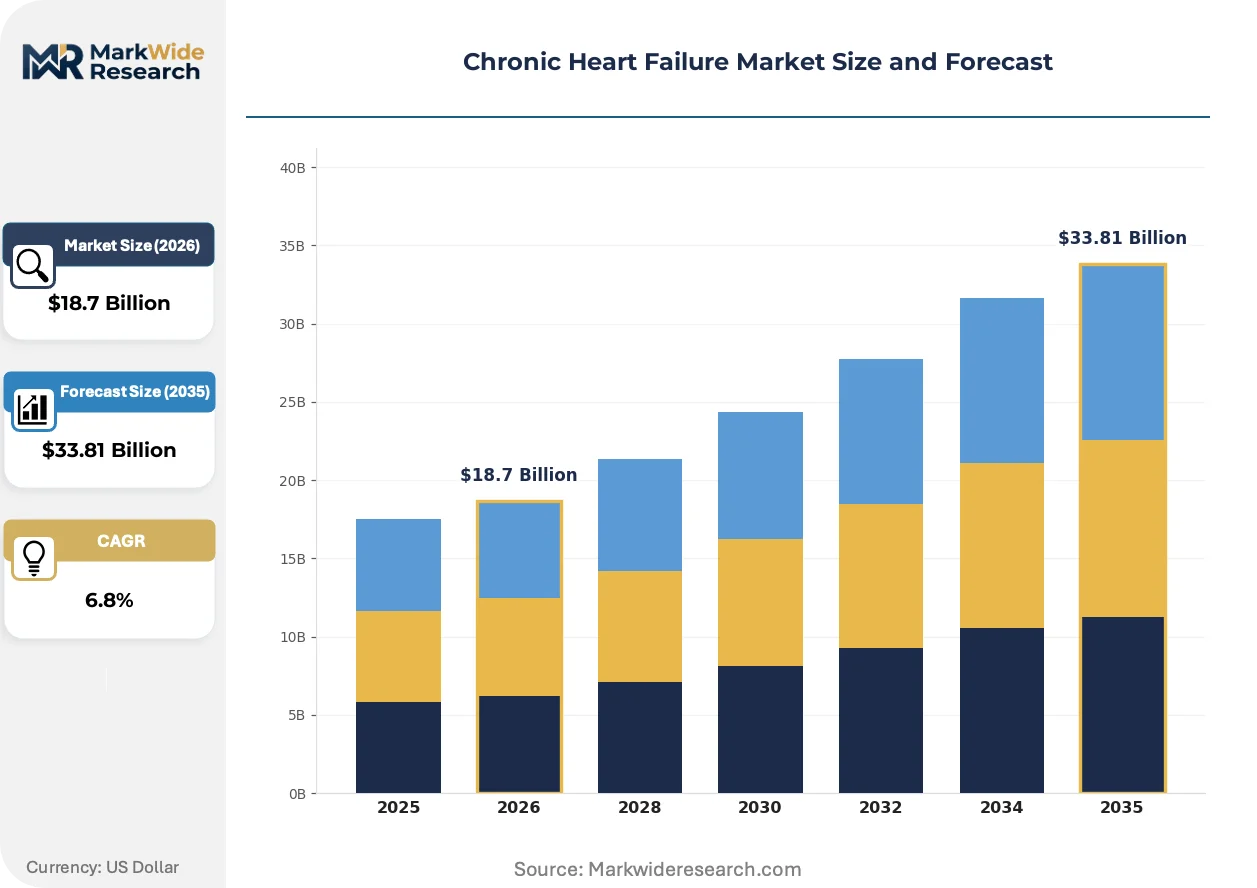
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACE Inhibitors, Beta Blockers, Diuretics, Aldosterone Antagonists Therapy Area: Heart Transplantation, Ventricular Assist Devices, Cardiac Resynchronization Therapy, Electrical Stimulation End User: Cardiology Clinics, Hospitals, Home Healthcare, Specialty Pharmacies Treatment Approach: Medication Management, Lifestyle Modification, Surgical Intervention, Palliative Care |
| Companies Covered | Merck & Co., Inc., Eli Lilly and Company, Novartis AG, Amgen Inc., Abbott Laboratories, AstraZeneca PLC, Boehringer Ingelheim International GmbH, Medtronic PLC, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Heart Failure Market Emerging Trajectories
Digital biomarker integration and miniaturized hemodynamic sensors are restructuring how clinicians detect decompensation before symptom onset. These innovations are compressing the traditional reactive care model into predictive, algorithm-guided intervention protocols.
Implantable pulmonary artery pressure monitors are absorbing clinical workflow responsibilities previously managed through scheduled clinic visits and emergency department assessments. Cardiology practices at centers like Cleveland Clinic and Mayo Clinic are embedding these devices into standard heart failure management protocols. The technology is absorbing volume from traditional telemetry-based follow-up models and enabling medication titration without physical examination.
EMA's Medical Device Regulation (MDR) is elevating post-market surveillance requirements for implantable cardiac devices across European markets. Manufacturers must now maintain active implant registries and submit periodic safety update reports that extend far beyond previous directives. Class III device categories including ventricular assist systems and resynchronization generators face the most intensive clinical evidence obligations, with notified bodies in Germany and the Netherlands experiencing substantial review backlogs.
Hospital system value-based care contracts are restructuring supplier relationships around total cost-of-care guarantees rather than unit pricing. Integrated delivery networks in Texas and California are negotiating risk-sharing arrangements where device manufacturers assume partial financial exposure for readmission events. This contracting evolution is most advanced among Medicare Advantage–dominated markets where capitated reimbursement creates aligned incentives for outcome accountability.
Chronic Heart Failure Market Segmentation
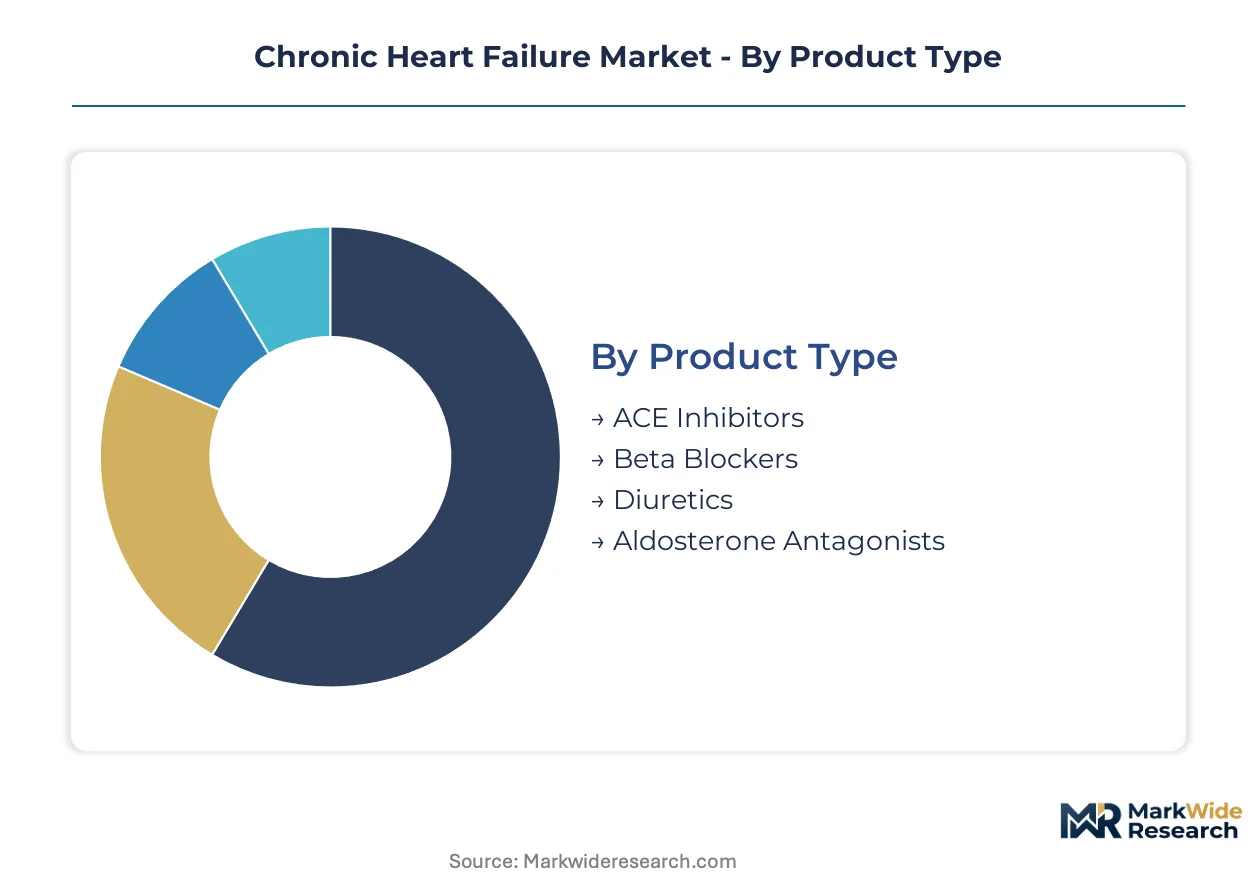
Chronic heart failure treatment pathways fragment across pharmacologic, mechanical, and surgical modalities. Each segment carries distinct regulatory burdens, reimbursement profiles, and site-of-care requirements that reshape competitive positioning.
Product Type:
Standardized small-molecule formulations dominate high-volume prescribing, while patent-protected combination therapies command premium positioning within consolidated formularies.
- ACE Inhibitors:First-line renin-angiotensin-aldosterone system blockers with established mortality benefit in HFrEF populations. Demand concentrates in Medicare Part D formularies where prior authorization requirements favor generic enalapril and lisinopril over branded alternatives.
- Beta Blockers:Sympatholytic agents including carvedilol, metoprolol succinate, and bisoprolol that reduce cardiac remodeling and sudden death risk. Cleveland Clinic and Mayo Clinic protocols mandate evidence-based beta blocker titration before device consideration, anchoring volume in tertiary referral patterns.
- Diuretics:Loop and thiazide agents managing congestion symptoms through sodium excretion.
- Aldosterone Antagonists:Mineralocorticoid receptor antagonists spironolactone and eplerenone.
Leading the category by volume: Beta Blockers. Expanding most quickly: Aldosterone Antagonists.
Therapy Area:
Mechanical circulatory support and electrophysiology interventions carry higher per-procedure margins but face steeper qualification requirements for implanting centers.
- Heart Transplantation:Definitive surgical remedy for end-stage refractory heart failure limited by donor organ scarcity. United Network for Organ Sharing allocation policy revisions in the United States prioritize status 1A and 1B candidates with durable mechanical support dependence.
- Ventricular Assist Devices:Implantable mechanical pumps providing destination therapy or bridge-to-transplant support. INTERMACS registry data drives CMS coverage determinations, with axial and centrifugal flow designs competing on thrombosis rates and driveline infection profiles.
- Cardiac Resynchronization Therapy:Biventricular pacing systems correcting electrical dyssynchrony.
- Electrical Stimulation:Implantable cardioverter-defibrillators and neuromodulation approaches.
Fastest share gains: Ventricular Assist Devices. Volume anchor: Cardiac Resynchronization Therapy.
End User:
Site-of-care economics and readmission penalty structures are redistributing patient touchpoints from inpatient wards toward ambulatory and home-based settings.
- Hospitals:Acute decompensation management, device implantation, and transplant evaluation. Texas Medical Center and New York-Presbyterian systems are consolidating advanced heart failure programs into dedicated institutes with embedded VAD and transplant capabilities.
- Home Healthcare:Skilled nursing, infusion services, and remote monitoring for stable chronic management. Medicare's Hospital at Home waiver expansion and readmission reduction programs are accelerating discharge-to-home protocols for hemodynamically stable patients.
- Cardiology Clinics:Outpatient medication titration and device surveillance.
- Specialty Pharmacies:Distribution of high-cost biologics and parenteral therapies.
Fastest channel expansion: Home Healthcare. Current volume concentration: Hospitals.
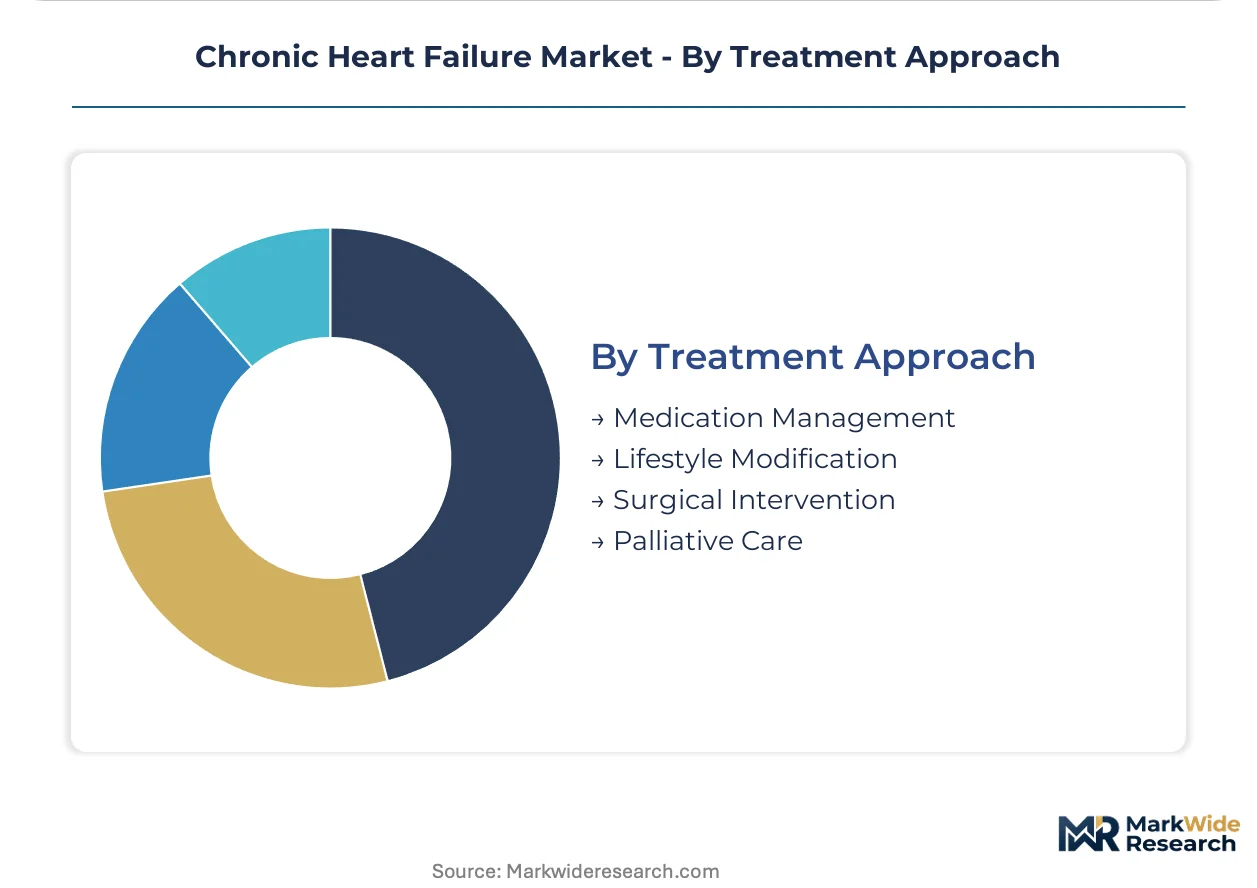
Treatment Approach:
Intervention intensity scales with disease stage, creating distinct margin profiles across the chronic-to-acute spectrum.
- Medication Management:Guideline-directed medical therapy comprising neurohormonal antagonists, SGLT2 inhibitors, and diuretic optimization. American College of Cardiology quality metrics now track quadruple therapy initiation rates, pressuring health systems toward protocolized prescribing.
- Surgical Intervention:Coronary revascularization, valve repair or replacement, and mechanical circulatory support implantation. Cleveland Clinic surgical volumes reflect patient selection toward younger candidates with reversible ischemic substrate or primary valvular disease.
- Lifestyle Modification:Sodium restriction, cardiac rehabilitation, and self-management education.
- Palliative Care:Symptom-focused management for advanced refractory disease.
Dominant by patient count: Medication Management. Steepest expansion trajectory: Surgical Intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Medicare reimbursement policies concentrate global demand for chronic heart failure therapies, with CMS coverage determinations directly shaping prescribing volumes and device eligibility criteria across the market.
United States
FDA Breakthrough Therapy designations and CMS national coverage determinations accelerate patient access to novel cardiovascular modalities. The Hospital at Home waiver expansion and readmission reduction programs are redistributing care delivery toward skilled nursing facilities and remote monitoring platforms. Texas Medical Center and New York-Presbyterian anchor advanced heart failure program consolidation with embedded ventricular assist device and transplant capabilities.
Germany
EMA Medical Device Regulation compliance requirements and notified body review backlogs are reshaping market entry timelines for implantable cardiac devices. The country's precision machining and biocompatible coating supplier base clusters around Stuttgart and Munich, creating concentrated manufacturing capabilities for ventricular assist systems. Heidelberg and Berlin university hospitals drive clinical evidence generation for next-generation hemodynamic monitoring technologies.
Japan
METI geriatric reimbursement incentives and PMDA fast-track designations for elderly-optimized dosing regimens open premium positioning opportunities. The country's aging demographic profile generates substantial addressable volume for age-appropriate heart failure formulations. Tokyo and Osaka medical centers lead adoption of miniaturized implantable sensors for proactive decompensation detection.
Switzerland
Swissmedic regulatory frameworks and precision manufacturing heritage sustain specialized foundry concentration for implantable device components. The country's micro-machining capabilities support biocompatible coating and precision component production for cardiac resynchronization generators. Basel and Zurich anchor pharmaceutical-device convergence research for cardiorenal metabolic axis therapies.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks determine formulary inclusion for high-cost heart failure biologics. The country's integrated care systems are consolidating cardiovascular service delivery into regional heart failure networks. London and Manchester academic medical centers generate real-world evidence requirements that manufacturers must satisfy for market access.
Chronic Heart Failure Market Vendor Landscape
United States pharmaceutical and device manufacturers anchor one tier; European specialists hold differentiated positions in precision implantable technologies and cardiorenal metabolic convergence. The market structure reflects consolidated procurement authority among integrated hospital networks alongside sustained innovation competition in mechanical circulatory support. Three archetypes dominate: diversified cardiovascular portfolios spanning drugs and devices, pure-play electrophysiology and hemodynamic monitoring specialists, and biologic-focused developers targeting neurohormonal pathways. Competitive moves center on formulary standardization negotiations and risk-sharing arrangements tied to readmission outcomes.
Within the diversified cardiovascular tier, Novartis AG and Abbott Laboratories exemplify contrasting strategic positions. Novartis AG occupies a position anchored by entrenched pharmaceutical portfolios within consolidated purchasing structures. Abbott Laboratories exemplifies device-drug synergy approaches spanning cardiac rhythm management and hemodynamic monitoring integration. Among European specialists, Boehringer Ingelheim International GmbH represents deep cardiorenal metabolic axis specialization, an area of intensifying clinical focus across prescribing guidelines.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Amgen Inc. |
| Abbott Laboratories |
| AstraZeneca PLC |
| Boehringer Ingelheim International GmbH |
| Medtronic PLC |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Recombinant protein feedstock indices and monoclonal antibody production costs cascade through pharmaceutical manufacturing tiers, compressing margin structures for biologic heart failure therapies while amplifying price sensitivity among Medicare-constrained hospital formularies.
Pricing Analysis
High-volume generic ACE inhibitors and beta blockers anchor the economy tier with thin per-unit margins, while patent-protected SGLT2 inhibitor combinations and implantable cardiac devices capture premium positioning. Price differentiation hinges on FDA Breakthrough Therapy designation status and CMS national coverage determination eligibility, with branded formulations commanding substantial markups over therapeutic equivalents. Pricing pressure stems from integrated hospital network consolidation into centralized pharmacy and therapeutics committees, which extract volume discounts through system-wide formulary standardization. Medicare Part D plans exhibit highest price sensitivity, whereas commercial payors in employer-sponsored markets demonstrate greater tolerance for innovative device-based interventions.
Supply Chain Analysis
Precision machining capabilities for ventricular assist device housings and biocompatible coating processes rest on specialized foundry concentration in Germany and Switzerland, creating single-source vulnerability for critical implantable components. Raw material dependencies span titanium alloys for pump housings, medical-grade silicone for driveline insulation, and recombinant cell lines for monoclonal antibody production. Supply chain risk centers on notified body review backlogs under EMA Medical Device Regulation, which delay component qualification and compress production planning horizons. Distribution runs through integrated delivery networks and group purchasing organizations that consolidate procurement authority across multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EMA Medical Device Regulation clinical evidence obligations and FDA post-market surveillance requirements erect substantial barrier-to-entry moats favoring manufacturers with established regulatory infrastructure and active implant registries.
For Market Incumbents: Anchor competitive position through backward integration into precision machining capabilities and biocompatible coating processes, securing captive supply of critical implantable device components against German and Swiss foundry bottlenecks. Deepen formulary lock-in via risk-sharing arrangements with Medicare Advantage–dominated integrated delivery networks, assuming partial financial exposure for heart failure readmission events to defend volume against SGLT2 inhibitor class entrants. For New Entrants and Emerging Players: Miniaturized implantable pulmonary artery pressure sensors offer technology-first wedge opportunities, exploiting legacy electronic health record integration complexity that impedes incumbent remote monitoring platforms. Target home healthcare channel expansion in Texas and California markets where Hospital at Home waiver adoption accelerates discharge-to-home protocols, partnering with skilled nursing facilities for medication titration services rather than competing directly for hospital implant volumes. For Investors and Strategic Acquirers: Distressed-cycle entries favor cardiorenal metabolic axis specialists with established SGLT2 inhibitor portfolios in United States markets, where Medicare reimbursement policies concentrate global demand and create durable revenue visibility. Watch FDA Breakthrough Therapy designation grants as inflection indicators signaling accelerated commercialization timelines and premium acquisition multiples for novel heart failure modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic protocols anchor tertiary referral patterns for device implantation volumes. |
| FDA Breakthrough Therapy Pathway | Accelerated approval compresses development timelines and enables earlier commercialization of transformative cardiovascular therapies. |
| Reimbursement Strategy | CMS national coverage determinations for cardiac resynchronization therapy directly shape patient eligibility and prescribing volumes. |
| Software Companion Development | Remote monitoring dashboards integrated with electronic health records enable proactive decompensation detection and reduce emergency admissions. |
| CE Marking Pathway | EMA Medical Device Regulation compliance elevates post-market surveillance requirements and extends clinical evidence obligations for European market access. |
Methodological Framework
FDA 510(k) and PMA filings, CMS national coverage determination records, and INTERMACS registry data formed the secondary backbone, cross-referenced against primary interviews with heart failure program directors, electrophysiologists, hospital pharmacy and therapeutics committee chairs, and medical device regulatory affairs specialists. Bottom-up and top-down triangulation validated patient volume estimates against pharmaceutical shipment data and implantable device procedure counts.
Bottom-up modeling anchored volume projections in Medicare claims data and hospital discharge records, while top-down approaches tested aggregate market sizing against pharmaceutical manufacturer revenue disclosures and medical device company segment reporting across the projection horizon. Segmentation dimensions included therapy area, product type, end user channel, and regional regulatory cluster, with CAGRs derived from historical procedure growth rates and formulary adoption curves adjusted for FDA approval pathway acceleration effects.
Several conditions sit outside the modeled scope, including potential SGLT2 inhibitor patent cliff effects, novel gene therapy regulatory pathways, and catastrophic supply disruptions at concentrated German and Swiss foundry operations. Forecasts embed assumptions regarding continued Medicare reimbursement stability and Hospital at Home waiver program continuity. A small set of named triggers warrants ongoing watch: FDA Breakthrough Therapy designation velocity, CMS national coverage determination reversals, and electrophysiologist fellowship training pipeline output.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
US Statin Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market