
 Middle-East and Africa Ischemic Heart Disease Market | 2026-2036
Middle-East and Africa Ischemic Heart Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Ischemic Heart Disease Market Outlook
Project finance for catheterization labs and leasing arrangements for imaging equipment is fragmenting competitive access across the Middle-East and Africa Ischemic Heart Disease landscape. Abbott Laboratories leverages its structural heart portfolio to anchor premium device segments in Gulf state tertiary hospitals. Medtronic sustains broad procedure coverage through integrated coronary and peripheral vascular platforms. Boston Scientific Corporation differentiates via drug-eluting stent specialization that commands preference in South African cardiac centers.
Ischemic heart disease encompasses coronary artery narrowing from atherosclerotic plaque accumulation, diagnosed through troponin biomarker thresholds, stress echocardiography, and fractional flow reserve measurements, with treatment aimed at restoring myocardial perfusion and preventing infarction. Stents and angioplasty balloons dominate procedural volumes across invasive intervention segments, while telemedicine represents the fastest-expanding technology dimension as Gulf health systems deploy remote cardiac monitoring to extend specialist reach into underserved populations. Medication management maintains the largest patient base within treatment approaches, though surgical interventions capture disproportionate value per procedure in private hospital networks.
Saudi Arabia's SFDA, the UAE's MOHAP, and South Africa's SAHPRA collectively govern device approval, clinical trial conduct, and post-market surveillance across the region, with harmonization efforts narrowing regulatory divergence and accelerating product entry timelines. The EU MDR's extraterritorial influence shapes quality system expectations for manufacturers exporting into Middle Eastern markets. Stakeholders must monitor how Gulf state hospital privatization programs redirect procurement authority from centralized ministries to facility-level committees, altering account targeting and contract negotiation dynamics.
Market Dynamics
Hospital privatization across Gulf Cooperation Council states is fragmenting procurement authority, shifting purchasing decisions from centralized ministries to facility-level committees and forcing device manufacturers to rebuild account targeting strategies around individual cardiac center relationships.
Growth Catalysts
- SFDA Streamlined Registration:Saudi Arabia's tightened medical device approval pathways accelerate market entry timelines for stent and diagnostic platforms.
- Telemedicine Infrastructure:Remote cardiac monitoring systems extend specialist reach into underserved populations across the UAE and Saudi Arabia.
- Interventional Cardiology Expansion:Cardiac centers in Dubai and Riyadh are adding catheterization labs and angiography suites to capture privatized patient flows.
Market Restraints
- Device Cost Concentration:Drug-eluting stents and imaging equipment require substantial capital outlay, limiting adoption in South African public hospitals.
- Regulatory Divergence:SAHPRA, SFDA, and MOHAP maintain non-harmonized clinical trial requirements, duplicating compliance burdens for manufacturers.
- Specialist Shortage:Interventional cardiologists concentrate in Gulf state tertiary centers, leaving secondary facilities in Egypt and Nigeria without procedural capacity.
Strategic Opportunities
- Equipment Leasing Models:Project finance arrangements for catheterization labs lower barriers to entry for private hospital groups in Jordan and Lebanon.
- Biomarker Integration:Troponin testing platforms combined with point-of-care diagnostics create bundled diagnostic offerings for emergency departments.
- Harmonization Momentum:Gulf Cooperation Council regulatory alignment initiatives promise unified device approval standards across member states.
Industry Challenges
- Biomedical Engineering Talent Gap:Maintenance and calibration of fractional flow reserve systems require trained technicians scarce outside South Africa and the UAE.
- Legacy System Integration:New telemedicine platforms must interface with existing hospital information systems in Saudi Arabia's fragmented provider landscape.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Ischemic Heart Disease Market |
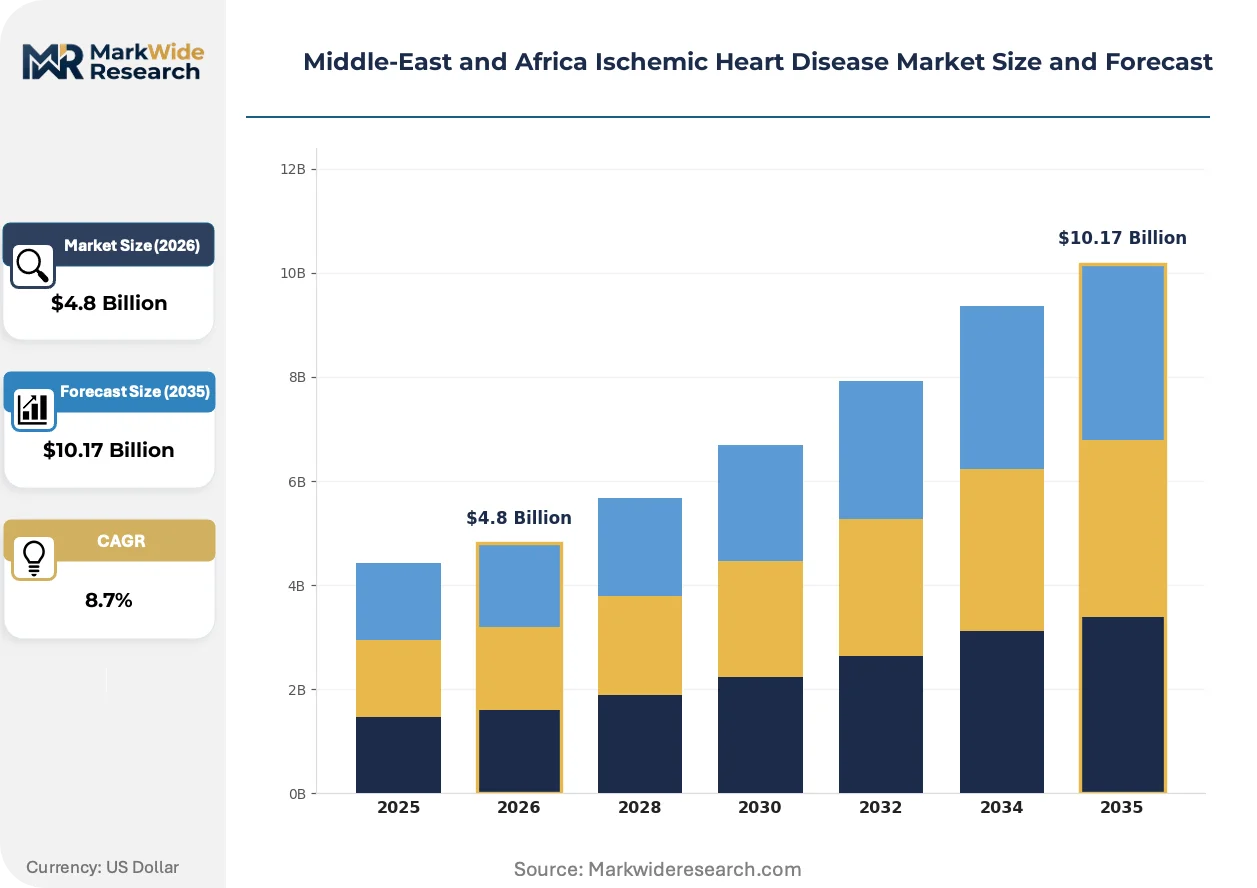
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Angioplasty Balloons, Coronary Bypass Grafts, Medications End User: Hospitals, Cardiac Centers, Specialty Clinics, Home Care Technology: Invasive Procedures, Non-invasive Diagnostics, Imaging Techniques, Telemedicine Treatment Approach: Medication Management, Surgical Interventions, Lifestyle Modifications, Rehabilitation Programs |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, Johnson & Johnson, GE Healthcare, Philips Healthcare, Biotronik, Siemens Healthineers, AstraZeneca, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Ischemic Heart Disease Market Strategic Shifts
Cardiac care delivery across the Middle-East and Africa is compressing diagnostic-to-intervention timelines while regulatory frameworks and procurement structures undergo parallel transformation.
Bioresorbable vascular scaffolds eliminate permanent metal implants from coronary procedures. Tertiary hospitals in Abu Dhabi and Jeddah pilot these platforms for younger patients requiring long-term vessel remodeling. Conventional bare-metal stents are rendering obsolete in premium intervention segments as absorbable polymers demonstrate comparable acute performance without late thrombotic risk.
EU MDR extraterritorial influence shapes quality system expectations for manufacturers exporting into Middle Eastern markets. Gulf state regulators increasingly reference European technical documentation standards during local approval reviews. Device sponsors targeting Saudi Arabia and the UAE must now maintain post-market surveillance systems mirroring EUDAMED reporting requirements.
Outcome-based contracting is displacing traditional device procurement in South African private hospital networks. Cardiac centers negotiate bundled payments covering stent placement, thirty-day readmission, and one-year revascularization rates. This shift concentrates purchasing power among hospital group procurement committees in Cape Town and Johannesburg, marginalizing distributor intermediaries.
Middle-East and Africa Ischemic Heart Disease Market Segmentation
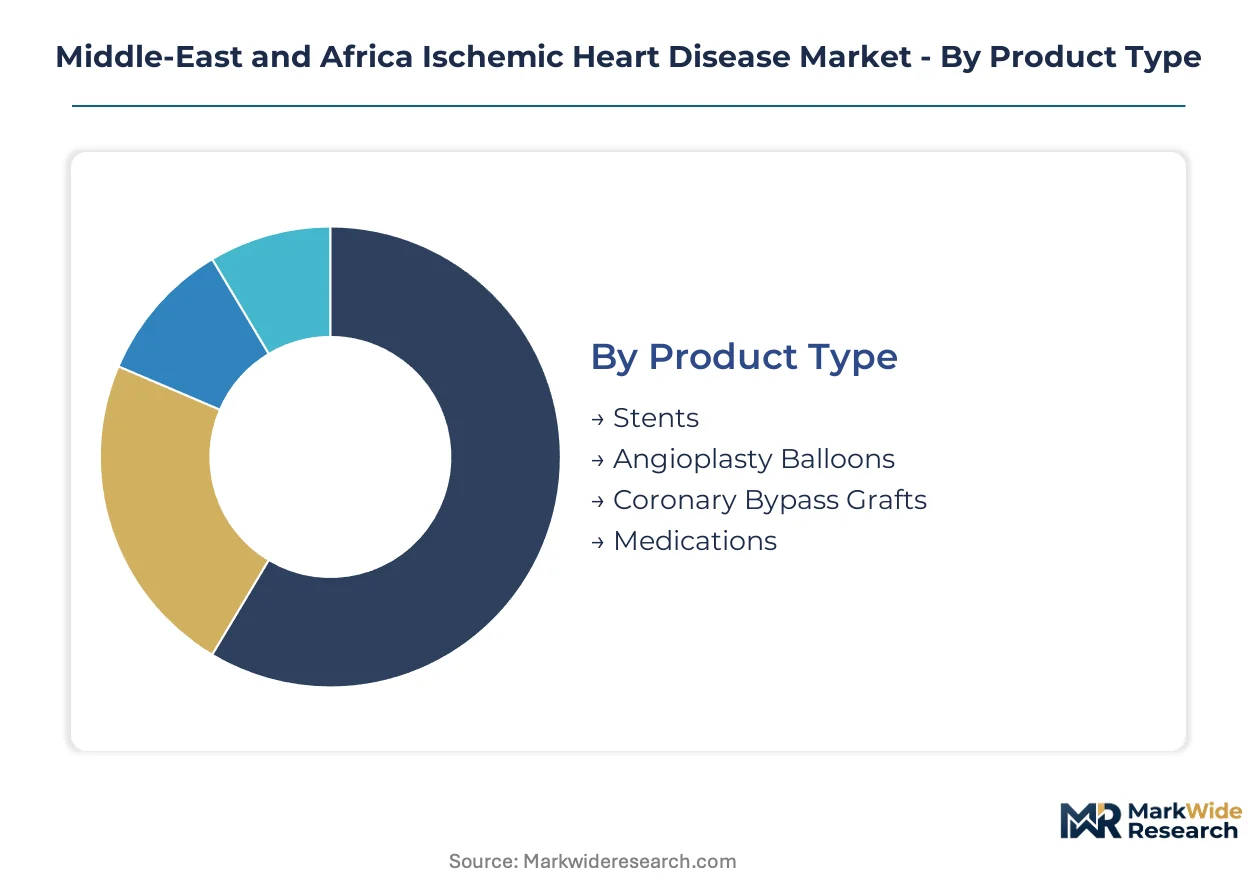
Segmentation of the Middle-East and Africa Ischemic Heart Disease Market reveals distinct procurement patterns across device categories, care settings, and intervention modalities. Understanding these divisions enables manufacturers to align product portfolios with the region's hospital privatization trends and regulatory harmonization efforts.
Product Type:
Device selection spans permanent implants, disposable interventional tools, and pharmaceutical regimens, with cost recovery models and reimbursement pathways determining adoption velocity across Gulf and African healthcare systems.
- Stents:Metallic or polymer-based scaffolds maintain vessel patency after angioplasty. Drug-eluting variants command preference in Saudi Arabian and Emirati tertiary centers where SFDA and MOHAP approvals accelerate procurement, though bare-metal alternatives persist in South African public hospitals facing budget constraints.
- Angioplasty Balloons:Inflatable catheters compress plaque to restore coronary flow. Demand concentrates in Dubai and Riyadh cardiac centers expanding catheterization lab capacity, with cutting and scoring balloon technologies gaining traction for calcified lesions.
- Coronary Bypass Grafts:Autologous vessel or synthetic conduit for surgical revascularization.
- Medications:Antiplatelet, statin, and antihypertensive therapies for chronic disease management.
Established volume favors Medications; emerging adoption favors Stents.
End User:
Care delivery infrastructure fragments across centralized ministry-controlled facilities and newly privatized hospital networks, altering purchasing authority and device specification requirements.
- Hospitals:Acute care institutions with full cardiac surgery and interventional capabilities. Saudi Arabia's hospital privatization program redirects procurement decisions from the Ministry of Health to facility-level committees in Riyadh and Jeddah, forcing device manufacturers to rebuild account relationships.
- Cardiac Centers:Dedicated facilities for cardiovascular diagnosis and intervention. The UAE's Dubai Healthcare City and Saudi Arabia's King Faisal Specialist Hospital anchor premium device demand, with catheterization lab expansion driving angiography suite investments.
- Specialty Clinics:Outpatient-focused practices for stable angina and post-intervention monitoring.
- Home Care:Remote patient monitoring and medication adherence support.
Procedure value concentrates in Cardiac Centers; patient volume concentrates in Hospitals.
Technology:
Diagnostic and therapeutic modalities range from catheter-based interventions to distributed monitoring platforms, with capital intensity and specialist availability governing deployment feasibility.
- Invasive Procedures:Catheter-based interventions including angioplasty and stent deployment. Specialist concentration in Gulf state tertiary centers leaves Egyptian and Nigerian secondary facilities without procedural capacity, limiting geographic penetration despite established clinical efficacy.
- Non-invasive Diagnostics:Stress testing, biomarker assays, and electrocardiography for initial disease detection. Troponin testing platforms combined with point-of-care diagnostics create bundled offerings for emergency departments across Jordanian and Lebanese hospitals.
- Imaging Techniques:Echocardiography, CT angiography, and cardiac MRI for anatomical assessment.
- Telemedicine:Remote cardiac monitoring and specialist consultation platforms. Gulf health systems deploy these systems to extend reach into underserved populations, with the UAE and Saudi Arabia leading infrastructure investment.
Capital deployment favors Invasive Procedures; infrastructure investment favors Telemedicine.
Treatment Approach:
Clinical pathways stratify across chronic pharmaceutical management, acute surgical intervention, and longitudinal prevention programs, with payment models influencing pathway selection.
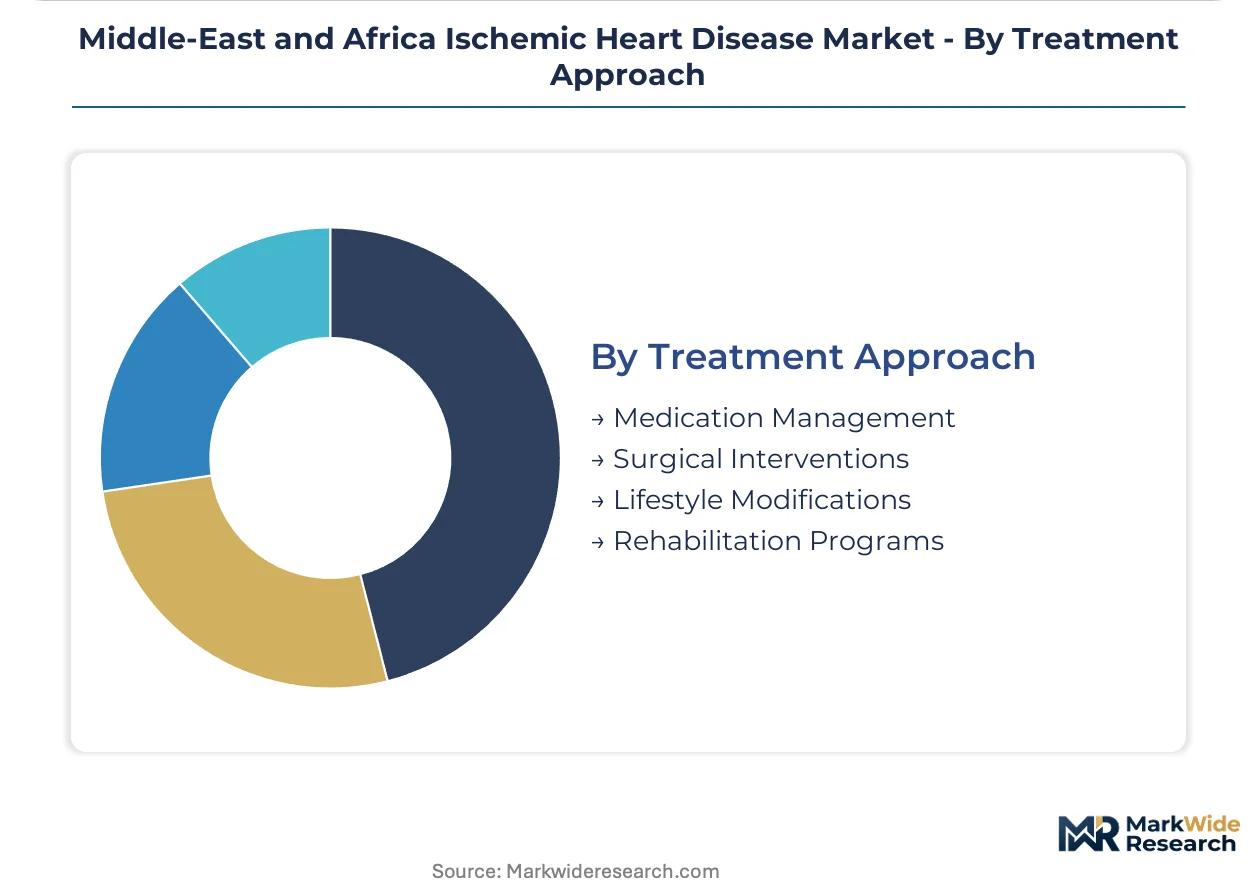
- Medication Management:Pharmacological control of atherosclerosis progression and symptom relief. This approach maintains the largest patient base across the Middle-East and Africa, though adherence challenges and generic substitution limit revenue per patient in South African public sector procurement.
- Surgical Interventions:Coronary artery bypass grafting and valve procedures for complex disease. Private hospital networks in Cape Town and Johannesburg capture disproportionate value per procedure through bundled payment negotiations covering stent placement and readmission rates.
- Lifestyle Modifications:Dietary, exercise, and smoking cessation programs for risk factor reduction.
- Rehabilitation Programs:Structured post-event recovery and secondary prevention services.
Patient volume favors Medication Management; revenue intensity favors Surgical Interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf state cardiac centers concentrate premium device procurement through privatized hospital networks, while South African and Egyptian facilities fragment purchasing across public and private channels.
Saudi Arabia
King Faisal Specialist Hospital and King Abdullah Medical City drive stent and diagnostic platform demand through expanded catheterization lab capacity. SFDA tightened medical device registration pathways, accelerating approval timelines for drug-eluting stents and fractional flow reserve systems. Riyadh and Jeddah anchor the kingdom's interventional cardiology infrastructure, with hospital privatization redirecting procurement authority from the Ministry of Health to facility-level committees.
United Arab Emirates
Dubai Healthcare City and Cleveland Clinic Abu Dhabi capture premium cardiac procedure volumes through medical tourism and domestic elite patient flows. MOHAP governs device approval and post-market surveillance, referencing EU MDR technical documentation standards during local reviews. Dubai's cardiac centers are adding angiography suites and telemedicine infrastructure to extend specialist reach into Northern Emirates populations.
South Africa
Netcare and Mediclinic hospital groups in Cape Town and Johannesburg negotiate outcome-based bundled payments covering stent placement and readmission rates. SAHPRA maintains non-harmonized clinical trial requirements with Gulf regulators, duplicating compliance burdens for manufacturers seeking multi-country approval. Public hospitals in Gauteng and Western Cape face budget constraints limiting drug-eluting stent adoption despite established clinical efficacy.
Egypt
Secondary facilities in Cairo and Alexandria lack interventional cardiologist concentration, leaving procedural capacity concentrated in tertiary centers. The country's national pharmaceutical regulator evaluates cardiac device imports against cost-effectiveness thresholds that favor bare-metal stents over premium drug-eluting alternatives. Private hospital groups in New Cairo are exploring equipment leasing models to lower catheterization lab capital barriers.
Israel
Sheba Medical Center and Hadassah Medical Center pioneer bioresorbable vascular scaffold adoption for younger patients requiring long-term vessel remodeling. The national medical device regulator aligns quality system expectations with EU MDR extraterritorial standards, accelerating product entry for European manufacturers. Tel Aviv's cardiac innovation cluster attracts pilot programs for remote cardiac monitoring platforms targeting underserved peripheral populations.
Middle-East and Africa Ischemic Heart Disease Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures created by Gulf hospital privatization. The vendor base splits between diversified cardiovascular conglomerates anchoring tertiary hospital relationships and focused interventional device specialists capturing premium stent segments. Three archetypes dominate: integrated platform providers bundling coronary and peripheral vascular offerings, drug-eluting stent specialists commanding preference in South African private networks, and diagnostic-imaging hybrid players leveraging telemedicine infrastructure investments. M&A activity concentrates on catheterization lab capacity expansion, while strategic partnerships target outcome-based contracting capabilities in privatized hospital networks.
Among US-based diversified manufacturers, Abbott Laboratories, Medtronic, and Boston Scientific Corporation exemplify distinct competitive positioning archetypes. Abbott represents the integrated structural heart platform approach, anchoring premium device segments through broad procedural coverage. Medtronic occupies the scale-driven position sustaining integrated coronary and peripheral vascular reach across Gulf state tertiary centers. Boston Scientific sits within the drug-eluting specialization tier, capturing preference in South African cardiac centers through focused stent technology positioning.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| GE Healthcare |
| Philips Healthcare |
| Biotronik |
| Siemens Healthineers |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Dubai Healthcare City's catheterization lab cluster concentrates high-value device procurement, with tertiary hospital expansion creating pricing power asymmetries between premium stent manufacturers and budget-constrained public facilities across the Gulf Cooperation Council states.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium drug-eluting stents and economy bare-metal alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects SFDA and MOHAP approval timelines, with Gulf state tertiary hospitals absorbing brand premiums while South African public sector procurement drives cost compression. Price differentiation hinges on after-sales service bundling and clinical outcome guarantees. Least price-sensitive buyers occupy privatized cardiac centers in Riyadh and Abu Dhabi; most sensitive buyers populate Egyptian secondary facilities facing national pharmaceutical regulator cost-effectiveness thresholds.
Supply Chain Analysis
Upstream cobalt-chromium alloy and polymer coating feedstocks draw from German precision metallurgy suppliers and US specialty chemical manufacturers. Device assembly concentrates in Ireland, Switzerland, and Malaysia for EU MDR-aligned quality systems. Single-source vulnerability runs through fractional flow reserve sensor microfabrication capacity anchored in Singapore and California. Distribution runs through authorized distributor networks in Saudi Arabia and direct hospital contracts in South Africa's privatized Netcare and Mediclinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital privatization across Gulf Cooperation Council states represents an early-cycle expansion story, with facility-level procurement authority creating new account entry points for device manufacturers ahead of regulatory harmonization completion.
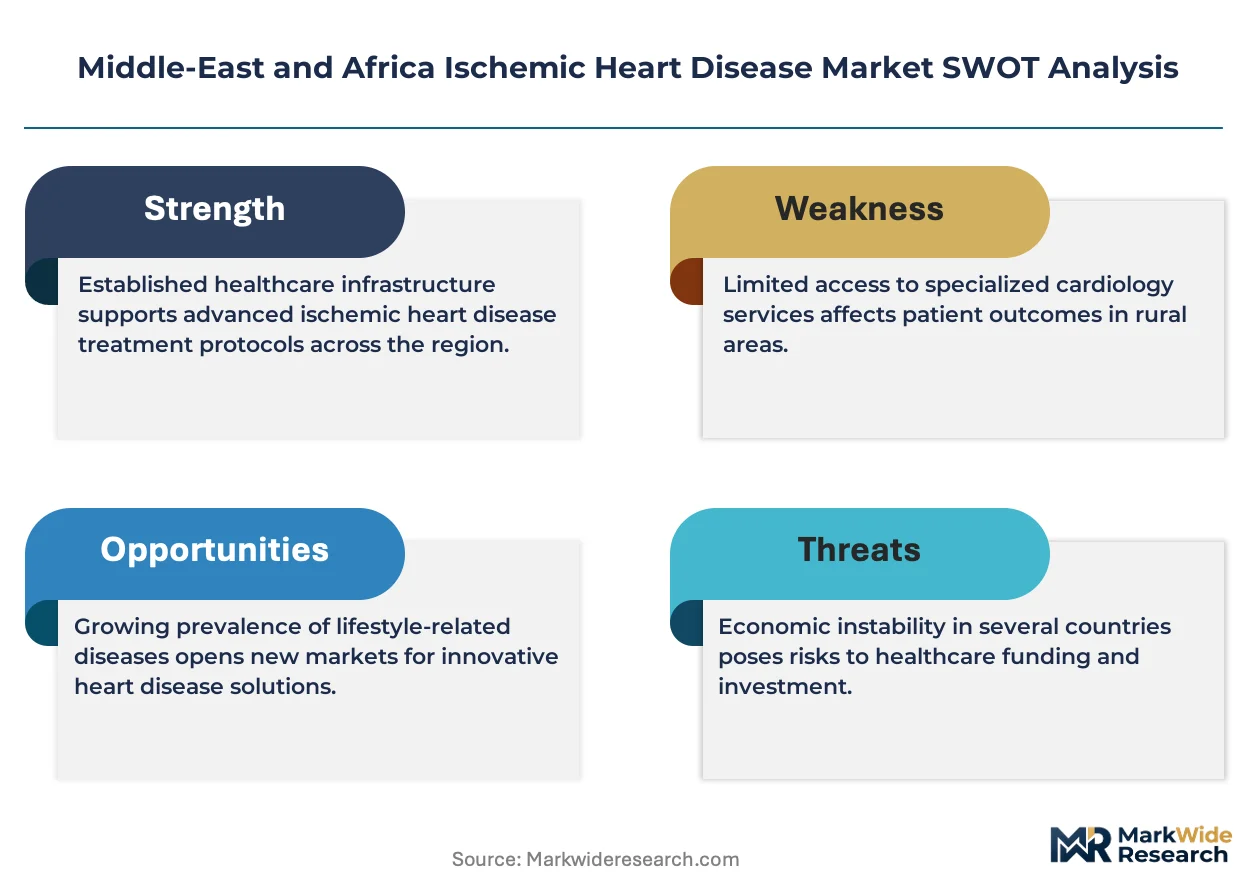
For Market Incumbents: Entrench catheterization lab relationships through equipment leasing partnerships that lock in multi-year consumable commitments. Deepen backward integration into bioresorbable polymer supply to defend margin position against emerging scaffold specialists. Prioritize SFDA and MOHAP regulatory affairs investment as Gulf harmonization accelerates approval timeline competition.
For New Entrants and Emerging Players: Build out telemedicine-integrated diagnostic platforms targeting Egyptian and Nigerian secondary facilities lacking interventional cardiologist concentration. Penetration is most achievable in remote cardiac monitoring infrastructure where Gulf health systems seek specialist reach extension. Go-to-market through Jordanian and Lebanese private hospital groups exploring project finance arrangements for angiography suite expansion.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic-imaging hybrid players leveraging telemedicine infrastructure investments. Long-term viability centers on outcome-based contracting capabilities as South African private networks displace traditional device procurement. Acquisition target archetype: catheterization lab capacity operators with established Cleveland Clinic Abu Dhabi or King Faisal Specialist Hospital relationships. Signal to watch: Gulf Cooperation Council regulatory alignment initiative implementation timelines as unified approval standard catalyst.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Fast-Track Registration | Accelerates market entry timelines for drug-eluting stent platforms in Saudi Arabia's privatized hospital networks. |
| Telemedicine Infrastructure Partnership | Extends specialist cardiac monitoring reach into UAE Northern Emirates underserved populations. |
| Equipment Leasing Model Deployment | Lowers catheterization lab capital barriers for Jordanian and Lebanese private hospital groups. |
| Biomarker-Diagnostic Bundling | Creates integrated troponin testing offerings for emergency departments across Egyptian secondary facilities. |
| Outcome-Based Contracting Capability | Captures bundled payment negotiations with South African Netcare and Mediclinic procurement committees. |
Study Parameters
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee members, biomedical engineering directors, and Gulf state regulatory affairs specialists and refined through secondary validation against SFDA device registration databases, MOHAP post-market surveillance filings, SAHPRA clinical trial registries, and EU MDR technical documentation standards. Bottom-up procedure volume estimates from cardiac centers in Riyadh, Dubai, and Johannesburg were triangulated against top-down healthcare expenditure flows from Gulf Cooperation Council ministry budgets and South African private hospital group capital expenditure disclosures.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type (stents, balloons, diagnostics), end user (tertiary hospitals, cardiac centers, specialty clinics), technology modality (invasive, non-invasive, telemedicine), and treatment approach (medication, surgical, lifestyle). CAGRs were derived from installed catheterization lab capacity expansion trajectories and procedure volume intensity assumptions, cross-referenced against SFDA and MOHAP approval pipeline data for new device entrants.
Practitioners should monitor Gulf regulatory harmonization implementation delays, South African public sector budget reallocation impacts, and Egyptian interventional cardiologist training program graduation rates for early signals of forecast revision. Cross-checking against EU MDR approval timelines and EUDAMED post-market surveillance reporting patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Stroke Management Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Pericarditis Treatment Market