
 Heart Transplant Market | 2026-2036
Heart Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Transplant Market Analysis
Post-transplant immunosuppression management revenue is fragmenting across biologic and small-molecule alternatives. Abbott Laboratories anchors its position through diagnostic monitoring platforms that track graft rejection biomarkers. TransMedics, Inc. differentiates via portable organ perfusion systems that extend viable ischemic time during donor heart transport. Berlin Heart GmbH specializes in ventricular assist devices that bridge patients to transplant eligibility.
A heart transplant replaces a diseased or failing heart with a donor organ through surgical implantation, requiring ABO blood type compatibility and negative crossmatch testing to prevent hyperacute rejection; the procedure serves end-stage heart failure patients when medical therapy and mechanical support prove insufficient. Orthotopic procedures dominate procedural volume while normothermic preservation technology captures expanding margin pools as transplant programs seek to reduce primary graft dysfunction rates. Organ perfusion systems represent the fastest-growing technology segment, displacing static cold storage in high-volume transplant centers across North America and Europe.
The FDA governs donor heart allocation through the Organ Procurement and Transplantation Network framework, while CMS reimbursement policies directly shape transplant center investment in advanced preservation technologies. The European Medicines Agency coordinates pharmacovigilance standards for immunosuppressive therapies under the EU Medical Device Regulation. Stakeholders must monitor evolving regulatory pathways for xenotransplantation trials and their potential to reshape donor pool constraints.
Market Dynamics
Normothermic preservation technology is compressing viable ischemic windows and forcing transplant centers to reallocate capital toward perfusion infrastructure or risk losing donor heart access to competing programs.
Growth Catalysts
- CMS Reimbursement Frameworks:Updated payment structures for advanced cardiac therapies incentivize US transplant centers to acquire portable organ perfusion systems. Procurement volumes rise as programs seek full reimbursement capture.
- German University Hospital Networks:Multi-organ retrieval logistics coordination across federal states reduces cold ischemia time through centralized donor pool management. This infrastructure investment lifts transplant eligibility rates.
- Biomarker Monitoring Platforms:Diagnostic tracking of graft rejection indicators enables precision immunosuppression dosing. Post-transplant survival metrics improve as clinicians titrate therapy based on real-time data.
Market Restraints
- Donor Pool Constraints:Static deceased donor availability creates allocation competition between heart, lung, and liver programs. Geographic mismatch between donor density and transplant center capacity persists.
- Perfusion System Capital Intensity:Portable normothermic devices require substantial upfront investment alongside disposable circuit costs. Smaller transplant programs face exclusion from technology access.
- Xenotransplantation Regulatory Friction:FDA and EMA pathways for porcine-derived organs remain underdeveloped. Clinical trial initiation delays alternative donor source commercialization.
Strategic Opportunities
- India Transplant Infrastructure:Underdeveloped organ retrieval networks and limited perfusion technology penetration create first-mover advantage for equipment vendors. Government health spending expansion supports center accreditation growth.
- Ventricular Assist Device Bridge-to-Transplant:Mechanical circulatory support eligibility expansion captures patients previously excluded from waitlists. Device-to-transplant workflow integration improves program throughput.
- Machine Perfusion Data Monetization:Real-time organ viability metrics collected during transport enable predictive analytics for graft outcome modeling. Transplant registries seek subscription access to perfusion biomarker datasets.
Industry Challenges
- Perfusion Specialist Workforce Scarcity:Normothermic system operation requires certified clinical perfusionists with cardiac surgery specialization. Training pipeline capacity lags behind technology deployment rates.
- Cross-Border Organ Transport Logistics:Multi-state and international donor heart movement encounters customs clearance delays and aviation scheduling constraints. Cold ischemia time accumulation threatens graft function.
- Immunosuppression Protocol Standardization:Center-specific variation in induction and maintenance regimens complicates multi-site clinical trial design. Pharmaceutical sponsors face enrollment friction from protocol heterogeneity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Transplant Market |
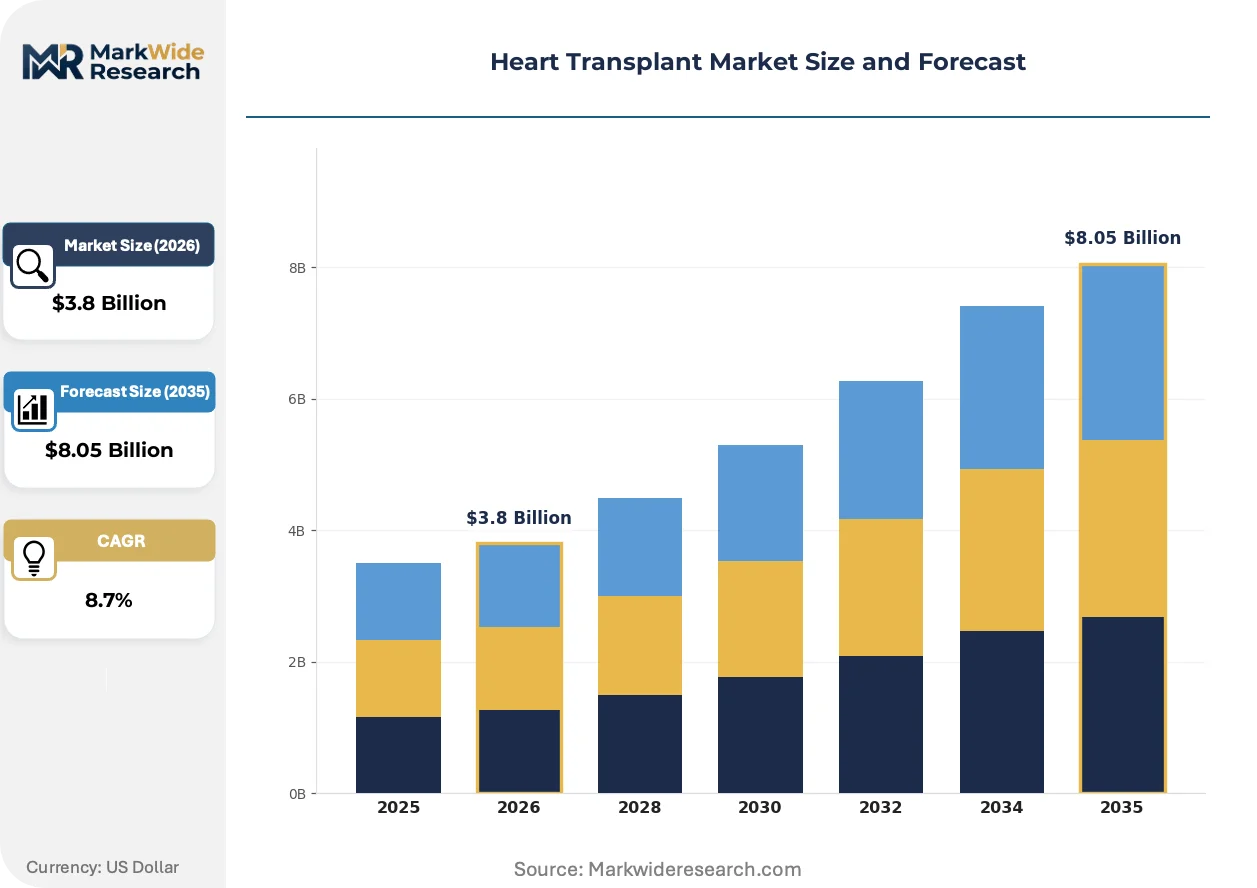
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Orthotopic, Heterotopic, Domino, Pediatric Technology: Mechanical Circulatory Support, Cold Storage, Normothermic Preservation, Organ Perfusion Systems End User: Hospitals, Specialty Clinics, Research Institutions, Transplant Centers Delivery Mode: Inpatient, Outpatient, Telemedicine, Hybrid |
| Companies Covered | TransMedics, Inc., Jarvik Heart Inc, Abbott Laboratories, LivaNova Plc, Berlin Heart GmbH, Medtronic plc, BiVACOR Inc, Abiomed Inc, SynCardia Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Transplant Market Emerging Trajectories
Digital twin modeling and machine learning applications are penetrating graft viability assessment, compressing decision timelines from donor acceptance to implant scheduling.
Normothermic regional perfusion systems maintain donor hearts at physiologic temperature during transport, extending viable preservation from four hours toward twelve. High-volume transplant centers in the United States and Germany are replacing static cold storage with these active perfusion platforms. The technology is virtualizing traditional procurement geography by enabling longer-distance donor heart retrieval without ischemic damage penalties.
The European Union Medical Device Regulation imposes stricter clinical evidence requirements on organ perfusion systems classified as Class III devices. Manufacturers must generate post-market surveillance data across multiple member states to maintain CE marking. Transplant programs in France and Italy are delaying procurement decisions pending clarified notified body guidance on perfusion circuit biocompatibility testing.
Transplant center purchasing committees are consolidating vendor relationships around single-source perfusion technology contracts with bundled disposable supply agreements. Independent service organizations and third-party maintenance providers are losing access as centers negotiate captive service terms directly with device manufacturers. This concentration is most visible in the Northeastern and Midwestern United States, where health system consolidation has created multi-hospital transplant networks with centralized procurement authority.
Heart Transplant Market Segmentation
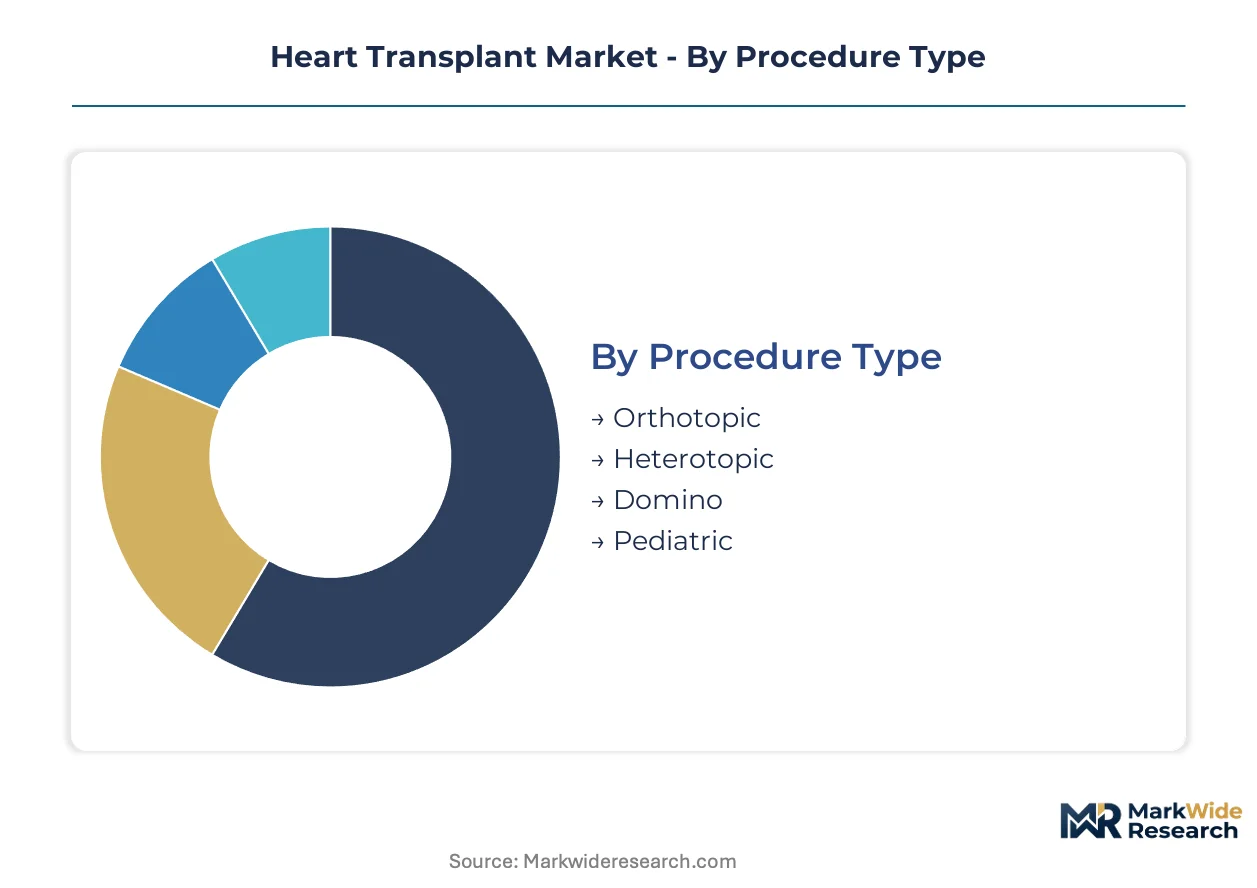
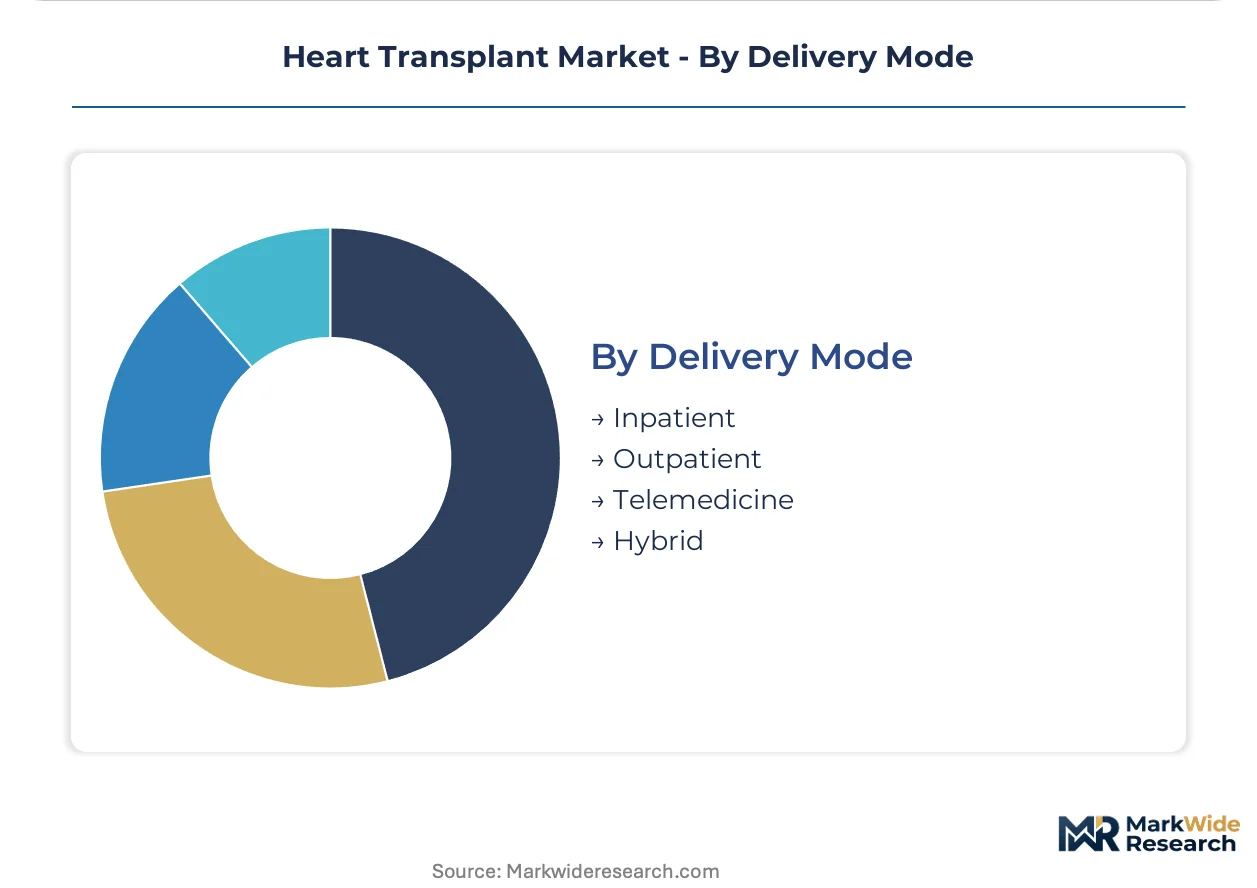
Heart transplant market segmentation reveals distinct procurement patterns across procedure types, preservation technologies, and care delivery settings. Centers allocate capital toward technologies that compress ischemic time while patient volume concentrates in high-acuity inpatient settings.
Procedure Type:
Cost tier stratification separates complex multi-stage interventions from streamlined single-procedure workflows, with reimbursement intensity tracking surgical complexity and post-operative resource consumption.
- Orthotopic:The donor heart replaces the recipient's native heart entirely, requiring atrial and great vessel anastomosis. Demand concentrates in high-volume US transplant centers pursuing full CMS reimbursement for advanced cardiac therapies. Primary graft dysfunction rates drive center investment in normothermic preservation infrastructure.
- Heterotopic:The donor heart implants alongside the native heart, preserving residual right ventricular function. Applications cluster in pulmonary hypertension cases across German university hospital networks where bridge-to-transplant protocols are standardized. This procedure captures patients excluded from orthotopic candidacy.
- Domino:The recipient's native heart serves as a donor organ for a second patient. Volume remains constrained by donor-recipient size matching requirements.
- Pediatric:Specialized surgical techniques address congenital anomalies and size-disparate donors. Programs concentrate at dedicated children's hospitals with congenital heart surgery specialization.
Orthotopic commands the established base. The steepest expansion runs through pediatric protocols as survival improvements extend eligibility to younger patients.
Technology:
Application-specific performance requirements separate devices that bridge patients to transplant from those preserving donor organ viability during logistics.
- Mechanical Circulatory Support:Ventricular assist devices and total artificial hearts sustain patients until donor organ availability. Bridge-to-transplant eligibility expansion at US centers captures patients previously excluded from waitlists. Device-to-transplant workflow integration improves program throughput metrics.
- Organ Perfusion Systems:Portable normothermic platforms maintain donor hearts at physiologic temperature during transport, extending viable preservation windows. North American and European high-volume centers displace static cold storage with these active perfusion platforms. The technology virtualizes procurement geography by enabling longer-distance retrieval without ischemic damage penalties.
- Cold Storage:Static hypothermic preservation remains standard at resource-constrained programs. Usage contracts as perfusion technology penetrates high-volume centers.
- Normothermic Preservation:Regional perfusion systems maintain organs at body temperature through ex-vivo circulation. Adoption accelerates following updated CMS reimbursement frameworks.
Mechanical circulatory support anchors current revenue. Organ perfusion systems are climbing the fastest as transplant programs reallocate capital toward active preservation infrastructure.
End User:
Customer type determines procurement authority, with consolidated health system networks exercising centralized purchasing control over independent specialty clinics.
- Transplant Centers:Designated programs with UNOS membership and CMS certification perform the surgical implantation and post-operative management. US centers in the Northeast and Midwest consolidate vendor relationships around single-source perfusion contracts with bundled disposable agreements.
- Hospitals:General acute care facilities refer patients and manage pre-transplant stabilization. Volume concentrates at academic medical centers with cardiac surgery residency programs.
- Specialty Clinics:Cardiology practices manage heart failure progression and transplant evaluation. Patient funnel functions dominate procedural revenue capture.
- Research Institutions:Xenotransplantation trials and perfusion biomarker studies occur at NIH-funded centers. Regulatory friction delays alternative donor source commercialization.
Transplant centers hold concentrated purchasing power. The steepest capacity expansion runs through hospital-based program accreditation.
Delivery Mode:
Volume distribution reflects care setting intensity, with high-acuity inpatient episodes dominating reimbursement capture against emerging remote monitoring applications.
- Inpatient:Surgical implantation and immediate post-operative critical care require ICU capacity and specialized nursing. All heart transplants occur in this setting.
- Outpatient:Post-transplant surveillance biopsies and immunosuppression monitoring shift toward ambulatory settings as graft stability establishes.
- Hybrid:Combined telemedicine and in-person protocols manage stable patients at geographic distance from transplant centers. Remote graft rejection biomarker tracking enables precision dosing adjustments.
- Telemedicine:Virtual consultations address routine immunosuppression management and infection screening. Penetration remains limited by biopsy requirements.
Inpatient episodes capture virtually all procedural value. Hybrid delivery models are gaining share fastest as remote monitoring platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Donor heart procurement infrastructure concentrates in health systems with established transplant networks and favorable reimbursement frameworks. Germany and the United States anchor supply-side capacity through university hospital coordination and CMS payment structures respectively.
United States
FDA oversight of the Organ Procurement and Transplantation Network governs donor allocation algorithms. Northeastern and Midwestern health systems consolidate vendor relationships around single-source perfusion contracts. Greater Boston transplant networks coordinate multi-state organ retrieval logistics.
Germany
University hospital networks manage multi-organ retrieval across federal states through centralized donor pool coordination. EMA pharmacovigilance standards under EU Medical Device Regulation shape immunosuppressive therapy protocols. Bavarian cardiac surgery centers pioneer bridge-to-transplant mechanical support workflows.
France
Agence de la Biomédecine coordinates national organ allocation with strict geographic proximity matching. ANSM and notified body guidance on perfusion circuit biocompatibility testing delays procurement decisions at Paris transplant centers. Île-de-France academic hospitals await clarified CE marking pathways.
India
Government health spending expansion supports transplant center accreditation growth under the National Organ Transplant Programme. CDSCO regulatory frameworks for medical devices create compliance hurdles for imported perfusion systems. Maharashtra and Karnataka hospital networks develop indigenous organ retrieval infrastructure.
United Kingdom
NHS Blood and Transplant manages donor heart allocation through centralized waiting list management. MHRA post-Brexit regulatory divergence from EU MDR creates uncertainty for perfusion device market authorization. London and Southeast transplant programs concentrate pediatric heart failure expertise.
Heart Transplant Market Vendor Landscape
Perfusion technology specialists and diversified cardiac device manufacturers split the market across preservation and mechanical support vectors. The vendor base clusters around three strategic archetypes: portable organ perfusion platform developers, ventricular assist device specialists, and integrated diagnostic monitoring providers. Consolidation pressures intensify as transplant centers negotiate bundled disposable agreements and captive service terms directly with manufacturers.
Within the perfusion technology tier, TransMedics, Inc. and Berlin Heart GmbH exemplify divergent specialization models. Abbott Laboratories anchors the diagnostic monitoring segment through graft rejection biomarker platforms. These three entities represent distinct competitive positions without overlapping core technology footprints.
| Leading Market Players |
|---|
| TransMedics, Inc. |
| Jarvik Heart Inc |
| Abbott Laboratories |
| LivaNova Plc |
| Berlin Heart GmbH |
| Medtronic plc |
| BiVACOR Inc |
| Abiomed Inc |
| SynCardia Systems LLC |
| Others |
Supply Flow & Price Mechanics
Undercapacity in certified clinical perfusionist training pipelines constrains normothermic system deployment, forcing transplant centers to bid up service contracts and accept captive pricing terms from device manufacturers. This utilization squeeze transfers pricing power upstream while compressing margins at programs unable to secure bundled disposable agreements.
Pricing Analysis
After-sales revenue from disposable perfusion circuits and captive service contracts drives lifetime value for equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates high-volume academic centers with bundled agreements from mid-tier programs on transactional terms and resource-constrained sites relegated to cold storage. Pricing pressure stems from CMS reimbursement rate compression for advanced cardiac therapies, which limits capital allocation flexibility at transplant programs. Community hospitals and emerging international centers exhibit highest price sensitivity, while consolidated US health system networks leverage volume for preferential terms.
Supply Chain Analysis
Contract manufacturing concentration for portable perfusion systems rests with specialized medical device EMS providers in Germany, Ireland, and Massachusetts. Critical component dependencies include biocompatible circuit polymers, battery systems for transport units, and sterile packaging materials. Single-source vulnerability in membrane oxygenator supply creates exposure to regulatory inspection delays at notified bodies. Distribution runs through direct manufacturer-to-hospital contracts with field service engineers embedded at high-volume transplant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. FDA and EMA certification requirements for Class III perfusion devices create insurmountable switching costs that protect incumbent positions.
For Market Incumbents: Insulate market position through backward integration into disposable circuit manufacturing and exclusive service contracts with consolidated health system networks. Emerging entrants from adjacent cardiac surgery device segments threaten pricing architecture through cross-subsidized perfusion platform launches. Priority defensive investment centers on perfusion specialist training pipeline partnerships that lock in operational dependency. For New Entrants and Emerging Players: India's underdeveloped organ retrieval infrastructure and limited normothermic technology penetration offer first-mover positioning before government accreditation expansion accelerates. White-space targets include indigenous perfusion device assembly for cost-sensitive hospital networks and remote monitoring software for hybrid post-transplant care. Go-to-market execution should anchor on CDSCO regulatory pathway navigation services bundled with equipment supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across organ perfusion technology manufacturing as EU MDR clinical evidence requirements demand expanded post-market surveillance infrastructure. Long-term viability favors platforms with installed base expansion potential and recurring revenue density over hardware-only plays. Acquisition target archetype: mid-cap perfusion specialists with CE marking and nascent US commercial presence. Signal to monitor: FDA xenotransplantation trial advancement timelines that would reshape donor pool economics.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Specialist Training Partnership | Addresses workforce scarcity constraining normothermic system deployment at expansion-phase transplant centers. |
| CE Marking Pathway Acceleration | Resolves notified body guidance delays blocking perfusion circuit procurement decisions at French and Italian centers. |
| Hospital System Partnership | Captures bundled disposable agreements as Northeastern and Midwestern US networks consolidate vendor relationships. |
| Reimbursement Strategy | Aligns CMS framework navigation with advanced cardiac therapy payment structure updates. |
| Software Companion Development | Enables predictive analytics monetization from real-time organ viability metrics during transport. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with transplant surgeons, clinical perfusionists, hospital purchasing committee members, and biomedical engineering directors. Secondary validation drew from FDA 510(k) filings, EMA device registration databases, CMS Medicare cost report data, and UNOS transplant registry statistics. Bottom-up modeling of procedure volumes and equipment procurement cycles triangulated against top-down market sizing from manufacturer revenue disclosures.
Calibration against historical penetration rates for normothermic preservation technology informed expansion assumptions across the projection horizon. Segmentation dimensions modeled encompass procedure type, preservation technology, end-user category, and delivery mode alongside geographic regulatory cluster differentiation. CAGRs were derived from fitted adoption curves weighted by reimbursement policy inflection points and transplant center accreditation trajectories. Forecast inputs incorporated perfusion system capital expenditure cycles and immunosuppression protocol standardization timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by xenotransplantation platform developers or cross-border organ transport logistics disruptors would shift outcomes substantially. Regulatory pathway acceleration for porcine-derived organs and machine learning graft viability applications represent primary revision risks. Quarterly review of CMS reimbursement bulletins and notified body guidance publications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Ischemia Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Heart Health Products Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Global Statin Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Chronic Heart Failure Market
Cardiovascular
Stroke Management Market
Cardiovascular
Cardio-Selective Beta Blockers Market