
 Endocarditis Therapeutics Market | 2026-2036
Endocarditis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Endocarditis Therapeutics Market Foresight
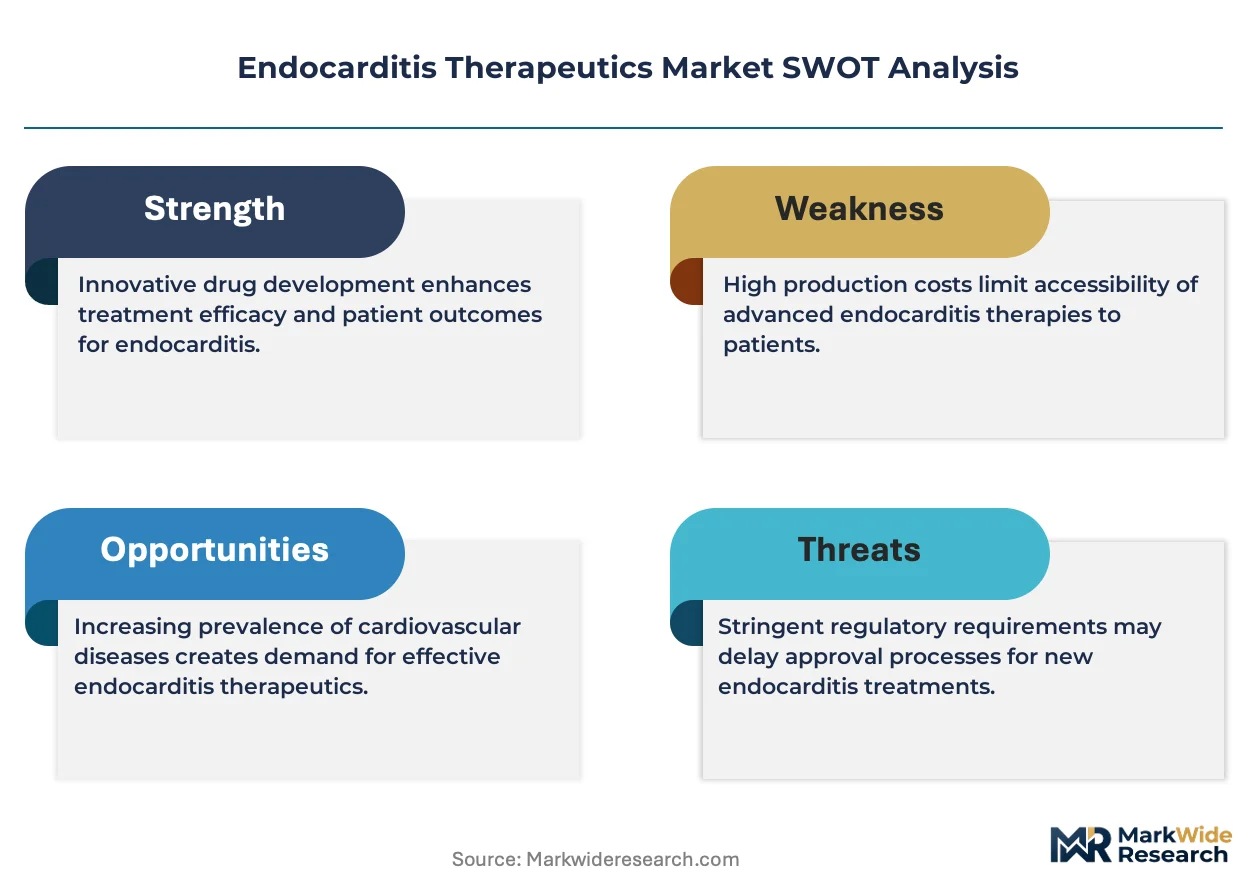
Treatment protocols for endocarditis is restructuring around a widening gap between premium branded antifungal therapies and commodity generic antibiotic regimens. Pfizer Inc. leverages its established anti-infective portfolio to sustain hospital formulary presence across major cardiac centers. Novartis AG anchors its position through immunosuppressant expertise that addresses prosthetic valve-related complications. Merck & Co. Inc. differentiates via manufacturing scale in parenteral cephalosporin production.
Endocarditis therapeutics encompasses pharmaceutical and surgical interventions targeting inflammation of the endocardial lining, typically involving four to six weeks of high-dose intravenous antimicrobial therapy guided by blood culture sensitivity and echocardiographic vegetation assessment. The primary purpose centers on pathogen eradication, embolic risk reduction, and preservation of native or prosthetic valve function. Antibiotics dominate current revenue flow due to entrenched clinical guidelines for bacterial endocarditis, while antifungal segments capture concentrated margin pools amid rising Candida and Aspergillus valve infections in immunocompromised populations. Intravenous delivery mode maintains structural priority for inpatient settings, though oral step-down protocols are gaining traction in stable patients meeting hemodynamic and microbiologic criteria.
FDA antimicrobial stewardship mandates and EMA pharmacovigilance frameworks tighten prescribing surveillance, directly shaping hospital procurement criteria and reimbursement thresholds for novel agents. Health Canada and Japan's PMDA impose parallel manufacturing quality standards that filter market access for generic injectable suppliers. Stakeholders must monitor evolving resistance surveillance data and regulatory exclusivity timelines to calibrate portfolio investments between established antibiotic classes and emerging targeted therapies.
Market Dynamics
FDA antimicrobial stewardship mandates and EMA pharmacovigilance frameworks are compressing formulary access for broad-spectrum antibiotics, forcing manufacturers to demonstrate resistance-specific efficacy before hospital procurement committees. This regulatory tightening is restructuring competitive positioning around narrow-spectrum agents with documented microbiologic outcomes.
Growth Catalysts
- Rising prosthetic valve implantation volumes:Aging demographics in Germany and Japan are expanding the addressable patient pool for device-related endocarditis requiring extended parenteral therapy.
- CDC resistance surveillance expansion:Enhanced bloodstream infection tracking in the United States is accelerating pathogen-specific diagnostic adoption and targeted antimicrobial selection.
- Oral step-down protocol validation:Clinical data supporting outpatient conversion for stable patients is extending therapy completion rates and reducing hospitalization burden.
Market Restraints
- Active pharmaceutical ingredient concentration:China dominates cephalosporin and penicillin intermediate supply, creating single-source vulnerability for parenteral antibiotic manufacturing.
- Extended manufacturing inspection timelines:FDA pre-approval facility audits for sterile injectable sites are stretching new product entry timelines by 18-24 months.
- Generic substitution pressure:Commodity vancomycin and gentamicin pricing erosion is compressing margin pools for established hospital antibiotic portfolios.
Strategic Opportunities
- Outpatient antimicrobial therapy (OPAT) infrastructure:Home infusion capabilities in the United States and United Kingdom are creating channel expansion for stable patient cohorts meeting hemodynamic criteria.
- Combination antifungal development:Candida auris valve infection clusters are driving demand for novel azole-echinocandin protocols in immunocompromised populations.
- Japan PMDA Sakigake designation:Expedited review pathways for resistant organism therapies are attracting development investment for methicillin-resistant Staphylococcus aureus (MRSA) targeted agents.
Industry Challenges
- Specialized infectious disease pharmacist scarcity:Hospital antimicrobial stewardship team expansion is outpacing board-certified ID pharmacy fellowship output in the United States.
- Sterile fill-finish capacity constraints:Multi-dose vial production lines for extended-course parenteral therapy require capital-intensive isolator technology upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endocarditis Therapeutics Market |
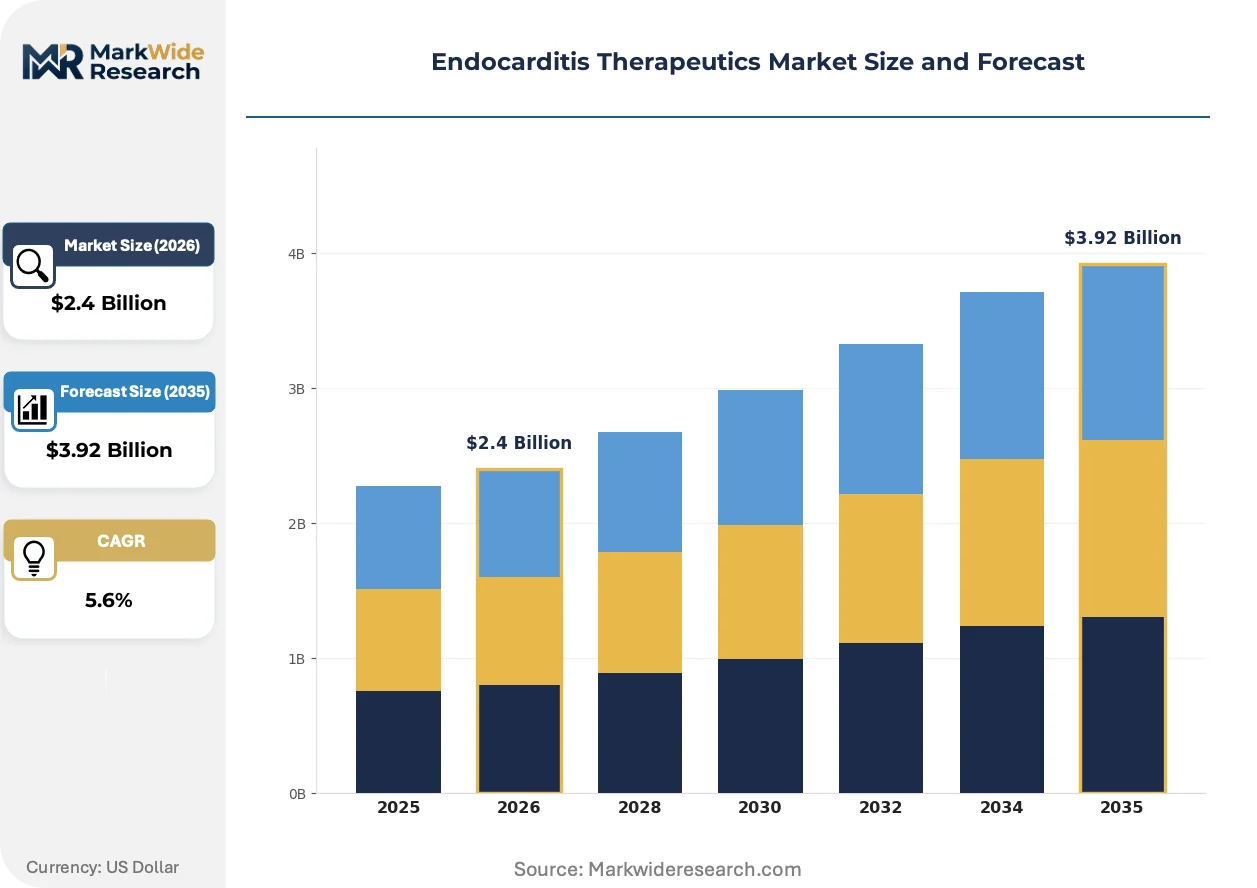
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Immunosuppressants, Surgical Intervention Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Age Group: Pediatrics, Adults, Geriatrics, Others |
| Companies Covered | Pfizer Inc., Novartis AG, Merck & Co. Inc., F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Fresenius Kabi AG, AbbVie Inc., Mylan N.V., ContraFect Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endocarditis Therapeutics Market Shifts & Advancements
Clinical practice is pivoting from empirical broad-spectrum coverage toward pathogen-directed therapy enabled by rapid molecular diagnostics and compressed blood culture turnaround. This shift is redrawing competitive boundaries between diagnostic and pharmaceutical suppliers.
Rapid antimicrobial susceptibility testing platforms are integrating mass spectrometry and PCR-based resistance gene detection to compress identification timelines from 48-72 hours to under six hours. Major cardiac centers in the United States and Germany are adopting these systems to accelerate targeted therapy initiation. The technology is integrating diagnostic and therapeutic decision workflows, reducing empirical vancomycin exposure and shortening intensive care unit lengths of stay.
EMA's revised clinical trial guidance for hospital-acquired bacterial infections is mandating pathogen-specific enrollment stratification and all-cause mortality endpoints rather than composite clinical cure measures. This regulatory tightening is elevating trial costs and extending development timelines for novel agents. Smaller biotechnology developers are responding through partnership structures with established hospital antibiotic marketers to share commercialization infrastructure.
Hospital procurement committees are consolidating antimicrobial purchasing through centralized therapeutic class reviews rather than individual product negotiations. This behavioral shift is concentrating volume with suppliers offering resistance surveillance data sharing and stewardship program support. The United States and United Kingdom are exhibiting the most pronounced committee centralization, with integrated delivery networks and National Health Service trusts respectively driving standardization across multiple facility sites.
Endocarditis Therapeutics Market Segmentation
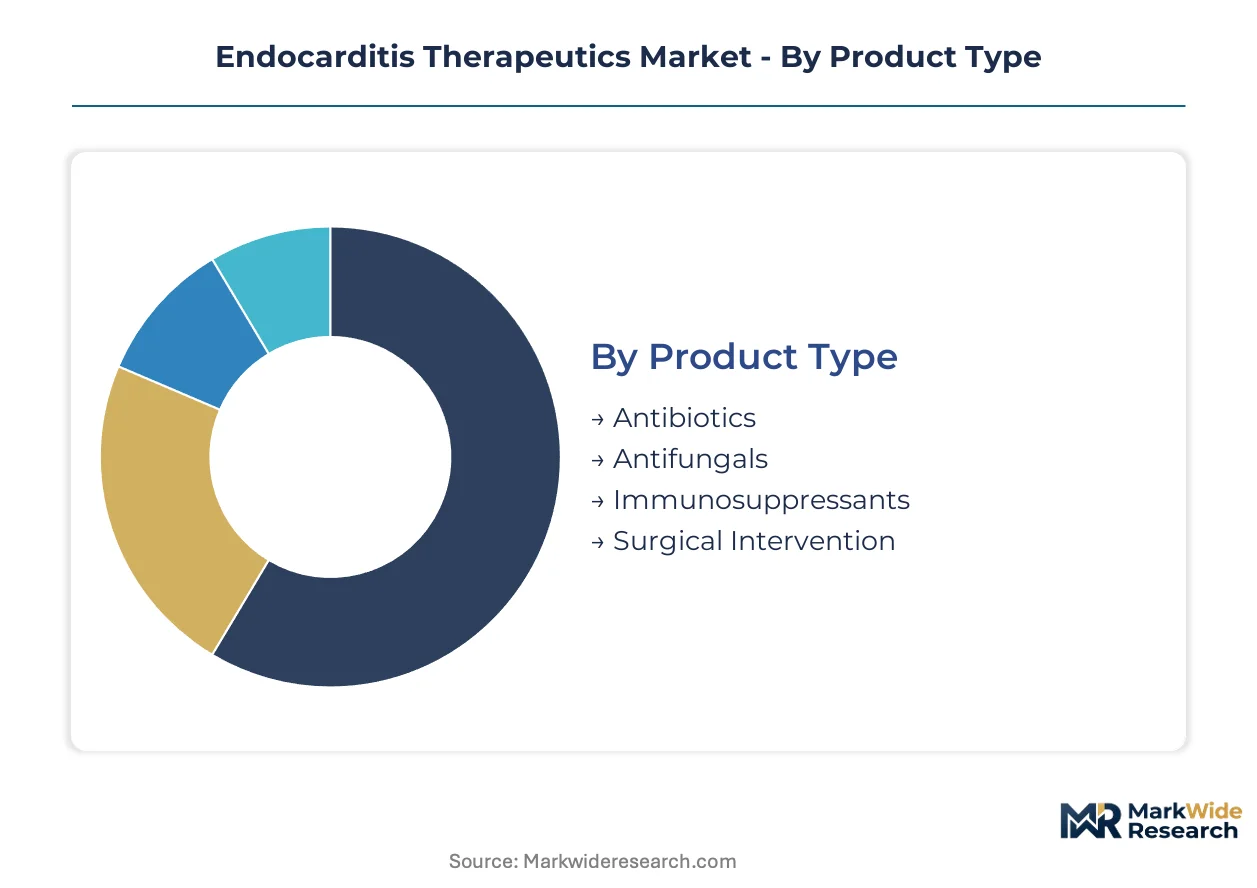
Endocarditis therapeutics segmentation reflects divergent regulatory pathways across antimicrobial classes and care settings. Each category carries distinct FDA, EMA, and PMDA approval burdens that shape manufacturer investment priorities and hospital procurement criteria.
Product Type:
FDA antimicrobial stewardship mandates and EMA pharmacovigilance frameworks impose tiered approval intensity across therapeutic classes, with sterile injectables facing the most stringent manufacturing inspections.
- Antibiotics:Beta-lactam, glycopeptide, and lipopeptide formulations dominate hospital formularies through established susceptibility-guided protocols. Demand concentrates in cardiac surgery centers across the United States and Germany, where CDC and ECDC resistance surveillance drives formulary restrictions on broad-spectrum agents.
- Antifungals:Azole and echinocandin therapies target Candida and Aspergillus valve infections in immunocompromised cohorts. Japan's PMDA Sakigake designation accelerates review for resistant organism therapies, attracting development investment for combination protocols addressing Candida auris clusters.
- Immunosuppressants:Corticosteroid and calcineurin inhibitor regimens manage prosthetic valve-related inflammatory complications.
- Surgical Intervention:Valve repair and replacement procedures complement pharmaceutical therapy in hemodynamically unstable patients.
Antibiotics sit at the top of the volume ranking, with antifungals climbing the fastest amid rising resistant fungal infections in transplant and oncology populations.
Delivery Mode:
Cost tier stratification separates capital-intensive sterile manufacturing from commodified oral formulations, with reimbursement differentials widening between inpatient and outpatient channels.
- Intravenous:Extended-course parenteral therapy requires isolator technology and FDA pre-approval facility audits stretching timelines by 18-24 months. Hospital procurement committees in the United States and United Kingdom centralize purchasing through therapeutic class reviews, concentrating volume with suppliers offering resistance surveillance data sharing.
- Oral:Step-down protocols enable outpatient conversion for stable patients meeting hemodynamic and microbiologic criteria, extending therapy completion rates. Demand is accelerating in United States home infusion networks and United Kingdom NHS trusts expanding OPAT infrastructure.
- Topical:Limited application for localized surgical site prophylaxis in cardiac procedures.
- Inhalation:Investigational delivery for respiratory complications in select endocarditis cases.
Intravenous maintains the dominant volume position, while oral delivery gains share fastest through validated step-down protocols reducing hospitalization burden.
End User:
Customer type determines reimbursement pathway complexity, with integrated delivery networks and national health systems imposing distinct procurement standardization pressures.
- Hospitals:Tertiary cardiac centers perform the bulk of valve surgeries and manage complex infective endocarditis requiring intensive care unit monitoring. Germany's university hospitals and Japan's designated cancer centers anchor regional demand through concentrated cardiac surgery volumes.
- Clinics:Outpatient infectious disease practices coordinate post-discharge monitoring and laboratory surveillance for patients completing extended antimicrobial courses.
- Home Healthcare:Infusion nursing services and remote monitoring platforms enable OPAT expansion in the United States, where Medicare reimbursement supports home-based parenteral administration.
- Rehabilitation Centers:Post-acute facilities manage recovery for patients with residual cardiac dysfunction following surgical intervention.
Hospitals capture the highest volume concentration, with home healthcare expanding most quickly through reimbursement-enabled OPAT infrastructure.
Age Group:
Demographic segmentation aligns with prosthetic valve implantation patterns and congenital heart disease prevalence, driving differential therapy duration and surgical candidacy.
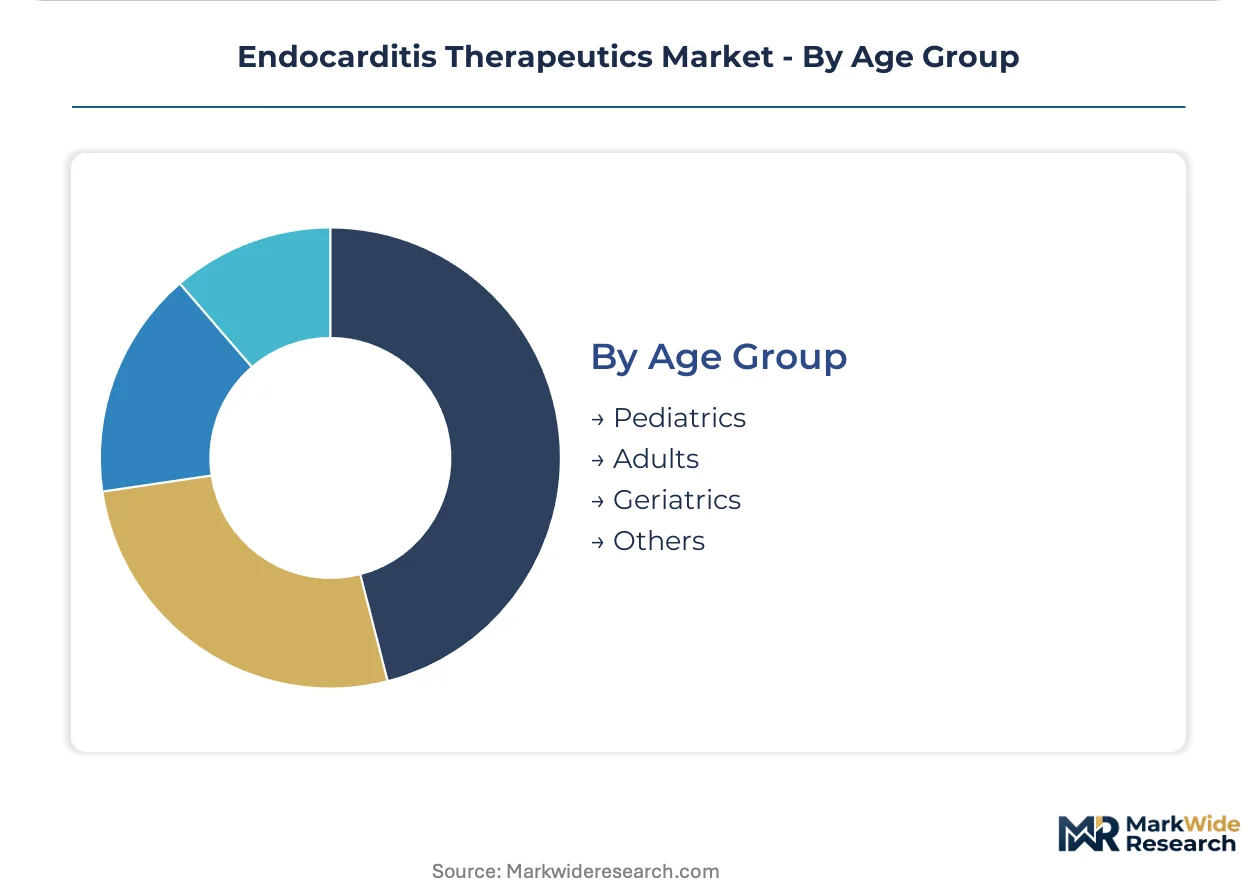
- Geriatrics:Aging populations in Germany and Japan generate the preponderance of device-related endocarditis cases requiring extended parenteral therapy. This cohort faces elevated surgical risk scores that prolong medical management and increase hospital length of stay.
- Adults:Native valve endocarditis in middle-aged patients often stems from injection drug use or structural cardiac abnormalities, with treatment protocols emphasizing pathogen-directed therapy guided by rapid molecular diagnostics.
- Pediatrics:Congenital heart disease-related endocarditis requires specialized dosing and multidisciplinary cardiac surgery coordination.
- Others:Neonatal and peripartum cases represent rare presentations with distinct microbiologic profiles.
Geriatrics holds the top volume position, with adults gaining share fastest through diagnostic-enabled targeted therapy reducing empirical broad-spectrum exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified infectious disease pharmacists and cardiac surgery specialists concentrate in tertiary medical centers across Germany, Japan, and the United States, anchoring regional demand for extended parenteral antimicrobial protocols.
United States
CDC resistance surveillance expansion and Medicare reimbursement for outpatient parenteral antimicrobial therapy drive hospital procurement centralization. FDA antimicrobial stewardship mandates tighten formulary access for broad-spectrum agents. Major cardiac centers in Cleveland and Houston anchor regional demand through concentrated valve surgery volumes and integrated delivery network purchasing consolidation.
Germany
Aging demographics and rising prosthetic valve implantation rates expand the addressable patient pool for device-related endocarditis. EMA pharmacovigilance frameworks reshape hospital procurement criteria around documented microbiologic outcomes. University hospitals in Munich and Berlin concentrate specialized infectious disease pharmacy expertise and cardiac surgery coordination.
Japan
Designated cancer centers and cardiac surgery hubs generate concentrated demand for resistant organism therapies. PMDA Sakigake designation accelerates review pathways for MRSA-targeted agents, attracting development investment. Tokyo and Osaka metropolitan areas anchor national demand through aging population density and tertiary referral patterns.
United Kingdom
NHS trust standardization drives antimicrobial purchasing consolidation across multiple facility sites. National Institute for Health and Care Excellence guidelines shape step-down protocol adoption for stable patients meeting hemodynamic criteria. London and Manchester cardiac centers lead OPAT infrastructure expansion through home infusion network development.
Switzerland
Swissmedic manufacturing quality standards filter market access for generic injectable suppliers, privileging established sterile fill-finish operators. University hospital networks in Zurich and Geneva concentrate specialized endocarditis management expertise and coordinate cross-border referral patterns with neighboring EU cardiac centers.
Endocarditis Therapeutics Market Competitive Landscape
Capital-heavy producers with captive sterile manufacturing infrastructure compete with asset-light developers licensing fill-finish capacity for parenteral antibiotic commercialization. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with hospital formulary anchoring, mid-cap generic injectable specialists with FDA pre-approved facility status, and biotechnology developers pursuing partnership structures for commercialization infrastructure. Consolidation pressure intensifies through centralized therapeutic class reviews by hospital procurement committees and extended FDA pre-approval audit timelines stretching new product entry.
Within the multinational tier, Pfizer Inc. and Novartis AG exemplify divergent strategic positioning around anti-infective portfolio depth versus immunosuppressant expertise for prosthetic valve complications. Merck & Co. Inc. occupies a position defined by manufacturing scale in parenteral cephalosporin production. Among generic injectable specialists, Teva Pharmaceutical Industries Ltd. and Mylan N.V. represent archetypes of commodity antibiotic supply facing margin compression from vancomycin and gentamicin pricing erosion. Fresenius Kabi AG anchors the European hospital channel through integrated infusion therapy and parenteral nutrition bundling. ContraFect Corporation exemplifies the biotechnology archetype pursuing resistant organism therapies through expedited regulatory pathways.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Merck & Co. Inc. |
| F. Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| AbbVie Inc. |
| Mylan N.V. |
| ContraFect Corporation |
| Others |
Supply & Pricing Matrix
Captive sterile fill-finish infrastructure anchors pricing power for established parenteral antibiotic suppliers, while outsourced manufacturing contracts expose generic entrants to FDA audit delays and procurement committee exclusion. This integration choice separates premium-positioned operators from commodity suppliers facing vancomycin and gentamicin price erosion.
Pricing Analysis
Bundled infusion therapy packages dominate hospital procurement, with unbundled commodity vials competing on spot purchasing for cost-conscious facilities. Price differentiation hinges on FDA pre-approved facility status and resistance surveillance data-sharing agreements, with stewardship program support commanding premium positioning. Pricing pressure intensifies through centralized therapeutic class reviews consolidating volume with select suppliers. Generic injectable specialists exhibit highest price sensitivity, while multinational operators with captive manufacturing maintain pricing resilience.
Supply Chain Analysis
Certification gating through FDA pre-approval facility audits and EMA GMP inspections filters market access, privileging established sterile manufacturers over new entrants. Active pharmaceutical ingredient supply concentrates in China for cephalosporin and penicillin intermediates, with India anchoring generic finished dose production. Supply chain risk centers on single-source API dependency for extended-course parenteral therapies. Distribution runs through hospital procurement committees and integrated delivery networks in the United States, with NHS trust centralization in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endocarditis therapeutics market compounds steadily through aging demographic tailwinds expanding prosthetic valve implantation volumes and device-related infection incidence.
For Market Incumbents: Deepen backward integration into sterile fill-finish capacity to defend against FDA audit timeline compression and procurement committee consolidation. Expand resistance surveillance data-sharing partnerships with hospital stewardship teams to anchor formulary position against generic substitution pressure. For New Entrants and Emerging Players: Begin with outpatient parenteral antimicrobial therapy infrastructure partnerships in the United States and United Kingdom, where reimbursement-enabled home infusion networks remain underpenetrated. Target combination antifungal development for Candida auris valve infections, leveraging Japan's PMDA Sakigake expedited review pathway as regulatory differentiation. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap generic injectable specialists because FDA pre-approved facility scarcity concentrates acquisition value in sterile manufacturing assets with established hospital channel access. Monitor oral step-down protocol validation rates as inflection indicator for OPAT infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Stewardship Program Partnership | Data-sharing agreements with CDC surveillance networks anchor hospital formulary placement against competitors. |
| OPAT Infrastructure Investment | Home infusion capabilities in United States Medicare reimbursement channels extend therapy completion rates. |
| Combination Antifungal Development | Azole-echinocandin protocols address rising Candida auris clusters in immunocompromised transplant populations. |
| Sterile Manufacturing Scale-Up | Isolator technology upgrades for multi-dose vial production lines meet FDA extended-course therapy demand. |
| Expedited Regulatory Pathway Pursuit | PMDA Sakigake designation accelerates MRSA-targeted agent review for Japan's designated cancer centers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with infectious disease pharmacists, hospital procurement managers, regulatory affairs leads at sterile manufacturers, and cardiac surgery coordinators with secondary validation through FDA 483 inspection databases, EMA GMP certificates, hospital formulary listings, and ClinicalTrials.gov enrollment records. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segment estimates.
Segment-weighting approaches distributed value across antibiotics, antifungals, immunosuppressants, and surgical interventions by delivery mode and end-user channel. CAGRs derived from regression analysis against prosthetic valve implantation procedure volumes, resistance surveillance expansion rates, and oral step-down protocol adoption curves across the projection horizon. Modeled inputs included CDC bloodstream infection tracking coverage, PMDA Sakigake designation timelines, and OPAT infrastructure reimbursement policy evolution.
Several conditions sit outside the modeled scope, including novel antimicrobial class clinical trial outcomes, geopolitical disruption to API supply corridors, and pandemic-related hospital capacity constraints. Forecasts assume continued FDA antimicrobial stewardship mandate enforcement and stable Medicare OPAT reimbursement. A model refresh is warranted upon material change in FDA pre-approval facility audit timelines or EMA pharmacovigilance framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Stable Angina Management Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Atherosclerosis Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Coronary Artery Disease Therapeutics Market