
 Global Atrial Fibrillation Market | 2026-2036
Global Atrial Fibrillation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atrial Fibrillation Market Analysis
North American electrophysiology lab expansion is reshaping competitive dynamics for device manufacturers. Medtronic plc anchors its position through deep R&D investment in cryoablation platforms. Abbott Laboratories differentiates via integrated mapping and ablation system architectures. Bristol-Myers Squibb Company sustains pharmaceutical relevance through anticoagulant portfolio breadth.
Atrial fibrillation constitutes a supraventricular tachyarrhythmia characterized by disorganized atrial electrical activation, typically exceeding 350 beats per minute, with consequent loss of effective atrial contraction and hemodynamic compromise. Its primary clinical purpose centers on stroke prevention, rhythm control, and symptom management across acute and chronic care settings. Ablation devices and antiarrhythmic drugs command the dominant margin pools, while cardiac monitors represent the fastest-growing segment due to ambulatory diagnostic adoption. Radiofrequency technology maintains procedural volume leadership, though cryoablation is gaining share in pulmonary vein isolation protocols.
FDA premarket notification pathways and the EU MDR framework govern device safety and clinical evidence requirements, directly shaping product development timelines and market access conditions. The EPA and OSHA intersect through sterilization process validation and workplace exposure limits in catheter manufacturing facilities. Stakeholders must monitor reimbursement parity between catheter ablation and pharmacological therapy across national health systems.
Market Dynamics
Catheter-based pulmonary vein isolation is displacing chronic pharmaceutical management as the first-line rhythm control strategy for paroxysmal atrial fibrillation, forcing hospital systems to reallocate capital toward electrophysiology infrastructure and away from anticoagulant formularies.
Growth Catalysts
- Ambulatory cardiac monitoring:Patch-based extended Holter systems enable 14-day arrhythmia detection outside hospital settings. Germany's statutory health insurance funds now reimburse these devices for cryptogenic stroke workups.
- FDA Breakthrough Device designation:Accelerated premarket review pathways compress clearance timelines for novel ablation catheters. This regulatory channel is reducing time-to-market for pulsed field ablation platforms.
- Integrated mapping systems:Three-dimensional electroanatomical mapping is digitizing procedural workflows. Academic medical centers in the United States are standardizing these platforms across multi-site electrophysiology networks.
Market Restraints
- Iridium electrode supply concentration:Mining and refining of this platinum-group metal centers on South Africa and Russia. Price volatility in this input directly impacts radiofrequency catheter manufacturing costs.
- EU MDR clinical evidence requirements:The expanded scope of post-market surveillance and PMCF studies is extending recertification timelines for legacy ablation devices. Small device manufacturers face disproportionate compliance burdens.
- Anticoagulant pharmacotherapy:Direct oral anticoagulants maintain strong clinical guidelines support for stroke prevention. This therapeutic alternative limits ablation candidacy expansion in elderly comorbid populations.
Strategic Opportunities
- Japan's aging demographic:The world's oldest population presents underpenetrated procedural volume potential. PMDA's recent alignment with FDA predicate device pathways is easing market entry for cryoablation platforms.
- Artificial intelligence-enhanced mapping:Machine learning algorithms are converging with intracardiac echocardiography. This technology pairing enables real-time lesion assessment without contrast fluoroscopy.
- India's PLI scheme for medical devices:Production-linked incentives for high-value manufacturing are attracting catheter assembly operations. Domestic production can circumvent import duties reaching 20% on finished electrophysiology products.
Industry Challenges
- Electrophysiologist training pipelines:The specialized skill set for complex ablation procedures requires 2-3 year fellowships. Fellowship positions are not expanding at pace with procedural demand in the United States.
- Hospital capital allocation cycles:Electrophysiology lab buildouts require $3-5 million per biplane fluoroscopy suite. Health system CFOs are prioritizing these investments against competing service line demands.
- Interoperability with legacy EHR systems:New mapping platforms must integrate with entrenched electronic health record architectures. This technical friction delays technology adoption in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atrial Fibrillation Market |
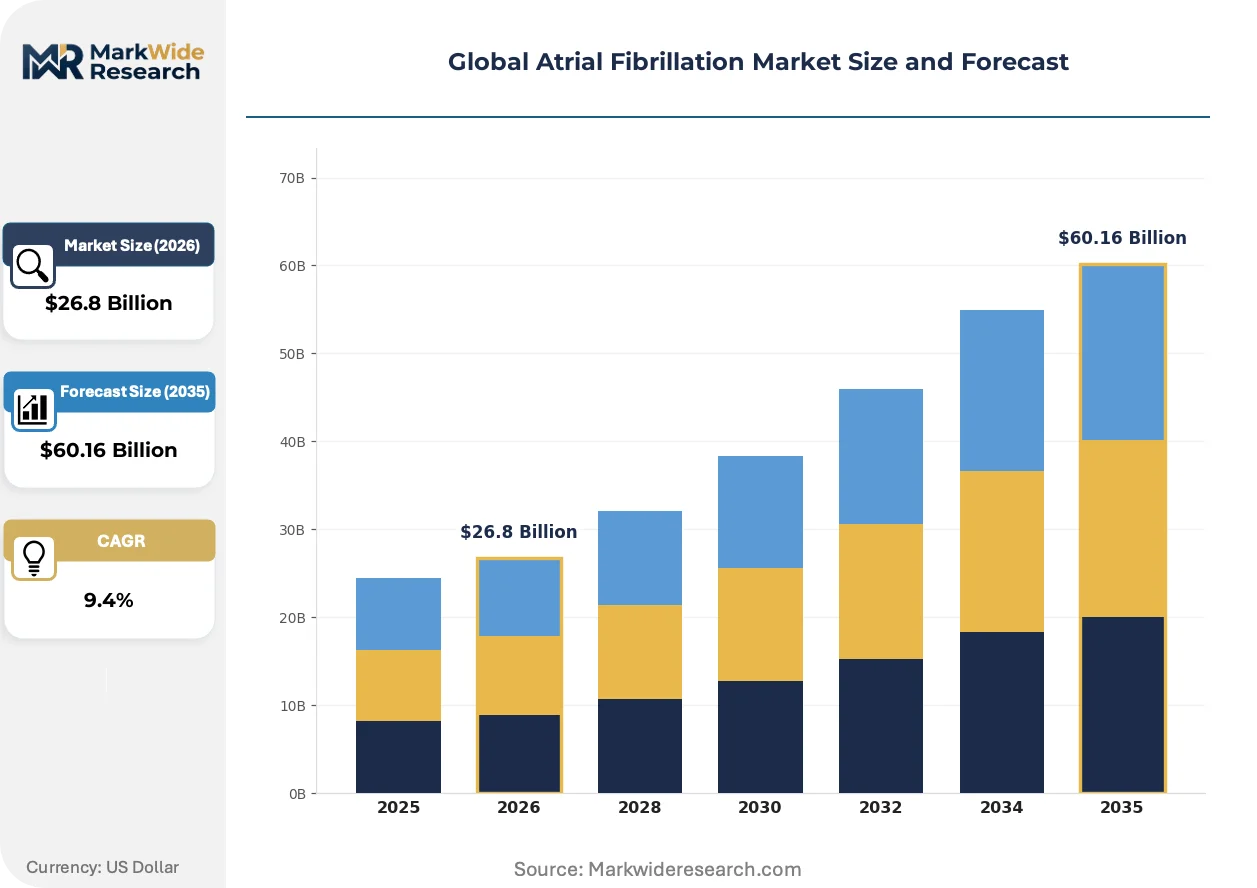
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $60.16 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Cardiac Monitors, Antiarrhythmic Drugs, Ablation Devices End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Research Organizations Delivery Mode: Oral, Injectable, Intravenous, Transdermal Technology: Radiofrequency, Cryoablation, Laser Ablation, Ultrasound |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Bristol-Myers Squibb Company, Medtronic plc, Abbott Laboratories, Daiichi Sankyo, Bayer AG, Boston Scientific Corporation, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atrial Fibrillation Market Emerging Trajectories
Digital catheter technologies are compressing procedural times while regulatory convergence across FDA and EU MDR frameworks is standardizing evidence requirements. These forces are reshaping how ablation platforms achieve commercial scale.
Pulsed field ablation is digitizing cardiac tissue characterization through irreversible electroporation. Academic electrophysiology departments in Germany and the Netherlands are adopting these platforms for first-in-human protocols. The technology is digitizing lesion creation by replacing thermal energy with non-thermal cellular disruption, enabling faster pulmonary vein isolation with reduced esophageal injury risk.
The EU MDR's reinforced clinical evaluation requirements are extending PMCF study obligations for Class III active implantable devices. Manufacturers must now generate prospective real-world evidence for legacy catheters previously cleared under the MDD. High-complexity ablation systems face the steepest compliance gradients, with notified body capacity constraints adding 12-18 months to recertification timelines.
Hospital purchasing committees are consolidating supplier relationships around single-vendor mapping and ablation ecosystems. This vendor concentration is displacing point-solution procurement in United States health systems. Integrated platform contracts now span capital equipment, disposable catheters, and remote technical support, with IDNs leveraging volume commitments for preferential pricing tiers.
Global Atrial Fibrillation Market Segmentation
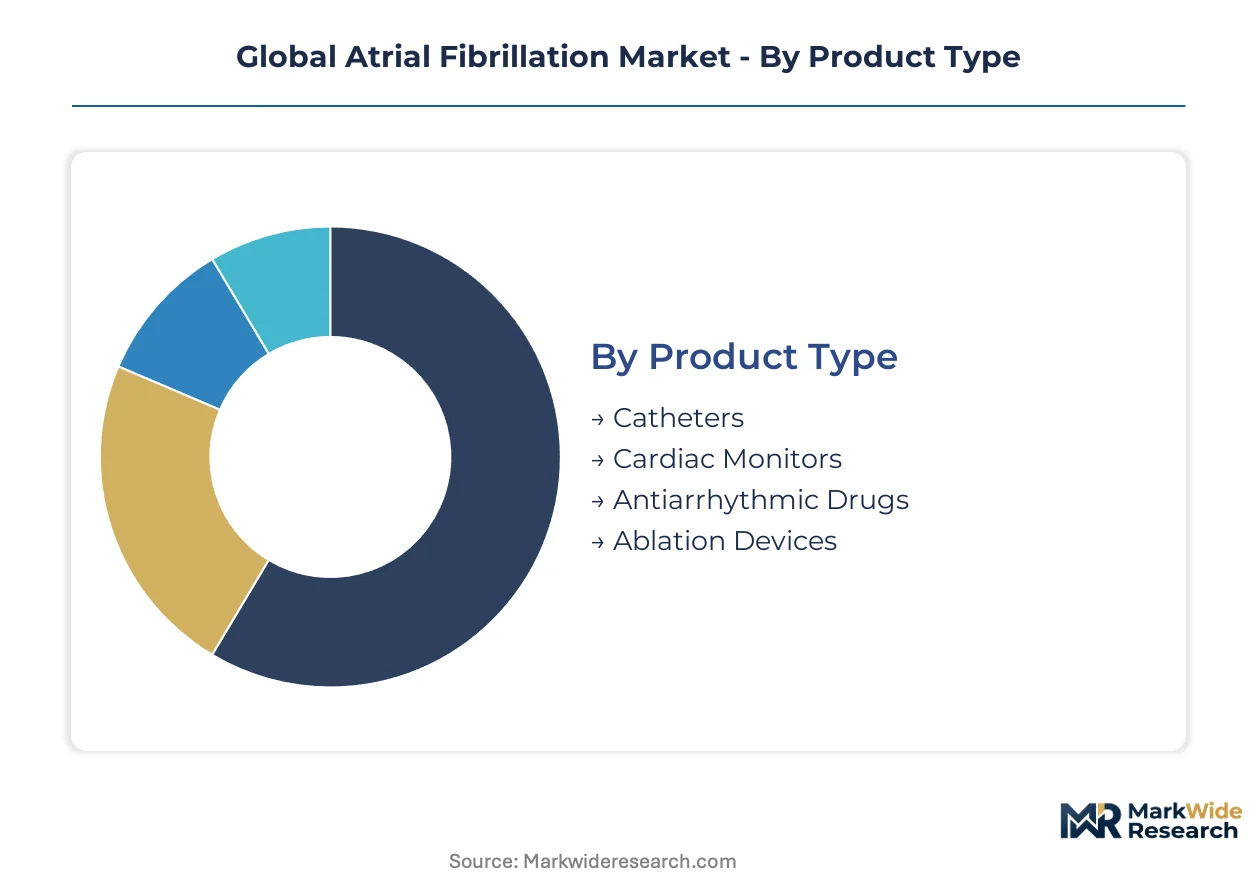
Segmentation in atrial fibrillation markets reveals divergent replacement cycles and margin structures. Catheter-based interventions refresh every 1-2 years while capital equipment spans 7-10 year depreciation schedules. Understanding these temporal patterns enables manufacturers to balance recurring revenue streams against long-cycle infrastructure sales.
Product Type:
Cycle times vary dramatically — disposable catheters turn over in months, cardiac monitors in 2-3 years, and ablation capital platforms across decade-long replacement windows.
- Catheters:Single-use electrophysiology catheters incorporate iridium electrodes and braided shafts for torque transmission. Demand clusters in German hospital systems expanding pulmonary vein isolation programs, pressured by statutory health insurance reimbursement shifts toward intervention over chronic drug management.
- Ablation Devices:Capital platforms integrating energy generators and irrigation pumps represent $500,000-800,000 investments per electrophysiology lab. United States academic medical centers are consolidating procurement around single-vendor ecosystems to secure remote technical support and training commitments.
- Cardiac Monitors:Patch-based extended Holter systems enable 14-day ambulatory arrhythmia detection outside hospital settings.
- Antiarrhythmic Drugs:Oral formulations including flecainide, amiodarone, and dronedarone maintain formulary presence for rate and rhythm control.
Catheters anchor the volume base while cardiac monitors gain share at the steepest rate.
End User:
Capital intensity and reimbursement sophistication stratify demand across facility types, with procedure volume migrating toward lower-acuity settings.
- Hospitals:Tertiary centers house biplane fluoroscopy suites and 3D electroanatomical mapping systems. German statutory health insurance funds now reimburse complex ablation procedures performed in certified cardiac rhythm management centers, concentrating high-acuity cases in university-affiliated institutions.
- Ambulatory Surgical Centers:Freestanding facilities perform paroxysmal atrial fibrillation ablations under streamlined anesthesia protocols. United States Medicare reimbursement parity for catheter ablation in ASC settings is accelerating site-of-service migration from inpatient hospital departments.
- Cardiology Clinics:Office-based practices manage anticoagulation therapy and arrhythmia monitoring referrals.
- Research Organizations:Academic consortia conduct first-in-human trials for pulsed field ablation platforms.
Hospitals retain the highest absolute spending while ambulatory surgical centers expand most quickly.
Delivery Mode:
Pharmacokinetic requirements and procedural contexts determine route selection, with oral dominance in chronic management and intravenous control in acute settings.
- Oral:Direct oral anticoagulants including apixaban and rivaroxaban enable outpatient stroke prevention without INR monitoring. German general practitioner networks prescribe these agents as first-line therapy for CHA2DS2-VASc scores of 2 or greater.
- Intravenous:Acute rate control in emergency departments relies on diltiazem or amiodarone infusion. United States hospital formularies stock intravenous formulations for hemodynamically unstable rapid atrial fibrillation requiring immediate ventricular rate reduction.
- Injectable:Subcutaneous heparin bridges anticoagulation interruption for procedural contexts.
- Transdermal:Patch-based drug delivery remains investigational for antiarrhythmic agents.
Oral formulations command the volume base while intravenous delivery climbs fastest in acute care expansion.
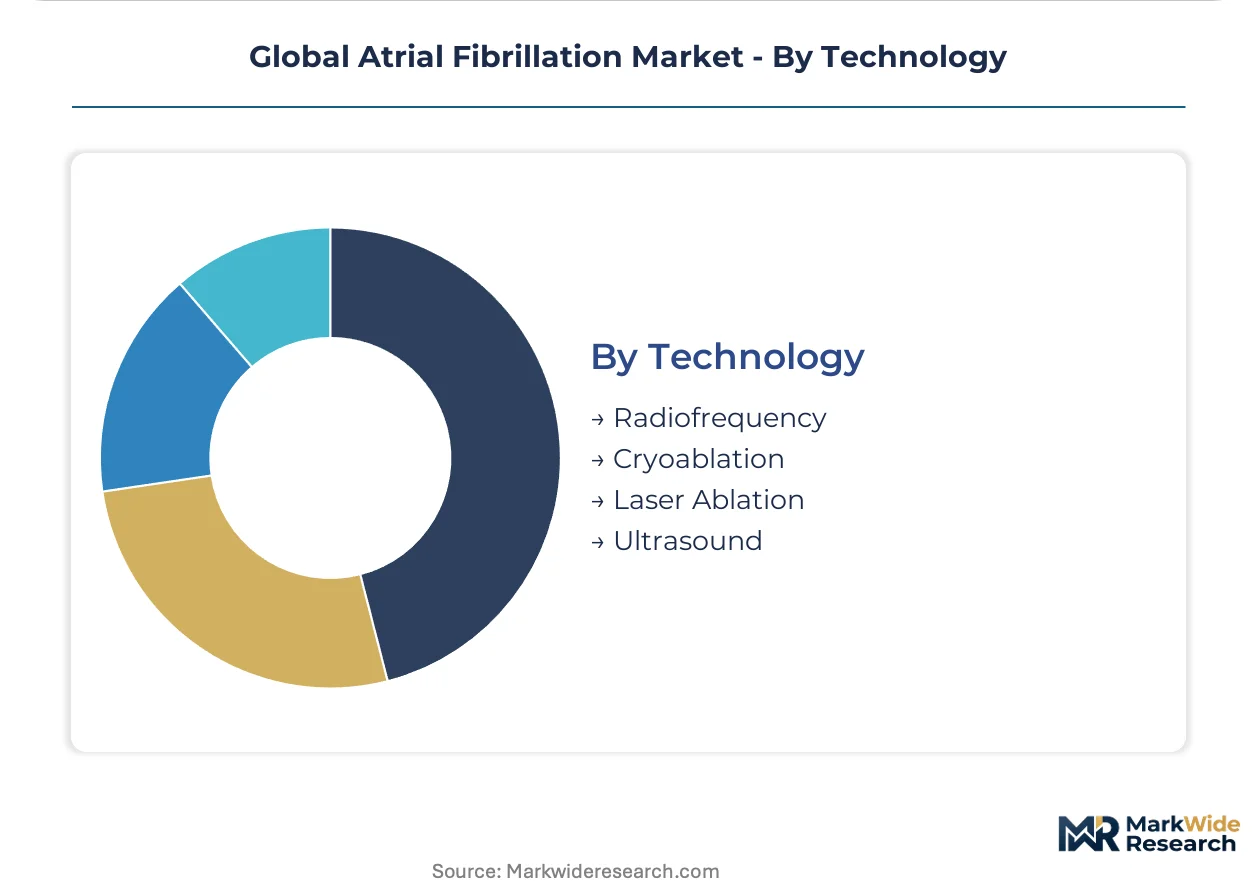
Technology:
Energy modality selection shapes lesion characteristics, procedure duration, and complication profiles across pulmonary vein isolation protocols.
- Radiofrequency:Thermal ablation via unipolar or bipolar current delivery creates transmural lesions with temperature-controlled feedback. Iridium electrode supply concentration in South Africa and Russia introduces input cost volatility for catheter manufacturers dependent on this platinum-group metal.
- Cryoablation:Nitrous oxide-mediated tissue freezing achieves pulmonary vein isolation with single-shot balloon catheters. PMDA alignment with FDA predicate device pathways is easing market entry for cryoablation platforms in Japan's underpenetrated procedural market.
- Laser Ablation:Optical energy delivery enables precise lesion geometry control.
- Ultrasound:High-intensity focused ultrasound ablation remains investigational for cardiac applications.
Radiofrequency anchors installed base volume while cryoablation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways anchor the dominant geography, while Germany's statutory health insurance funds and Japan's PMDA alignment with predicate device standards shape secondary demand centers. Hospital systems across these markets are reallocating capital toward electrophysiology infrastructure.
United States
Academic medical centers are standardizing three-dimensional electroanatomical mapping platforms across multi-site electrophysiology networks. Medicare reimbursement parity for catheter ablation in ambulatory surgical center settings accelerates site-of-service migration from inpatient departments. The Cleveland Clinic and Mayo Clinic anchor high-volume pulmonary vein isolation programs with integrated vendor ecosystems.
Germany
Statutory health insurance funds reimburse patch-based extended Holter systems for cryptogenic stroke workups, expanding ambulatory diagnostic penetration. The EU MDR framework governs post-market surveillance obligations for Class III active implantable devices. University hospitals in Munich and Heidelberg concentrate certified cardiac rhythm management centers performing complex ablation procedures.
Japan
The world's oldest population presents underpenetrated procedural volume potential for rhythm control interventions. PMDA's recent alignment with FDA predicate device pathways eases market entry for cryoablation platforms. Tokyo and Osaka metropolitan areas house the bulk of electrophysiology lab capacity, with regional hospitals lagging in catheter-based infrastructure.
India
Production-linked incentives for high-value medical device manufacturing attract catheter assembly operations under the PLI scheme. Domestic production circumvents import duties reaching 20% on finished electrophysiology products. Hyderabad and Bengaluru clusters emerge as contract manufacturing hubs for multinational device firms seeking cost arbitrage.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex ablation procedures in designated cardiac centers. The MHRA operates under retained EU law for medical device regulation pending future divergence. London and Manchester anchor the highest procedural volumes, with regional variation in access to three-dimensional mapping technology.
Global Atrial Fibrillation Market Vendor Landscape
Integrated platform specialists and pharmaceutical incumbents split the market into distinct competitive spheres. Device manufacturers consolidate procurement relationships around single-vendor ecosystems spanning capital equipment, disposable catheters, and remote technical support. Two strategic archetypes dominate: diversified medtech conglomerates with deep R&D investment in energy delivery platforms, and anticoagulant-focused pharmaceutical firms sustaining formulary presence through stroke prevention portfolios. Competitive moves center on vendor concentration contracts with integrated delivery networks and accelerated regulatory pathways for novel ablation technologies.
Within the diversified medtech tier, Medtronic plc and Abbott Laboratories exemplify integrated platform strategies, while Bristol-Myers Squibb Company anchors pharmaceutical relevance through anticoagulant portfolio breadth. Johnson & Johnson and Boston Scientific Corporation occupy positions spanning device and pharmaceutical adjacencies. These five entities represent the competitive core, with Daiichi Sankyo, Bayer AG, Pfizer Inc., and Sanofi constituting a secondary tier focused on pharmacological rhythm and stroke management.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Medtronic plc |
| Abbott Laboratories |
| Daiichi Sankyo |
| Bayer AG |
| Boston Scientific Corporation |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Undercapacity in South African iridium refining is compressing electrode supply availability and amplifying pricing power for catheter manufacturers with captive sourcing arrangements. This utilization squeeze propagates through radiofrequency ablation device costs while cryoablation platforms gain relative cost stability from nitrous oxide supply diversification.
Pricing Analysis
Geographic price spreads widen substantially between United States academic medical centers and Indian ambulatory surgical centers, reflecting reimbursement disparity and import duty structures. Three-tier pricing structure across premium integrated mapping ecosystems, standard generator-catheter bundles, and economy single-use disposables dominates procurement contracts. Cost compression in the economy tier is intensifying because domestic manufacturing under India's PLI scheme erodes landed cost advantages. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement caps, while German university hospitals prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for electrophysiology lab capital equipment, with supply-chain finance facilities emerging from medical device distributors to bridge working capital gaps. Manufacturing concentration rests on Germany for precision catheter assembly, the United States for mapping system integration, and India for cost-optimized component production. Iridium electrode supply, nitrous oxide refrigerant, and braided polymer shafts constitute critical input dependencies. Single-source vulnerability in South African platinum-group metal mining introduces procurement risk. Distribution runs through integrated delivery networks consolidating vendor relationships around single-source mapping and ablation ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in atrial fibrillation markets derive from regulatory entrenchment, where FDA predicate device pathways and EU MDR clinical evidence requirements create decade-long certification barriers that protect installed base positions.
For Market Incumbents: Harden ecosystem lock-in through exclusive remote technical support contracts tied to capital equipment refresh cycles. Deepen backward integration into iridium electrode supply through offtake agreements with South African refiners. Cryoablation platform commoditization from PMDA-aligned market entrants in Japan threatens margin compression in the pulmonary vein isolation segment.
For New Entrants and Emerging Players: Pursue white-space positioning in India's underpenetrated electrophysiology infrastructure, where PLI scheme benefits offset import duty burdens for domestic assembly operations. Target ambulatory surgical center site-of-service migration in the United States, where Medicare reimbursement parity creates procurement entry points outside established hospital vendor relationships. Lead with AI-enhanced mapping software companions requiring lower capital commitment than full platform ecosystems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among catheter disposable manufacturers with hospital system sole-source contracts, offering superior cash flow predictability versus capital equipment vendors. Five-to-ten year viability favors platforms with cryoablation and pulsed field ablation technology breadth rather than radiofrequency-dependent portfolios. Monitor PMDA approval velocity for cryoablation platforms as inflection indicator for Japanese market penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts with Cleveland Clinic and Mayo Clinic anchor high-volume referral networks. |
| FDA Breakthrough Device Pathway | Accelerated premarket review compresses time-to-market for pulsed field ablation catheter platforms. |
| CE Marking Pathway | EU MDR clinical evaluation requirements extend recertification timelines for legacy ablation systems. |
| Software Companion Development | AI-enhanced mapping algorithms enable real-time lesion assessment without contrast fluoroscopy. |
| Reimbursement Strategy | German statutory health insurance fund coverage decisions determine ambulatory monitor adoption velocity. |
Methodological Framework
The analysis maps catheter-based interventions, cardiac monitoring devices, ablation capital platforms, and anticoagulant pharmacotherapy segments, each validated through electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up unit economics triangulated against top-down market sizing across procedure volume and device pricing dimensions.
Assumptions held fixed include current FDA predicate device pathway structures and statutory health insurance reimbursement parity in Germany, while regulatory convergence timelines and PMDA alignment velocity were varied across scenarios. Segmentation dimensions modeled encompass product type, end-user facility tier, energy delivery technology, and geographic regulatory cluster. CAGRs derived from procedure volume growth rates applied to average selling price trajectories, with electrophysiologist fellowship pipeline constraints and hospital capital allocation cycles as industry-specific forecast inputs.
Sensitivities concentrate around iridium supply disruption, EU MDR notified body capacity constraints, and Medicare site-of-service reimbursement shifts. Forecasts reflect documented assumptions regarding procedural adoption curves and technology substitution patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Pericarditis Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Antihypertensive Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Tachycardia Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Angina Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Prinzmetal Angina Therapeutics Market