
 Medical Nitroglycerin Spray Market | 2026-2036
Medical Nitroglycerin Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Nitroglycerin Spray Market Foresight
Asset-light contract manufacturing and third-party aerosol filling partnerships are fragmenting competitive barriers in the Medical Nitroglycerin Spray space, enabling mid-size entrants to challenge incumbents without capital-intensive inhaler assembly lines. Pfizer Inc. leverages its respiratory device heritage to sustain formulation consistency across regulatory jurisdictions. G. Pohl-Boskamp GmbH & Co. KG anchors European supply through specialized nitroglycerin stabilization expertise. Glenmark Pharmaceuticals Ltd. competes on cost-engineered pump spray alternatives for price-sensitive hospital tenders.
Medical nitroglycerin spray comprises a metered-dose aerosol or pump delivery of nitroglycerin dissolved in ethanol-propylene glycol excipients, typically dosed at 0.4 mg per activation for rapid sublingual or buccal absorption to relieve acute angina pectoris through smooth muscle vasodilation. The fast-acting product type dominates acute care settings where symptom onset demands sub-sixty-second therapeutic onset, while extended-release formulations capture margin pools in ambulatory home care protocols. Emergency services applications are expanding fastest as pre-hospital chest pain protocols standardize spray-based first-line intervention before hospital transfer.
FDA Current Good Manufacturing Practice enforcement for metered-dose inhalers shapes batch release testing and shelf-life validation requirements, while EMA stability guidelines for nitroglycerin in pressurized containers dictate European packaging and storage standards. India's CDSCO mandates bioequivalence documentation for imported spray formulations, adding regulatory friction for multinational entrants. Stakeholders must monitor evolving pharmacopeial harmonization between USP aerosol performance standards and European Pharmacopoeia delivery uniformity tests to anticipate reformulation investments.
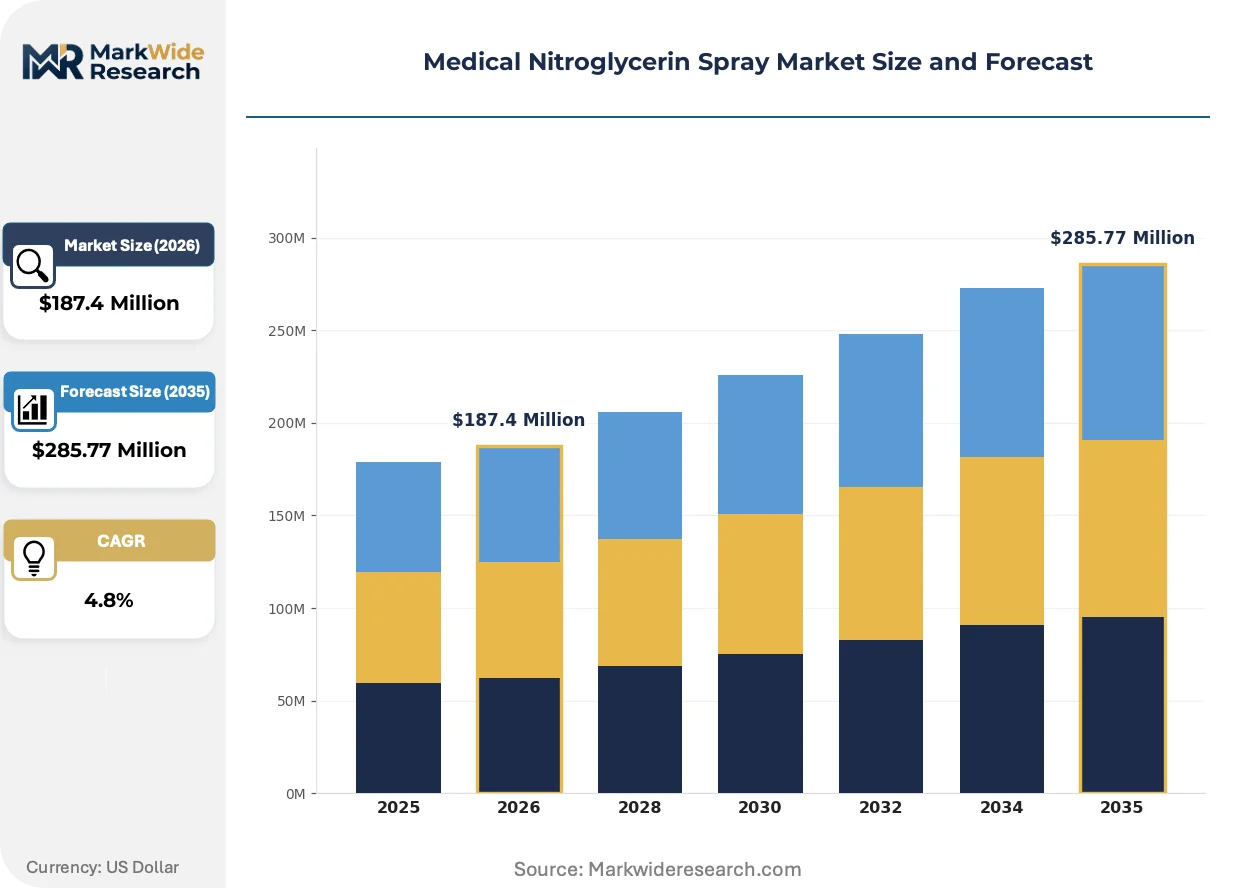
Market Dynamics
FDA Current Good Manufacturing Practice enforcement for metered-dose inhalers is compressing batch release timelines and forcing manufacturers to revalidate shelf-life protocols, restructuring competitive economics around compliance infrastructure rather than formulation alone.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:Cardiovascular emergency preparedness protocols are expanding pre-hospital spray deployment, driving institutional procurement of fast-acting formulations.
- EMA stability guidelines for pressurized nitroglycerin containers:Harmonized European packaging standards are reducing cross-border regulatory friction, accelerating product registration across EU member states.
- Emergency medical services standardization:Chest pain protocols in North American and European ambulance systems now mandate spray-based first-line intervention before hospital transfer.
Market Restraints
- Ethanol-propylene glycol excipient volatility:Input cost swings for pharmaceutical-grade solvents compress margin predictability for generic manufacturers.
- Specialized nitroglycerin stabilization expertise concentration:European contract manufacturers with proprietary stabilization know-how control critical supply nodes.
- CDSCO bioequivalence documentation requirements:India's regulator imposes additional clinical validation burdens on imported spray formulations, extending market entry timelines.
Strategic Opportunities
- Asset-light contract manufacturing expansion:Third-party aerosol filling partnerships enable mid-size entrants to challenge incumbents without capital-intensive inhaler assembly investments.
- Extended-release formulation development:Ambulatory home care protocols present margin capture potential beyond acute care settings.
- PLI scheme alignment in India:Domestic production incentives for pharmaceutical devices reduce import dependency for metered-dose systems.
Industry Challenges
- Aerosol performance testing talent scarcity:USP delivery uniformity validation requires specialized analytical chemists in short supply across contract manufacturing organizations.
- Pharmacopeial harmonization uncertainty:Divergent USP and European Pharmacopoeia aerosol standards force parallel reformulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Nitroglycerin Spray Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast-Acting, Extended-Release, Sublingual, Transdermal Application: Angina Pectoris, Heart Failure, Myocardial Infarction, Hypertension End User: Hospitals, Home Care, Clinics, Emergency Services Delivery Mode: Aerosol Spray, Pump Spray, Metered Dose Inhaler, Sublingual Tablet |
| Companies Covered | Glenmark Pharmaceuticals Ltd., Evus Health Solutions LLC., Pfizer Inc., Sun Pharmaceutical Industries Ltd., Akrimax Pharmaceuticals LLC., Perrigo Company plc, Novartis AG, Troikaa Pharmaceuticals Ltd., G. Pohl-Boskamp GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Nitroglycerin Spray Market Shifts & Advancements
Formulation stability, regulatory harmonization pressures, and pre-hospital care protocol evolution are converging to reshape how nitroglycerin spray products are manufactured, validated, and distributed across acute and ambulatory channels.
Pump spray alternatives are collapsing the traditional metered-dose aerosol monopoly in price-sensitive hospital tenders. Glenmark Pharmaceuticals and other cost-engineered competitors are capturing procurement volume in emerging markets where ethanol-propylene glycol pressurized systems face excipient cost volatility. The technology is collapsing premium pricing power for legacy aerosol incumbents.
REACH and RoHS substance restrictions in the European Union are forcing propellant reformulation across pressurized drug delivery devices. Manufacturers must substitute legacy hydrofluorocarbon propellants with lower-global-warming-potential alternatives, triggering stability revalidation cycles. German and French hospital pharmacies are prioritizing suppliers with certified green chemistry propellant transitions.
Pre-hospital emergency protocols are consolidating buyer decision-making into centralized emergency medical services procurement offices. Ambulance fleet operators in the United States and Japan are negotiating multi-year supply agreements directly with manufacturers, disintermediating traditional wholesale distribution. This concentration is most visible in North American municipal EMS systems with standardized chest pain response mandates.
Medical Nitroglycerin Spray Market Segmentation
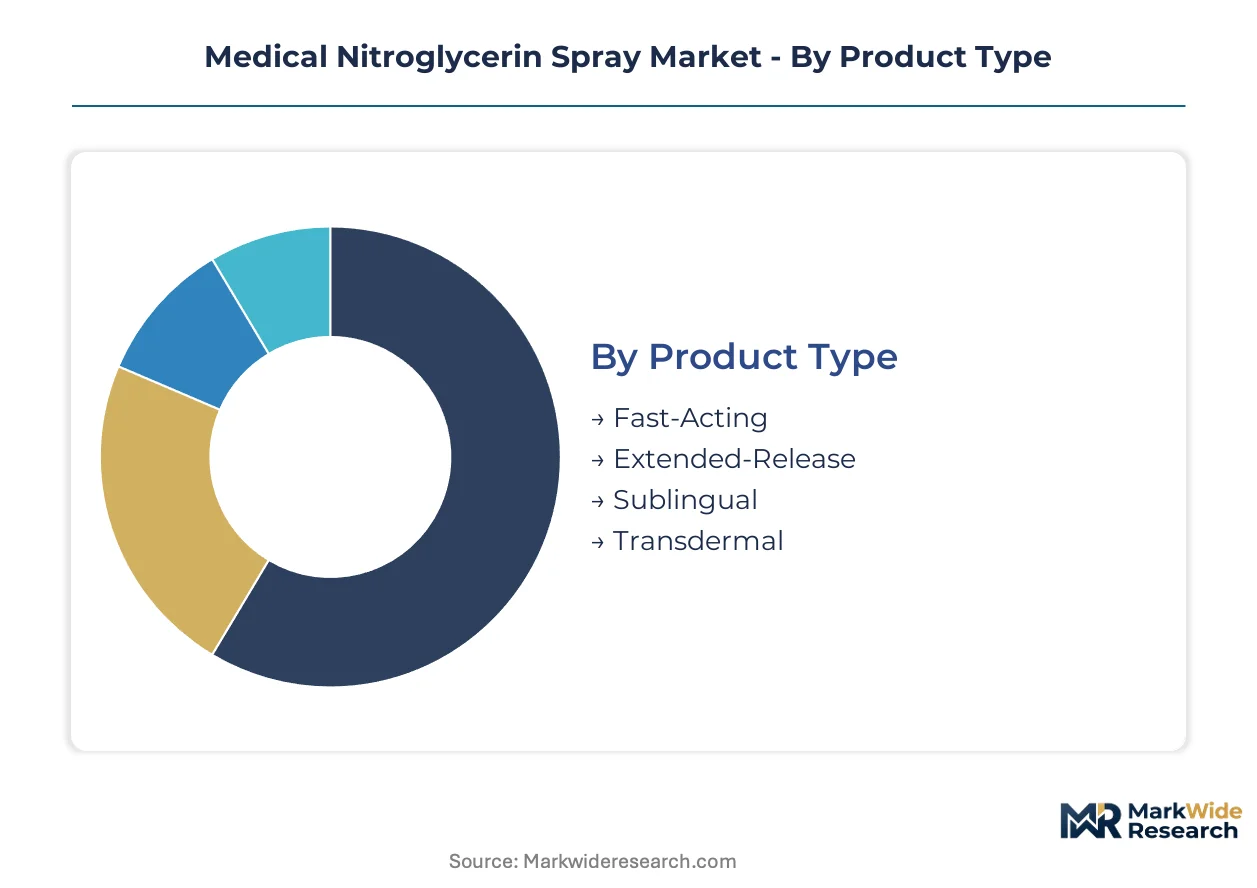
Segmentation in the Medical Nitroglycerin Spray Market reveals distinct procurement patterns across acute versus ambulatory care channels. Product formulators must align stability engineering, delivery mechanism precision, and regulatory documentation with the specific clinical setting and reimbursement pathway of each segment.
Product Type:
After-sales service intensity varies sharply across product types, with pressurized aerosol systems demanding specialized field calibration support while pump alternatives minimize ongoing technical dependency.
- Fast-Acting:Metered-dose aerosol delivering 0.4 mg nitroglycerin per activation through ethanol-propylene glycol excipients for sub-sixty-second therapeutic onset. Demand concentrates in United States emergency medical services and German hospital pharmacies where acute angina protocols mandate pre-hospital spray deployment. FDA stability-testing requirements for metered-dose aerosols compress batch release timelines and force shelf-life revalidation investments.
- Extended-Release:Formulation engineering prioritizes sustained vasodilation for ambulatory home care protocols, capturing margin pools beyond acute settings through reduced dosing frequency. Japanese aging demographics drive cardiovascular emergency preparedness expansion into residential care settings, with METI guidelines shaping packaging standards for patient self-administration.
- Sublingual:Traditional tablet dissolution under the tongue bypasses first-pass hepatic metabolism for rapid absorption. CDSCO bioequivalence documentation requirements in India extend market entry timelines for imported formulations.
- Transdermal:Patch-based delivery systems provide continuous nitroglycerin absorption over extended wear periods. EMA stability guidelines for pressurized containers do not apply, reducing European regulatory friction for this non-aerosol format.
Fast-Acting holds the largest share; momentum sits with Extended-Release as home care protocols expand.
Application:
Cost tier differentiation separates premium acute-intervention formulations from economy maintenance therapies, with reimbursement codes directly mapping to clinical severity stratification.
- Angina Pectoris:Chest pain relief through coronary vasodilation represents the foundational indication for nitroglycerin spray therapy. United States hospital pharmacies anchor procurement volume as chest pain protocols standardize spray-based first-line intervention.
- Heart Failure:Afterload reduction through venous dilation supports acute decompensated heart failure management in intensive care settings. German and French hospital systems prioritize suppliers with certified green chemistry propellant transitions under REACH substance restrictions.
- Myocardial Infarction:Rapid coronary vasodilation during acute coronary syndrome demands formulation consistency across regulatory jurisdictions. Emergency services applications are expanding fastest as pre-hospital protocols standardize intervention before hospital transfer.
- Hypertension:Acute blood pressure reduction in hypertensive emergencies utilizes nitroglycerin's smooth muscle relaxation properties. Japan's PMDA oversees stability validation for metered-dose systems in this acute application.
Angina Pectoris dominates procurement volume; Myocardial Infarction is gaining share fastest through EMS protocol standardization.
End User:
Customer type determines packaging scale, with institutional buyers negotiating multi-year supply agreements while individual patients drive retail pharmacy replenishment cycles.
- Hospitals:Centralized pharmacy procurement of fast-acting formulations for emergency department and inpatient acute angina management. FDA Current Good Manufacturing Practice enforcement shapes batch release testing and competitive economics around compliance infrastructure.
- Home Care:Patient-directed administration in residential settings demands intuitive device operation and extended shelf-life stability. Extended-release formulations capture margin pools in ambulatory protocols as aging populations in Japan and the United States drive cardiovascular emergency preparedness.
- Clinics:Outpatient cardiac care facilities balance acute intervention capability with inventory turnover efficiency. EMA stability guidelines for pressurized nitroglycerin containers reduce cross-border regulatory friction across EU member states.
- Emergency Services:Ambulance fleet operators in North American municipal systems negotiate direct manufacturer agreements, disintermediating traditional wholesale distribution. Pre-hospital chest pain protocols now mandate spray-based first-line intervention before hospital transfer.
Hospitals hold the largest share; Emergency Services is climbing the fastest as fleet procurement centralizes.
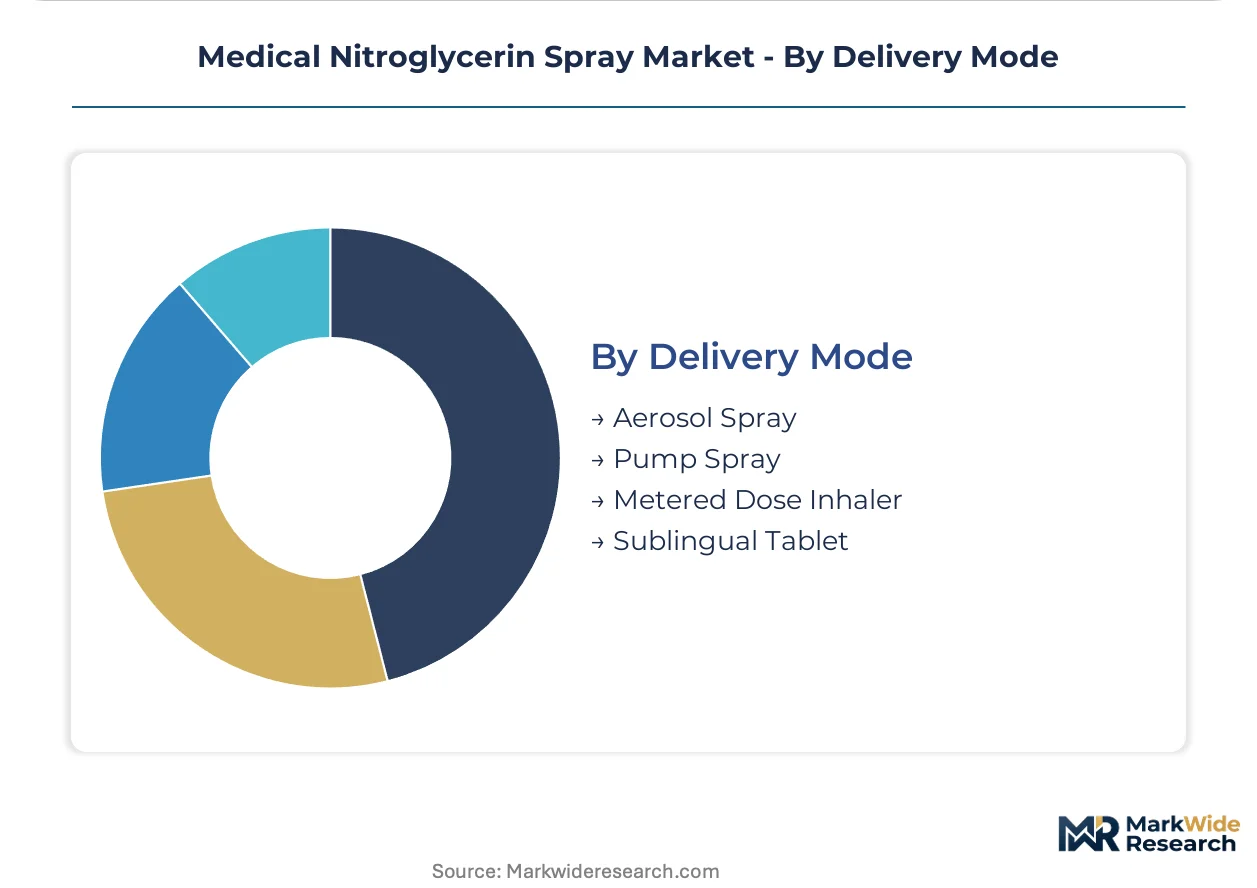
Delivery Mode:
Supply concentration in specialized European contract manufacturers with proprietary nitroglycerin stabilization expertise shapes competitive access for each delivery technology.
- Aerosol Spray:Pressurized metered-dose systems using hydrofluorocarbon propellants face REACH and RoHS substance restrictions forcing reformulation. German hospital pharmacies prioritize suppliers with certified green chemistry propellant transitions.
- Pump Spray:Cost-engineered alternatives collapse traditional aerosol monopoly in price-sensitive hospital tenders. Glenmark Pharmaceuticals captures procurement volume in emerging markets where ethanol-propylene glycol pressurized systems face excipient cost volatility.
- Metered Dose Inhaler:Respiratory device heritage enables formulation consistency across regulatory jurisdictions. USP aerosol performance standards and European Pharmacopoeia delivery uniformity tests create parallel reformulation investment pressures.
- Sublingual Tablet:Non-pressurized solid dosage forms bypass propellant stability concerns entirely. India's PLI scheme for pharmaceutical devices reduces import dependency for domestic tablet manufacturing.
Aerosol Spray retains the largest share; Pump Spray is expanding most quickly through cost-engineered hospital tender capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in medical nitroglycerin spray concentrate in developed pharmaceutical manufacturing hubs, with the United States and Germany running structural trade surpluses in finished aerosol formulations while India and emerging markets remain net importers of active pharmaceutical ingredients and device components.
United States
Emergency medical services fleets in Texas and California drive institutional procurement volume as municipal chest pain protocols mandate pre-hospital spray deployment. FDA Current Good Manufacturing Practice enforcement for metered-dose inhalers compresses batch release timelines and forces shelf-life revalidation investments. The Greater Boston corridor anchors respiratory device heritage capabilities that sustain formulation consistency across regulatory jurisdictions.
Germany
German hospital pharmacies in Bavaria and North Rhine-Westphalia prioritize suppliers with certified green chemistry propellant transitions under REACH substance restrictions. EMA stability guidelines for pressurized nitroglycerin containers reduce cross-border regulatory friction across EU member states. The Hamburg region hosts specialized contract manufacturers with proprietary nitroglycerin stabilization expertise controlling critical supply nodes.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas expand cardiovascular emergency preparedness into residential care settings. METI guidelines shape packaging standards for patient self-administration of extended-release formulations. The Kansai region concentrates pharmaceutical device engineering talent for metered-dose system validation under PMDA oversight.
India
Domestic hospital tenders in Maharashtra and Gujarat favor cost-engineered pump spray alternatives as ethanol-propylene glycol pressurized systems face excipient cost volatility. CDSCO bioequivalence documentation requirements extend market entry timelines for imported spray formulations. The PLI scheme for pharmaceutical devices reduces import dependency for metered-dose systems manufactured in the Delhi-NCR corridor.
United Kingdom
NHS procurement consolidation across London and the Southeast favors multi-year supply agreements with manufacturers demonstrating REACH-compliant propellant formulations. EMA stability guidelines apply during the post-Brexit recognition period, maintaining regulatory alignment for pressurized container standards. The Midlands region hosts third-party aerosol filling partnerships enabling mid-size entrants without capital-intensive inhaler assembly investments.
Medical Nitroglycerin Spray Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in excipient supply and stabilization chemistry. The vendor base clusters around three tiers: multinational pharmaceutical conglomerates with respiratory device heritage, specialized European stabilization houses, and cost-engineered generic challengers from emerging markets. Consolidation pressures favor asset-light contract manufacturing partnerships over captive production investments. Competitive moves center on green chemistry propellant transitions and third-party aerosol filling alliances that bypass capital-intensive assembly lines.
Among the archetype mix, Pfizer Inc. and Novartis AG exemplify multinational platform integrators leveraging respiratory device heritage across regulatory jurisdictions. G. Pohl-Boskamp GmbH & Co. KG occupies a position within the specialized European stabilization tier, anchoring supply security through proprietary nitroglycerin chemistry expertise. Glenmark Pharmaceuticals Ltd. represents the cost-engineered challenger archetype, capturing procurement volume in price-sensitive hospital tenders through pump spray alternatives.
| Leading Market Players |
|---|
| Glenmark Pharmaceuticals Ltd. |
| Evus Health Solutions LLC. |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Akrimax Pharmaceuticals LLC. |
| Perrigo Company plc |
| Novartis AG |
| Troikaa Pharmaceuticals Ltd. |
| G. Pohl-Boskamp GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
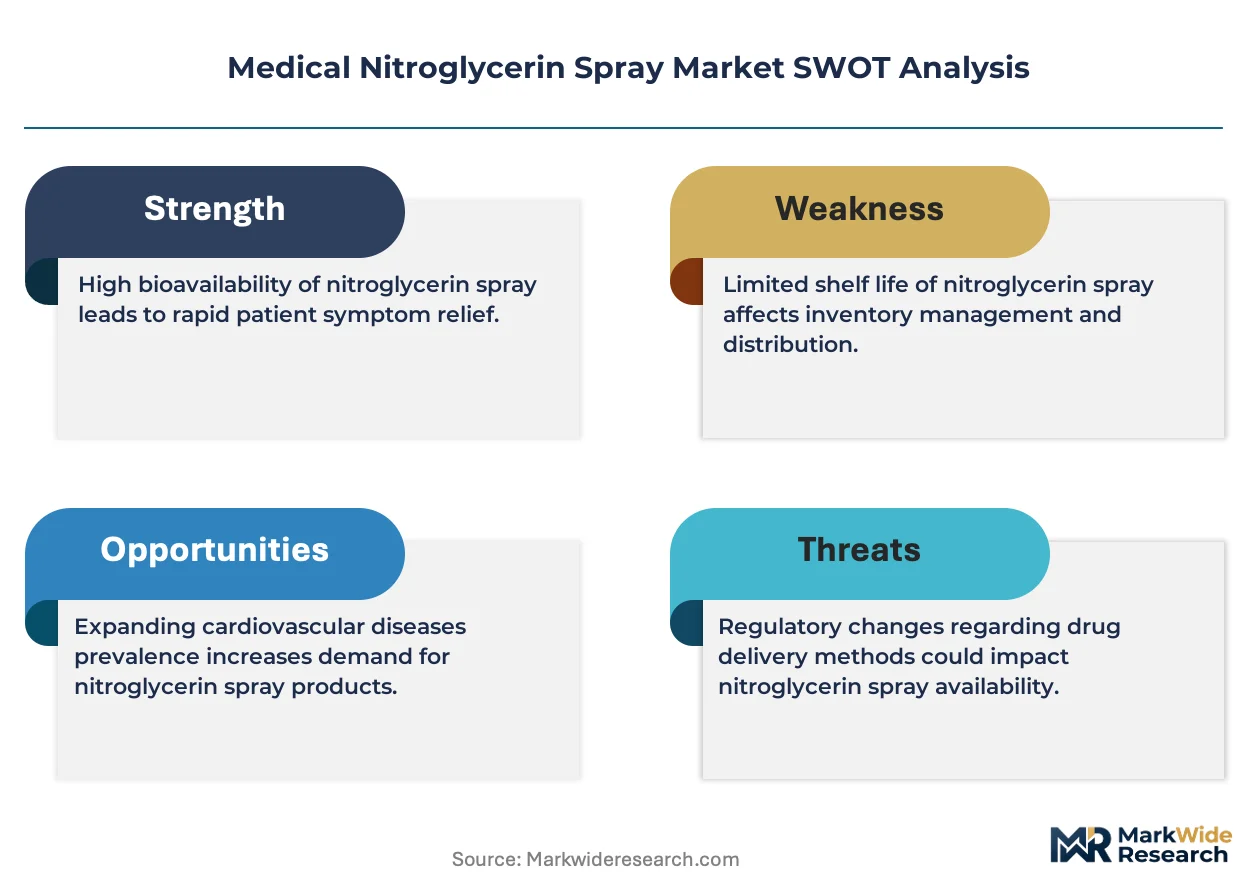
Overcapacity in Indian pump spray manufacturing is compressing margins across the ethanol-propylene glycol excipient tier and forcing European aerosol specialists to defend premium positioning through green chemistry certification investments. This utilization asymmetry between cost-engineered and legacy pressurized systems is reshaping procurement negotiations in German hospital pharmacies and Japanese emergency medical services fleets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across emergency medical services procurement offices, with three-tier pricing separating FDA-validated metered-dose systems from CE-marked European alternatives and economy pump sprays. Price differentiation rests on certification grade and after-sales calibration service bundling. Cost compression in the generic pump tier is intensifying because ethanol-propylene glycol excipient volatility erodes margin predictability. Municipal EMS fleets in the United States exhibit lowest price sensitivity due to protocol-mandated standardization, while Indian hospital tenders demonstrate highest sensitivity to per-unit acquisition costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning as active pharmaceutical ingredient sourcing concentrates in Indian and Chinese chemical manufacturing clusters. Nitroglycerin stabilization chemistry, pharmaceutical-grade ethanol, and hydrofluorocarbon propellants constitute critical input dependencies. Single-source vulnerability in specialized European contract manufacturers with proprietary stabilization expertise creates concentration risk at the formulation stage. Distribution runs through emergency medical services procurement offices and hospital pharmacy central committees, with direct manufacturer agreements displacing traditional wholesale channels in North American municipal systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as pre-hospital protocol standardization creates specialized niches for device-agnostic formulation suppliers and green chemistry propellant specialists.
For Market Incumbents: Insulate formulation consistency advantages by deepening backward integration into nitroglycerin stabilization chemistry and securing multi-year direct supply agreements with municipal EMS fleets before pump spray alternatives capture additional procurement volume. Threats from cost-engineered generic challengers in Indian manufacturing clusters demand defensive certification investments in REACH-compliant propellant transitions. For New Entrants and Emerging Players: Japanese residential care settings for extended-release ambulatory formulations represent the most penetrable white-space target, with METI-guided packaging standards creating regulatory clarity for patient self-administration devices. A go-to-market angle through third-party aerosol filling partnerships bypasses capital-intensive inhaler assembly investments and accelerates market entry without captive manufacturing infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized European stabilization houses with proprietary nitroglycerin chemistry expertise and long-term hospital pharmacy supply contracts. Long-term viability over a multi-year horizon favors acquisition targets with demonstrated green chemistry propellant transition capabilities and direct EMS procurement relationships. The signal to watch is consolidation momentum in North American municipal emergency services procurement centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Propellant Transition | REACH and RoHS compliance secures access to German and French hospital pharmacy procurement channels. |
| Third-Party Aerosol Filling Partnership | Asset-light manufacturing model enables mid-size entrants to challenge incumbents without inhaler assembly investments. |
| Direct EMS Procurement Agreement | Multi-year municipal contracts disintermediate wholesale distribution and lock in volume with standardized protocol adherence. |
| Extended-Release Formulation Development | Ambulatory home care protocols in Japan capture margin pools beyond acute emergency department settings. |
| CDSCO Bioequivalence Documentation Investment | Clinical validation capabilities reduce market entry timelines for imported spray formulations in Indian hospital tenders. |
Research Methodology
Cross-validation between regulatory filing analysis and procurement database screening anchors the qualitative findings in this study. Primary interviews with hospital pharmacy directors, emergency medical services procurement officers, regulatory affairs specialists at metered-dose device manufacturers, and contract manufacturing organization technical directors were combined with secondary validation from FDA 483 inspection observations, EMA marketing authorization databases, CDSCO import approval records, and hospital GPO contract repositories. Bottom-up demand modeling and top-down market sizing triangulate volume estimates across the analysis window.
Calibration against historical regulatory approval timelines and procurement cycle data refines the analytical framework. Segmentation dimensions include product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs were derived from slope analysis of projected demand curves adjusted for protocol standardization momentum. Industry-specific forecast inputs incorporate EMA stability guideline revision schedules and METI packaging standard implementation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian pump spray manufacturers or accelerated green chemistry propellant transitions by European specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market