
 Ischemia Reperfusion Injury Treatment Market | 2026-2036
Ischemia Reperfusion Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemia Reperfusion Injury Treatment Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is hardening procurement standards across European hospital networks. Pfizer Inc. leverages its global manufacturing footprint to sustain supply security for ischemia reperfusion compounds across multiple continents. Novartis AG anchors its position through deep specialization in cell therapy platforms for organ transplantation protocols. Bristol Myers Squibb competes aggressively on immunomodulatory approaches that differentiate its pipeline from conventional cytoprotective agents.
Ischemia reperfusion injury treatment encompasses therapeutic interventions designed to prevent cellular damage occurring when blood flow returns to previously oxygen-deprived tissue, typically involving pharmacological compounds, biologics, or mechanical devices administered at therapeutic temperatures and controlled infusion rates to preserve mitochondrial membrane integrity and reduce reactive oxygen species burst. Its primary purpose is to improve survival rates and functional recovery in patients undergoing cardiac surgery, organ transplantation, or stroke revascularization where temporary blood flow interruption is clinically necessary. Pharmaceuticals dominates current revenue contribution due to established reimbursement pathways for small-molecule cytoprotectants, while cell therapy represents the fastest-expanding technology segment as autologous and allogeneic approaches advance through late-stage clinical validation. Hospitals capture the largest end-user share given their control over surgical and interventional settings where ischemia reperfusion protocols deploy, though research institutions are building disproportionate influence over early technology access and investigator-initiated trials.
The FDA maintains stringent chemistry, manufacturing, and controls requirements for advanced therapy medicinal products, while the EMA's ATMP framework imposes comparable standards across European member states, collectively elevating barrier costs for novel entrants. ISO 14155 governs clinical investigation design for device-therapy combinations, shaping how sponsors structure pivotal trials for regulatory acceptance. Japan's PMDA operates a conditional early approval system that accelerates market access for regenerative medicines addressing unmet ischemic conditions. Stakeholders must monitor evolving evidentiary standards across these jurisdictions to align development investments with viable approval pathways.
Market Dynamics
The FDA's accelerated approval pathways for regenerative medicines are compressing clinical trial timelines and redirecting R&D investment toward cell-based platforms, fundamentally restructuring how sponsors prioritize pipeline assets and commercialization sequencing.
Growth Catalysts
- Japan's PMDA conditional early approval system:This framework accelerates market access for regenerative medicines addressing unmet ischemic conditions, drawing foreign sponsors to prioritize Japanese trial sites.
- Cardiac surgery volumes:Aging populations in the United States, Germany, and Japan sustain procedure demand where ischemia reperfusion protocols deploy as standard of care.
- EU Green Deal pharmaceutical sustainability criteria:Hardening procurement standards across European hospital networks favor suppliers with verified carbon-footprint reductions and circular manufacturing processes.
Market Restraints
- EMA ATMP chemistry, manufacturing, and controls requirements:These standards elevate barrier costs for novel entrants, particularly small-cap developers lacking established quality infrastructure.
- Plasma-derived biologics supply concentration:Dependency on limited geographic sources for critical raw materials creates vulnerability to collection disruptions and viral safety events.
- Cryopreservation technical limitations:Current dimethyl sulfoxide-based protocols impose cell viability losses that constrain allogeneic product shelf-life and logistics flexibility.
Strategic Opportunities
- India's CDSCO emerging ATMP framework:Early regulatory clarity positions the country as a cost-efficient manufacturing and trial destination for cell therapy developers.
- Mechanical perfusion device convergence with pharmacologic cocktails:Integration of hypothermic machine perfusion with targeted cytoprotectant delivery creates differentiated product-service bundles.
- Direct-to-hospital specialty pharmacy channels:Bypassing traditional wholesale distribution for temperature-sensitive biologics reduces cold-chain handoffs and margin leakage.
Industry Challenges
- Cell therapy manufacturing talent scarcity:Shortages of process development scientists and GMP operators with autologous workflow experience constrain scale-up velocity.
- ISO 14155 clinical investigation complexity:Device-therapy combination trials require dual competency teams, extending study startup timelines and investigator site qualification.
- Patent thickets around mitochondrial-targeted antioxidants:Dense overlapping IP estates complicate freedom-to-operate assessments for novel small-molecule entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemia Reperfusion Injury Treatment Market |
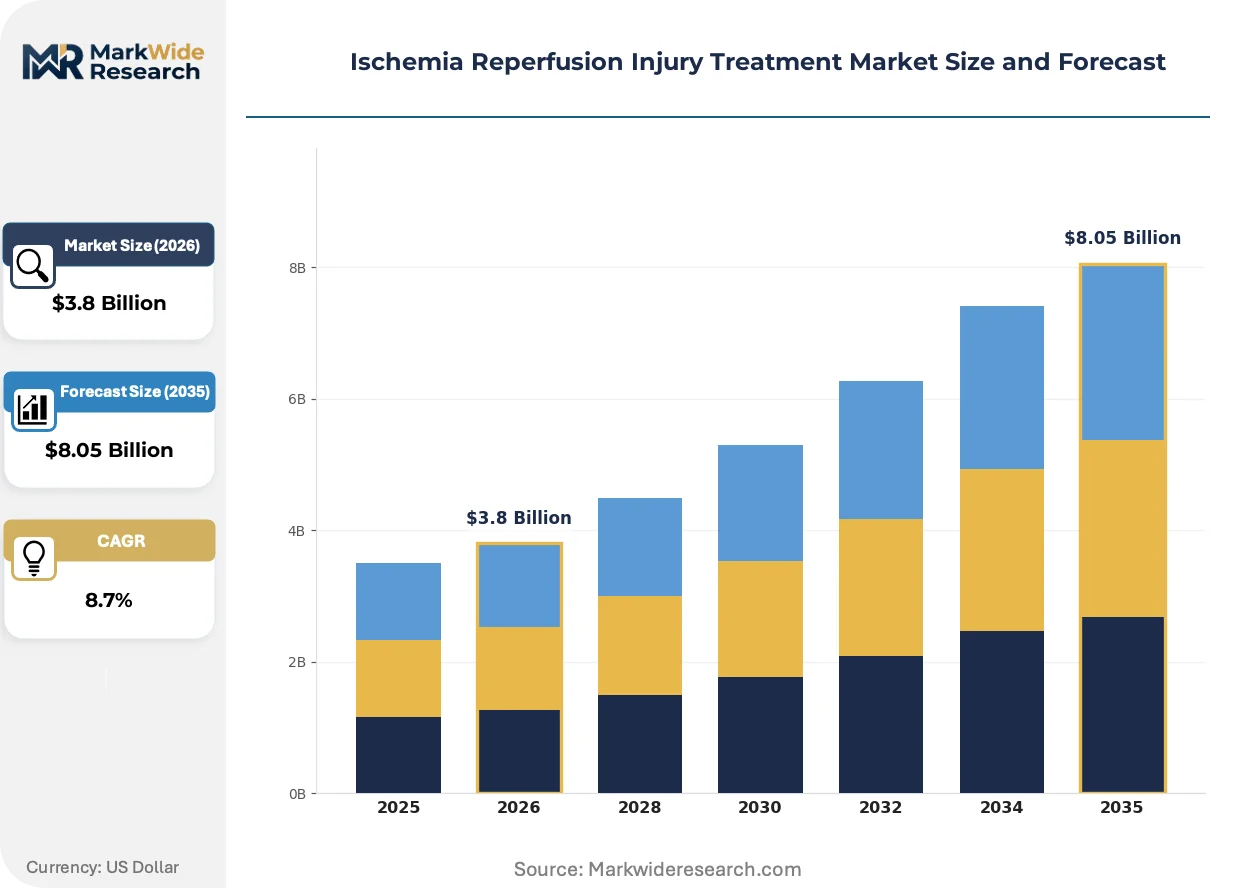
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Devices, Therapies, Procedures Technology: Cell Therapy, Gene Therapy, Surgical Techniques, Pharmacological Interventions End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Application: Cardiac Surgery, Organ Transplantation, Stroke Management, Pain Management |
| Companies Covered | Pfizer Inc., Novartis AG, AstraZeneca PLC, Bristol Myers Squibb, F. Hoffmann-La Roche Ltd, Sanofi, Merck KGaA, Takeda Pharmaceutical Company, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemia Reperfusion Injury Treatment Market Shifts & Advancements
Cell therapy manufacturing automation is overtaking manual open-system processing, while regulatory convergence around real-world evidence and sustainability disclosure is rewriting competitive qualification criteria across procurement channels.
Allogeneic off-the-shelf cell products are overtaking autologous patient-specific manufacturing in late-stage development pipelines. Academic medical centers in Germany and Japan are adopting closed-system bioreactors to reduce contamination risk and batch failure rates. This shift is compressing cost-per-dose estimates and enabling centralized manufacturing models that serve multiple transplant networks from single facilities.
REACH authorization requirements for novel chemical entities are tightening toxicological data expectations for small-molecule cytoprotectants entering European markets. Sponsors now face extended preclinical timelines and higher registration dossier costs. The pharmaceutical segment is responding by prioritizing biologic modalities with established human safety profiles over de novo chemical synthesis programs.
Hospital procurement departments are consolidating vendor panels and demanding outcome guarantees for high-cost perfusion devices and adjunct therapies. Traditional fee-for-service purchasing is giving way to risk-sharing arrangements tied to graft survival metrics or length-of-stay reductions. This behavioral shift is most pronounced in United States academic medical centers and integrated delivery networks with sophisticated analytics infrastructure.
Ischemia Reperfusion Injury Treatment Market Segmentation
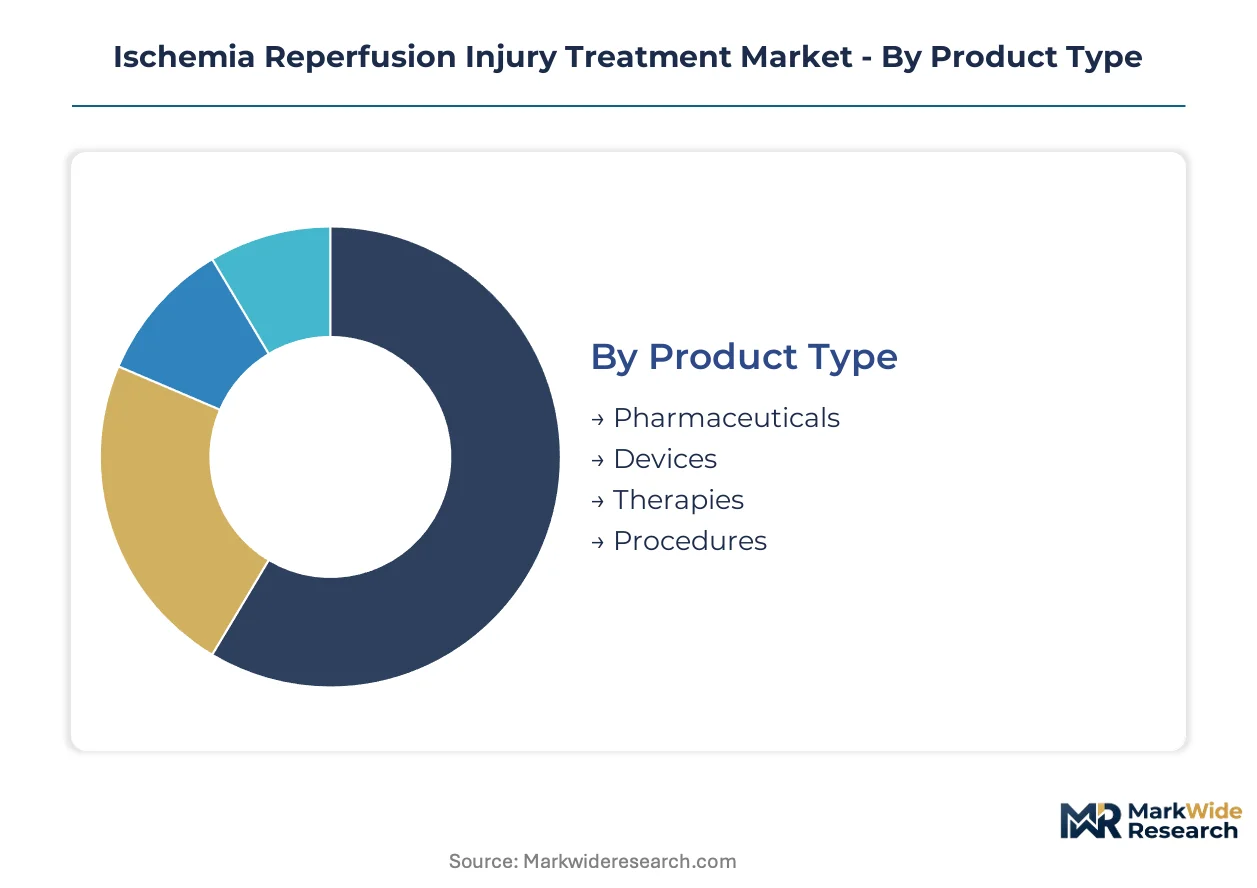
Therapeutic modality selection in ischemia reperfusion injury treatment follows distinct procurement logics across acute care settings. Technology maturity, reimbursement pathways, and procedural integration requirements create divergent commercial trajectories for each segment cluster.
Product Type:
Pharmaceuticals command volume leadership through established formularies, while devices capture premium pricing through technology differentiation and outcome guarantees.
- Pharmaceuticals:Small-molecule cytoprotectants and biologics administered intravenously or by infusion to stabilize mitochondrial membranes and scavenge reactive oxygen species during reperfusion. Demand concentrates in United States academic medical centers where CMS reimbursement pathways for cardiac surgery adjuncts remain well-defined. Established chemistry, manufacturing, and controls infrastructure sustains supply security across multiple continents.
- Devices:Mechanical perfusion systems, temperature management units, and controlled reperfusion catheters delivering precise flow rates and thermal profiles to ischemic tissue. German and Japanese hospitals lead procurement for hypothermic machine perfusion platforms integrated with organ transplantation protocols. Capital equipment procurement cycles and outcome-based contracting reshape vendor selection criteria.
- Therapies:Integrated treatment protocols combining pharmacologic and mechanical interventions administered as standardized care bundles in surgical settings.
- Procedures:Interventional techniques including controlled reperfusion and ischemic conditioning performed by specialized surgical teams.
Mature deployment sits with Pharmaceuticals. Newer deployment is concentrated in Devices.
Technology:
Autologous manufacturing models dominate current revenue, though allogeneic platforms are gaining share fastest through centralized production economics.
- Cell Therapy:Autologous and allogeneic cellular products including stem cells and engineered immune cells administered to modulate inflammatory cascades and promote tissue repair. Japan's PMDA conditional early approval system accelerates clinical validation for regenerative medicines targeting unmet ischemic conditions. Closed-system bioreactor adoption in German academic medical centers reduces contamination risk and batch failure rates.
- Gene Therapy:Viral and non-viral vector delivery systems modifying cellular responses to ischemic stress through transient or permanent genetic intervention.
- Surgical Techniques:Ischemic preconditioning, postconditioning, and controlled reperfusion protocols performed by cardiothoracic and transplant surgical teams.
- Pharmacological Interventions:Targeted small molecules and biologics modulating specific molecular pathways in reperfusion injury cascades.
Established clinical validation sits with Pharmacological Interventions. Steepest expansion trajectory is concentrated in Cell Therapy.
End User:
Procedure volume and technology access stratify sharply between integrated hospital systems and distributed outpatient settings.
- Hospitals:Academic medical centers and community hospitals controlling surgical suites, interventional catheterization laboratories, and transplantation programs where ischemia reperfusion protocols deploy as standard of care. United States integrated delivery networks with sophisticated analytics infrastructure pioneer risk-sharing arrangements tied to graft survival metrics.
- Clinics:Outpatient facilities administering post-acute monitoring and rehabilitation for patients recovering from ischemic events.
- Research Institutions:University hospitals and dedicated research centers conducting investigator-initiated trials and early technology validation studies.
- Rehabilitation Centers:Long-term care facilities managing functional recovery for stroke and cardiac surgery patients.
Revenue concentration sits with Hospitals. Disproportionate influence over early technology access sits with Research Institutions.
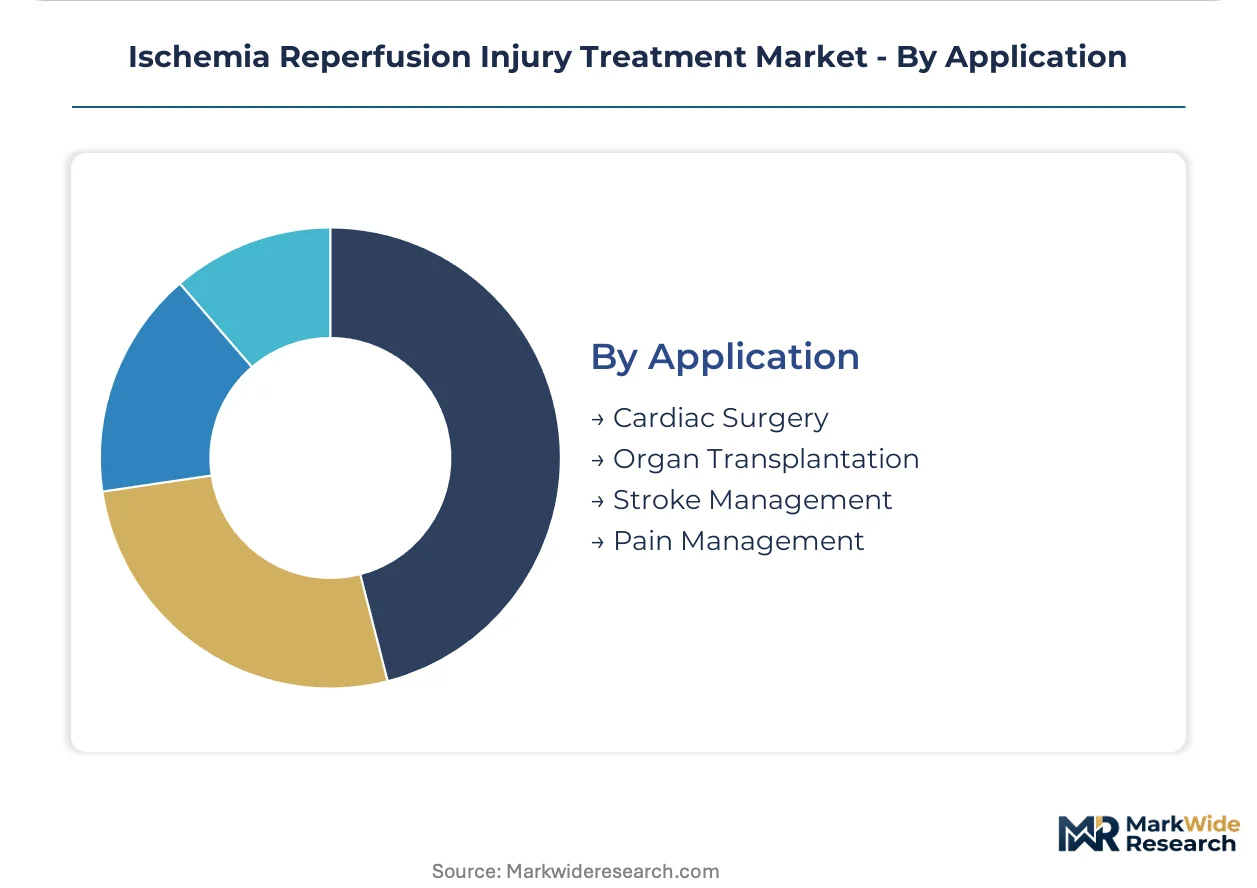
Application:
Transplant infrastructure maturity and aging demographics create divergent demand profiles across therapeutic areas.
- Cardiac Surgery:Coronary artery bypass grafting, valve replacement, and aortic procedures where temporary cardioplegic arrest necessitates myocardial protection protocols. Germany and Japan sustain procedure demand through established cardiac surgery networks and aging populations requiring revascularization.
- Organ Transplantation:Kidney, liver, heart, and lung transplantation where donor organ preservation and recipient reperfusion management determine graft outcomes. United States transplant centers lead adoption of machine perfusion with pharmacologic adjunct delivery.
- Stroke Management:Endovascular thrombectomy and revascularization procedures for acute ischemic stroke.
- Pain Management:Interventions for ischemic pain syndromes including complex regional pain syndrome and peripheral vascular disease.
Established reimbursement pathways sit with Cardiac Surgery. Emerging protocol standardization is concentrated in Organ Transplantation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors North American cell therapy development, while transplant infrastructure maturity and regulatory pathways create divergent competitive advantages across national markets.
United States
CMS reimbursement pathways for cardiac surgery adjuncts sustain procedure volumes at academic medical centers. The FDA's accelerated approval pathways for regenerative medicines compress clinical trial timelines and redirect R&D investment. Massachusetts General Hospital and the Cleveland Clinic pioneer risk-sharing arrangements tied to graft survival metrics.
Germany
Aging populations requiring revascularization sustain cardiac surgery demand through established networks. The EMA's ATMP framework imposes chemistry, manufacturing, and controls standards that elevate barrier costs for novel entrants. Heidelberg and Berlin academic medical centers adopt closed-system bioreactors to reduce contamination risk in cell therapy manufacturing.
Japan
The PMDA's conditional early approval system accelerates market access for regenerative medicines addressing unmet ischemic conditions. METI's industrial policy supports domestic biomanufacturing capacity expansion. Tokyo and Osaka transplant centers lead adoption of machine perfusion platforms integrated with organ preservation protocols.
United Kingdom
NHS procurement consolidation favors suppliers with verified carbon-footprint reductions under EU Green Deal sustainability criteria. The MHRA operates post-Brexit alignment with EMA standards while maintaining independent ATMP assessment pathways. London's Royal Brompton Hospital and Cambridge biomedical cluster concentrate early technology validation studies.
India
CDSCO's emerging ATMP framework positions the country as a cost-efficient manufacturing destination for cell therapy developers. The PLI scheme incentivizes domestic biopharmaceutical production capacity. Hyderabad and Bengaluru biotechnology corridors attract foreign sponsors establishing centralized manufacturing models for regional supply.
Ischemia Reperfusion Injury Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory validation depth. The vendor base stratifies between multinational pharmaceutical conglomerates with established cytoprotectant portfolios and emerging cell therapy specialists building ATMP-compliant manufacturing infrastructure. Three archetypes dominate: integrated biopharmaceutical conglomerates with global distribution networks, cell therapy platform specialists with closed-system manufacturing capabilities, and device-therapy combination developers with perfusion technology expertise. Competitive moves concentrate on strategic partnerships for ATMP manufacturing capacity and geographic expansion into Japan's early-access regulatory environment.
Within the integrated biopharmaceutical tier, Pfizer Inc. and Novartis AG exemplify divergent strategic positioning. Pfizer leverages its global manufacturing footprint to sustain supply security across multiple continents, while Novartis anchors its position through deep specialization in cell therapy platforms. Bristol Myers Squibb occupies a distinct position competing on immunomodulatory approaches that differentiate its pipeline from conventional cytoprotective agents.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| AstraZeneca PLC |
| Bristol Myers Squibb |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Merck KGaA |
| Takeda Pharmaceutical Company |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Process development scientists with GMP manufacturing experience in Germany and Switzerland command compensation premiums that widen spreads between premium-tier cell therapies and commodity-grade pharmaceuticals. Labor-cost differentials between centralized European bioreactor facilities and distributed manual processing sites directly translate into three-tier pricing structures across the market.
Pricing Analysis
Graft survival guarantees anchor value-based pricing for hypothermic machine perfusion platforms adopted by United States academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates closed-system bioreactor-manufactured cell products from open-process autologous therapies and generic small-molecule cytoprotectants. Price differentiation rests on EMA ATMP certification status and cold-chain reliability records. Cost compression in the pharmaceutical segment intensifies as REACH authorization requirements extend preclinical timelines for novel chemical entities. Hospital procurement committees demonstrate highest price sensitivity for capital equipment with extended depreciation cycles, while transplant centers show lowest sensitivity for outcome-guaranteed perfusion devices.
Supply Chain Analysis
Dual-sourcing requirements for dimethyl sulfoxide cryopreservation media and plasma-derived albumin force manufacturers to qualify suppliers across the United States, Germany, and Japan. Raw material dependencies center on limited geographic sources for critical cell culture media, viral vector production substrates, and mitochondrial-targeted antioxidant precursors. Single-source vulnerability concentrates in autologous workflow reagents where batch qualification timelines stretch eighteen to twenty-four months. Distribution runs through direct-to-hospital specialty pharmacy channels for temperature-sensitive biologics, bypassing traditional wholesale networks to reduce cold-chain handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy manufacturing capacity constraints prop pricing power for qualified GMP facilities, with batch failure rates and contamination risk perpetuating supply scarcity across transplant networks.
For Market Incumbents: Deepen backward integration into cryopreservation media production to secure dimethyl sulfoxide supply against viral safety events and collection disruptions. Expand closed-system bioreactor capacity in Germany and Japan to capture PMDA conditional early approval pathway demand. Patent thickets around mitochondrial-targeted antioxidants threaten freedom-to-operate for novel small-molecule programs; prioritize biologic modalities with established human safety profiles. For New Entrants and Emerging Players: Capture India's CDSCO emerging ATMP framework opportunity by establishing cost-efficient manufacturing in Hyderabad and Bengaluru biotechnology corridors. Mechanical perfusion device convergence with pharmacologic cocktails represents the most penetrable white-space, enabling differentiated product-service bundles for organ transplantation protocols. Direct-to-hospital specialty pharmacy channels offer the clearest go-to-market angle for temperature-sensitive biologics seeking margin protection. For Investors and Strategic Acquirers: Re-rating potential sits with cell therapy platform specialists given FDA accelerated approval pathway compression and Japan PMDA early-access regulatory convergence. Five-to-ten year viability favors developers with centralized allogeneic manufacturing models over distributed autologous processing infrastructure. Watch batch failure rate improvements at German academic medical centers as the inflection indicator for scalable platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Bioreactor Scale-Up | Heidelberg and Berlin academic medical centers reduce contamination risk through automated cell therapy manufacturing adoption. |
| PMDA Conditional Early Approval Pathway | Tokyo and Osaka transplant centers accelerate regenerative medicine market access for unmet ischemic conditions. |
| Direct-to-Hospital Specialty Pharmacy Channel | United States integrated delivery networks bypass wholesale distribution to minimize cold-chain handoffs for biologics. |
| EU Green Deal Sustainability Certification | NHS procurement consolidation favors suppliers with verified carbon-footprint reductions across European hospital networks. |
| Mechanical-Pharmacologic Convergence Development | German hospitals integrate hypothermic machine perfusion with targeted cytoprotectant delivery for transplantation protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving cell therapy manufacturing executives, transplant surgeons, hospital procurement directors, and regulatory affairs specialists. FDA accelerated approval pathway documentation, EMA ATMP framework submissions, PMDA conditional early approval records, and ClinicalTrials.gov enrollment data provided validation benchmarks. Bottom-up procedure volume estimates from cardiac surgery networks and organ transplantation registries were triangulated against top-down pharmaceutical and device revenue assessments.
Granularity-level modeling dissected therapeutic modality, technology platform, end-user facility type, and application area across the projection horizon. Segmentation dimensions included product type clusters, autologous versus allogeneic manufacturing approaches, academic medical center versus community hospital procurement patterns, and cardiac surgery versus organ transplantation versus stroke management application protocols. CAGRs were derived from procedure volume trajectories, pricing tier evolution, and technology substitution rates. Forecast inputs incorporated EMA ATMP chemistry manufacturing controls compliance timelines and Japan PMDA early-access pathway utilization rates.
The model holds under sustained FDA and EMA regulatory convergence; deviation in accelerated approval evidentiary standards or REACH authorization toxicological data expectations would shift the outlook materially. Deviation in cryopreservation technical breakthroughs or plasma-derived biologics supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Angina Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Tachycardia Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
North America Acute Coronary Syndrome Market