
 Coronary Artery Disease Therapeutics Market | 2026-2036
Coronary Artery Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Coronary Artery Disease Therapeutics Market Outlook
CE marking under the EU Medical Device Regulation is reorganizing competitive access for coronary intervention devices across European territories. AstraZeneca leverages its SGLT2 inhibitor portfolio to sustain cardiovascular outcomes leadership. Pfizer competes through anticoagulant specialization in post-acute coronary syndrome settings. Novartis anchors its position with lipid-lowering therapies that integrate into hospital formularies.
Coronary artery disease therapeutics encompass pharmacological agents, implantable devices, and procedural interventions designed to restore myocardial perfusion and prevent ischemic events. These treatments function through plaque modification, thrombus dissolution, or mechanical revascularization, with stent platforms requiring cobalt-chromium alloy specifications and drug-eluting polymer coatings to control neointimal hyperplasia. Medications dominate current revenue pools due to chronic administration patterns, while transcatheter delivery modes capture the fastest expansion as minimally invasive techniques displace conventional surgical revascularization in eligible patients. Home care end users remain underdeveloped relative to hospital channels, though remote monitoring integration is shifting post-procedural follow-up economics.
FDA, EMA, and Japan's PMDA enforce divergent evidentiary standards for novel antithrombotic therapies, with FDA's accelerated approval pathways enabling earlier market entry than EMA's conditional marketing authorization framework. These regulatory asymmetries shape sponsor trial design priorities and geographic launch sequencing. Stakeholders must monitor evolving HTA methodologies in Germany and Japan, where incremental clinical benefit thresholds now determine reimbursement access for next-generation drug-eluting stents and PCSK9 inhibitors.
Market Dynamics
Transcatheter revascularization techniques are compressing the addressable surgical bypass population as cobalt-chromium stent platforms achieve parity outcomes with coronary artery bypass grafting in multivessel disease. Hospital procurement committees now weight 30-day readmission metrics above device acquisition cost in vendor selection algorithms.
Growth Catalysts
- FDA Accelerated Approval:Compressed evidentiary timelines for novel antiplatelet therapies enable sponsors to reach reimbursement eligibility faster than under EMA conditional frameworks. Cardiology centers in the United States prioritize these pathways for portfolio expansion.
- Japan's PMDA Sakigake Designation:Priority review status for first-in-class PCSK9 inhibitors shortens regulatory lag versus standard submissions. Tokyo's university hospitals anchor early adoption cohorts.
- Bioresorbable polymer coatings:Controlled-release sirolimus analogues reduce dual antiplatelet therapy duration from twelve to three months. German interventional cardiologists drive European uptake of these platforms.
Market Restraints
- Cobalt-chromium alloy concentration:Three specialty foundries in Germany and Japan supply 80% of stent-grade substrate, creating single-source vulnerability for device manufacturers.
- EU MDR technical documentation:Expanded clinical evaluation requirements for drug-eluting stents extend conformity assessment timelines by 14-18 months versus previous Medical Device Directive standards.
- Generic statin substitution:Rosuvastatin and atorvastatin commoditization in the United States compresses branded lipid therapy margins by 60% in commercial payer segments.
Strategic Opportunities
- Remote patient monitoring integration:Post-procedural telemetry via implantable loop recorders enables hospital-at-home reimbursement under CMS cardiac rehabilitation codes.
- India's PLI scheme for medical devices:Domestic manufacturing incentives for coronary stents reduce import dependence and create price-competitive supply for Southeast Asian markets.
- AI-enabled lesion assessment:Machine learning algorithms for fractional flow reserve computation converge with intravascular imaging to reduce operator variability in complex bifurcation cases.
Industry Challenges
- Interventional cardiologist training pipelines:Fellowship positions in transcatheter structural heart procedures divert talent from coronary intervention programs, creating procedural capacity constraints in community hospitals.
- Legacy electronic health record integration:Catheterization lab hemodynamic data systems require middleware development to feed quality registries mandated by the National Cardiovascular Data Registry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coronary Artery Disease Therapeutics Market |
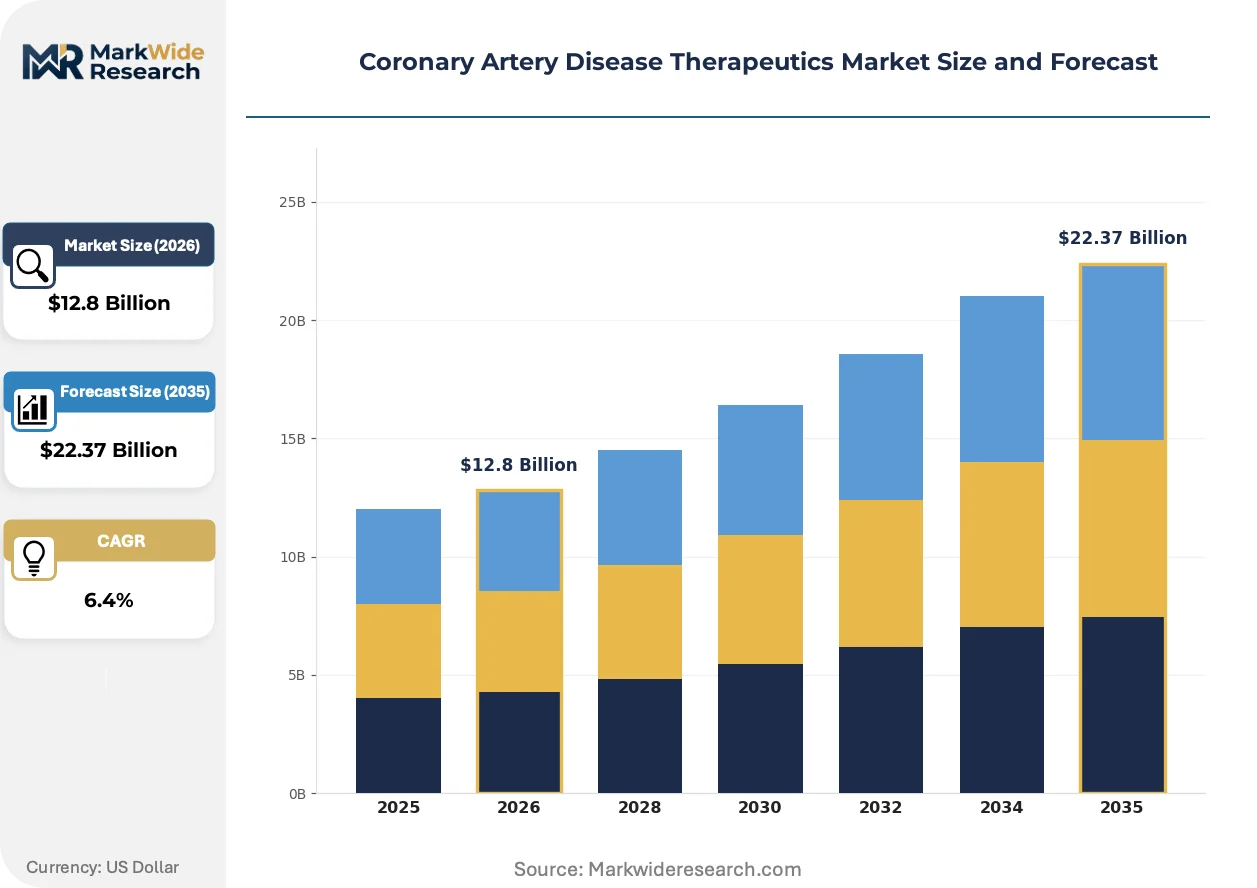
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Surgical Procedures, Rehabilitation Services Delivery Mode: Oral, Injectable, Transcatheter, Surgical End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Therapy Area: Preventive Care, Symptomatic Relief, Interventional Procedures, Risk Factor Management |
| Companies Covered | AstraZeneca Plc, Novartis AG, Pfizer Inc, Bayer AG, Bristol-Myers Squibb Company, Merck & Co., Inc, Sanofi, Kowa Pharmaceuticals America, Inc., Viatris Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coronary Artery Disease Therapeutics Market Strategic Shifts
Bioresorbable scaffold technology is supplanting permanent metallic platforms as the default strategy for younger patients with de novo lesions. Regulatory science evolution and procurement model compression are simultaneously reshaping competitive access and commercial economics.
Thin-strut cobalt-chromium stents with biodegradable polymer matrices achieve target lesion revascularization rates below 5% at twelve months. Community hospitals in the United States adopt these platforms faster than academic centers due to simplified inventory management. The technology is supplanting first-generation durable polymer devices in formulary negotiations.
REACH authorization requirements for nanomaterial-containing drug coatings now mandate extended carcinogenicity studies for novel polymer formulations. European notified bodies apply these standards retroactively to pipeline products, forcing sponsors to redesign toxicology programs. German manufacturers absorb the longest timeline impacts as BfArM coordinates with ECHA on substance classification.
Hospital purchasing consortia in the United States consolidate antiplatelet therapy procurement through specialty pharmacy carve-outs, displacing traditional wholesale distribution. Integrated delivery networks in Texas and Florida negotiate direct manufacturer contracts for ticagrelor and prasugrel. This concentration is most visible in Medicare Advantage populations where pharmacy benefit manager alignment drives therapeutic substitution protocols.
Coronary Artery Disease Therapeutics Market Segmentation
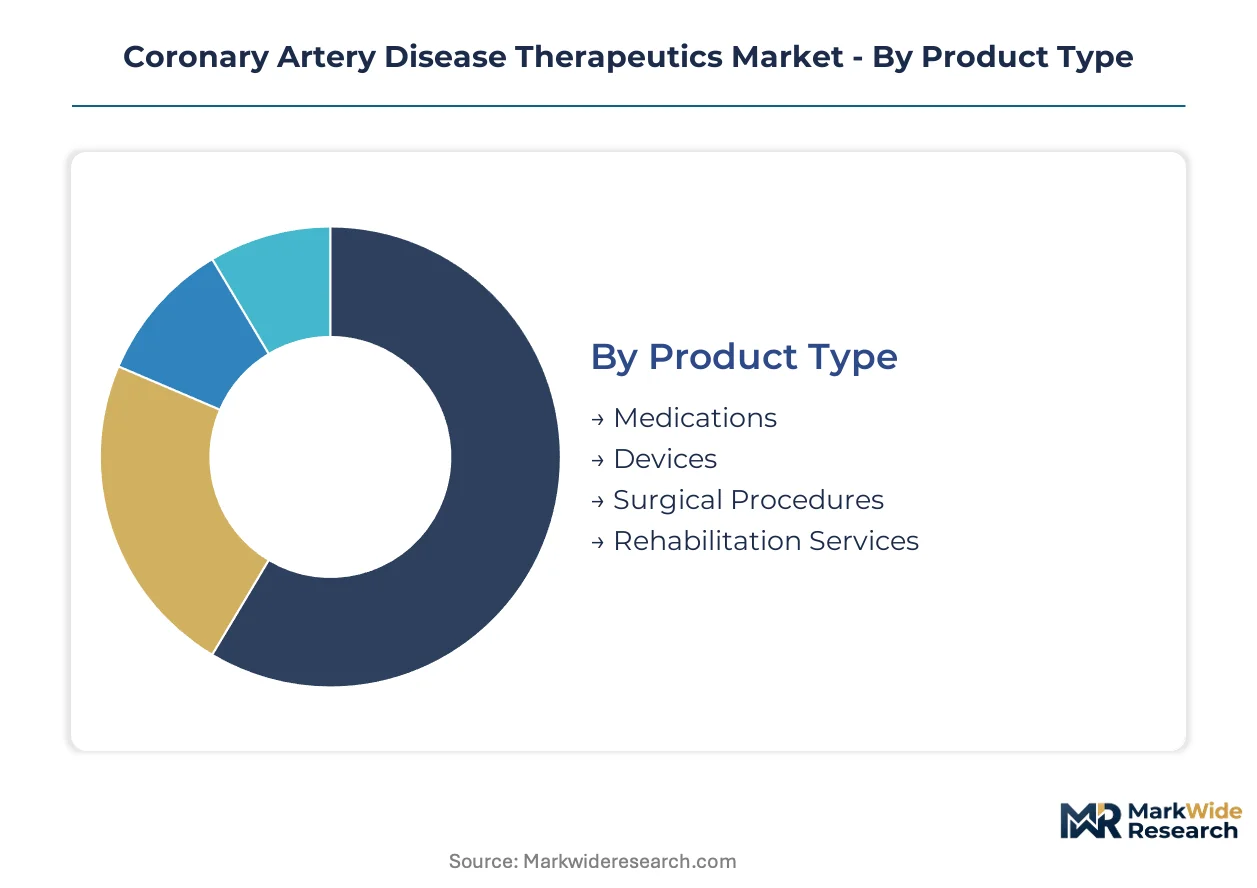
Channel economics in coronary artery disease therapeutics diverge sharply across product categories. Medications flow through consolidated specialty pharmacy networks, while devices and procedures anchor hospital-based procurement committees with divergent vendor selection criteria.
Product Type:
Medications and devices capture divergent margin structures through distinct distribution architectures, with chronic therapies favoring wholesale consolidation and acute interventions requiring direct manufacturer contracting.
- Medications:Antiplatelet agents, statins, beta-blockers, and ACE inhibitors form chronic administration regimens with recurring pharmacy benefit claims. Demand concentrates in Medicare Advantage populations where pharmacy benefit manager alignment drives therapeutic substitution protocols.
- Devices:Drug-eluting stents and balloon catheters incorporate cobalt-chromium alloy substrates with polymer coatings controlling sirolimus analogue release. German interventional cardiologists anchor European uptake of bioresorbable polymer platforms that compress dual antiplatelet therapy duration.
- Surgical Procedures:Coronary artery bypass grafting retains indication in multivessel disease with diabetes or reduced left ventricular function.
- Rehabilitation Services:Cardiac rehabilitation programs integrate exercise physiology with medication adherence monitoring under CMS reimbursement codes.
Medications dominate installed base. Devices are where expansion concentrates.
Delivery Mode:
Cost tier stratification separates acute intervention pricing from chronic therapy economics, with transcatheter delivery commanding premium reimbursement relative to oral generic substitution.
- Oral:Once-daily antiplatelet and lipid-lowering tablets anchor outpatient compliance programs. Generic statin substitution in the United States compresses branded therapy margins in commercial payer segments.
- Injectable:Subcutaneous PCSK9 inhibitors and heparin formulations require specialty pharmacy cold chain logistics. Japan's PMDA Sakigake Designation accelerates priority review for first-in-class injectable therapies.
- Transcatheter:Percutaneous coronary intervention delivery of stent platforms achieves mechanical revascularization without thoracotomy. Community hospitals in the United States adopt thin-strut cobalt-chromium devices faster than academic centers.
- Surgical:Sternotomy-based revascularization retains role in complex three-vessel disease with concomitant valvular pathology.
Oral formulations dominate prescription volume. Transcatheter delivery is climbing the fastest.
End User:
Customer type determines procurement sophistication, with integrated delivery networks consolidating vendor negotiations while home care channels remain fragmented.
- Hospitals:Catheterization labs in the United States, Germany, and Japan anchor procedural volume with 24/7 primary PCI capability. Hospital procurement committees weight 30-day readmission metrics above device acquisition cost in vendor selection algorithms.
- Outpatient Clinics:Ambulatory surgical centers capture stable elective PCI cases with lower overhead structures. Texas and Florida integrated delivery networks negotiate direct manufacturer contracts for antiplatelet therapy carve-outs.
- Rehabilitation Centers:Phase II cardiac rehabilitation programs integrate telemetry monitoring with exercise prescription.
- Home Care:Remote patient monitoring via implantable loop recorders enables hospital-at-home reimbursement under CMS cardiac rehabilitation codes.
Hospitals dominate procedural revenue. Home care is gaining share fastest.
Therapy Area:
Application maturity separates established preventive protocols from emerging interventional technologies, with risk factor management anchoring long-term adherence economics.
- Preventive Care:Statin initiation and lifestyle modification protocols target asymptomatic patients with elevated 10-year cardiovascular risk scores. REACH authorization requirements for novel drug coatings now mandate extended carcinogenicity studies in European jurisdictions.
- Symptomatic Relief:Nitrates and beta-blockers address angina pectoris through afterload reduction and heart rate control.
- Interventional Procedures:Percutaneous and surgical revascularization restore myocardial perfusion in acute coronary syndromes. Bioresorbable scaffold technology supplants permanent metallic platforms as the default strategy for younger patients with de novo lesions.
- Risk Factor Management:SGLT2 inhibitors and GLP-1 receptor agonists integrate cardiovascular outcomes data into diabetes treatment algorithms.
Preventive care dominates prescription initiations. Interventional procedures represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government reimbursement stability and aging demographics concentrate procedural demand in specific national markets. Hospital systems expand catheterization capacity where regulatory pathways compress development timelines. Procurement sophistication varies sharply across territories.
United States
Medicare Advantage enrollment growth and hospital-at-home reimbursement expansion drive demand for remote cardiac monitoring solutions. FDA accelerated approval pathways enable earlier market entry for novel antiplatelet therapies than EMA conditional frameworks. Texas and Florida integrated delivery networks negotiate direct manufacturer contracts for antiplatelet therapy carve-outs.
Germany
Statutory health insurance reimbursement stability and interventional cardiologist density support sustained procedural volume in university hospitals. BfArM coordinates with ECHA on REACH authorization requirements for nanomaterial-containing drug coatings, extending toxicology timelines. The Rhine-Ruhr and Bavarian medical technology clusters absorb the longest conformity assessment impacts under EU MDR technical documentation standards.
Japan
Super-aging demographics and universal health coverage sustain demand for minimally invasive revascularization procedures. PMDA Sakigake Designation grants priority review status for first-in-class PCSK9 inhibitors, shortening regulatory lag versus standard submissions. Tokyo's university hospitals anchor early adoption cohorts for novel injectable therapies.
India
Rising coronary disease prevalence and expanding health insurance penetration create addressable demand for cost-optimized stent platforms. The PLI scheme for medical devices incentivizes domestic manufacturing of coronary stents, reducing import dependence. Gujarat and Karnataka production clusters supply price-competitive devices for Southeast Asian export markets.
Coronary Artery Disease Therapeutics Market Competitive Environment
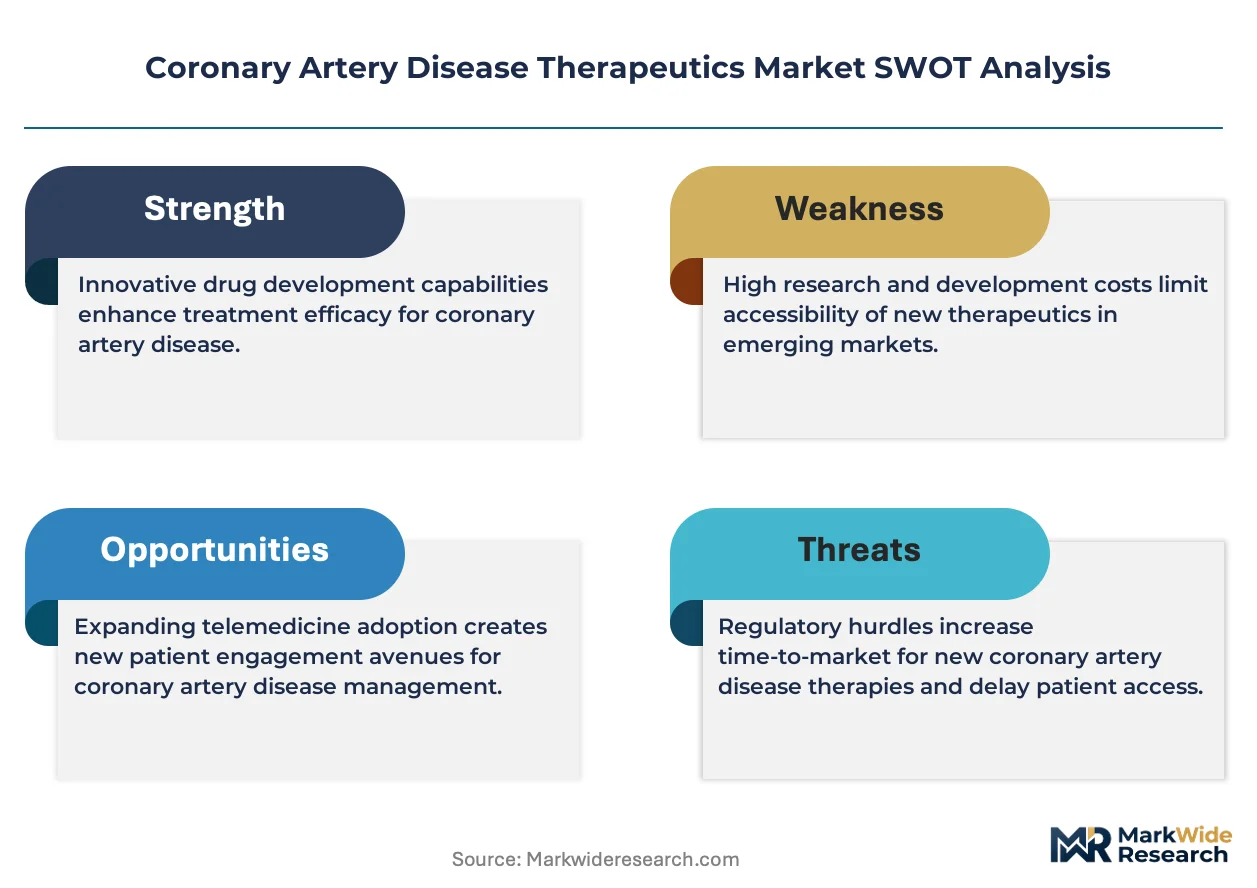
Listed leaders compete with private specialists across portfolio breadth and geographic reach in this market. The competitive structure consolidates around pharmaceutical conglomerates with cardiovascular verticals and device manufacturers with interventional specialization. Three archetypes dominate: SGLT2 inhibitor portfolio holders, anticoagulant specialists, and lipid-lowering therapy anchors. Strategic moves center on formulary integration negotiations and catheterization lab vendor consolidation.
Among the pharmaceutical conglomerates, AstraZeneca Plc, Novartis AG, and Pfizer Inc occupy positions defined by therapeutic specialization rather than scale alone. AstraZeneca exemplifies the cardiovascular outcomes leadership archetype through metabolic therapy integration. Novartis AG represents the hospital formulary anchor model with lipid-lowering portfolio depth. Pfizer Inc sits within the post-acute coronary syndrome anticoagulant specialization tier.
| Leading Market Players |
|---|
| AstraZeneca Plc |
| Novartis AG |
| Pfizer Inc |
| Bayer AG |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc |
| Sanofi |
| Kowa Pharmaceuticals America, Inc. |
| Viatris Inc |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month conformity assessment extensions under EU MDR technical documentation standards concentrate pricing power with German and Japanese cobalt-chromium foundries that supply stent-grade substrate, while hospital procurement committees in the United States weight 30-day readmission metrics above device acquisition cost in vendor selection algorithms.
Pricing Analysis
Certification level (FDA-grade versus CE-marked versus standard ISO) creates the primary spread across drug-eluting stent tiers, with bioresorbable polymer platforms commanding premium positioning against first-generation durable polymer devices. Three-tier pricing structure across premium, standard, and economy levels reflects dual antiplatelet therapy duration compression capabilities and cobalt-chromium alloy purity grades. Pricing pressure stems from generic statin substitution in Medicare Advantage populations, where pharmacy benefit manager alignment drives therapeutic substitution protocols. Integrated delivery networks in Texas and Florida exhibit highest price sensitivity through direct manufacturer contract negotiations, while academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Inventory buffers for cobalt-chromium alloy substrate extend to 90-120 days across device manufacturers due to concentration in three German and Japanese specialty foundries supplying 80% of stent-grade material. Raw material dependencies center on cobalt-chromium alloy specifications, sirolimus analogue active pharmaceutical ingredients, and biodegradable polymer matrices for controlled-release coatings. Single-source vulnerability for substrate supply creates structural risk, compounded by REACH authorization requirements for nanomaterial-containing drug coatings extending toxicology timelines. Distribution runs through hospital procurement committees and integrated delivery network specialty pharmacy carve-outs, displacing traditional wholesale channels for antiplatelet therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for novel antiplatelet therapies compress evidentiary timelines, creating a high-growth disruption window as bioresorbable scaffold technology supplants permanent metallic platforms in formulary negotiations.
For Market Incumbents: Compound formulary integration depth through SGLT2 inhibitor cardiovascular outcomes data and hospital system partnership consolidation. Defend against generic statin substitution pressure by anchoring lipid-lowering portfolios in academic medical center protocols. Prioritize backward integration into cobalt-chromium alloy substrate supply to mitigate single-source foundry concentration risk in Germany and Japan. For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-tracks market entry for AI-enabled fractional flow reserve algorithms targeting community hospital catheterization labs. White-space concentration sits with remote patient monitoring integration under CMS cardiac rehabilitation codes, where hospital-at-home reimbursement remains underdeveloped relative to procedural channels. Target ambulatory surgical centers in Medicare Advantage-dominant states with simplified inventory management thin-strut stent platforms. For Investors and Strategic Acquirers: Long-term, this sits as a chronic therapy annuity play because antiplatelet administration patterns generate recurring pharmacy benefit claims regardless of procedural volume cyclicality. Acquisition focus centers on device manufacturers with bioresorbable polymer coating intellectual property and established German interventional cardiologist adoption cohorts. Monitor PMDA Sakigake Designation grant velocity as inflection signal for priority review pathway utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Accelerated Approval Pathway | Compressed timelines enable sponsors to reach reimbursement eligibility faster than EMA conditional frameworks. |
| Bioresorbable Polymer Coating Development | German interventional cardiologists drive European uptake of platforms reducing dual antiplatelet therapy duration. |
| Hospital System Partnership Consolidation | Texas and Florida integrated delivery networks negotiate direct manufacturer contracts displacing wholesale distribution. |
| Remote Patient Monitoring Integration | Implantable loop recorders enable hospital-at-home reimbursement under CMS cardiac rehabilitation codes. |
| EU MDR Technical Documentation Compliance | Extended clinical evaluation requirements reshape competitive access timelines for drug-eluting stent sponsors. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with interventional cardiologists, hospital procurement committee members, formulary directors, and regulatory affairs specialists; and secondary validation through FDA 510(k) filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement contract repositories. Bottom-up triangulation across catheterization lab procedure volumes, pharmacy benefit claims data, and device shipment records converged with top-down market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type (medications, devices, procedures, rehabilitation services), delivery mode (oral, injectable, transcatheter, surgical), end user (hospitals, outpatient clinics, rehabilitation centers, home care), and therapy area (preventive care, symptomatic relief, interventional procedures, risk factor management). CAGRs were derived from procedural volume trajectories, reimbursement rate stability assessments, and demographic aging curves across United States, Germany, Japan, and India markets.
Underlying assumptions cover regulatory pathway timeline stability, cobalt-chromium substrate supply continuity, and Medicare Advantage enrollment growth patterns, with deviation risk concentrated in EU MDR conformity assessment duration variability and generic substitution acceleration in commercial payer segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
US Statin Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Global Statin Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Global Pericarditis Market