
 Treatment-Resistant Hypertension Management Market | 2026-2036
Treatment-Resistant Hypertension Management Market Size, Share, and Industry Trends Forecast 2026-2036
Treatment-Resistant Hypertension Management Market Analytics
Renal denervation catheter systems is reshaping how interventional cardiologists approach patients failing triple-drug regimens, shifting care from pharmaceutical escalation to minimally invasive neuromodulation. Abbott leverages its electrophysiology infrastructure to sustain catheter-based hypertension programs across integrated delivery networks. Medtronic anchors the device segment through Symplicity registry data and symposia-led physician education. AstraZeneca competes in the pharmaceutical layer with fixed-dose combination therapies targeting residual volume and aldosterone pathways.
Treatment-resistant hypertension management encompasses therapeutic interventions for patients whose blood pressure remains above goal despite concurrent use of three antihypertensive agents of different classes at maximally tolerated doses, including a diuretic; renal denervation employs radiofrequency or ultrasound energy delivered via femoral access to disrupt renal afferent and efferent sympathetic nerves. The primary purpose is reducing cardiovascular event risk in a population carrying disproportionate rates of stroke, heart failure, and end-stage renal disease. Combination therapy leads the pharmaceutical segment due to payer preference for single-pill adherence and guideline endorsement of multi-mechanism blockade. Device-based therapy represents the fastest-expanding structural category as catheter-based renal denervation secures reimbursement in selective European markets and builds procedural volume in United States academic medical centers. Medication management remains the mature margin pool where generic diuretic and renin-angiotensin blockade commoditization pressures originator pricing.
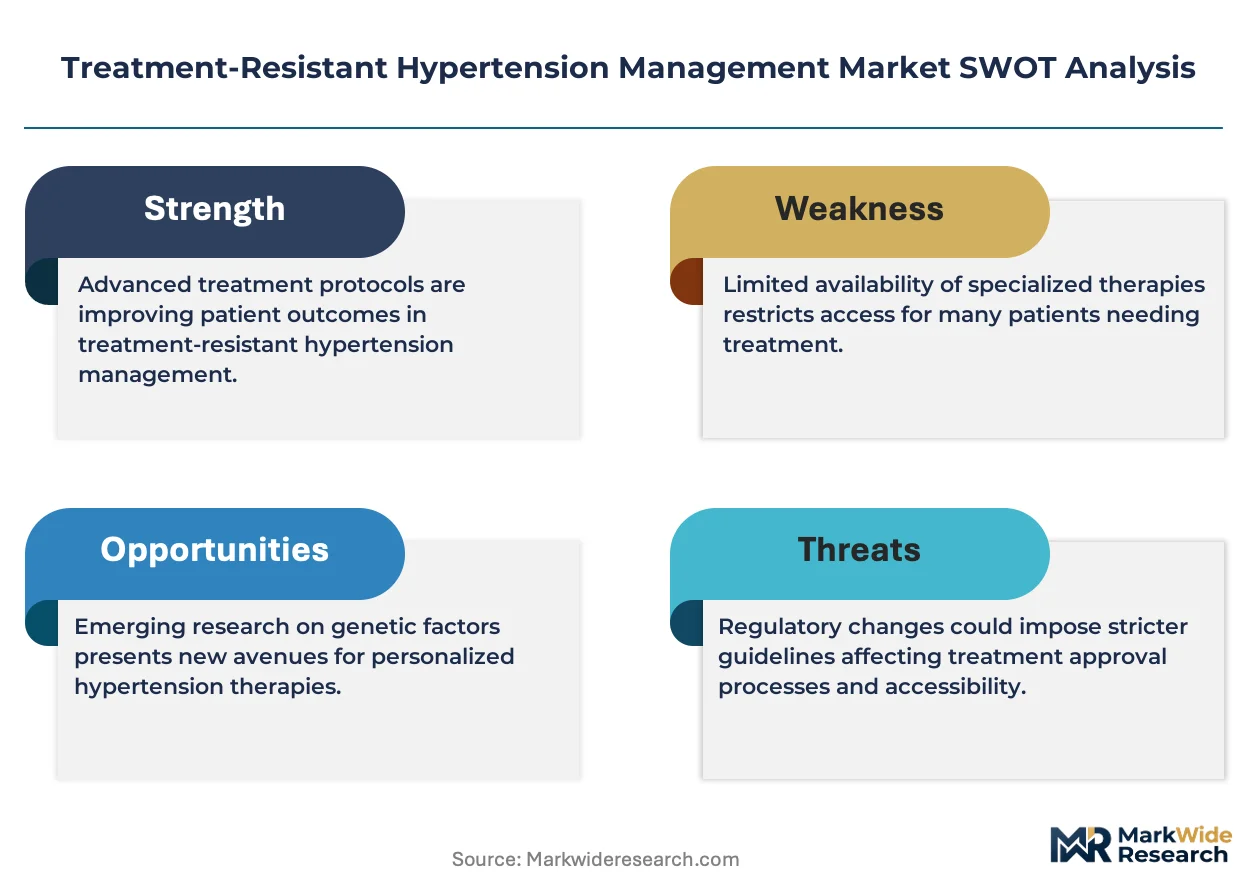
The FDA breakthrough device program and EMA's adaptive pathway for innovative cardiovascular technologies shape market access timelines for renal denervation systems, while the EU Medical Device Regulation imposes clinical evidence requirements that favor companies with post-market surveillance infrastructure. In the United States, CMS national coverage determination processes govern whether hospital outpatient departments receive adequate reimbursement for catheter-based procedures. Stakeholders must monitor whether real-world evidence from hypertension registries satisfies payer demands for durable blood pressure reduction beyond procedural endpoints.
Market Dynamics
Renal denervation catheter systems are compressing the pharmaceutical escalation pathway for refractory hypertension, forcing integrated delivery networks to restructure interventional cardiology service lines around procedural neuromodulation rather than drug titration protocols.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated review pathway compresses time-to-market for catheter-based hypertension therapies, allowing earlier commercial access in United States academic medical centers.
- Triple-drug failure population:Patients remaining above blood pressure targets despite maximally tolerated diuretic, renin-angiotensin, and calcium channel blockade create procedural demand for sympathetic nerve ablation.
- Radiofrequency energy delivery:Catheter systems employing thermal nerve disruption achieve durable blood pressure reduction with femoral access techniques familiar to electrophysiology specialists.
Market Restraints
- CMS national coverage determination delays:Reimbursement uncertainty for hospital outpatient departments constrains procedural volume expansion despite FDA device approvals.
- EU Medical Device Regulation clinical evidence requirements:Post-market surveillance infrastructure demands favor established manufacturers with registry capabilities, raising competitive entry barriers.
- Generic diuretic commoditization:Patent-expired thiazide and loop diuretics compress pharmaceutical segment margins, reducing originator investment in combination therapy development.
Strategic Opportunities
- Underpenetrated Japanese referral networks:Refractory hypertension specialist pathways in Japan remain less developed than United States or German systems, creating first-mover positioning for device manufacturers.
- Ultrasound-based renal denervation:Alternative energy modalities that avoid radiofrequency thermal injury may expand treatable patient populations with renal artery anatomical variants.
- Integrated delivery network risk contracts:Hospital systems bearing cardiovascular outcome accountability seek procedural interventions that reduce long-term stroke and heart failure event rates.
Industry Challenges
- Interventional cardiology training gaps:Sympathetic nerve ablation requires specific catheter manipulation skills distinct from coronary or electrophysiology procedures, limiting qualified operator supply.
- Real-world evidence generation timelines:Payer demands for durable blood pressure reduction data beyond procedural endpoints require multi-year registry follow-up, delaying reimbursement expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treatment-Resistant Hypertension Management Market |
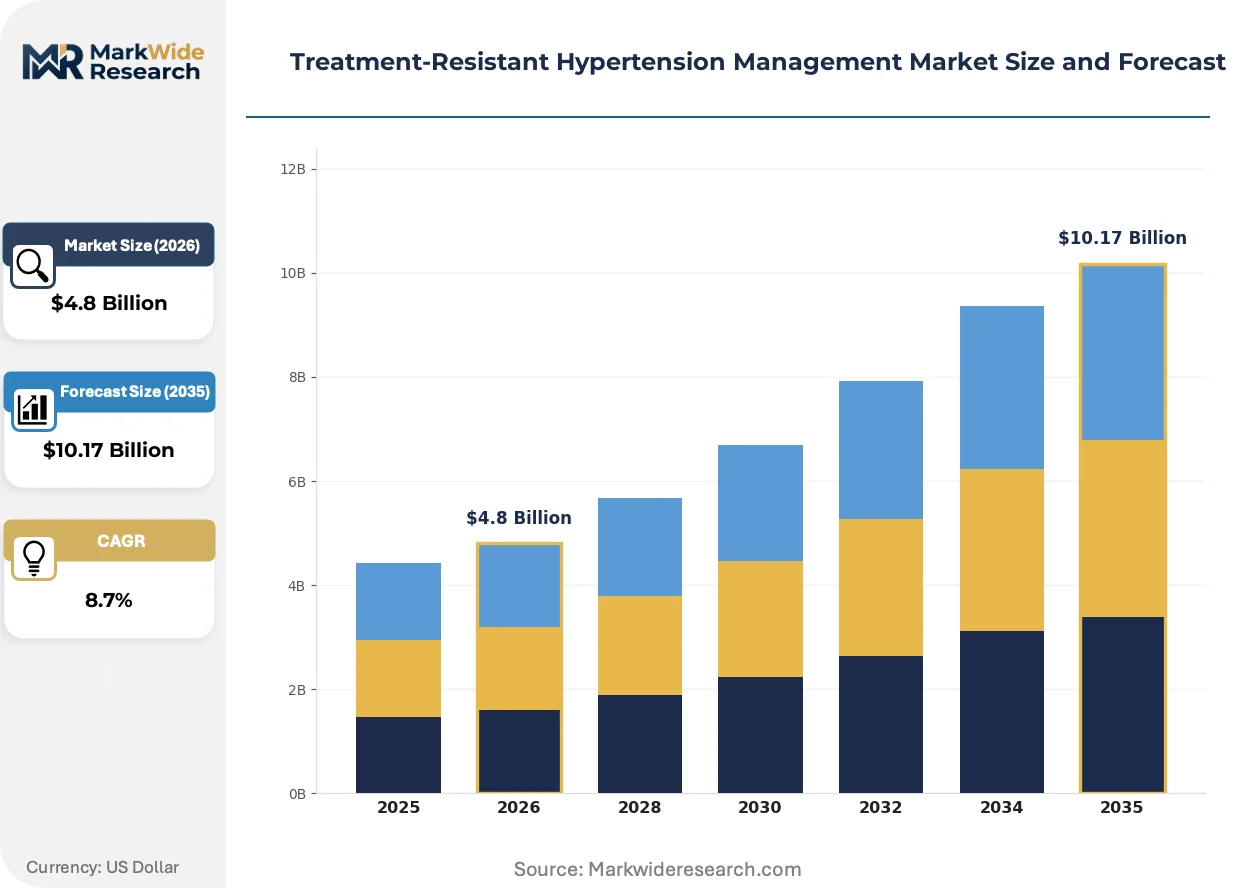
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensive Drugs, Diuretics, Renin Inhibitors, Combination Therapy Delivery Mode: Oral Administration, Injectable Solutions, Intravenous Infusion, Transdermal Patches Patient Type: Elderly Patients, Adolescents, Adults, Post-Operative Patients Treatment Approach: Medication Management, Lifestyle Modification, Device-Based Therapy, Intervention Strategies |
| Companies Covered | Abbott, Quantum Genomics, Janssen Biotech, Kona Medical, KBP Biosciences, Medtronic, Ionis Pharmaceuticals, AstraZeneca, Vifor Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treatment-Resistant Hypertension Management Market Evolving Landscape
Device-based therapy protocols are displacing pharmaceutical escalation as the default third-line intervention, while regulatory pathways and procurement models co-evolve to accommodate procedural hypertension management.
Ultrasound renal denervation systems are virtualizing the treatment paradigm for patients with unfavorable renal artery anatomy or prior radiofrequency failure. Academic medical centers in Germany and Japan are piloting these alternative energy platforms for expanded eligibility criteria. The technology is virtualizing the boundary between treatable and excluded patient populations, compressing the residual volume of pharmaceutical-only candidates.
EMA's adaptive pathway for innovative cardiovascular technologies is compressing market access timelines for catheter-based hypertension devices in selective European markets. The framework permits conditional approval with post-market evidence generation, shifting regulatory risk toward manufacturers with robust surveillance infrastructure. German hospital outpatient departments are responding by accelerating procurement of renal denervation systems ahead of permanent reimbursement codes.
Specialty cardiology clinics are unbundling hypertension management from general internal medicine, creating dedicated refractory hypertension service lines with embedded interventional capabilities. United States integrated delivery networks are consolidating referral pathways into these focused centers, displacing community-based pharmaceutical titration. The concentration is most visible in United States metropolitan markets where hospital systems compete for cardiovascular outcome-based contracts.
Treatment-Resistant Hypertension Management Market Segmentation
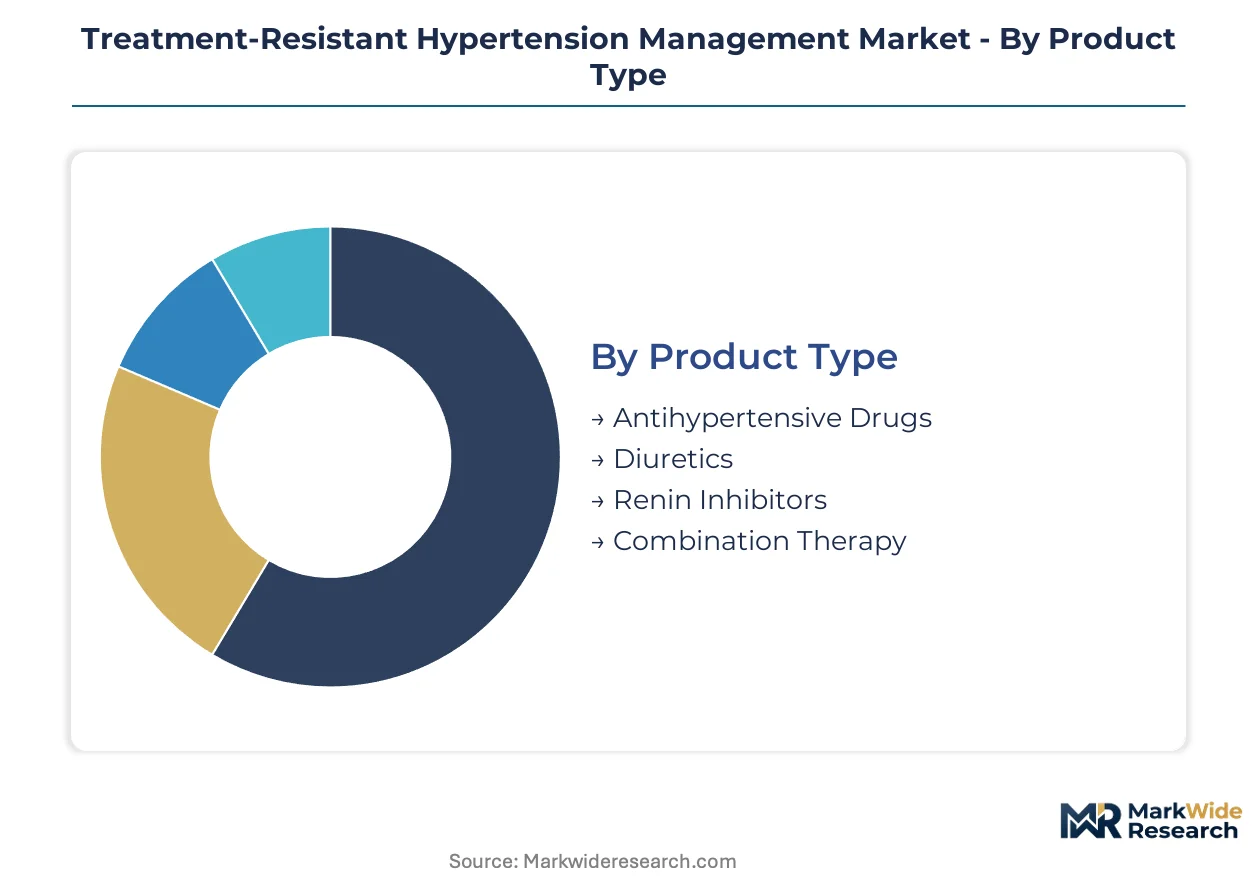
Segmentation in treatment-resistant hypertension management reveals distinct procurement cycles and clinical decision pathways. Pharmaceutical segments turn over through formulary negotiations while device categories require capital equipment planning and operator certification timelines.
Product Type:
Prescription renewal cycles vary dramatically across this category, with generic diuretics turning over monthly and combination therapies locking in annual contracts.
- Antihypertensive Drugs:ACE inhibitors, ARBs, and calcium channel blockers constitute the chronic maintenance layer where pharmaceutical benefit managers negotiate tiered formulary placement. United States Medicaid programs and German statutory health insurance funds drive volume through preferred drug lists that favor single-mechanism generics.
- Diuretics:Thiazide and loop diuretics represent the commoditized foundation of triple-drug regimens, with hydrochlorothiazide and chlorthalidone commanding the lowest per-unit reimbursement. Payer pressure on this segment accelerates originator exit and concentrates manufacturing among contract research organizations.
- Renin Inhibitors:Aliskiren-containing formulations occupy a narrow niche for patients with ACE inhibitor intolerance.
- Combination Therapy:Single-pill formulations of ARB-diuretic or ACE inhibitor-calcium channel blocker combinations capture adherence premiums.
Antihypertensive drugs dominate installed base. Combination therapy is where expansion concentrates.
Delivery Mode:
Cost tiers separate acute intervention formats from chronic maintenance channels, with hospital-administered infusions commanding procedure-based reimbursement.
- Oral Administration:Tablet and capsule formulations anchor outpatient management through retail pharmacy networks and mail-order distribution. United States Medicare Part D and Japanese NHI reimbursement structures favor ninety-day supplies that reduce per-prescription dispensing costs.
- Injectable Solutions:Subcutaneous formulations including aliskiren depot preparations target non-adherent populations in specialty clinic settings.
- Intravenous Infusion:Hospital-based administration for hypertensive emergency bridges to oral conversion.
- Transdermal Patches:Clonidine patches serve nursing home populations where swallowing difficulties complicate oral regimens.
Oral administration dominates installed base. Injectable solutions are climbing the fastest.
Patient Type:
Volume concentration varies by age-stratified prevalence, with elderly populations presenting the highest absolute case counts and adolescents representing emerging diagnostic expansion.
- Elderly Patients:Patients over seventy-five carry the highest prevalence of true resistant hypertension with renal impairment and polypharmacy complexity. United States Medicare Advantage plans and Japanese long-term care insurance systems generate concentrated demand for simplified regimens.
- Adults:The forty-five to sixty-four demographic presents the largest addressable population for device-based therapy candidacy.
- Adolescents:Pediatric resistant hypertension remains confined to specialty academic centers.
- Post-Operative Patients:Surgical recovery units manage transient hypertensive episodes.
Elderly patients dominate installed base. Adults are gaining share fastest.
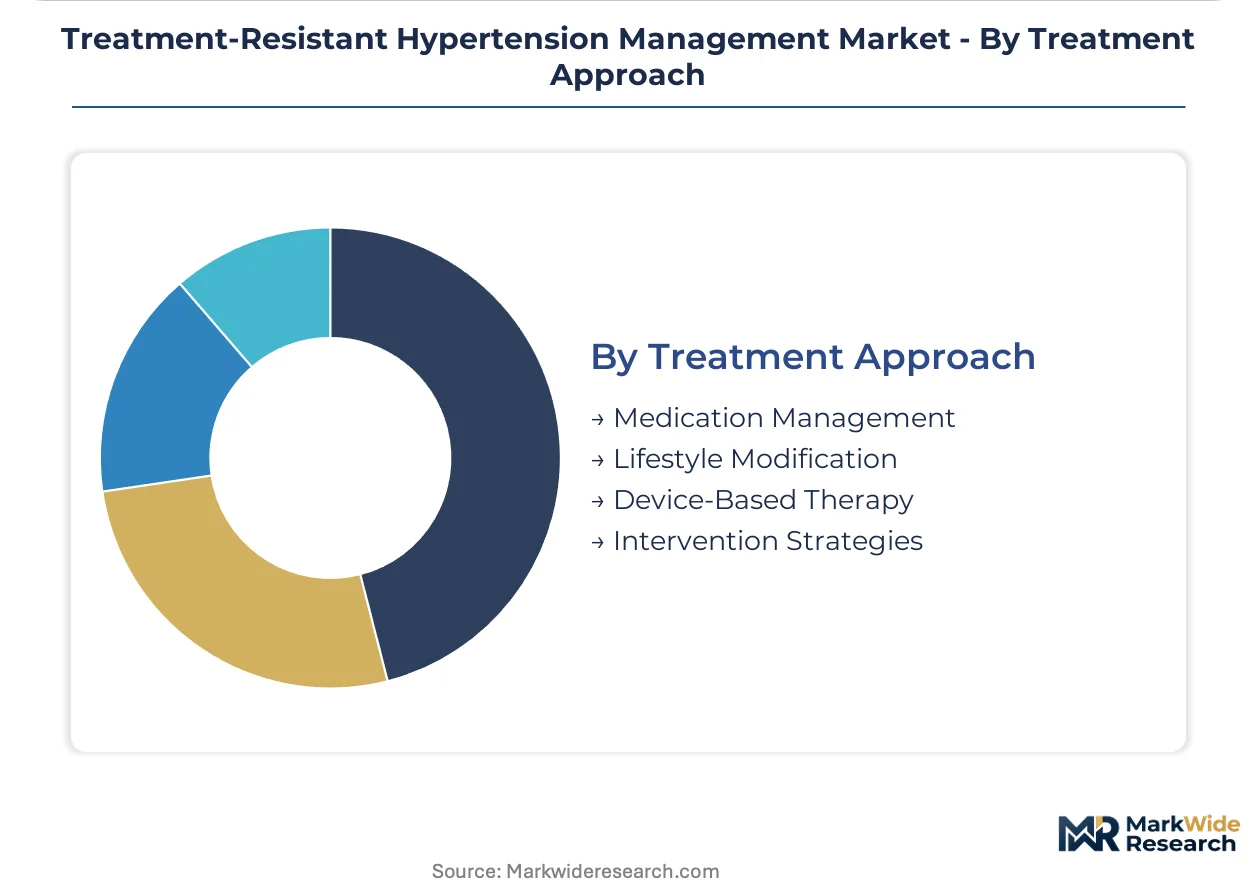
Treatment Approach:
Maturity gradients separate established pharmaceutical protocols from emerging procedural categories requiring new infrastructure investment.
- Medication Management:Triple-drug titration protocols represent the default first-line intervention with established clinical guidelines and universal reimbursement. German disease management programs and United States patient-centered medical homes structure care around pharmacist-led medication review.
- Device-Based Therapy:Renal denervation catheter systems require interventional cardiology suite allocation and electrophysiology-trained operators.
- Lifestyle Modification:Dietary sodium restriction and weight management programs complement pharmaceutical intervention.
- Intervention Strategies:Baroreflex activation and carotid body ablation remain investigational.
Medication management dominates installed base. Device-based therapy is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and specialty cardiology clinics in the United States, Germany, and Japan concentrate the highest procedural volumes for device-based hypertension management. Academic medical centers in these markets anchor referral networks for patients failing triple-drug regimens.
United States
Medicare Advantage plans and integrated delivery networks drive demand for renal denervation procedures that reduce long-term cardiovascular event rates. The FDA breakthrough device designation pathway accelerates commercial access for catheter-based therapies in academic medical centers. Cleveland Clinic and Mayo Clinic anchor interventional cardiology training programs that expand qualified operator supply.
Germany
Statutory health insurance funds and hospital outpatient departments create concentrated procurement demand for device-based hypertension interventions. The EMA adaptive pathway permits conditional approval with post-market evidence generation, compressing access timelines for renal denervation systems. Berlin and Munich academic medical centers pilot ultrasound-based alternative energy platforms for expanded patient eligibility.
Japan
Long-term care insurance systems and elderly populations with polypharmacy complexity generate demand for simplified hypertension management regimens. The PMDA reviews renal denervation technologies through its priority review pathway for innovative cardiovascular devices. Tokyo and Osaka metropolitan hospital systems compete for cardiovascular outcome-based contracts that favor procedural interventions.
United Kingdom
NHS England specialized commissioning frameworks concentrate refractory hypertension referrals into dedicated service lines at tertiary centers. NICE technology appraisals govern reimbursement decisions for novel device therapies in hospital outpatient settings. London and Manchester academic medical centers structure interventional cardiology training around sympathetic nerve ablation techniques.
Switzerland
Swissmedic's streamlined review procedures for breakthrough cardiovascular technologies attract early commercial launches from multinational device manufacturers. Cantonal hospital systems in Zurich and Geneva integrate renal denervation into electrophysiology service lines with existing catheter infrastructure. The country's outcome-based health insurance models reward procedural interventions that demonstrate durable blood pressure reduction.
Treatment-Resistant Hypertension Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmaceutical and device segments. The market structures around three tiers: diversified cardiovascular conglomerates with electrophysiology infrastructure, mid-cap device specialists focused on renal denervation catheter systems, and pharmaceutical originators with fixed-dose combination portfolios. Strategic moves concentrate on registry-led physician education, symposia-based training programs, and integrated delivery network risk contracting.
Among diversified cardiovascular device manufacturers, Medtronic and Abbott anchor the interventional tier through their electrophysiology and catheter system capabilities. AstraZeneca occupies a position within the pharmaceutical layer with combination therapies targeting residual volume pathways. Kona Medical exemplifies the device-specialist archetype focused on alternative energy modalities for sympathetic nerve ablation.
| Leading Market Players |
|---|
| Abbott |
| Quantum Genomics |
| Janssen Biotech |
| Kona Medical |
| KBP Biosciences |
| Medtronic |
| Ionis Pharmaceuticals |
| AstraZeneca |
| Vifor Pharma |
| Others |
Value Network & Pricing Analysis
Trans-Atlantic air freight corridors connecting Frankfurt and Chicago carry renal denervation catheter systems at premium rates that compound with EU Medical Device Regulation compliance costs, concentrating supply-side pricing power among manufacturers with established post-market surveillance infrastructure while forcing tiered pricing stratification across academic medical centers and community hospital systems.
Pricing Analysis
Cost-plus contracts with medical device price indexation anchor procurement agreements between hospital systems and catheter manufacturers. Three-tier pricing structure across premium multi-electrode, standard single-electrode, and economy reprocessed catheter levels reflects FDA breakthrough designation status and operator training bundling. Pricing pressure stems from CMS national coverage determination delays that extend sales cycles and intensify competitive discounting for pilot programs. Community hospital systems exhibit highest price sensitivity due to capital equipment budget constraints, while integrated delivery networks with cardiovascular outcome contracts absorb premium tier pricing.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from institutional distributors ease working capital burdens for mid-cap catheter manufacturers competing against diversified cardiovascular conglomerates. Manufacturing concentrates in United States, Ireland, and Costa Rica for final assembly, with nitinol tubing and electrode materials sourced from Japan and Germany. Single-source vulnerability in radiofrequency generator components creates procurement risk for second-tier device specialists. Distribution runs through specialized cardiovascular device distributors holding consignment inventory at hospital catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in United States metropolitan markets, with Cleveland Clinic, Mayo Clinic, and Kaiser Permanente anchoring procurement decisions that displace fragmented community-based purchasing.
For Market Incumbents: Harden registry-led physician education programs against ultrasound-based alternative energy entrants by embedding Symplicity and Spyral data into cardiology fellowship curricula. Secure vertical integration into electrode manufacturing to offset nitinol supply constraints from Japanese specialty metals suppliers. Lock in multi-year risk contracts with Medicare Advantage plans bearing cardiovascular outcome accountability. For New Entrants and Emerging Players: Establish a beachhead in Japanese metropolitan hospital systems where refractory hypertension referral networks remain underdeveloped relative to United States and German markets. Target ultrasound renal denervation platforms for patients with unfavorable renal artery anatomy excluded from radiofrequency protocols. Pursue conditional EMA adaptive pathway approval with German academic medical center pilot partnerships. For Investors and Strategic Acquirers: Device-specialist manufacturers with alternative energy platforms and robust post-market surveillance infrastructure present acquisition targets with defensible positioning against commoditized pharmaceutical segments. Long-term viability hinges on CMS national coverage determination resolution and real-world evidence generation timelines from hypertension registries. Watch for FDA expanded indication decisions and German statutory health insurance permanent reimbursement code establishment as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses time-to-market for catheter-based hypertension therapies in United States academic medical centers. |
| Hospital System Risk Contracting | Integrated delivery networks bearing cardiovascular outcome accountability seek procedural interventions reducing stroke and heart failure event rates. |
| Symposium-Based Physician Training | Medtronic and Abbott anchor operator supply expansion through electrophysiology-trained interventional cardiology fellowship programs. |
| Ultrasound Platform Development | Alternative energy modalities expand treatable patient populations with renal artery anatomical variants beyond radiofrequency eligibility. |
| Reimbursement Strategy Execution | CMS national coverage determination and German statutory health insurance permanent code procurement govern procedural volume scalability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA adaptive pathway decisions, CMS national coverage determination documents, and hospital procurement databases. Primary interviews engaged interventional cardiologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and payer access specialists across United States, German, and Japanese markets. Bottom-up segmentation modeling triangulates against top-down epidemiological prevalence estimates for triple-drug failure populations.
Forecast inputs include procedure volume build-ups from academic medical center pilot programs, pharmaceutical formulary placement trajectories, and regulatory approval timeline assumptions across the projection horizon. Segmentation dimensions span product type, delivery mode, patient type, and treatment approach with geographic regulatory cluster overlays. CAGRs derive from logistic diffusion curves for device adoption layered against pharmaceutical segment generic erosion rates. Reimbursement expansion scenarios and real-world evidence generation timelines inform scenario-weighted outputs.
Stress conditions across CMS coverage determination delays, EU Medical Device Regulation enforcement intensity, and Japanese PMDA priority review timeline variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding physician training pipeline expansion and hospital capital equipment allocation priorities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Vasculitis Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market