
 Global Dental Endodontics Market | 2026-2036
Global Dental Endodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Endodontics Market Foresight
Premium-grade nickel-titanium alloy specifications is collapsing the gap between commodity files and performance instruments in the Global Dental Endodontics Market. Dentsply Sirona leverages its vertically controlled melt-to-file production to sustain consistent superelasticity thresholds across batch volumes. Envista anchors its competitive stance through intensive R&D spending on proprietary surface treatments that extend instrument fatigue resistance. Coltene Group differentiates by dominating the European bioceramic obturation segment with specialized sealer chemistries engineered for warm vertical compaction techniques.
Dental endodontics encompasses the diagnosis, prevention, and treatment of diseases affecting dental pulp and periradicular tissues, utilizing instruments typically fabricated from nickel-titanium alloys with austenite finish temperatures between 15°C and 35°C to achieve controlled flexibility within curved root canal anatomies. The primary commercial purpose centers on preserving natural dentition through mechanized debridement, disinfection, and three-dimensional sealing of root canal systems. Rotary systems occupy the largest margin pool among product categories due to recurring instrument replacement cycles and practitioner brand loyalty tied to handpiece compatibility. Bioceramic materials represent the fastest-growing technology segment as clinicians shift from resin-based sealers toward calcium silicate compositions that demonstrate superior dimensional stability and osteoconductive potential. Root canal therapy generates the dominant application volume, though retreatment procedures are expanding fastest as aging initial treatments fail and magnification-assisted disassembly techniques improve.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations are elevating barrier costs for new file manufacturers while accelerating consolidation toward established quality management systems. ISO 3630-1 standards for endodontic instruments and ADA Seal of Acceptance criteria collectively shape product specifications that determine market access in North America and European dental supply chains. REACH compliance for nickel ion release and Japan's PMDA material master file requirements add further jurisdictional complexity to global product registration strategies. Stakeholders must monitor evolving regulatory divergence between major markets as a decisive factor in localization versus centralized manufacturing investment.
Market Dynamics
Precision manufacturing of nickel-titanium alloys with controlled austenite transformation temperatures is compressing the performance gap between commodity and premium endodontic files, forcing suppliers to differentiate through proprietary surface engineering rather than raw material specifications alone.
Growth Catalysts
- Warm vertical compaction protocols:Specialty dental practices in Germany and Japan are standardizing bioceramic sealer placement techniques that demand matched file-taper systems, expanding instrument replacement cycles.
- EU MDR technical documentation pathways:Stricter biocompatibility validation for nickel-titanium instruments is accelerating consolidation toward manufacturers with established quality management systems.
- Magnification-assisted retreatment:Operating microscopes and dental loupes are enabling safer disassembly of failed initial therapies, expanding addressable procedure volumes in aging patient cohorts.
Market Restraints
- Nickel price volatility:Superelastic alloy feedstock costs fluctuate with base metal commodity markets, squeezing margin stability for file manufacturers without captive melt capacity.
- Regulatory friction from FDA 510(k) backlog:Extended clearance timelines for novel file geometries are delaying commercialization of next-generation instruments in the United States.
- Substitute threat from implant dentistry:Titanium dental implants are capturing extraction-replacement decisions that previously defaulted to endodontic preservation, particularly in anterior tooth cases.
Strategic Opportunities
- Underpenetrated Indian dental infrastructure:Government clinic expansion and private practice consolidation in Maharashtra and Karnataka are creating first-mover advantages for rotary system suppliers.
- AI-guided canal mapping:Integration of cone-beam computed tomography with machine learning segmentation is enabling predictive file selection algorithms that reduce procedural variability.
- Brazilian ANVISA fast-track pathways:Streamlined registration for instruments with prior FDA or CE marking is lowering barrier costs for manufacturers seeking Latin American market entry.
Industry Challenges
- ISO 3630-1 dimensional tolerance compliance:Batch-to-batch consistency in tip diameter and taper angle requires capital-intensive metrology infrastructure that strains mid-tier manufacturers.
- Clinician training standardization:Variable continuing education quality across dental schools and private academies produces inconsistent technique adoption that complicates product positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Endodontics Market |
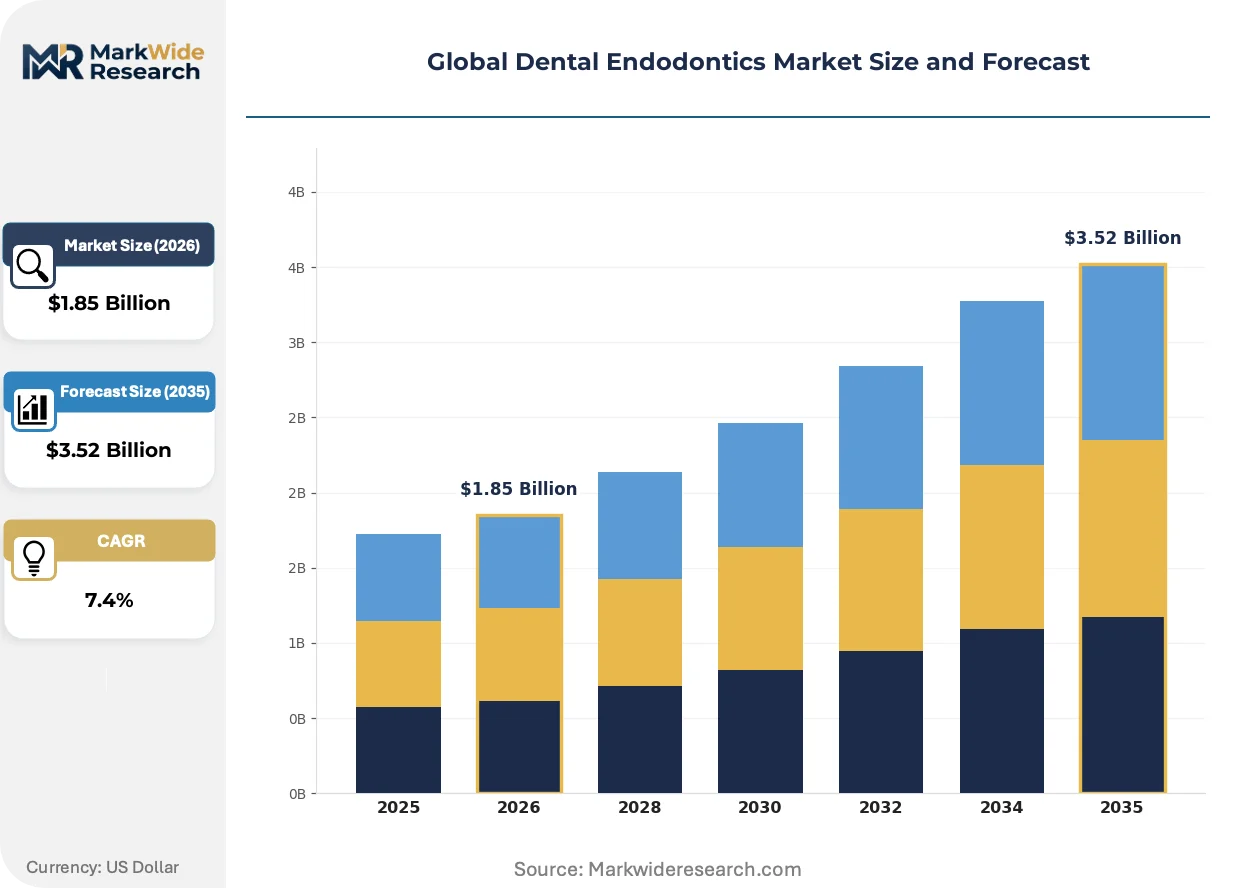
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.52 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endodontic Files, Irrigants, Obturation Materials, Apex Locators, Rotary Systems Application: Pulpitis Treatment, Root Canal Therapy, Apicoectomy, Retreatment Procedures, Trauma Management End User: Dental Clinics, Specialty Practices, Hospitals, Academic Institutions, Diagnostic Centers Technology: Nickel-Titanium Instruments, Ultrasonic Devices, Digital Imaging, Bioceramic Materials, Adhesive Systems |
| Companies Covered | Dentsply Sirona, Envista, Coltene Group, Septodont Holding, Ultradent Products, Ivoclar Vivadent, Brasseler USA, FKG Dentaire, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Endodontics Market Shifts & Advancements
Digital workflow integration is reconfiguring how endodontic instruments are specified, procured, and utilized in clinical practice, with software-defined treatment planning now preceding physical instrument selection.
Engineered surface treatments utilizing diamond-like carbon coatings and electropolishing protocols are supplanting unmodified nickel-titanium substrates in premium file segments. Multi-specialty dental groups in the United States are adopting these enhanced instruments at replacement rates exceeding standard files by substantial margins. The shift is compressing addressable market share for commodity manufacturers while rewarding suppliers with proprietary finishing capabilities.
EU MDR post-market surveillance obligations are mandating systematic clinical follow-up data collection for bioceramic sealers and nickel-titanium files marketed in European Economic Area member states. Manufacturers must now maintain vigilance systems that track adverse events across distributed practitioner networks. Small-to-mid-tier suppliers lacking regulatory affairs infrastructure are exiting the European market rather than absorbing compliance costs, concentrating supply among established quality system holders.
Group purchasing organizations and dental service organizations are consolidating procurement authority previously dispersed across individual practitioner decisions. These centralized buyers are unbundling instrument pricing from handpiece compatibility commitments that historically locked practitioners into single-supplier ecosystems. The restructuring is most visible in United States metropolitan markets where dental practice aggregation has advanced furthest, with similar patterns emerging in Australian capital cities.
Global Dental Endodontics Market Segmentation
Segmentation in dental endodontics reveals how procurement authority concentrates among distinct buyer types and how technology tiers map to specific clinical workflows. Understanding these divisions exposes where margin pools accumulate and where substitution threats operate most intensely.
Product Type:
Channel mix varies sharply across product categories, with rotary systems and files flowing primarily through dealer networks while obturation materials and apex locators penetrate via direct specialty distributor relationships.
- Rotary Systems:Mechanized nickel-titanium file systems with matched handpiece interfaces generate recurring revenue through instrument replacement cycles. Demand clusters in United States metropolitan dental service organizations where standardization across practice networks drives volume procurement.
- Obturation Materials:Bioceramic sealers and gutta-percha variants engineered for warm vertical compaction protocols command premium positioning. German specialty practices lead adoption as EU MDR biocompatibility documentation becomes mandatory for market access.
- Endodontic Files:Hand and rotary instruments fabricated to ISO 3630-1 dimensional tolerances.
- Irrigants:Sodium hypochlorite and EDTA solutions for canal disinfection protocols.
- Apex Locators:Electronic devices for working length determination during procedures.
By volume, endodontic files lead. By growth pace, obturation materials are climbing the fastest as clinicians transition from resin-based to calcium silicate sealers.
Application:
Procedure complexity and reimbursement differentiation create distinct cost tiers across applications, with retreatment commanding premium instrument specifications and trauma management requiring emergency supply chain responsiveness.
- Root Canal Therapy:Primary debridement, disinfection, and sealing of infected pulp chambers represents the foundational volume application. Japanese university hospitals anchor demand for precision-engineered nickel-titanium systems with documented fatigue resistance profiles.
- Retreatment Procedures:Disassembly and re-treatment of failed initial therapies demands specialized instruments for safe removal of existing filling materials. United States specialty practices with operating microscope capabilities are expanding this segment most aggressively as aging patient cohorts present with deteriorating historical work.
- Pulpitis Treatment:Vital pulp therapy and partial pulpotomy interventions.
- Apicoectomy:Surgical root-end resection and retrograde filling procedures.
- Trauma Management:Emergency interventions for dental injuries and luxation cases.
Root canal therapy dominates absolute procedure counts. Retreatment procedures are gaining share fastest as magnification-assisted techniques improve safety profiles.
End User:
Customer type determines purchasing behavior patterns, with dental service organizations consolidating previously fragmented individual practice decisions while academic institutions prioritize training compatibility over instrument longevity.
- Dental Clinics:General practice settings performing routine endodontic procedures represent volume demand. Indian government clinic expansion in Maharashtra and Karnataka is creating concentrated procurement opportunities for rotary system suppliers.
- Specialty Practices:Endodontic-focused clinics with advanced imaging and magnification infrastructure. These buyers in Germany and Japan are standardizing bioceramic sealer protocols that require matched file-taper systems.
- Hospitals:Institutional settings with centralized supply chain management.
- Academic Institutions:Dental schools and training programs with curriculum-driven instrument specifications.
- Diagnostic Centers:Facilities with cone-beam computed tomography capabilities supporting referral networks.
Specialty practices lead by revenue per procedure. Dental clinics are expanding most quickly in underpenetrated emerging markets.
Technology:
Technology maturity stages vary across segments, with nickel-titanium alloys approaching commodity specifications while digital imaging and bioceramic materials remain differentiated through proprietary innovation cycles.
- Bioceramic Materials:Calcium silicate-based sealers with dimensional stability and osteoconductive properties are displacing resin-based alternatives. Coltene Group's European market position in this segment demonstrates how specialized chemistry expertise creates defendable positioning.
- Digital Imaging:Cone-beam computed tomography and AI-guided canal mapping integration is reshaping pretreatment planning. United States multi-specialty dental groups are adopting these workflows at rates exceeding traditional radiography-dependent practices.
- Nickel-Titanium Instruments:Superelastic alloy files with controlled austenite transformation temperatures.
- Ultrasonic Devices:Piezoelectric and magnetostrictive systems for canal irrigation and post removal.
- Adhesive Systems:Resin-based materials for coronal sealing and restorative integration.
Nickel-titanium instruments retain volume leadership. Bioceramic materials are on the steepest expansion trajectory as regulatory biocompatibility requirements favor their clinical profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in dental endodontics favor established manufacturing bases in Germany and Japan against rising domestic production in India and Brazil. The United States maintains a persistent trade deficit in precision nickel-titanium instruments, sourcing specialized files from European and Asian suppliers while exporting bioceramic materials and digital imaging systems.
United States
Multi-specialty dental groups in metropolitan markets are consolidating procurement authority through group purchasing organizations, reshaping distributor relationships. FDA 510(k) clearance timelines for novel file geometries are extending commercialization delays, favoring incumbents with established quality systems. The Greater Boston and Pacific Northwest clusters anchor demand for magnification-assisted retreatment capabilities as aging patient cohorts present with failed initial therapies.
Germany
Specialty practices in Bavaria and North Rhine-Westphalia are standardizing warm vertical compaction protocols that require matched bioceramic sealer and file-taper systems. EU MDR technical documentation obligations for nickel-titanium biocompatibility are accelerating supplier consolidation toward manufacturers with vigilance infrastructure. The Stuttgart industrial corridor concentrates precision alloy processing capabilities serving instrument fabricators across the European Economic Area.
Japan
University hospitals in the Kanto and Kansai regions anchor demand for fatigue-resistant nickel-titanium systems with documented superelasticity profiles. PMDA material master file requirements for nickel ion release add jurisdictional complexity to registration strategies for foreign suppliers. The Nagoya manufacturing belt hosts specialized melt-to-file production facilities serving domestic and export markets with controlled austenite transformation specifications.
India
Government clinic expansion in Maharashtra and Karnataka is creating concentrated procurement opportunities for rotary system suppliers entering previously fragmented general practice markets. Central Drugs Standard Control Organization registration pathways for instruments with prior FDA or CE marking are streamlining market access for multinational manufacturers. Private practice consolidation in Delhi-NCR and Chennai is elevating demand for standardized instrument protocols across dental service organization networks.
Brazil
São Paulo and Rio de Janeiro specialty clinics are adopting digital imaging workflows that precede physical instrument selection, reshaping procurement patterns. ANVISA fast-track registration for devices with established FDA or CE approvals is lowering barrier costs for international suppliers seeking Latin American entry. The Minas Gerais industrial corridor is developing domestic bioceramic sealer production capabilities to reduce import dependency for calcium silicate compositions.
Global Dental Endodontics Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D scale dimensions, creating a tiered structure where public companies sustain vertical control over alloy supply chains while private operators concentrate on niche surface engineering capabilities. The vendor base segments into three strategic archetypes: diversified dental conglomerates with melt-to-file production integration, mid-tier specialists with proprietary finishing protocols, and regional distributors with localized regulatory affairs infrastructure. Dominant competitive moves include backward integration into nickel-titanium alloy melting capacity and strategic partnerships with dental service organizations for volume procurement contracts.
Among the diversified conglomerates, Dentsply Sirona and Envista occupy positions defined by upstream control over superelastic alloy specifications and intensive R&D spending on fatigue resistance technologies. Coltene Group exemplifies the specialist archetype through concentrated positioning in bioceramic obturation chemistry. These three anchors demonstrate how competitive differentiation in dental endodontics depends on material science capabilities rather than distribution scale alone, with quality management system maturity becoming the decisive barrier under tightening EU MDR and FDA biocompatibility requirements.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista |
| Coltene Group |
| Septodont Holding |
| Ultradent Products |
| Ivoclar Vivadent |
| Brasseler USA |
| FKG Dentaire |
| Danaher |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for nickel-titanium alloy feedstock lock in both supply access and price visibility for rotary file manufacturers serving United States dental service organizations and German specialty practices. These arrangements insulate holders from nickel commodity volatility while stranding competitors to spot market exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Global Dental Endodontics Market. Price differentiation rests on ISO 3630-1 certification grade and fatigue resistance documentation, with premium instruments commanding substantial margins for holders of proprietary surface treatment patents. Cost compression in standard-grade files is intensifying because mid-tier manufacturers lack captive melt capacity. Dental clinics in emerging markets exhibit highest price sensitivity, while Japanese university hospitals prioritize performance specifications over unit economics.
Supply Chain Analysis
Austenite transformation temperature control in nickel-titanium alloy melting constitutes a chokepoint that underwrites competitive positioning for precision file manufacturers. Production gravity centers on Germany, Japan, and Switzerland, with specialized melt-to-file facilities in Stuttgart and Nagoya feeding downstream fabricators. Raw material dependencies span nickel ore concentrates, superelastic alloy billets, and diamond-like carbon coating precursors. Single-source vulnerability concentrates in superelastic alloy suppliers with validated biocompatibility profiles for EU MDR compliance. Distribution runs through dealer networks for rotary systems and direct specialty distributors for obturation materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among dental service organizations and group purchasing organizations, fragmenting individual practitioner decision-making and elevating buyer leverage in contract negotiations.
For Market Incumbents: Consolidate backward integration into nickel-titanium alloy melting capacity to secure feedstock cost visibility against nickel commodity volatility. Deepen quality management system investments to sustain EU MDR technical documentation advantages as biocompatibility requirements tighten. Channel control through exclusive handpiece compatibility protocols remains essential for locking practitioner ecosystems against emerging competitors. For New Entrants and Emerging Players: Differentiate on AI-guided canal mapping integration that reduces procedural variability for dental service organizations standardizing across practice networks. Target underpenetrated Indian government clinic expansion in Maharashtra and Karnataka with rotary systems priced for first-mover procurement cycles. ANVISA fast-track registration leveraging prior FDA clearance offers lowest-friction Latin American market entry. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with proprietary bioceramic sealer chemistries and established European regulatory affairs infrastructure. Long-term viability hinges on material science capabilities rather than distribution scale alone, with quality system maturity becoming the decisive barrier under tightening global biocompatibility requirements. Monitor EU MDR vigilance system implementation as an inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Melting | Captive nickel-titanium production insulates margins from commodity volatility and secures batch consistency. |
| EU MDR Technical Documentation Investment | Established quality systems accelerate market access while forcing competitor exit from European Economic Area. |
| AI-Guided Canal Mapping Partnership | Software integration with cone-beam computed tomography reshapes pretreatment planning and instrument selection protocols. |
| Bioceramic Sealer Chemistry Specialization | Calcium silicate expertise captures warm vertical compaction protocol standardization in German specialty practices. |
| Dental Service Organization Volume Contracting | Centralized procurement authority unbundles instrument pricing from historical handpiece compatibility lock-ins. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with endodontic specialists, dental service organization procurement directors, rotary system manufacturing engineers, bioceramic sealer R&D leads, and regulatory affairs managers at file fabricators. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, ISO 3630-1 standard revision records, PMDA material master file submissions, and hospital procurement contract disclosures. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Across the analysis window, the forecast framework modeled product type segmentation by technology maturity stage, application segmentation by procedure complexity tier, end user segmentation by purchasing behavior pattern, and geographic segmentation by regulatory cluster alignment. CAGRs were derived from procedure volume growth trajectories, instrument replacement cycle compression, and technology substitution elasticities. Nickel price volatility assumptions and EU MDR implementation timelines fed scenario-weighted projections.
Material uncertainties — nickel commodity spikes, FDA 510(k) clearance delays for novel geometries, and implant dentistry substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about clinician training standardization and digital workflow adoption rates that may shift with continuing education quality variability. Practitioners should keep alternative scenarios live as regulatory divergence between major markets evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Aligners Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Dental Calipers Market
Dental Devices
Root Canal Market
Dental Devices
Dental Sealants Market
Dental Devices
UAE Dental Devices Market
Dental Devices
North America Dental Lab Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Dental Implants Market
Dental Devices
Dental Braces Market
Dental Devices
India Dental Devices Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Global Dental Labs Market