
 Medical Device Technologies Market | 2026-2036
Medical Device Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Technologies Market Outlook
Asset-light leasing models for high-end imaging and robotic surgical suites is reshaping competitive entry in the Medical Device Technologies Market. Medtronic leverages its captive financing arm to place capital equipment without upfront hospital expenditure. Siemens Healthineers anchors its position through long-term service contracts bundled with hardware upgrades. Philips Healthcare differentiates via subscription-based access to advanced imaging platforms across mid-tier hospital networks.
Medical device technologies encompass engineered instruments, apparatus, and software systems designed for diagnosis, treatment, or monitoring of medical conditions, typically manufactured under ISO 13485 quality management systems with biocompatibility validation per ISO 10993. These technologies serve to improve clinical outcomes, reduce procedural invasiveness, and enable continuous patient monitoring across acute and ambulatory settings. Diagnostic Equipment commands substantial margin pools due to high replacement cycles and software dependency, while Wearable Technology represents the fastest-expanding technology segment as remote patient monitoring protocols expand. Robotics within surgical applications sustains premium pricing through proprietary instrumentation and training ecosystems.
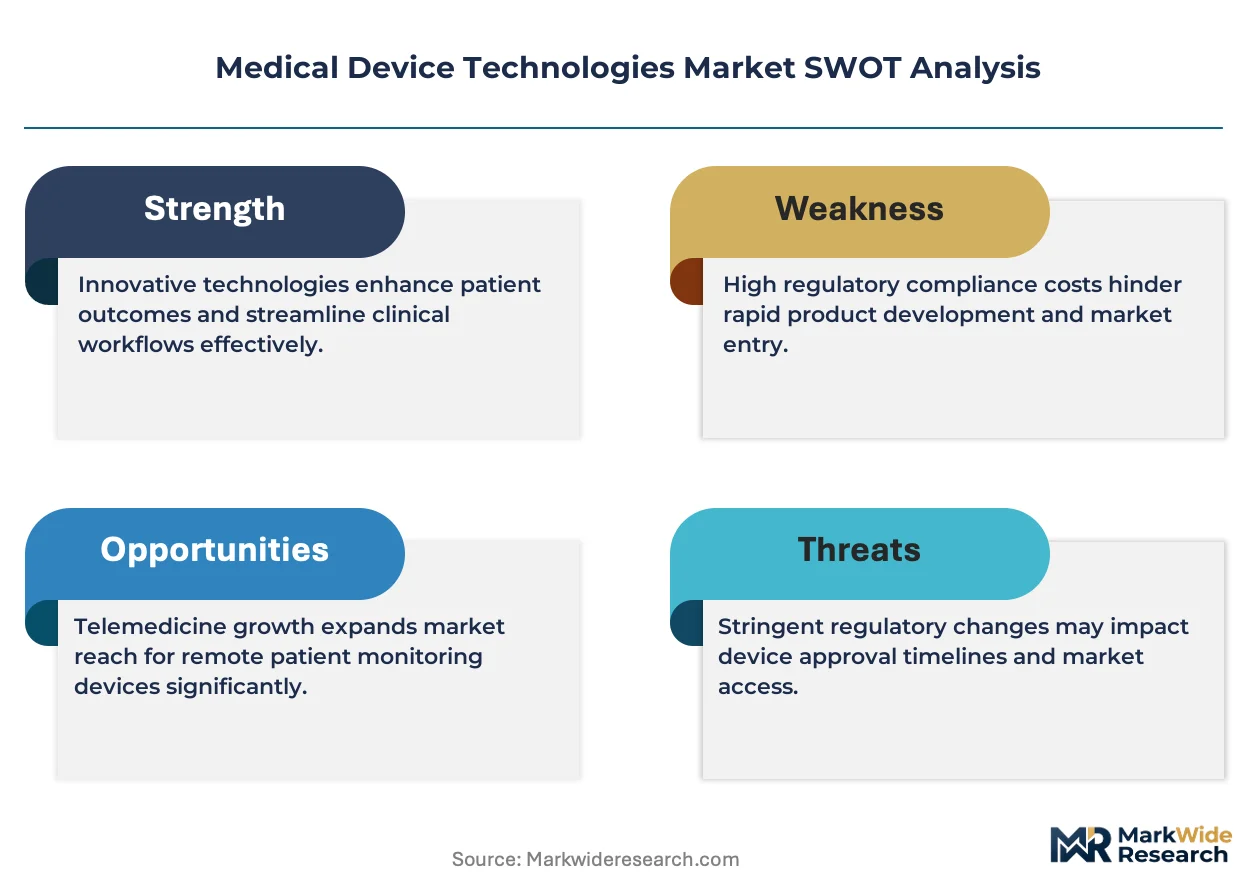
FDA premarket clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking multi-regional commercialization. Health Canada and Japan's PMDA impose additional conformity assessments that filter market participants by documentation depth and quality system maturity. Stakeholders must monitor evolving cybersecurity mandates and post-market surveillance obligations as regulators tighten accountability for connected device performance.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around full-service partnerships that bundle hardware, software, and continuous clinical support into multi-year agreements. This shift compresses traditional equipment sales cycles and elevates service revenue as the primary margin driver for manufacturers.
Growth Catalysts
- FDA Cybersecurity Premarket Guidance:The updated framework mandates threat modeling and software bill of materials for connected devices, accelerating hospital demand for hardened monitoring infrastructure that meets submission standards.
- EU Medical Device Regulation (MDR):Stricter clinical evidence requirements and post-market surveillance obligations are filtering out marginal competitors, creating volume concentration among established suppliers with robust quality systems.
- Remote Patient Monitoring Protocols:Cardiology and diabetes management programs in the United States are expanding reimbursement for continuous glucose monitors and wearable ECG patches, pulling sensor miniaturization investment.
Market Restraints
- Semiconductor Supply Concentration:Advanced imaging ASICs and FPGA components for MRI and CT systems source predominantly from Taiwan and South Korea foundries, exposing lead time volatility to geopolitical friction.
- Clinical Trial Cost Escalation:EU MDR's expanded patient follow-up requirements and PMCF studies extend time-to-revenue for Class III implants by 18-36 months, freezing R&D budgets.
- Reprocessing and Refurbishment:Third-party certified reprocessors of single-use devices capture hospital cost-saving mandates, compressing OEM recurring revenue from consumables.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives targeting domestic manufacturing of electronics and precision components attract contract manufacturers establishing catheter and stent production near Hyderabad and Bengaluru.
- AI-Enabled Diagnostic Workflows:Convergence of convolutional neural networks with point-of-care ultrasound is creating autonomous image interpretation for emergency departments lacking specialist coverage.
- Subscription Access Models:Mid-tier hospital networks in Germany are adopting per-scan pricing for MRI and CT platforms, replacing capital expenditure with operational budgets and expanding addressable facilities.
Industry Challenges
- Cybersecurity Talent Scarcity:Medical device manufacturers compete with fintech and defense sectors for embedded security engineers capable of implementing FDA-mandated secure boot and encryption protocols.
- Legacy System Interoperability:New connected monitoring platforms must integrate with hospital IT architectures running decades-old HL7 v2 interfaces, requiring costly middleware development and validation.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face capacity constraints at accredited laboratories, delaying regulatory submissions for novel polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Technologies Market |
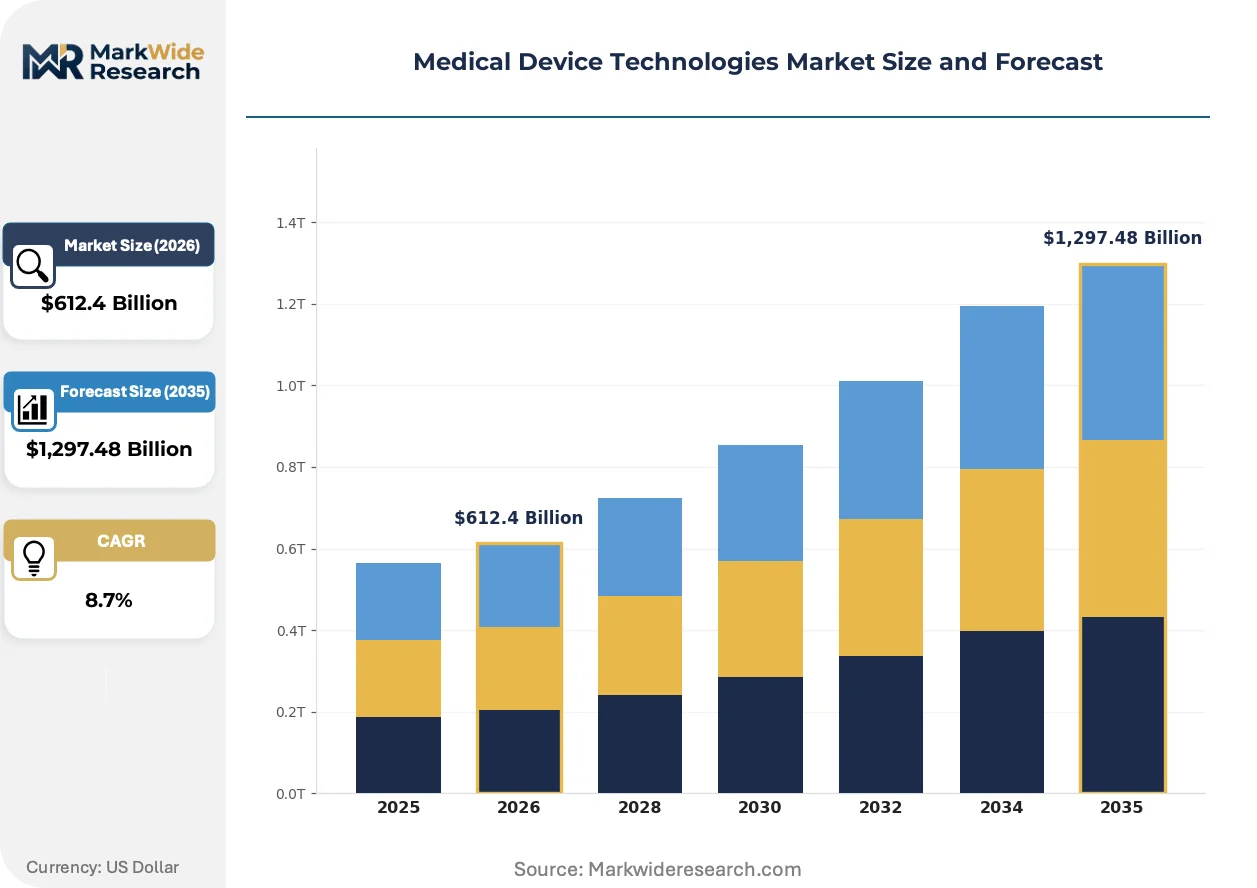
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Devices, Diagnostic Equipment, Surgical Instruments, Therapeutic Devices Application: Cardiology, Orthopedics, Neurology, Respiratory Technology: Wearable Technology, Telemedicine, Robotics, Imaging End User: Hospitals, Clinics, Home Care, Research Labs |
| Companies Covered | Medtronic, Johnson & Johnson MedTech, Abbott Laboratories, Siemens Healthineers, Stryker, GE Healthcare, Philips Healthcare, Boston Scientific, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Technologies Market Strategic Shifts
Computational capabilities embedded at the point of care are compressing diagnostic latency and enabling real-time clinical decision support without centralized IT infrastructure. These shifts are reconfiguring how medical device value is captured and delivered across acute and ambulatory settings.
Edge computing architectures are digitizing physiological signal processing directly within patient monitors and infusion pumps. Critical care units at academic medical centers in the United States are deploying these platforms to enable local anomaly detection and alarm prioritization. This architecture is digitizing the traditional central nursing station model by distributing intelligence to the bedside and reducing dependency on hospital network uptime.
The EU AI Act's risk classification system for medical device software is imposing conformity assessment requirements on diagnostic algorithms previously self-certified under MDR. Manufacturers must now maintain post-market monitoring systems and human oversight protocols for high-risk AI applications. Radiology AI tools for mammography screening face the steepest compliance burden, with several developers withdrawing from the European market rather than absorbing certification costs.
Hospital procurement departments are consolidating supplier relationships around outcome guarantees rather than equipment specifications. Health systems in the Netherlands and Denmark now contract for guaranteed uptime, image quality metrics, and clinical workflow integration rather than discrete hardware purchases. This restructuring is most visible in diagnostic imaging, where Philips and Siemens Healthineers compete on operational performance commitments rather than technical specifications alone.
Medical Device Technologies Market Segmentation
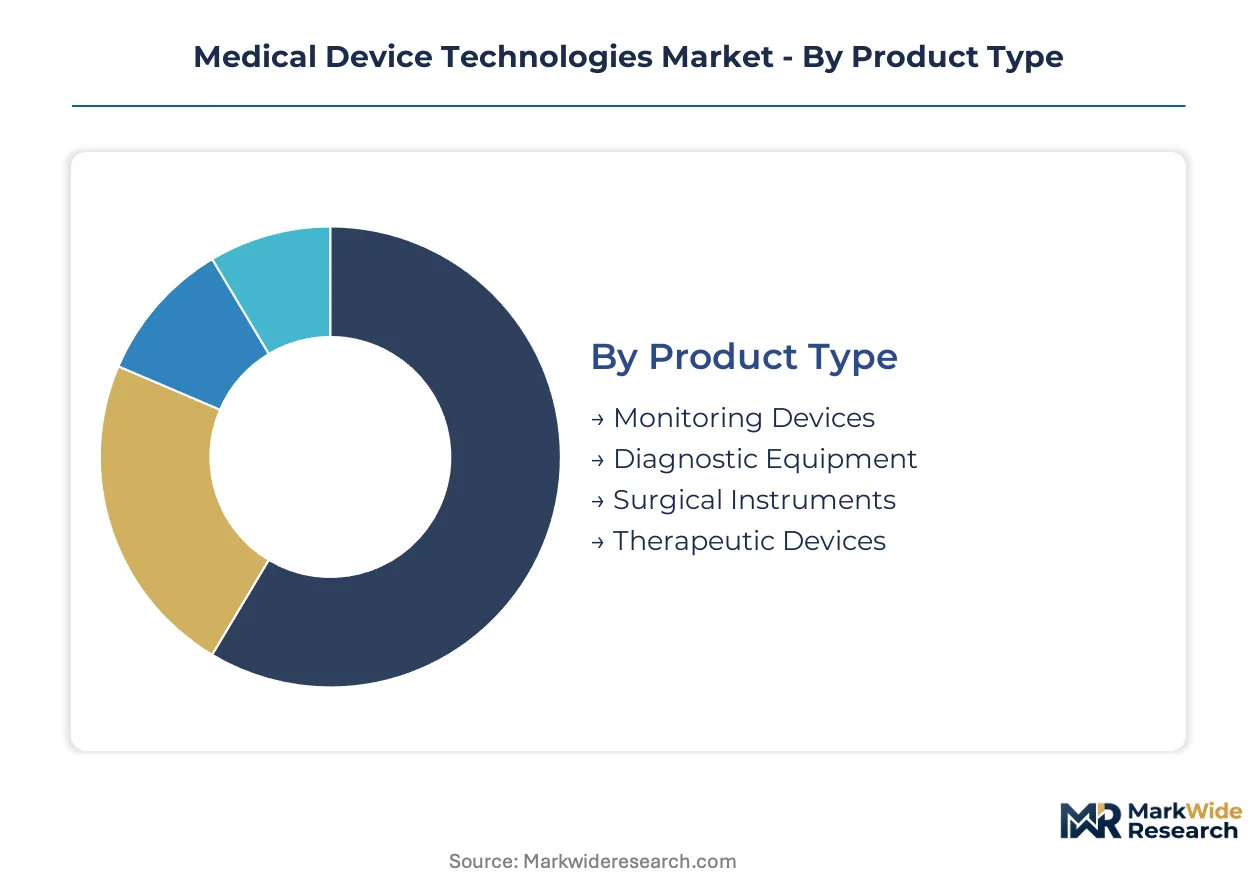
Segmentation reveals how capital allocation, regulatory exposure, and reimbursement pathways diverge across medical device categories. Hospital procurement teams weight lifecycle costs differently than home care distributors, while FDA clearance timelines vary substantially by technology modality.
Product Type:
Hospital capital budgets and reimbursement codes create distinct procurement rhythms across engineered instrument categories.
- Monitoring Devices:Continuous glucose monitors, pulse oximeters, and multi-parameter bedside systems integrate wireless telemetry for centralized nursing station oversight. Demand concentrates in United States academic medical centers deploying FDA-cleared remote patient monitoring protocols for chronic disease management, constrained by cybersecurity validation requirements for connected infrastructure.
- Diagnostic Equipment:MRI, CT, and ultrasound platforms embed computational reconstruction algorithms that compress scan times. Germany's precision manufacturing corridor sustains premium placement through bundled service contracts, though semiconductor lead times for imaging ASICs extend delivery schedules.
- Surgical Instruments:Electrosurgical units and laparoscopic toolsets serve procedural volume in high-throughput OR suites.
- Therapeutic Devices:Infusion pumps and dialysis equipment target chronic care protocols with recurring consumable revenue.
Established volume favors Diagnostic Equipment; emerging adoption favors Monitoring Devices.
Application:
Clinical evidence thresholds and specialist density shape addressable market depth across therapeutic domains.
- Cardiology:Wearable ECG patches and implantable loop recorders enable ambulatory arrhythmia detection without hospital admission. United States cardiology practices drive sensor miniaturization investment as CMS expands reimbursement for continuous cardiac monitoring in value-based care contracts.
- Orthopedics:Robotic surgical platforms and patient-specific implant guides improve alignment accuracy in joint replacement. Japan's aging demographic sustains volume concentration for hip and knee systems, constrained by PMDA clinical trial requirements for novel bearing surfaces.
- Neurology:Deep brain stimulation and intraoperative monitoring address movement disorders and epilepsy surgical planning.
- Respiratory:Ventilators and CPAP systems serve sleep apnea and COPD management with home care transition protocols.
Procedure volume anchors Orthopedics; reimbursement innovation is expanding fastest in Cardiology.
Technology:
Intellectual property density and regulatory novelty determine competitive moat durability across technology modalities.
- Wearable Technology:Skin-interfaced biosensors and ambulatory ECG patches stream physiological data to cloud analytics platforms. United States diabetes management programs pull continuous glucose monitor adoption fastest as payors recognize remote glycemic control outcomes.
- Robotics:Surgical platforms combine haptic feedback with proprietary instrumentation ecosystems that lock hospital customers into long-term service agreements. Da Vinci system density in United States research hospital clusters sustains premium pricing through training certification requirements.
- Telemedicine:Remote consultation platforms and digital stethoscopes extend specialist reach into underserved geographies.
- Imaging:AI-enhanced reconstruction algorithms reduce radiation dose while maintaining diagnostic confidence.
Hardware margins concentrate in Robotics; connected infrastructure is climbing the fastest in Wearable Technology.
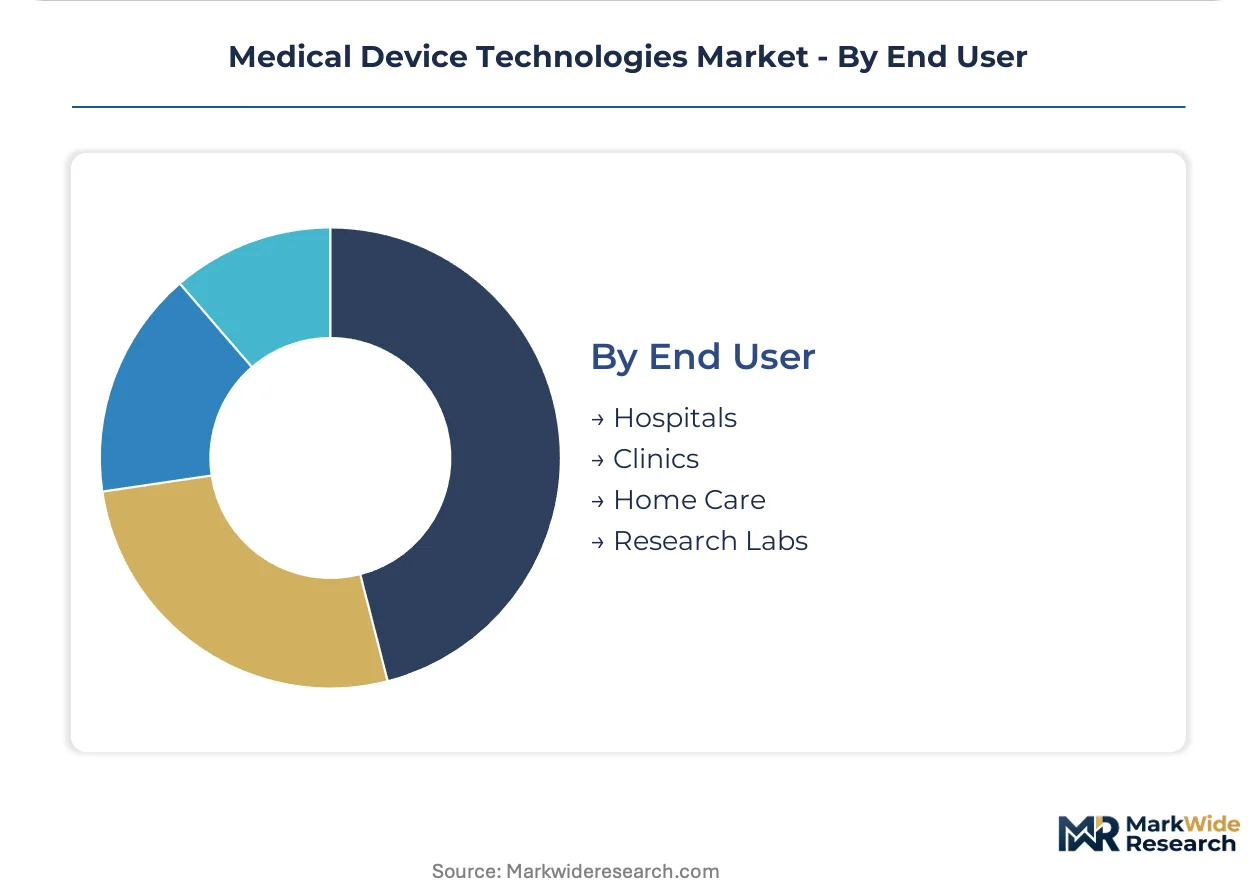
End User:
Purchasing authority and total cost of ownership calculations diverge sharply across care settings.
- Hospitals:Integrated delivery networks consolidate vendor relationships around multi-year full-service partnerships bundling hardware, software, and uptime guarantees. Germany's mid-tier hospital networks adopt per-scan pricing for MRI platforms, converting capital expenditure to operational budgets.
- Home Care:Portable oxygen concentrators and sleep therapy devices serve post-acute transition with insurance reimbursement dependency. United States durable medical equipment distributors face margin compression from competitive bidding programs.
- Clinics:Point-of-care ultrasound and rapid diagnostic instruments enable specialist-proximate testing without hospital referral.
- Research Labs:Preclinical imaging and biomarker detection platforms support pharmaceutical development partnerships.
Contract value peaks in Hospitals; patient volume is gaining share fastest in Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentives and updated regulatory frameworks are redirecting capital flows toward domestic manufacturing clusters and compliance-ready supply chains across major medical device markets.
United States
Academic medical centers in Boston and the Research Triangle are scaling procurement of connected monitoring systems for remote patient management. FDA's updated cybersecurity guidance for premarket submissions mandates threat modeling and software bill of materials, accelerating hospital demand for hardened infrastructure. The Minneapolis-St. Paul corridor sustains concentration of cardiac rhythm management and neuromodulation device headquarters.
Germany
Mid-tier hospital networks are adopting per-scan pricing models for MRI and CT platforms, converting capital expenditure to operational budgets. EU Medical Device Regulation enforcement filters marginal competitors through expanded clinical evidence requirements. The precision manufacturing corridor around Erlangen and Forchheim anchors diagnostic imaging production with bundled long-term service contracts.
China
Domestic manufacturers are capturing share in mid-tier imaging and patient monitoring equipment as NMPA accelerates review pathways for innovative devices. Provincial health commissions in Jiangsu and Guangdong are consolidating procurement around domestic suppliers for volume tenders. The Yangtze River Delta cluster concentrates contract manufacturing of precision components and disposable consumables.
India
Production-linked incentive schemes targeting electronics and precision components are attracting catheter and stent manufacturers near Hyderabad and Bengaluru. CDSCO is harmonizing medical device rules with global standards to streamline import substitution and export readiness. The medical technology manufacturing zone in Visakhapatnam is scaling domestic production of cardiac stents and orthopedic implants.
Japan
Aging demographics sustain volume concentration for joint replacement and cardiac rhythm devices despite reimbursement price compression. PMDA clinical trial requirements for novel bearing surfaces and biomaterials extend development timelines for orthopedic innovators. The Kobe and Osaka industrial zones maintain precision machining capabilities for surgical instrumentation and implantable device components.
Medical Device Technologies Market Competitive Environment
On the supply side, the industry is consolidating around full-service partnerships that bundle hardware, software, and clinical support into multi-year agreements. Tiered competitive positioning separates integrated conglomerates with captive financing arms from specialized technology developers and regional contract manufacturers. Dominant competitive moves include strategic partnerships for AI-enabled diagnostic workflows and geographic expansion through localized production incentives.
Among diversified health technology conglomerates, Medtronic, Johnson & Johnson MedTech, and Siemens Healthineers exemplify archetypes that anchor competitive dynamics. Medtronic represents the integrated financing-and-device model, leveraging captive capital placement to reduce hospital upfront expenditure. Johnson & Johnson MedTech occupies a position spanning surgical instrumentation and orthopedics with broad therapeutic reach. Siemens Healthineers anchors the diagnostic imaging tier through bundled hardware-service-upgrade contracts that lock in long-term revenue streams.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson MedTech |
| Abbott Laboratories |
| Siemens Healthineers |
| Stryker |
| GE Healthcare |
| Philips Healthcare |
| Boston Scientific |
| Becton Dickinson |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility amplifies price spreads between FDA-grade and CE-marked device tiers while compressing margins for manufacturers dependent on Taiwan-sourced imaging ASICs. Hospital procurement committees exploit this cost asymmetry to extract per-scan pricing concessions from diagnostic equipment vendors.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared and economy-grade devices, with ISO 13485 quality systems commanding substantial premiums over self-certified alternatives. Subscription-based access models for robotic surgical platforms and advanced imaging systems dominate hospital procurement, displacing capital expenditure structures. Price differentiation rests on bundled service contracts and proprietary training ecosystems rather than hardware specifications alone. Cost compression in mid-tier monitoring devices is intensifying because third-party reprocessors capture hospital mandates for single-use device refurbishment.
Supply Chain Analysis
Advanced imaging ASICs and FPGA components for MRI and CT systems draw predominantly from Taiwan and South Korea foundries, with precision polymer formulations sourcing from Germany and Switzerland. Biocompatibility testing capacity constraints at ISO 17025-accredited laboratories create bottlenecks for novel implant coatings. Single-source vulnerability in semiconductor lithography equipment exposes lead time volatility to geopolitical friction. Distribution runs through consolidated group purchasing organizations and integrated delivery networks rather than independent medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face substitution pressure from AI-enabled diagnostic workflows that bypass traditional hardware revenue models entirely. Defense requires locking hospital customers into outcome-guaranteed service ecosystems.
For Market Incumbents: Insulate recurring revenue streams by embedding proprietary training certifications and consumable lock-in within robotic surgical platforms. Capture backward integration into precision component manufacturing near Hyderabad and Bengaluru to offset semiconductor supply concentration. Defend against AI-native diagnostic developers by acquiring edge-computing sensor miniaturization capabilities. For New Entrants and Emerging Players: India's mid-tier hospital networks present the most penetrable geography for subscription-based imaging access models that convert capital expenditure to operational budgets. Target cardiology wearable ECG patches in United States value-based care contracts where CMS reimbursement innovation outpaces established sensor manufacturers. Pursue hospital system partnerships offering guaranteed uptime commitments rather than equipment specifications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates spinning non-core therapeutic device divisions under EU MDR compliance cost pressure. Long-term viability favors manufacturers with captive financing arms and installed base density in research hospital clusters. Monitor FDA cybersecurity premarket submission backlogs as signal for which connected device developers possess quality system maturity to absorb regulatory burden.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket threat modeling documentation accelerates hospital procurement of hardened connected monitoring infrastructure. |
| CE Marking Pathway | EU MDR clinical evidence requirements filter marginal competitors and concentrate volume among established suppliers. |
| Hospital System Partnership | Full-service agreements bundling hardware, software, and uptime guarantees displace transactional equipment sales. |
| Software Companion Development | AI-enabled diagnostic workflows for point-of-care ultrasound create autonomous interpretation capabilities. |
| Reimbursement Strategy | CMS recognition of remote patient monitoring outcomes pulls continuous glucose monitor adoption in diabetes management. |
Study Parameters
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs directors anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR notified body decisions, CMS reimbursement code updates, and hospital procurement database trends. Bottom-up unit economics triangulated against top-down macro health expenditure flows.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product type, application, technology modality, and end-user setting. CAGRs derived from weighted average of historical trajectory and forward-looking regulatory impact assessment. Forecast inputs incorporated semiconductor lead time volatility and biocompatibility testing capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native diagnostic developers or contract manufacturers exploiting India's PLI scheme would shift outcomes. Cross-checking against hospital capital expenditure surveys and GPO contract renewal rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Oxygen Generator Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Hormonal Implants Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Medical Coatings Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Flow Diverters Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market