
 Global Dental Laboratory Welders Market | 2026-2036
Global Dental Laboratory Welders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Laboratory Welders Market Intelligence
The rising complexity in implantology and prosthodontics is recalibrating market focus away from traditional orthodontic repairs. This shift favors equipment capable of handling advanced materials and intricate designs. LaserStar leverages its expertise in high-precision fiber laser systems for fabricating titanium frameworks. Sunstone Engineering LLC specializes in micro-welding solutions tailored for smaller dental labs. ElettroLaser differentiates through its compact, user-friendly benchtop laser welders that are popular across European workshops.
Dental laboratory welders are precision instruments designed to join and repair metal components in dental restorations. These devices utilize a focused energy source, such as a laser beam or plasma arc, to create strong, non-porous welds on alloys like titanium and cobalt-chrome. Among product types, laser welders command the premium segment due to their superior precision and minimal heat-affected zones. Application-wise, demand from prosthodontics and implantology for creating complex frameworks drives higher-value sales than routine orthodontic repairs.
Regulatory frameworks, including the EU's Medical Device Regulation (MDR) and FDA guidelines in the United States, impose strict quality and traceability standards on custom dental prosthetics. Compliance with ISO 13485 for medical device quality management systems is also critical for market access in many jurisdictions. Navigating the evolving landscape of biocompatible materials while maintaining welding precision and affordability remains the central challenge for equipment manufacturers.
Market Dynamics
The primary structural force is the pivot in dental manufacturing toward complex prosthetics made from biocompatible alloys. This shift elevates the need for welding systems that deliver superior precision and control over heat-affected zones, displacing older, less precise techniques.
Growth Catalysts
- Regulatory Mandates:The EU's Medical Device Regulation (MDR) necessitates higher quality standards for custom devices, pushing labs towards welders that can precisely handle certified biocompatible alloys.
- Prosthodontic Complexity:Expanding implantology applications in countries like Germany require strong, passive-fitting frameworks for bridges and bars, a task well-suited for advanced laser welding.
- Advanced Material Adoption:The shift to welding titanium and cobalt-chrome enables lighter, more biocompatible restorations than traditional casting, driving demand for specialized equipment.
Market Restraints
- High Capital Outlay:The significant upfront cost of premium laser welders is a major financial barrier for smaller dental laboratories, restricting market penetration.
- Technician Skill Gap:A scarcity of technicians trained to operate advanced welding systems and associated digital design software creates an operational bottleneck for labs.
- CAD/CAM Milling Competition:The ability of 5-axis milling machines to produce monolithic zirconia restorations provides a non-welded alternative, posing a substitution threat.
Strategic Opportunities
- Emerging Market Entry:Dental sectors in countries like Brazil and Mexico are modernizing, creating new demand for mid-tier welding systems as labs upgrade from manual casting.
- New Material Applications:Developing specialized welders for novel materials like PEEK-based composites for removable prosthetics opens a new application frontier.
- Subscription-Based Models:Offering welders through leasing arrangements can lower the adoption barrier for smaller labs, unlocking a previously inaccessible customer segment.
Industry Challenges
- Digital Workflow Integration:A key challenge is ensuring new welders integrate seamlessly with the fragmented ecosystem of third-party CAD software and scanners used by labs.
- Regulatory Compliance Burden:Maintaining compliance with evolving international standards, like FDA rules and the EU's MDR, demands significant ongoing investment in quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Laboratory Welders Market |
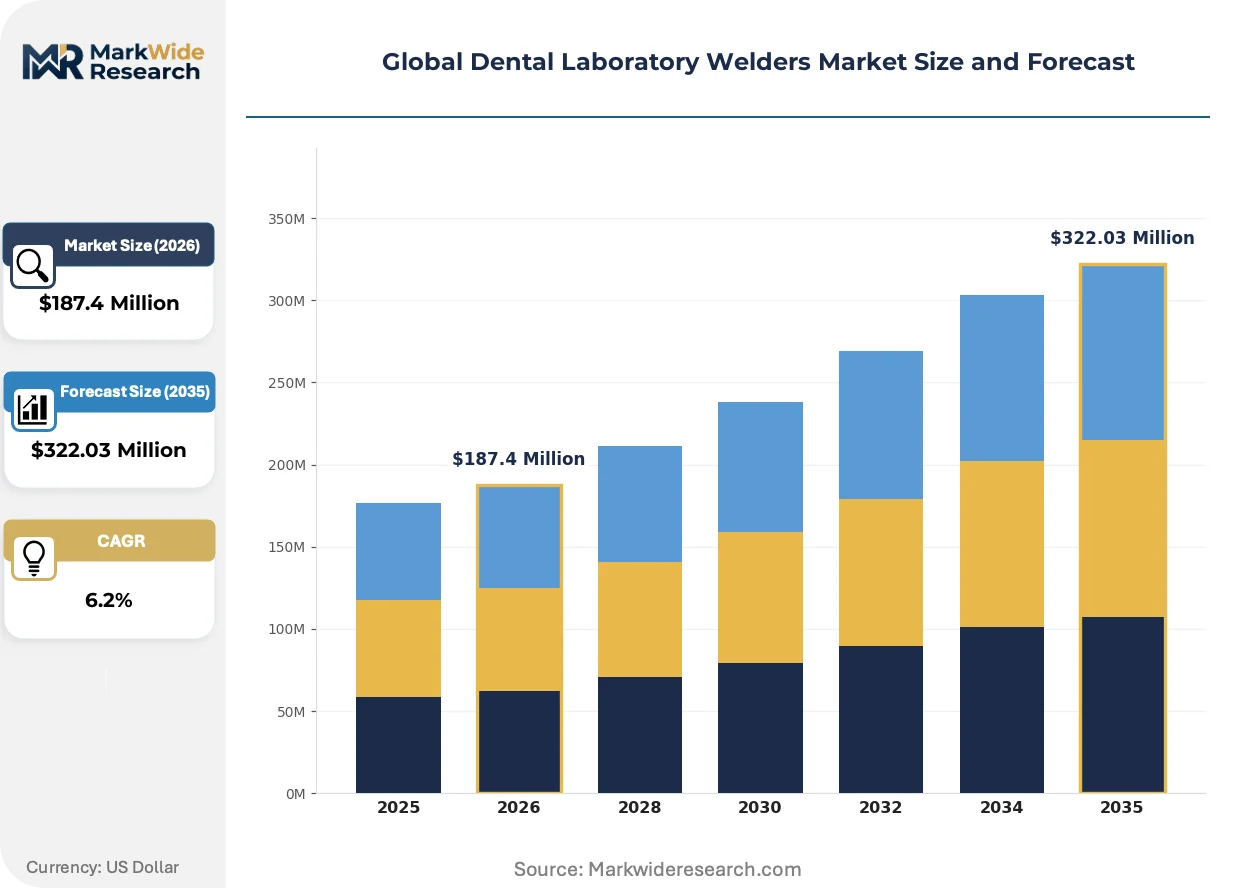
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $322.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Welders, TIG Welders, Resistance Welders, Ultrasonic Welders Technology: Fiber Laser, CO2 Laser, Microplasma, Plasma Arc, Torch-based Application: Orthodontics, Prosthodontics, Implantology, Maxillofacial Reconstruction End User: Dental Labs, Prosthetic Fabricators, Orthodontic Clinics, Specialty Workshops |
| Companies Covered | LaserStar, Sunstone Engineering LLC, IPG Photonics, Primotec, Max Photonics, ElettroLaser, Alpha Laser, Orion, Micro Precision Welding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Laboratory Welders Market Strategic Shifts & Innovations
Automation and digital integration are fundamentally altering the dental laboratory landscape. This evolution prioritizes equipment that enhances precision, ensures regulatory compliance, and fits within a complete digital workflow from patient scan to final restoration.
Compact fiber laser welders provide high-precision joining capabilities in a small benchtop format. Smaller dental laboratories are rapidly adopting these systems to bring advanced fabrication in-house. This trend is decentralizing complex prosthetic manufacturing, moving it from large production centers to local workshops.
The global enforcement of the ISO 13485 quality management standard is becoming a critical market access requirement. The standard mandates complete traceability for all materials and processes used in manufacturing custom medical devices. Welding equipment manufacturers are responding by embedding data logging and process validation features into their systems.
Dental laboratories now prioritize equipment that functions within a complete digital workflow, from intraoral scan to final prosthetic. This preference disrupts the standalone hardware purchase model in favor of vendors offering open-architecture systems compatible with leading CAD software. This shift is most prominent in North American and European markets.
Global Dental Laboratory Welders Market Segmentation
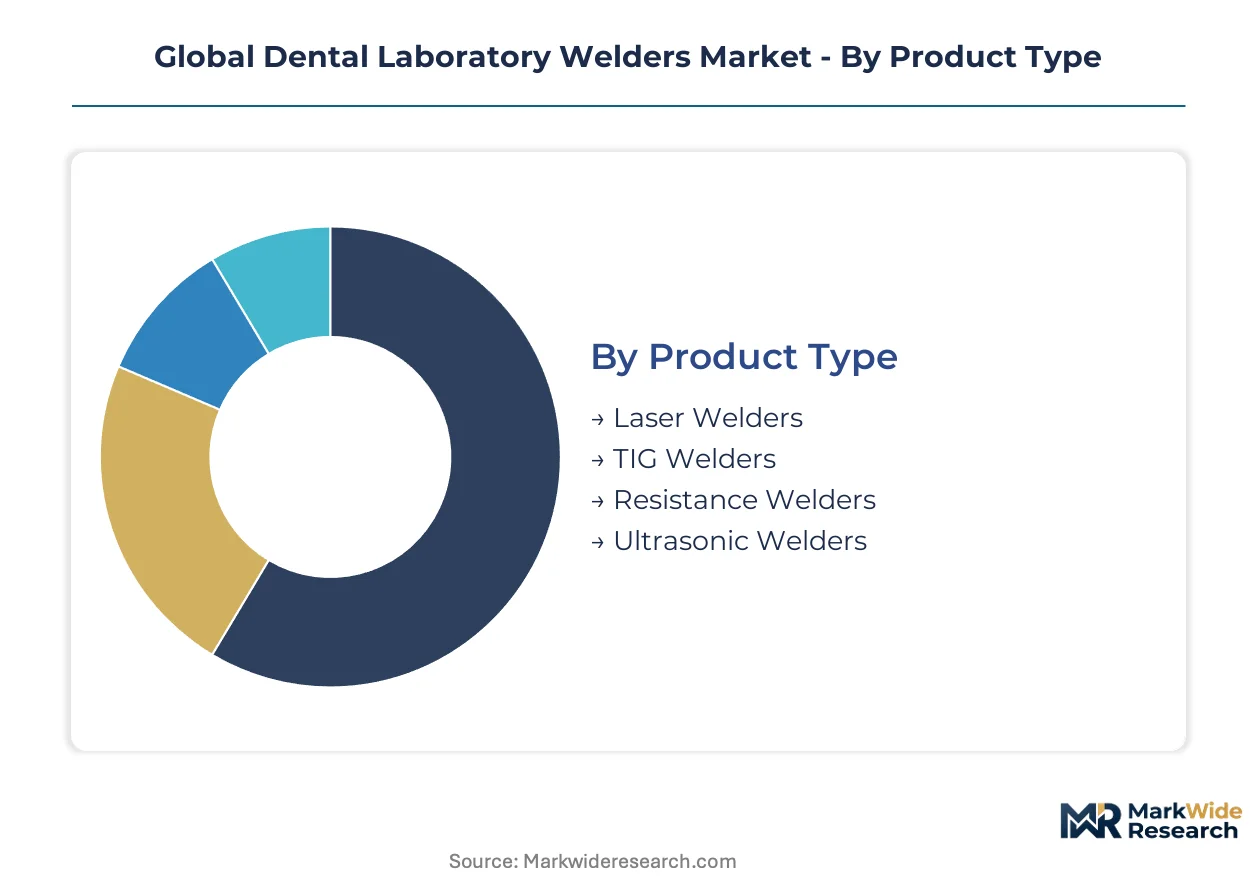
Understanding the distinct segments within the global dental laboratory welders market reveals the varied technological demands and end-user requirements. This granular view helps manufacturers tailor product development and market strategies to specific niches. Each segment reflects unique operational needs, material compatibility, and regulatory considerations.
Product Type:
Compliance with medical device regulations like the EU's MDR heavily influences the choice of product type, with certified systems essential for market access.
- Laser Welders:These instruments use a focused laser beam to create precise, low heat-affected zone welds, ideal for intricate dental frameworks. Demand is concentrating in Germany and Switzerland, driven by stringent quality standards for titanium and cobalt-chrome prosthetics.
- TIG Welders:Utilizing a non-consumable tungsten electrode, TIG welders offer strong, ductile welds suitable for various dental alloys. Adoption is strong in developing markets like Brazil, where their versatility and lower initial cost appeal to upgrading labs.
- Resistance Welders:These welders join metals by passing a strong current through the components, creating heat at the contact points.
- Ultrasonic Welders:Employing high-frequency acoustic vibrations, ultrasonic welders are used for joining certain non-ferrous metals and plastics in specific dental applications.
Laser Welders sits at the top of the volume ranking, with Ultrasonic Welders climbing the fastest.
Technology:
The cost tier of welding technology directly correlates with the precision and material handling capabilities required by dental labs.
- Fiber Laser:These systems deliver high-power, high-precision laser beams through optical fibers, enabling fine welds on complex geometries. Their adoption is significant in North America, where demand for advanced implantology solutions drives investment in premium equipment.
- Microplasma:Microplasma welding provides a stable, concentrated arc for micro-joining applications, particularly suitable for delicate dental components. Smaller dental labs in Italy and Spain are increasingly adopting microplasma solutions for in-house fabrication due to their efficiency.
- CO2 Laser:CO2 lasers offer a versatile welding solution for various metals, though typically with a larger spot size than fiber lasers.
- Plasma Arc:Plasma arc welding uses an ionized gas stream to create a highly focused heat source, offering deep penetration and high-quality welds.
- Torch-based:Traditional torch-based welding involves using a flame to melt and join metal parts, a technique still employed for certain repairs and less critical applications.
Precision-focused technologies like Fiber Laser command premium pricing, while traditional torch-based methods serve cost-sensitive segments.
Application:
Application segments are differentiated by the complexity of the restoration and the required precision of the weld, impacting equipment choice.
- Prosthodontics:This segment involves fabricating complex dental prostheses like bridges, crowns, and dentures, requiring high-precision welding for framework integrity. The need for strong, biocompatible frameworks for multi-unit prostheses drives demand in countries with aging populations, such as Japan.
- Implantology:Welding in implantology focuses on creating passive-fitting frameworks for dental implants, where precise fit is crucial for long-term success. Expanding implant procedures in the United States necessitate advanced welding capabilities for titanium and cobalt-chrome structures.
- Orthodontics:Orthodontic applications primarily involve repairing and fabricating wires and bands, generally requiring less intricate welding than prosthetics.
- Maxillofacial Reconstruction:This specialized application involves welding components for reconstructive surgeries, demanding exceptionally high precision and material compatibility.
Demand for intricate frameworks in implantology drives technological advancement, while orthodontic repairs remain a stable, high-volume segment.
End User:
End-user segmentation highlights the varying operational scales and specialization levels among dental fabrication entities.
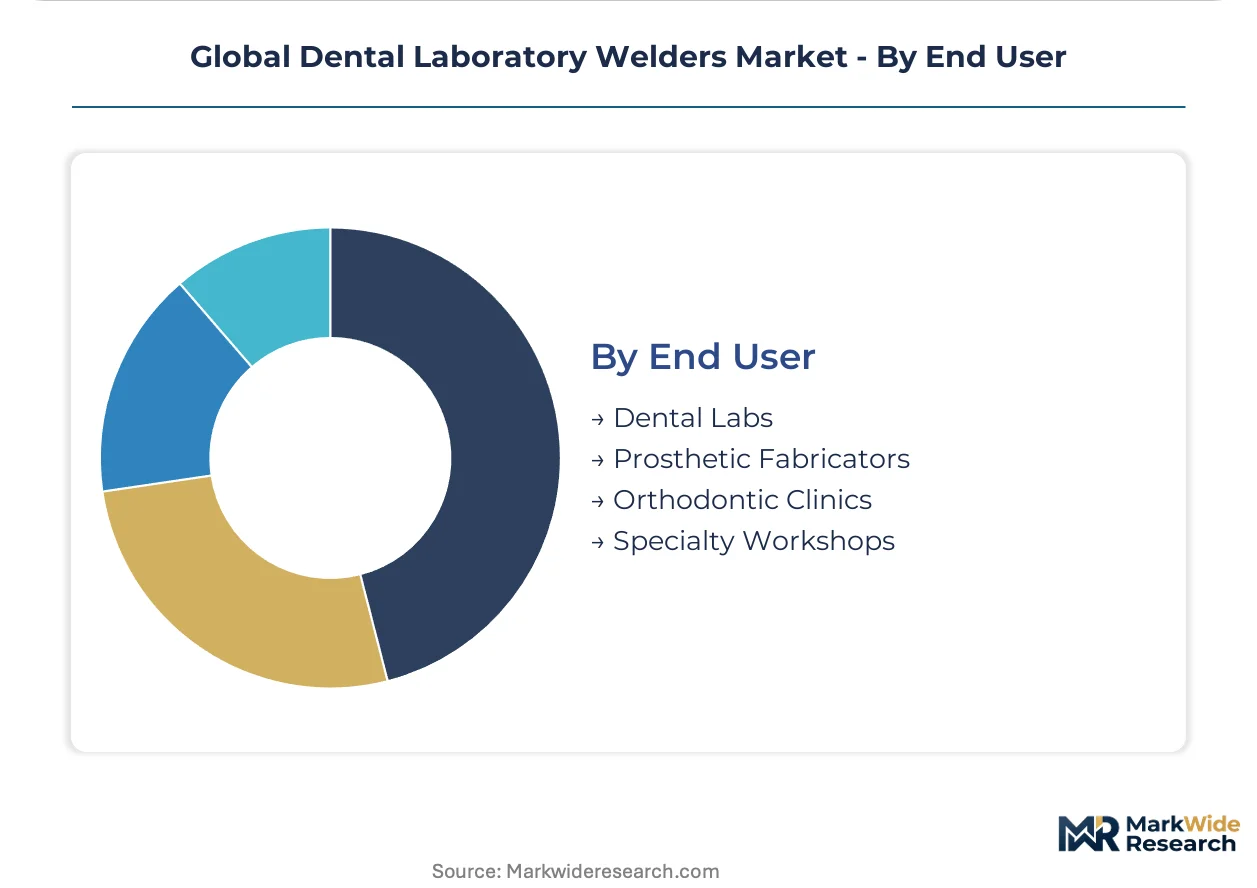
- Dental Labs:These facilities produce a wide range of dental restorations, from simple crowns to complex implant frameworks, requiring versatile welding equipment. Large commercial dental laboratories in Canada are investing in automated welding systems to enhance throughput and precision.
- Prosthetic Fabricators:Specialized fabricators focus exclusively on producing dental prosthetics, often at a high volume, necessitating robust and efficient welding solutions. These fabricators in the UK prioritize welders capable of handling diverse biocompatible alloys for custom devices.
- Orthodontic Clinics:These clinics primarily focus on orthodontic treatments and may use welders for in-house adjustments or repairs of orthodontic appliances.
- Specialty Workshops:These workshops cater to niche dental fabrication needs, often requiring customized welding solutions for unique materials or designs.
Large dental labs and specialized prosthetic fabricators represent the primary purchasing power, with smaller clinics adopting compact solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's strong dental technology sector drives demand for advanced dental laboratory welders. This sector focuses on high-precision equipment for complex prosthodontics and implantology. The market expands as dental labs upgrade from traditional casting methods.
Germany
Expanding implantology applications and stringent quality standards for titanium and cobalt-chrome prosthetics drive demand in Germany. The EU's Medical Device Regulation (MDR) necessitates higher quality standards for custom devices. The industrial region around Stuttgart focuses on developing and adopting advanced laser welding technologies for dental fabrication.
United States
United States' expanding implant procedures and demand for advanced implantology solutions necessitate precise welding capabilities. FDA guidelines impose strict quality and traceability standards on custom dental prosthetics. Dental technology hubs in California are investing in premium fiber laser systems for precision framework fabrication.
Japan
Japan's aging population creates significant demand for strong, biocompatible frameworks for multi-unit prostheses. PMDA regulations ensure the safety and efficacy of medical devices, including sophisticated dental welders. The Osaka region sees significant research into new material applications for advanced dental restorations.
Brazil
Brazil's modernizing dental sectors are upgrading from manual casting to more advanced mid-tier welding systems. ANVISA guidelines govern medical device approval and quality control for dental equipment. Dental manufacturing facilities in São Paulo are adopting TIG welders for their versatility and lower initial cost.
Canada
Canadian large commercial dental laboratories require enhanced throughput and precision for various restorations. Health Canada regulates medical devices, requiring compliance for all dental welding equipment. Major dental laboratory networks in Ontario are investing in automated welding systems to improve efficiency and consistency.
Global Dental Laboratory Welders Market Key Industry Players
Technology specialization dominates the current landscape, with manufacturers focusing on distinct niches. The market exhibits a tiered structure, ranging from high-precision laser systems to more cost-effective micro-welding solutions. Key archetypes include premium laser system providers, compact benchtop specialists, and versatile TIG welder suppliers for developing markets. Companies are pursuing portfolio diversification into new material applications and geographic expansion into modernizing dental sectors to capture new customer segments.
Specialists in high-precision laser systems, such as LaserStar, exemplify the premium segment focusing on complex titanium frameworks and advanced material handling. Sunstone Engineering LLC occupies a position among micro-welding solution providers, catering to smaller dental laboratories needing tailored equipment for intricate repairs. ElettroLaser, a European-based company, anchors the compact, user-friendly benchtop laser welder segment, popular across European workshops for its accessibility and efficient design. These companies represent distinct segments of the market, each addressing specific operational needs and material compatibility requirements within the dental fabrication industry.
| Leading Market Players |
|---|
| LaserStar |
| Sunstone Engineering LLC |
| IPG Photonics |
| Primotec |
| Max Photonics |
| ElettroLaser |
| Alpha Laser |
| Orion |
| Micro Precision Welding |
| Others |
Cost & Logistics Intelligence
Global titanium commodity prices and cobalt-chrome alloy benchmarks cascade through the dental laboratory welders' supply chain, directly influencing equipment manufacturing costs and subsequent pricing tiers for end-users.
Pricing Analysis
Input-cost pass-through significantly impacts the final price of dental welding systems, particularly for premium laser welders utilizing specialized optical components. The dominant pricing structure involves tiered premium-mid-economy pricing differentiation, reflecting technological sophistication and brand reputation. Price differentiation drivers include the quality grade of laser components, ISO 13485 certification levels, and comprehensive after-sales service packages. Pricing pressure stems from the increasing viability of CAD/CAM milling as an alternative, particularly for zirconia restorations. Smaller dental laboratories exhibit the highest price sensitivity, often opting for more cost-effective TIG welders or microplasma solutions, while large commercial labs prioritize precision and compliance.
Supply Chain Analysis
Certification and qualification gating profoundly affect the dental welder supply chain, with ISO 13485 compliance and regional medical device regulations dictating component sourcing. Geographic supply concentration for high-precision laser diodes and optical components centers in Germany and the United States, while more cost-effective electronic assemblies originate from China. The supply chain depends on specialized optics, high-power laser diodes, and biocompatible metal alloys for system integration. Single-source vulnerability for these high-precision components represents a significant structural risk. Distribution runs through a combination of direct sales by manufacturers and specialized dental equipment distributors serving regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the dental industry's pivot towards high-value, complex prosthodontics requiring premium laser welding systems.
For Market Incumbents:
Deepen R&D investments into advanced material applications, specifically developing welders compatible with novel PEEK-based composites and complex titanium alloys. Integrate seamlessly with fragmented digital workflows, ensuring open-architecture compatibility with leading CAD software to counter the threat from monolithic CAD/CAM milling. Expand manufacturing capacity for critical high-precision components in regions like Germany to secure supply. Invest in robust data logging and process validation features to meet evolving ISO 13485 and EU MDR traceability requirements.
For New Entrants and Emerging Players:
A price-point gap exists between premium laser systems and traditional welding methods, creating an opportunity for mid-tier solutions. Target underserved emerging markets like Brazil and Mexico, where dental labs are upgrading from manual casting techniques. Focus on developing compact, user-friendly benchtop systems with strong local support infrastructure. Implement subscription-based models or leasing arrangements to lower the adoption barrier for smaller dental laboratories seeking to bring advanced fabrication in-house.
For Investors and Strategic Acquirers:
Consolidation pressure builds where specialized technological capabilities align with stringent regulatory demands. The long-term viability of this market remains strong, fueled by global aging populations and increasing demand for complex implantology. Identify acquisition targets that possess niche expertise in micro-welding solutions, compact fiber laser systems, or strong regional distribution networks in key growth areas. A critical signal to watch is the increasing enforcement of medical device traceability regulations, favoring companies with embedded compliance features.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop welders for PEEK-based composites | This extends application scope into removable prosthetics, capturing new demand segments. |
| Integrate with leading CAD software platforms | This ensures seamless digital workflow compatibility, enhancing market adoption for dental labs. |
| Expand subscription-based models in Brazil | This lowers capital outlay barriers, unlocking access to modernizing dental sectors. |
| Acquire specialized micro-welding solution providers | This strengthens portfolio in intricate repair and small-scale fabrication, diversifying offerings. |
| Enhance data logging for ISO 13485 compliance | This ensures critical market access and addresses traceability mandates for custom devices. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a comprehensive market view. Primary interviews engaged dental lab owners, equipment engineers, prosthodontists, and regulatory experts. Secondary data sources included medical device regulations (EU MDR, FDA guidelines), industry association reports, patent databases, and relevant company financial filings. The market size and forecast were derived through a rigorous bottom-up and top-down triangulation approach.
Historical market data was cross-referenced against expert panel input to project market trends across the analysis window. The analytical framework modeled key segmentation dimensions including product type, technology, application, end-user, and geographic region. Compound Annual Growth Rates (CAGRs) were derived from a blend of historical performance and projected industry shifts. Key industry-specific forecast inputs included dental implant procedure volumes and global regulatory compliance rates for medical devices.
Caveats apply where evolving material science, changes in medical device regulations, or significant economic shifts could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. A model refresh is warranted upon material change in global dental care spending patterns or regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Digital Facebow Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Air Polishers Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Chile Dental Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Plaque Disclosing Aids Market