
 Pain Relievers for Teeth Market | 2026-2036
Pain Relievers for Teeth Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Relievers for Teeth Market Insights
Dental clinic procurement of non-systemic pain solutions is expanding as practitioners seek to reduce opioid exposure following extractions and root canals. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf presence across retail pharmacy channels. Bayer anchors its position through topical analgesic formulations that bypass gastrointestinal absorption concerns. GSK competes in the pediatric segment with flavor-modified liquid formulations designed for compliance.
Pain relievers for teeth encompass pharmacological agents formulated to interrupt nociceptive signaling from dental pulp, periodontal tissue, or alveolar bone, typically achieving therapeutic effect through cyclooxygenase inhibition, sodium channel blockade, or counterirritant mechanisms at concentrations calibrated for oral mucosa safety. These products serve both acute post-procedural management and chronic conditions such as irreversible pulpitis or periapical abscess. Non-steroidal anti-inflammatory drugs occupy the largest margin pool due to prescription-tier pricing and established efficacy in inflammatory dental pain, while topical analgesics represent the fastest-growing category as clinicians prioritize localized delivery to minimize systemic exposure. The tablet formulation segment remains mature with stable demand, whereas gel and oral rinse formats are gaining share in dental clinic settings where immediate site-specific application is clinically preferred.
The FDA regulates active ingredient concentrations and labeling claims for over-the-counter oral pain products, directly constraining formulation innovation and marketing language available to manufacturers. The EPA oversees environmental discharge from pharmaceutical manufacturing facilities, raising compliance costs for domestic production of active pharmaceutical ingredients. ISO 13485 quality management standards govern contract manufacturers supplying dental-specific topical devices, creating a certification barrier for new entrants. Stakeholders must monitor evolving FDA guidance on combination analgesic safety and determine whether to invest in novel delivery mechanism R&D or defend existing formulation positions through bioequivalence studies.
Market Dynamics
FDA labeling restrictions on over-the-counter oral analgesics are compressing formulation flexibility while dental clinics accelerate procurement of non-systemic alternatives to limit opioid exposure in post-operative protocols.
Growth Catalysts
- Post-procedural pain protocols:Dental clinics in the United States are expanding topical analgesic procurement to manage extraction and root canal recovery without systemic drug exposure.
- ISO 13485 certification expansion:Contract manufacturers achieving dental-specific quality standards are unlocking supply contracts with clinic networks seeking audited topical device suppliers.
- EPA discharge compliance investments:Domestic API producers upgrading environmental controls are securing preferred supplier status with retailers prioritizing verified supply chain documentation.
Market Restraints
- Active ingredient concentration ceilings:FDA caps on benzocaine and lidocaine formulations limit efficacy differentiation for over-the-counter topical products.
- Pediatric formulation toxicity thresholds:EMA safety reviews of methemoglobinemia risk in infant teething gels have triggered voluntary withdrawals across European pharmacy chains.
- Excipient supply concentration:Carbomer and poloxamer production clusters in China create vulnerability for gel-based topical manufacturers dependent on imported rheology modifiers.
Strategic Opportunities
- Flavor-modified liquid compliance:Pediatric formulation specialists can capture share by engineering palatability profiles that reduce administration refusal rates in children aged 2-6.
- India pharmacy retail expansion:Organized pharmacy chains in tier-2 and tier-3 cities present underpenetrated distribution channels for topical dental analgesics currently concentrated in metro hospitals.
- Dual carbon alignment:China's NMPA is accelerating reviews for manufacturers demonstrating renewable energy integration in API synthesis, creating regulatory preference for low-carbon topical production.
Industry Challenges
- Bioequivalence study timelines:Generic topical entrants face 18-24 month FDA validation periods for demonstrating comparable absorption kinetics to reference listed drugs.
- Multinational formulation registration:Divergent concentration limits across Health Canada, TGA, and MFDS jurisdictions force SKU proliferation and complicate inventory planning for global OTC portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Relievers for Teeth Market |
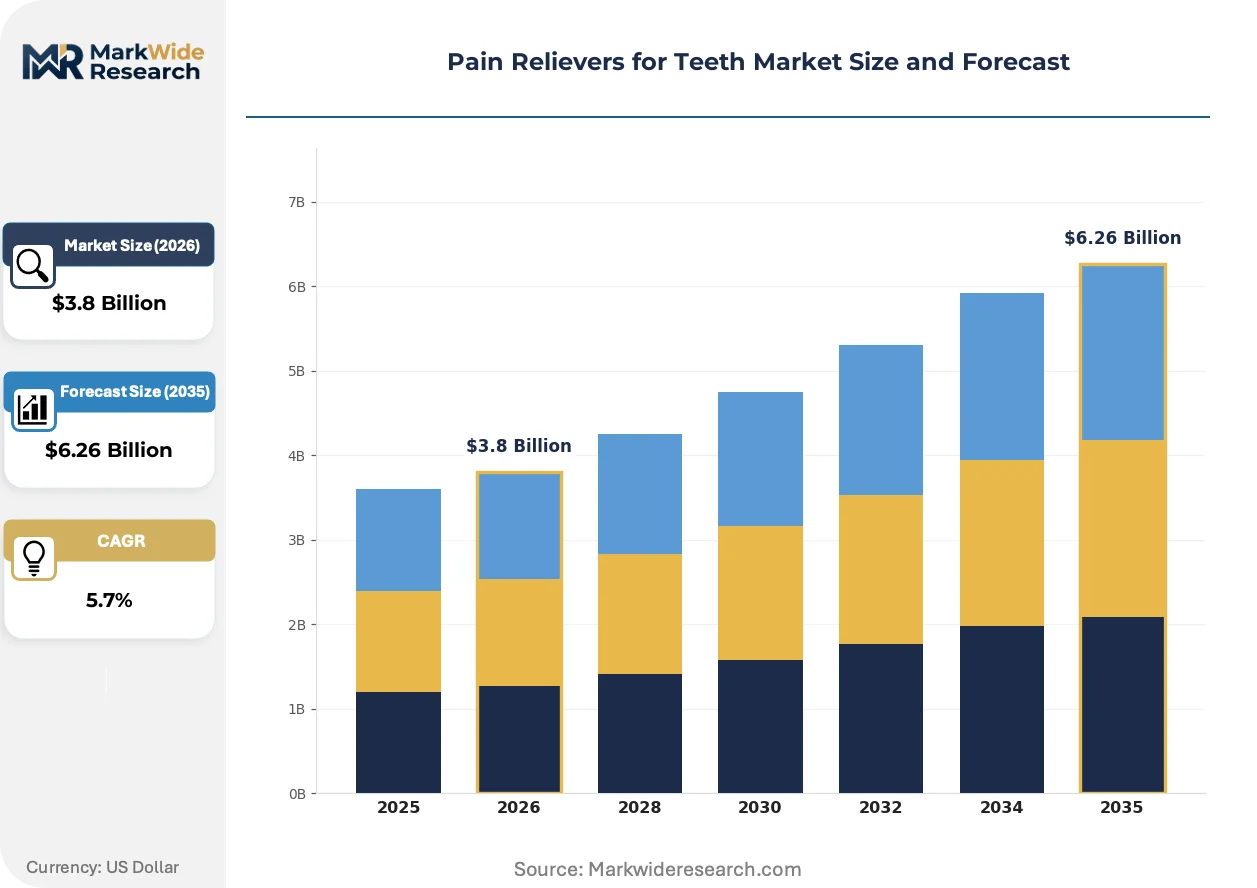
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-steroidal Anti-inflammatory Drugs, Acetaminophen, Aspirin, Topical Analgesics End User: Adults, Pediatrics, Elderly, Dental Clinics Formulation: Tablets, Liquid, Gel, Oral Rinse Administration Route: Oral, Topical, Intravenous, Sublingual |
| Companies Covered | Merck, Bayer, Johnson & Johnson, GSK, 3M, Sunstar, Colgate-Palmolive, Septodont, Bausch Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Relievers for Teeth Market Trends and Innovations
Localized drug delivery mechanisms are displacing systemic absorption models as the dominant innovation vector, with mucoadhesive polymers and nanoemulsion carriers reshaping how active ingredients reach dental pulp and periodontal tissue.
Nanoemulsion carrier systems are integrating lipophilic active compounds into aqueous bases at sub-micron scale, enabling transmucosal penetration without alcohol irritation. Dental clinic procurement teams are prioritizing these formulations for immediate post-extraction application. The technology is integrating site-specific delivery into standard-of-care protocols previously reliant on systemic NSAIDs.
REACH restrictions on persistent organic pollutants are forcing reformulation of solvent-based oral rinses across EU manufacturing facilities. The regulation is compressing timelines for alternative preservative validation. Pediatric liquid segments are absorbing the highest compliance costs as manufacturers replace paraben systems with novel biostatic compounds.
Direct-to-clinic distribution platforms are compressing traditional wholesale pharmacy margins by enabling dental practices to order topical analgesics through specialized procurement portals. United States multi-location dental service organizations are consolidating purchasing through these channels. The shift is most visible in Sun Belt metropolitan areas where DSO concentration exceeds 40 percent of clinic establishments.
Pain Relievers for Teeth Market Segmentation
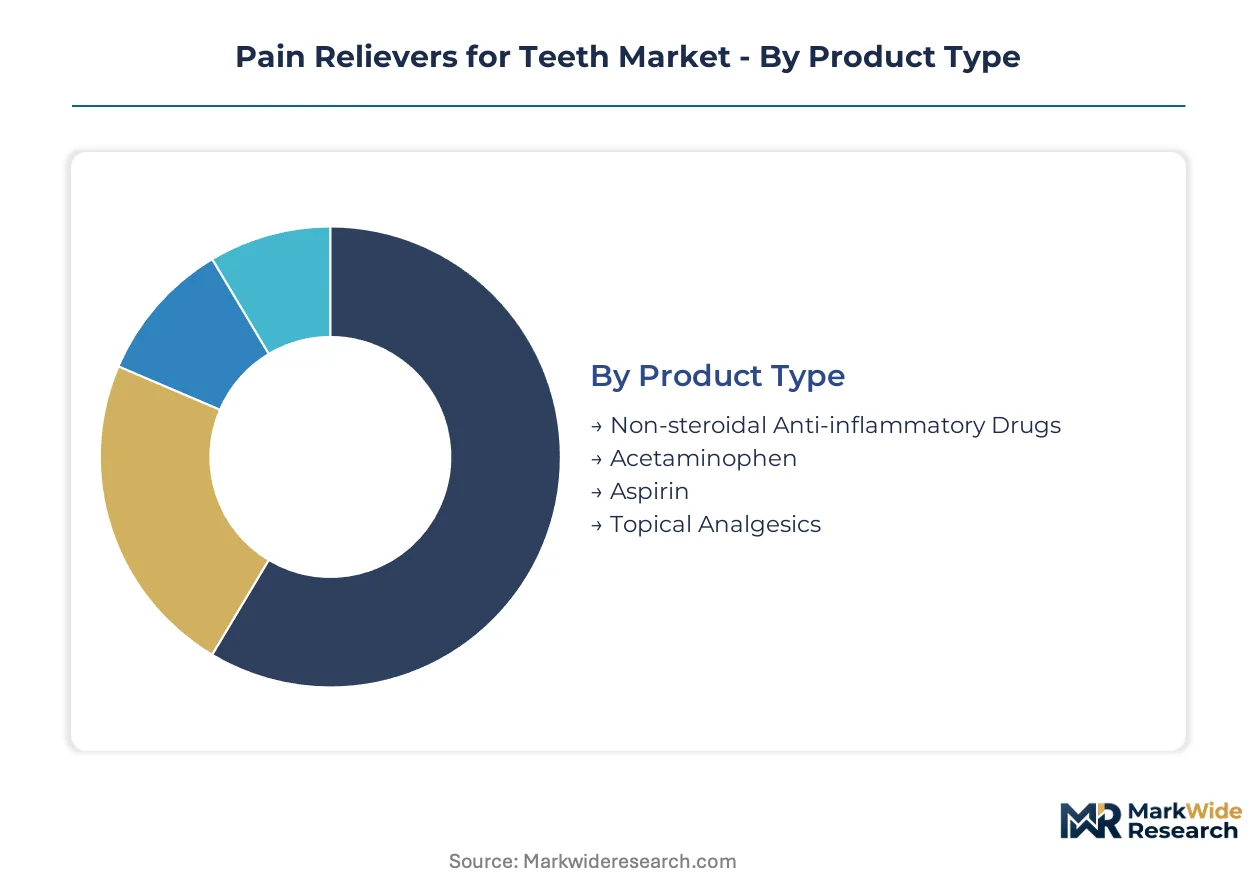
Segmentation in dental pain management reveals how formulation choices and patient demographics reshape procurement patterns. Manufacturers calibrate portfolios across pharmacological classes and delivery mechanisms to match distinct clinical settings and regulatory constraints.
Product Type:
Upgrade cycles in dental pain management are accelerating as practitioners replace systemic protocols with site-specific alternatives that minimize opioid exposure and gastrointestinal complications.
- Non-steroidal Anti-inflammatory Drugs:Cyclooxygenase inhibitors including ibuprofen and naproxen dominate prescription-tier pricing through established efficacy in inflammatory dental conditions. Demand concentrates in dental clinics managing post-extraction protocols where anti-inflammatory action reduces edema alongside analgesia.
- Topical Analgesics:Benzocaine and lidocaine formulations deliver sodium channel blockade directly to oral mucosa without hepatic metabolism. United States dental service organizations are expanding procurement of these non-systemic options to limit drug interactions in polypharmacy patients.
- Acetaminophen:Centrally acting analgesic preferred when COX inhibition is contraindicated.
- Aspirin:Salicylate derivative with declining dental utilization due to bleeding risk in surgical contexts.
Non-steroidal Anti-inflammatory Drugs sit at the top of the volume ranking, with Topical Analgesics climbing the fastest.
End User:
Cost tier differentiation separates premium clinic-grade formulations from mass-market retail SKUs, with reimbursement pathways determining effective pricing floors across patient categories.
- Adults:Largest addressable population with established self-medication patterns for episodic dental pain. United States retail pharmacy channels capture the majority of adult demand through 24-hour convenience formats.
- Dental Clinics:Professional procurement of prescription-tier products and advanced topical devices. ISO 13485-certified suppliers are securing multi-year supply agreements with expanding dental service organizations in Sun Belt metropolitan areas.
- Pediatrics:Flavor-modified liquid formulations engineered for compliance in children aged 2-6.
- Elderly:Formulations accounting for polypharmacy interactions and renal function considerations.
Adults generate the highest absolute volume, while Dental Clinics show the steepest expansion trajectory as procedural volumes recover and opioid-sparing protocols proliferate.
Formulation:
Application-specific delivery mechanisms determine bioavailability profiles and patient compliance, with immediate-release formats dominating acute pain episodes.
- Tablets:Mature solid-dose category with stable demand across retail pharmacy. Manufacturing infrastructure is concentrated among established pharmaceutical houses with validated compression and coating lines.
- Gel:Mucoadhesive polymer systems enabling prolonged tissue contact for periodontal and post-extraction application. Dental clinics in the United States are prioritizing carbomer-thickened formulations for immediate site-specific relief.
- Liquid:Pediatric and geriatric preference for dose flexibility and swallowing ease.
- Oral Rinse:Transient contact format for diffuse mucosal coverage in generalized dental pain.
Tablets maintain volume leadership, though Gel formats are gaining share fastest as clinic procurement shifts toward localized delivery.
Administration Route:
Customer type segmentation separates institutional purchasers with formulary committees from individual consumers making shelf-level decisions.
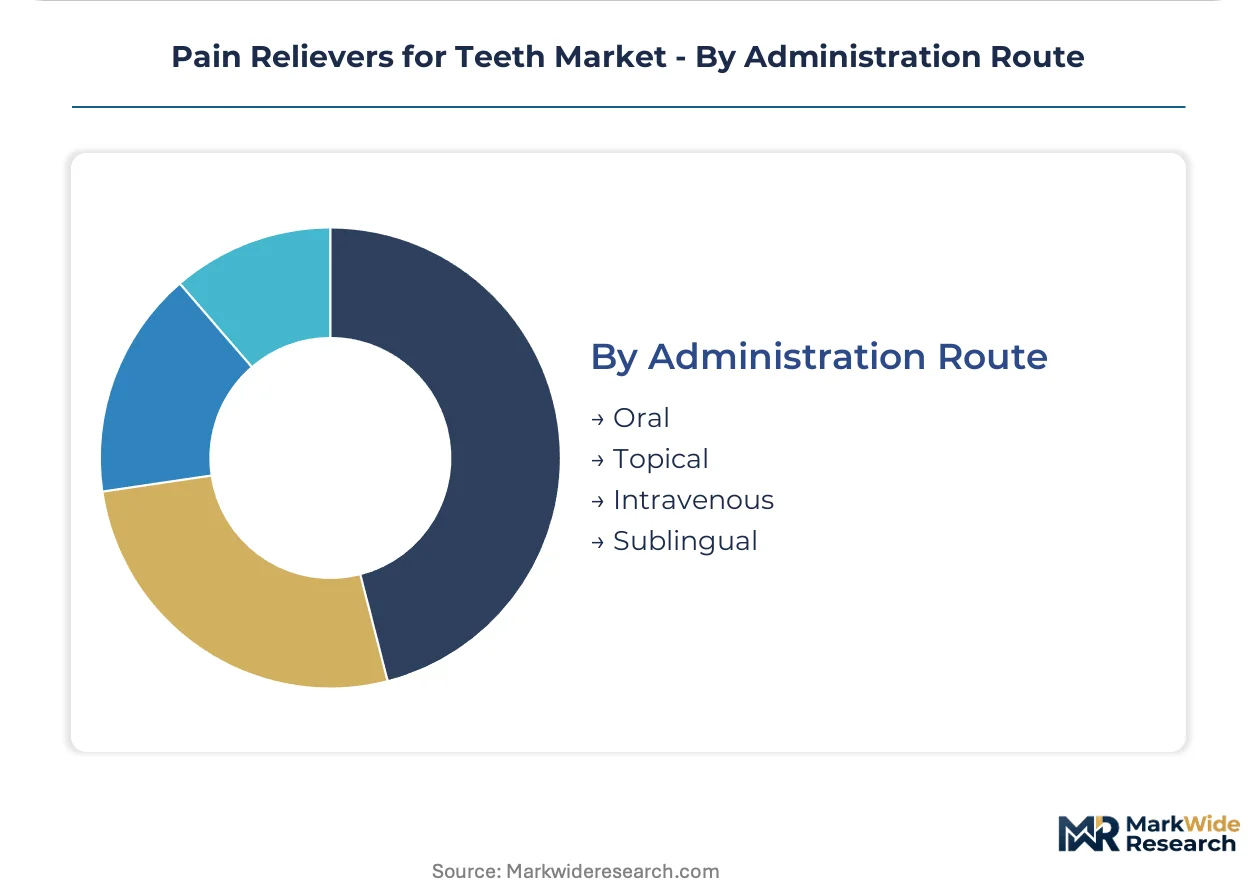
- Oral:Systemic absorption through gastrointestinal tract remains the default for moderate-to-severe dental pain. United States households maintain OTC oral analgesics as standard medicine cabinet inventory.
- Topical:Dermal and mucosal application bypassing first-pass metabolism. EPA-compliant domestic manufacturers are securing preferred supplier status with retailers demanding verified environmental documentation.
- Intravenous:Hospital and surgical center administration for acute post-operative management.
- Sublingual:Rapid buccal absorption for patients with compromised swallowing or gastric motility.
Oral administration dominates current volume, with Topical routes expanding most quickly as non-systemic protocols displace traditional approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting topical analgesic production toward jurisdictions where EPA-style environmental compliance costs remain lower, while dental clinic procurement concentrates in markets with the strongest opioid-sparing protocols.
United States
Dental service organizations across Sun Belt metropolitan areas are consolidating topical analgesic purchasing through direct-to-clinic portals. The FDA's tightened benzocaine concentration ceilings for over-the-counter products are compressing formulation flexibility for retail-facing manufacturers. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf presence across pharmacy chains in Florida and Texas.
Germany
REACH restrictions on persistent organic pollutants are forcing reformulation of solvent-based oral rinses at manufacturing facilities in North Rhine-Westphalia. The EMA's safety reviews of methemoglobinemia risk have triggered voluntary withdrawals of infant teething gels across pharmacy chains. Bayer anchors its position through topical analgesic formulations that bypass gastrointestinal absorption concerns.
China
The NMPA is accelerating reviews for manufacturers demonstrating renewable energy integration in active pharmaceutical ingredient synthesis. Carbomer and poloxamer production clusters in Jiangsu and Zhejiang provinces create supply concentration for gel-based topical manufacturers. Domestic producers are securing preferred supplier status with retailers demanding verified environmental documentation.
India
Organized pharmacy chains in tier-2 and tier-3 cities present underpenetrated distribution channels for topical dental analgesics currently concentrated in metro hospitals. CDSCO regulations on combination analgesic safety are reshaping formulation strategies for export-oriented manufacturers. GSK competes in the pediatric segment with flavor-modified liquid formulations designed for compliance in Mumbai and Delhi clinic networks.
Japan
PMDA quality standards for mucosal-contact devices are creating certification barriers for new topical entrants seeking dental clinic contracts. METI incentives for low-carbon pharmaceutical production are favoring domestic manufacturers with renewable energy integration. Sunstar occupies a position within the oral care specialist tier serving periodontal pain management protocols in Tokyo and Osaka metropolitan areas.
Pain Relievers for Teeth Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumer health conglomerates dominating retail pharmacy channels while ISO 13485-certified suppliers capture dental clinic procurement. The market exhibits moderate consolidation at the top tier, where diversified pharmaceutical houses leverage existing distribution infrastructure. Three archetypes define competitive positioning: consumer health conglomerates with shelf-space dominance, pharmaceutical specialists with prescription-tier pricing power, and oral care-focused manufacturers with periodontal expertise. Capacity expansion in topical gel manufacturing and strategic partnerships with dental service organizations represent the dominant competitive moves reshaping supply relationships.
Among diversified pharmaceutical houses, Merck and Bayer exemplify the prescription-tier archetype through cyclooxygenase inhibitor portfolios, while Johnson & Johnson represents the consumer health conglomerate model with retail pharmacy channel control. Septodont occupies a position within the dental-specialist tier, anchoring professional procurement relationships with clinic networks seeking audited topical device suppliers. These three company types illustrate how competitive advantage flows from either regulatory navigation capability, consumer brand equity, or clinical channel specialization.
| Leading Market Players |
|---|
| Merck |
| Bayer |
| Johnson & Johnson |
| GSK |
| 3M |
| Sunstar |
| Colgate-Palmolive |
| Septodont |
| Bausch Health |
| Others |
Pricing and Supply Chain Analysis
Nanoemulsion carrier systems are compressing cost economics for topical gel manufacturers while simultaneously concentrating supply relationships among EPA-compliant domestic producers with validated environmental documentation. This production-method transition rewards scaled operators capable of absorbing compliance investments while fragmenting margin pools for importers facing tariff and documentation friction.
Pricing Analysis
Distributor margins in dental clinic procurement channels absorb compression as direct-to-clinic portals disintermediate wholesale pharmacy intermediaries. Pricing stratifies across premium clinic-grade formulations with ISO 13485 certification, standard retail-facing SKUs under FDA concentration ceilings, and economy generic tablets subject to bioequivalence study costs. Cost compression in the generic topical tier is intensifying because FDA validation timelines extend 18-24 months. Dental service organizations demonstrate lowest price sensitivity due to formulary standardization, while individual retail consumers exhibit highest elasticity.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive gel formulations is elevating landed costs for European and Asian manufacturers serving United States dental clinic networks. Active pharmaceutical ingredient synthesis concentrates in India and China, with carbomer and poloxamer rheology modifiers sourcing primarily from Jiangsu and Zhejiang province production clusters. Single-source vulnerability sits with concentrated excipient supply from Chinese chemical manufacturers. Distribution runs through specialized dental procurement platforms consolidating multi-location dental service organization purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pain relievers for teeth constitute a late-cycle quality story as dental clinics prioritize audited suppliers with ISO 13485 certification and verified EPA compliance over lowest-unit-cost alternatives. Demand is shifting toward premium topical formulations with mucoadhesive polymer delivery systems.
For Market Incumbents: Acquire ISO 13485-certified contract manufacturing capacity to secure multi-year supply agreements with expanding dental service organizations. Defend against generic topical entrants by accelerating novel delivery mechanism R&D in nanoemulsion carriers. Prioritize backward integration into carbomer and poloxamer supply to mitigate excipient concentration risk from Chinese production clusters. For New Entrants and Emerging Players: NMPA accelerated review pathways in China for low-carbon API synthesis open a window for renewable energy-integrated manufacturers to capture regulatory preference. Target organized pharmacy chains in India's tier-2 and tier-3 cities with flavor-modified liquid formulations for pediatric compliance. Pursue direct-to-clinic distribution partnerships bypassing traditional wholesale pharmacy channels. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic API producers upgrading EPA environmental controls to secure preferred retailer documentation status. Long-term viability hinges on regulatory navigation capability across divergent FDA, EMA, and NMPA concentration limits. Monitor ISO 13485 certification expansion rates among contract manufacturers as inflection indicator for supply contract availability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Expansion | Unlocks multi-year supply agreements with dental service organizations requiring audited topical device suppliers. |
| Nanoemulsion R&D Investment | Enables transmucosal penetration without alcohol irritation for immediate post-extraction clinic protocols. |
| Direct-to-Clinic Distribution Platform | Compresses wholesale pharmacy margins while capturing Sun Belt metropolitan dental service organization consolidation. |
| EPA Compliance Upgrade | Secures preferred supplier status with retailers demanding verified environmental documentation for topical products. |
| Flavor-Modified Liquid Development | Captures pediatric segment share by reducing administration refusal rates in children aged 2-6. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged dental clinic procurement managers, contract manufacturing quality directors, regulatory affairs specialists at consumer health conglomerates, and pharmacy chain category buyers. Secondary sources included FDA labeling guidance documents, EMA safety review publications, EPA discharge compliance records, ISO 13485 certification databases, and dental service organization purchasing disclosures. Bottom-up product-level volume builds were triangulated against top-down market sizing from trade flow analysis.
Rate-of-change decomposition across the analysis window separated volume growth from pricing dynamics and mix shifts toward premium formulations. Segmentation dimensions modeled encompassed pharmacological class, formulation type, end-user category, and regional regulatory cluster. CAGRs were derived from logistic adoption curves for novel delivery technologies and linear extrapolation for mature tablet segments. Forecast inputs incorporated dental procedure volume recovery trajectories and opioid-sparing protocol penetration rates.
Revisions become necessary when FDA guidance on combination analgesic safety materializes or when REACH restrictions expand to additional solvent categories. Forecasts reflect assumptions about regulatory stability and excipient supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chinese Fibromyalgia Market
Pain Management
Arthralgia Management Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Chronic Pain Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Dyspareunia Market
Pain Management
Visceral Pain Market
Pain Management
Migraine Management Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Cluster Headache Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Cold Pain Therapy Market
Pain Management
Global Analgesic Infusion Pumps Market