
 Guided Biofilm Therapy Market | 2026-2036
Guided Biofilm Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Guided Biofilm Therapy Market Outlook
Laser-assisted biofilm visualization is reshaping how dental professionals approach preventive periodontal care, replacing traditional exploratory scaling with targeted, evidence-based intervention. EMS leverages its Swiss engineering heritage to dominate high-precision ultrasonic instrumentation for biofilm removal. Straumann Group anchors its position through integrated digital dentistry workflows that connect diagnostic imaging with therapeutic execution. Dentsply Sirona competes across the full technology stack, from intraoral scanners to chairside treatment delivery systems.
Guided biofilm therapy combines diagnostic imaging, disclosing agents, and mechanical or chemical removal methods to identify and eliminate bacterial biofilm with minimal tissue trauma. The procedure typically employs erythrosine-based disclosing dyes alongside air-polishing devices operating at controlled pressure parameters to preserve root cementum. Instruments and systems command the largest revenue share as practices replace legacy scaling equipment with connected, feedback-enabled platforms. Diagnostic tools represent the fastest-expanding segment, driven by AI-enhanced fluorescence imaging that maps biofilm maturity in real time. Chemical agents occupy a mature, margin-compressed position where generic formulations limit pricing power for non-specialized suppliers.
FDA 510(k) clearances govern device marketing in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements on biofilm detection systems sold in Europe. Japan's PMDA maintains rigorous biocompatibility standards for disclosing agents used in mucosal contact, creating a barrier for new chemical entrants. Stakeholders must monitor how reimbursement authorities in Germany, France, and Japan classify guided biofilm therapy relative to conventional prophylaxis, as coding decisions will determine whether adoption accelerates beyond premium private practices into standard-of-care protocols.
Market Dynamics
Reimbursement coding decisions in Germany, France, and Japan are restructuring competitive positioning by determining whether guided biofilm therapy remains confined to premium private practices or expands into standard-of-care protocols across national health systems.
Growth Catalysts
- EU MDR compliance deadlines:Stricter clinical evidence requirements for biofilm detection systems are accelerating replacement cycles as manufacturers upgrade legacy platforms to meet certification standards.
- Preventive care prioritization:Swiss and German dental clinics are embedding guided biofilm protocols into routine periodontal maintenance schedules to reduce long-term treatment costs.
- AI-enhanced fluorescence imaging:Real-time biofilm maturity mapping is improving chairside diagnostic accuracy and driving instrument upgrade demand among high-volume practices.
Market Restraints
- Capital intensity:Connected, feedback-enabled platforms require substantial upfront investment that limits adoption among independent dental practitioners.
- Generic chemical formulations:Non-specialized suppliers face margin compression in disclosing agents where patent protection has expired and pricing power collapsed.
- Japan PMDA biocompatibility barriers:Rigorous mucosal contact standards for new chemical entrants extend time-to-market and elevate regulatory compliance costs.
Strategic Opportunities
- Underpenetrated Japanese market:Premium private practices in Tokyo and Osaka represent expansion potential if PMDA pathways streamline for established disclosing dye formulations.
- Integrated digital dentistry workflows:Convergence of intraoral scanning, diagnostic imaging, and therapeutic execution creates bundled platform opportunities.
- Air-polishing device miniaturization:Portable systems for mobile dental units open access to rural and institutional care settings previously excluded from advanced biofilm management.
Industry Challenges
- Legacy equipment integration:Practices face workflow friction when connecting new feedback-enabled platforms to existing practice management software and sterilization protocols.
- Clinician training standardization:Variability in erythrosine-based disclosing technique and air-polishing pressure calibration affects treatment consistency and patient outcomes.
- Supply chain reconfiguration:Component sourcing for precision ultrasonic transducers concentrates among Swiss and German specialty manufacturers, creating vulnerability to regional disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guided Biofilm Therapy Market |
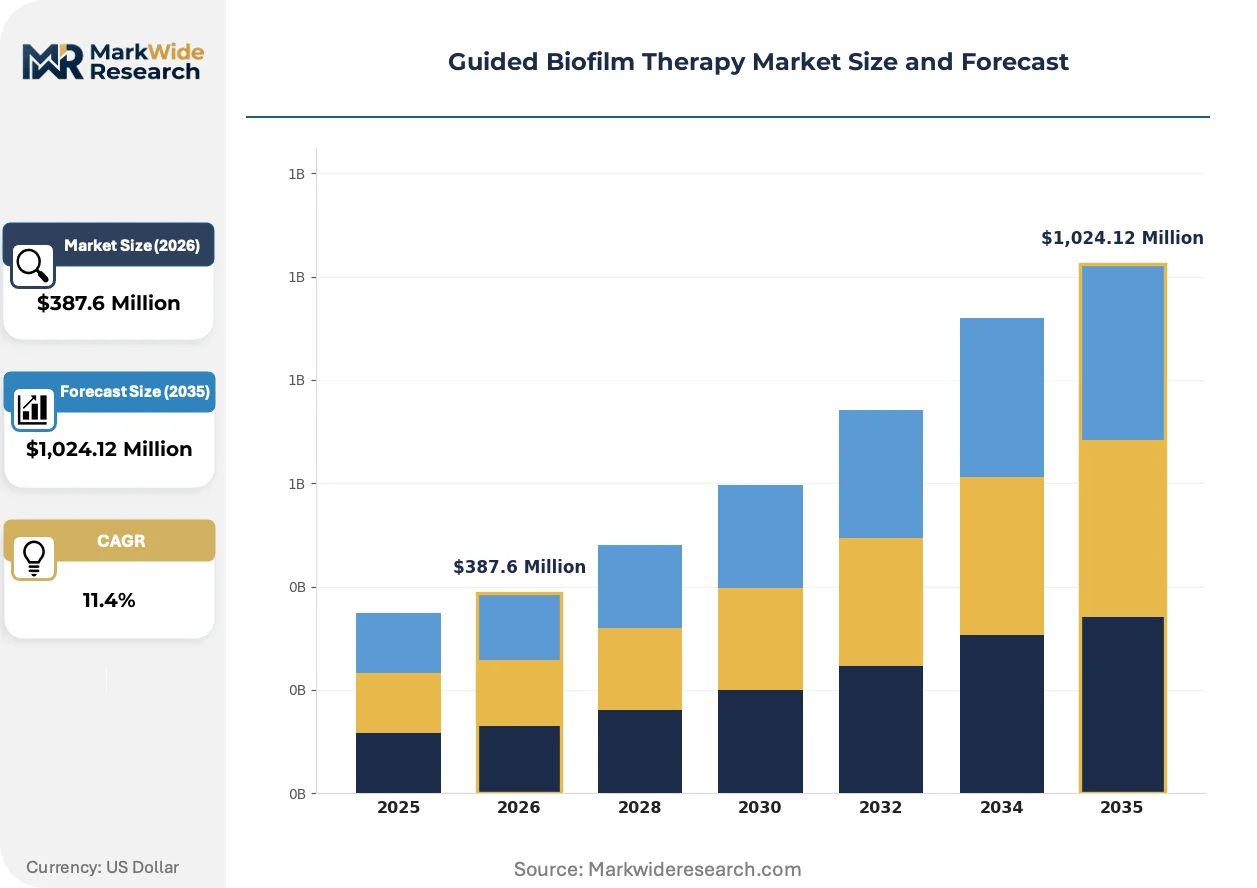
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Chemicals, Devices, Systems End User: Dentists, Clinics, Hospitals, Research Laboratories Application: Oral Care, Surgical Procedures, Infection Control, Wound Management Technology: Laser, Ultrasound, Chemical Agents, Diagnostic Tools |
| Companies Covered | EMS, Straumann Group, Dentsply Sirona, Hu-Friedy Group, Kerr Corporation, Henry Schein, A-dec, Colgate-Palmolive, 3M Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guided Biofilm Therapy Market Strategic Shifts
Diagnostic imaging convergence with therapeutic execution is collapsing traditional boundaries between detection and intervention, while regulatory frameworks in Europe and Asia-Pacific recalibrate evidence requirements for software-enabled medical devices.
Fluorescence-based biofilm visualization is collapsing the diagnostic phase of periodontal appointments by enabling immediate, chairside identification of bacterial maturity without exploratory scaling. High-volume dental clinics in Germany and Switzerland are adopting these systems fastest, replacing tactile assessment with objective, photodocumentable evidence. Treatment planning compression is collapsing appointment structures from multi-visit sequences into single-visit interventions.
EU MDR Article 10 clinical evaluation requirements are tightening post-market surveillance obligations for biofilm detection systems marketed in Europe. Manufacturers must now maintain systematic procedures to collect and review experience gained from devices in production, elevating documentation burdens. Class IIa and IIb devices face extended notified body review timelines, compressing product launch windows and favoring established players with regulatory infrastructure.
Swiss and German dental service organizations are consolidating procurement authority from individual practitioners to centralized purchasing functions. Group practice networks negotiate directly with EMS and Straumann Group for platform-level contracts covering instruments, disposables, and maintenance. This concentration shifts vendor relationship economics toward volume-based pricing and away from traditional distributor-mediated transactions in Western European metropolitan markets.
Guided Biofilm Therapy Market Segmentation
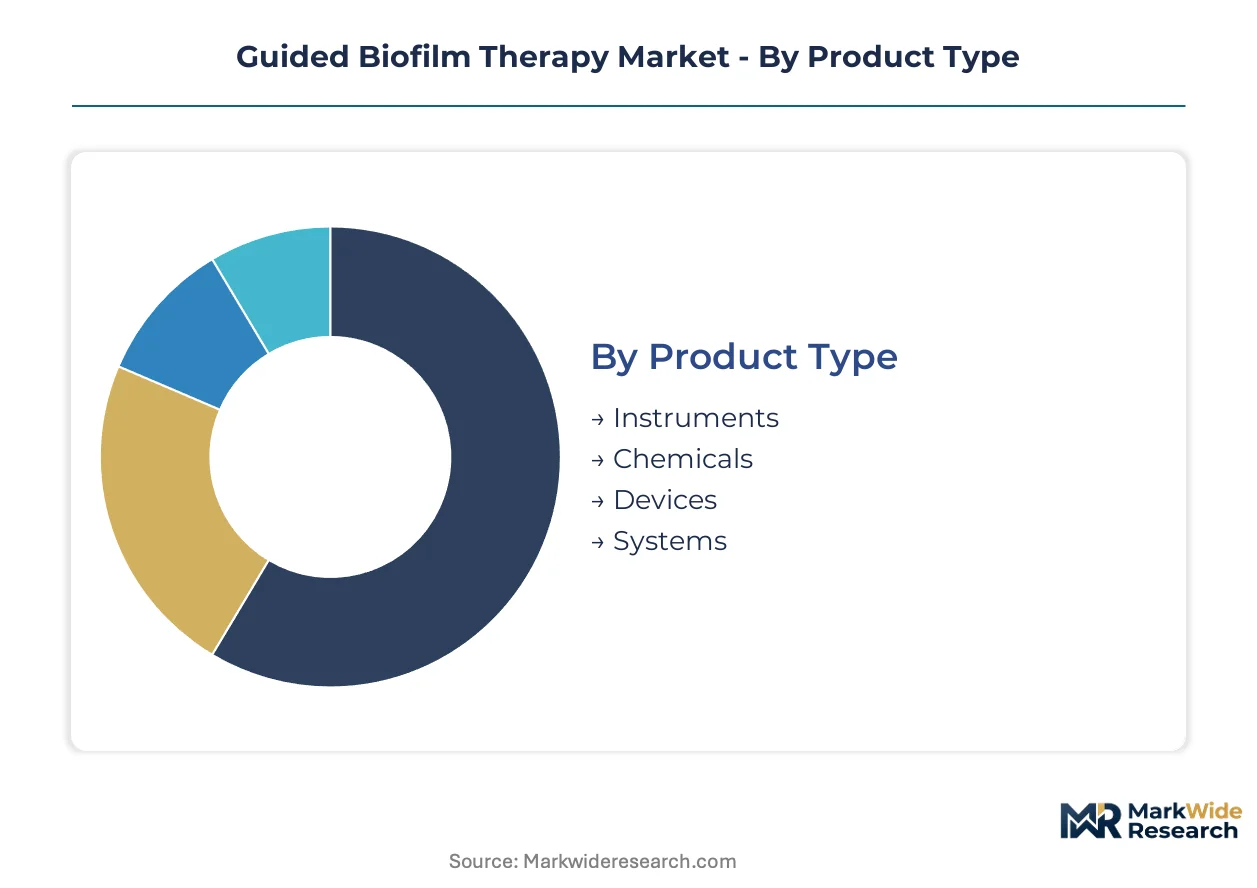
Segmentation in guided biofilm therapy reveals distinct replacement cycles and margin structures across product categories. Understanding these patterns helps vendors align R&D investment with revenue stability and growth vectors.
Product Type:
Instruments and devices turn over fastest as practices upgrade to connected platforms, while chemical agents cycle slowest due to commoditization.
- Instruments:Precision ultrasonic transducers and air-polishing handpieces with real-time pressure feedback dominate capital expenditure in German and Swiss dental clinics. EMS and Straumann Group compete intensely for platform-level contracts as group practices consolidate procurement authority.
- Systems:Integrated diagnostic-therapeutic platforms combining fluorescence imaging, disclosing agent delivery, and mechanical removal command premium positioning. These bundled solutions are gaining share fastest among high-volume metropolitan practices seeking workflow compression.
- Devices:Standalone air-polishing units and portable detection systems serve mid-tier practices and mobile dental units.
- Chemicals:Erythrosine-based disclosing dyes and prophylaxis powders face margin compression from generic competition.
Instruments dominate installed base. Systems represent where expansion concentrates.
End User:
Cost tier stratification separates premium private practices from institutional procurement with divergent sensitivity to upfront capital requirements.
- Dentists:Independent practitioners in Germany and Switzerland drive initial adoption of fluorescence-based protocols, prioritizing patient differentiation and clinical documentation capabilities over pure cost efficiency.
- Clinics:Dental service organizations in Western Europe negotiate centralized purchasing for multi-location standardization, demanding volume pricing and unified maintenance contracts across their networks.
- Hospitals:Academic medical centers and integrated health systems incorporate guided biofilm therapy into perioperative oral health protocols for surgical patients.
- Research Laboratories:Universities and contract research organizations utilize advanced diagnostic tools for biofilm maturity studies and therapeutic validation.
Clinics concentrate procurement volume. Dentists remain the primary technology validation channel.
Application:
Volume distribution follows reimbursement coding decisions that privilege preventive over therapeutic interventions in European health systems.
- Oral Care:Routine periodontal maintenance and preventive prophylaxis constitute the core volume application, with German statutory health insurance frameworks increasingly covering minimally invasive biofilm management.
- Surgical Procedures:Preoperative oral optimization for implant placement and orthognathic surgery commands premium pricing in private-pay segments.
- Infection Control:Biofilm reduction protocols in immunocompromised patient populations represent a specialized hospital application.
- Wound Management:Chronic wound biofilm disruption extends the technology platform beyond traditional dental boundaries.
Oral care absorbs the majority of device utilization. Surgical applications generate the highest revenue per procedure.
Technology:
Supply concentration for precision components creates vulnerability to regional disruption, particularly for ultrasonic and laser subsystems.
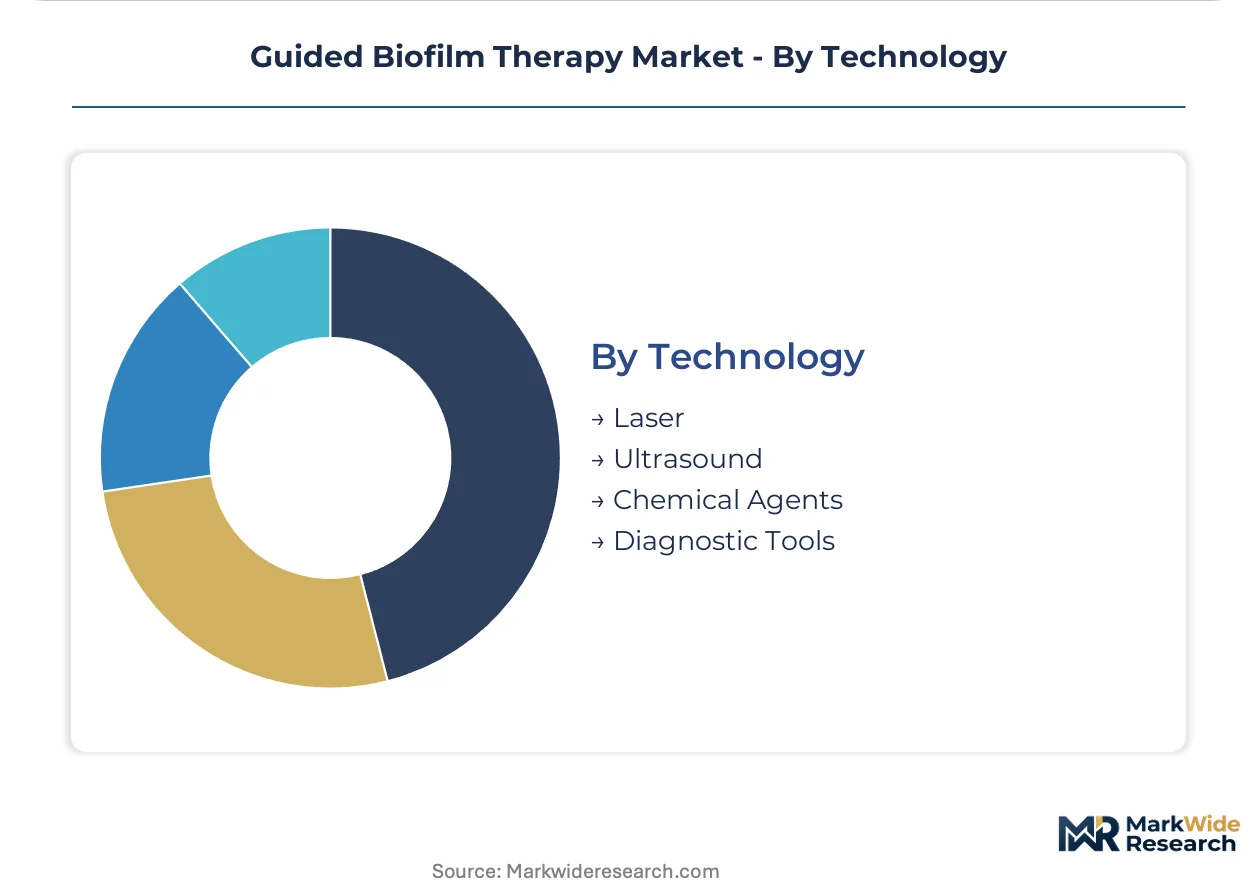
- Laser:Fluorescence excitation systems for real-time biofilm visualization enable immediate chairside intervention without exploratory scaling. German clinics adopt these fastest for photodocumentable diagnostic evidence.
- Diagnostic Tools:AI-enhanced fluorescence imaging platforms mapping bacterial maturity in real time are climbing the fastest as practices replace tactile assessment with objective measurement.
- Ultrasound:Piezoelectric transducers for controlled biofilm removal preserve root cementum better than traditional scaling.
- Chemical Agents:Disclosing dyes and air-polishing powders serve as consumable revenue streams with limited differentiation.
Ultrasound anchors current installed capacity. Diagnostic tools represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium private practices in Germany and Switzerland concentrate procurement authority, while reimbursement frameworks in Japan and France determine whether protocols expand beyond high-end dentistry into national health systems.
Germany
Dental service organizations in Berlin and Munich consolidate multi-location purchasing for fluorescence imaging platforms. The statutory health insurance framework under the Federal Joint Committee (G-BA) evaluates minimally invasive periodontal treatments for reimbursement coding expansion. Bavarian group practices negotiate directly with Swiss manufacturers for platform-level maintenance contracts.
Switzerland
Preventive care prioritization drives Zurich and Geneva clinics to embed biofilm protocols into routine maintenance schedules. Swissmedic maintains stringent clinical evidence requirements for diagnostic device approvals that favor established regulatory infrastructure. The Basel-Zurich corridor concentrates precision ultrasonic transducer manufacturing for regional supply.
Japan
Tokyo and Osaka private practices represent underpenetrated expansion potential pending regulatory pathway streamlining. The Pharmaceuticals and Medical Devices Agency (PMDA) imposes rigorous biocompatibility standards for disclosing agents used in mucosal contact. Kanto region academic medical centers pilot perioperative oral health protocols for surgical patients.
France
Parisian clinics drive adoption of AI-enhanced fluorescence imaging for photodocumentable diagnostic evidence. The National Health Authority (HAS) assesses guided biofilm therapy classification relative to conventional prophylaxis for reimbursement decisions. Île-de-France dental networks standardize procurement across metropolitan locations.
United States
High-volume practices in California and New York upgrade to connected, feedback-enabled platforms for workflow compression. The FDA 510(k) clearance pathway governs device marketing with moderate evidence requirements compared to European standards. Boston academic centers integrate diagnostic-therapeutic platforms into periodontal residency training programs.
Guided Biofilm Therapy Market Competitive Environment
Channel-controlling players compete with product-specialist players for procurement authority as group practices consolidate purchasing. The vendor base organizes around three archetypes: Swiss-engineered precision instrument manufacturers, integrated digital dentistry platform providers, and diversified dental supply conglomerates. M&A activity concentrates on diagnostic imaging capabilities, while strategic partnerships target bundled workflow solutions.
Among Swiss-engineered specialists, EMS and Straumann Group occupy positions anchored by regional manufacturing heritage and platform-level contract negotiation. Dentsply Sirona exemplifies the diversified conglomerate archetype, spanning diagnostic imaging through therapeutic execution without geographic concentration in its corporate nomenclature. These three entities represent the competitive anchors around which procurement authority, regulatory infrastructure, and technology convergence organize market structure.
| Leading Market Players |
|---|
| EMS |
| Straumann Group |
| Dentsply Sirona |
| Hu-Friedy Group |
| Kerr Corporation |
| Henry Schein |
| A-dec |
| Colgate-Palmolive |
| 3M Health Care |
| Others |
Value Chain & Pricing Dynamics
The Basel-Zurich corridor anchors precision ultrasonic transducer manufacturing, concentrating component supply among Swiss and German specialty producers whose limited capacity elevates pricing power for feedback-enabled platforms downstream. This geographic clustering creates asymmetric leverage where instrument manufacturers command premium positioning while chemical suppliers face commoditization.
Pricing Analysis
Cost-plus contracts with Swiss franc and euro indexation dominate platform procurement between dental service organizations and precision instrument manufacturers. Price differentiation rests on certification tier under EU MDR and bundled after-sales service coverage. Cost compression in disclosing agents intensifies because patent expiration collapsed pricing power for erythrosine formulations. Independent practitioners exhibit highest price sensitivity, while group practices prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Piezoelectric ceramic substrates and precision-machined titanium handpiece housings feed from specialized suppliers in Switzerland, Germany, and Japan. Raw material dependencies center on rare-earth dopants for fluorescence imaging systems, medical-grade polymers for disposable tips, and high-purity erythrosine for disclosing formulations. Single-source vulnerability concentrates in Swiss precision grinding capacity for ultrasonic transducers. Distribution runs through manufacturer-direct field service teams for capital equipment, with chemical consumables flowing via dental supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Guided biofilm therapy demand follows dental capital expenditure cycles, with current recovery momentum tied to EU MDR compliance deadlines forcing platform replacement across Western European clinics.
For Market Incumbents: Build regulatory moat through accelerated EU MDR certification for AI-enhanced diagnostic modules before Article 10 clinical evaluation timelines extend. Consolidate procurement relationships with Berlin and Munich dental service organizations through captive maintenance contracts. Counter generic chemical erosion by backward integration into proprietary disclosing dye formulations with mucosal biocompatibility dossiers. For New Entrants and Emerging Players: Build out portable air-polishing systems for mobile dental units serving rural Japan and institutional care settings excluded from premium platform access. Target Tokyo private practices with streamlined PMDA pathways for established dye formulations. Pursue software companion positioning that integrates with existing EMS and Straumann Group installed bases rather than competing at hardware level. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic imaging specialists with FDA 510(k) clearances and EU MDR technical documentation already filed. Long-term viability hinges on reimbursement coding expansion beyond premium private practices into statutory health insurance frameworks. Monitor Federal Joint Committee (G-BA) and National Health Authority (HAS) classification decisions as inflection signals for standard-of-care protocol adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Filing | Accelerates market access ahead of extended notified body review timelines compressing launch windows. |
| AI-Enhanced Fluorescence Imaging Launch | Replaces tactile assessment with photodocumentable diagnostic evidence in German high-volume clinics. |
| Group Practice Maintenance Contracting | Captures recurring revenue streams as Bavarian networks consolidate procurement from individual practitioners. |
| Portable System Miniaturization | Opens mobile dental unit access to rural care settings previously excluded from advanced biofilm management. |
| Reimbursement Strategy Development | Positions protocols for statutory health insurance coding expansion beyond private-pay segments in France. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases. Clinical interviews with periodontists, biomedical engineers, and GPO contracts managers informed instrument upgrade cycle dynamics. Dental service organization procurement heads and regulatory affairs leads at precision manufacturers provided pricing and compliance intelligence. Bottom-up installation base estimates triangulated against top-down reimbursement expenditure analysis.
Forecast inputs include technology adoption curves across fluorescence imaging, air-polishing device penetration, and disclosing agent utilization rates. Segmentation dimensions span product type, end-user archetype, application setting, and technology platform. CAGRs derive from replacement cycle modeling, reimbursement trajectory assumptions, and group practice consolidation patterns. Industry-specific inputs incorporate EU MDR compliance cost pass-through and PMDA biocompatibility review duration assumptions.
Stress conditions across reimbursement coding decisions, regulatory approval timelines, and supply chain disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding group practice procurement concentration and diagnostic imaging convergence rates. Cross-checking against Federal Joint Committee (G-BA) and National Health Authority (HAS) published guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental Chair Market
Dental Devices
China Dental Implants Market
Dental Devices
Digital Facebow Market
Dental Devices
Dental Needle Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Acrylic Teeth Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Global Dental Turbine Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Global Dental Hygiene Devices Market