
 Spain Facial Aesthetics Market | 2026-2036
Spain Facial Aesthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Facial Aesthetics Market Insights
Spanish aesthetic device manufacturing is consolidating around specialized producers in Barcelona and Madrid. AbbVie (Allergan Aesthetics) leverages its Juvederm portfolio to dominate dermal filler supply chains across Iberia. Galderma SA sustains competitive pressure through integrated dermatology platforms that span prescription skincare to injectables. Merz Aesthetics anchors its position with ultrasound-based tightening systems distributed through certified clinic networks.
Facial aesthetics encompasses non-surgical procedures that modify skin texture, volume distribution, and structural contour using injectable biologics, energy-based devices, and topical resurfacing agents formulated with precise concentrations of active compounds. Botulinum toxin and dermal fillers constitute the mature revenue core, while laser treatments capture expanding margin pools as device costs decline and treatment protocols standardize. Medical spas represent the fastest-growing end-user channel, displacing traditional hospital outpatient settings through convenience-focused service models and flexible pricing structures.
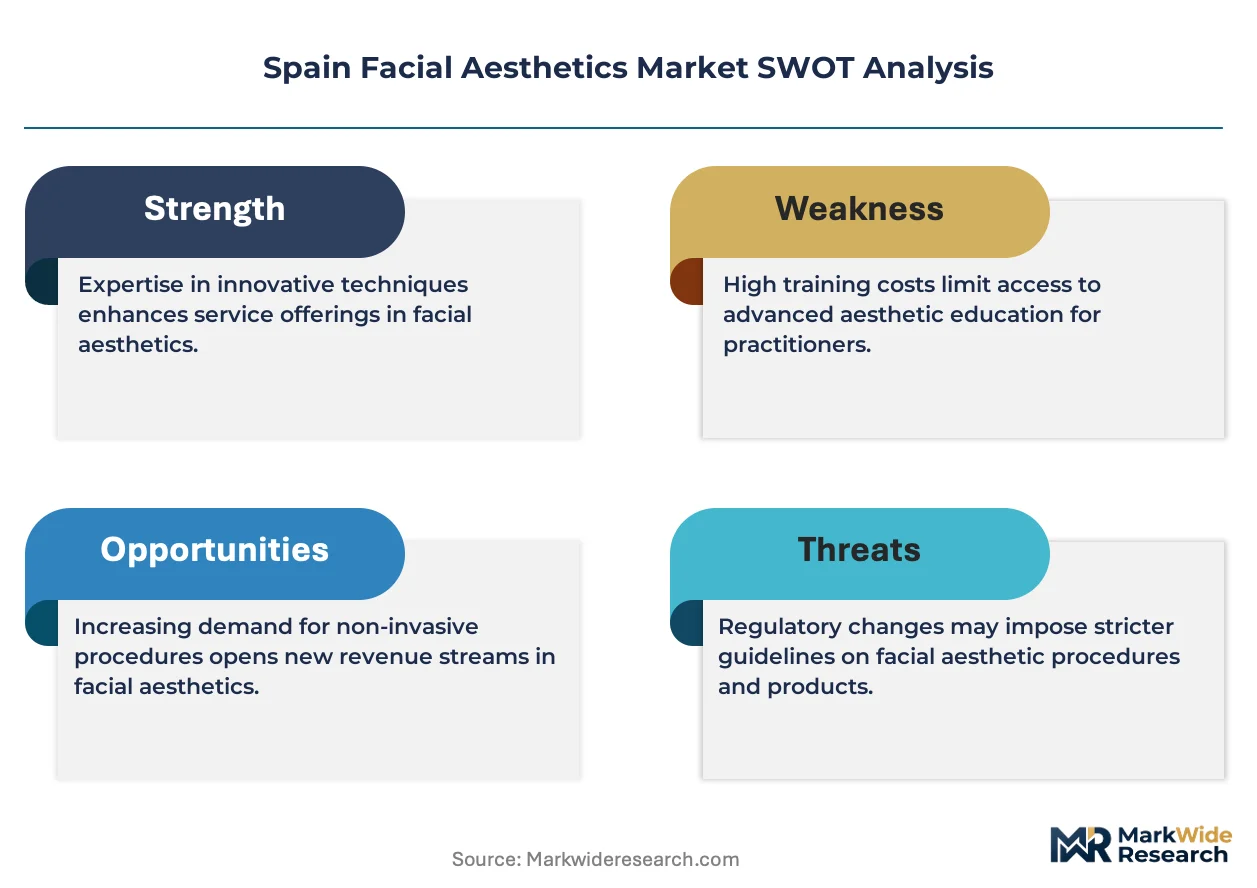
Spain's Ministry of Health and the Spanish Agency for Medicines and Health Products enforce CE-marking compliance under EU MDR transition timelines, elevating documentation burdens for imported devices. The General Council of Official Medical Colleges sets accreditation standards that restrict which practitioners may administer botulinum toxin and fillers, directly shaping addressable supply capacity. Stakeholders must monitor how autonomous community health departments interpret training hour minimums, as divergent local enforcement will fragment market access across Andalusia, Catalonia, and the Basque Country.
Market Dynamics
The Spanish facial aesthetics sector is restructuring around autonomous community-level enforcement of practitioner accreditation, fragmenting market access across regional health departments with divergent training hour interpretations.
Growth Catalysts
- EU MDR transition timelines:CE-marking documentation burdens elevate compliance costs for imported devices, advantaging domestic Barcelona and Madrid manufacturers with established notified body relationships.
- Medical spa channel expansion:Convenience-focused service models in Catalonia and Madrid displace traditional hospital outpatient settings through flexible pricing structures and extended operating hours.
- Cross-border patient flows:Premium dermatology centers along Barcelona's clinic corridor attract Portuguese and French consumers seeking specialized minimally invasive procedures unavailable in home markets.
Market Restraints
- Hyaluronic acid raw material concentration:Supply chains for dermal filler precursors depend on a limited base of specialized fermentation facilities, creating input cost volatility and batch consistency risks.
- Practitioner supply caps:Royal Decree 1277/2003 training requirements restrict which medical professionals may administer botulinum toxin, directly constraining addressable treatment capacity expansion.
- Energy-based device substitution:Ultrasound and radiofrequency tightening systems compete for the same consumer wallet as injectable volume procedures, pressuring filler margin pools in mature urban markets.
Strategic Opportunities
- Andalusian medical tourism infrastructure:Underdeveloped clinic density in Málaga and Sevilla relative to Barcelona-Madrid axis offers first-mover positioning for premium service formats targeting northern European seasonal residents.
- Integrated dermatology platforms:Convergence of prescription skincare, injectables, and energy-based treatments within single-practice workflows captures higher lifetime patient value and reduces channel conflict.
- Autonomous community regulatory arbitrage:Basque Country and Galicia health departments currently interpret training minimums less stringently than Catalonia, enabling faster practitioner onboarding and service rollout.
Industry Challenges
- CE-marking certification timelines:Extended EU MDR technical documentation reviews delay new device introductions, compressing competitive windows for novel energy-based modalities.
- Practitioner skill heterogeneity:Divergent aesthetic medicine curricula across Spanish medical schools produce inconsistent injection technique standards, elevating liability exposure and patient safety incident rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Facial Aesthetics Market |
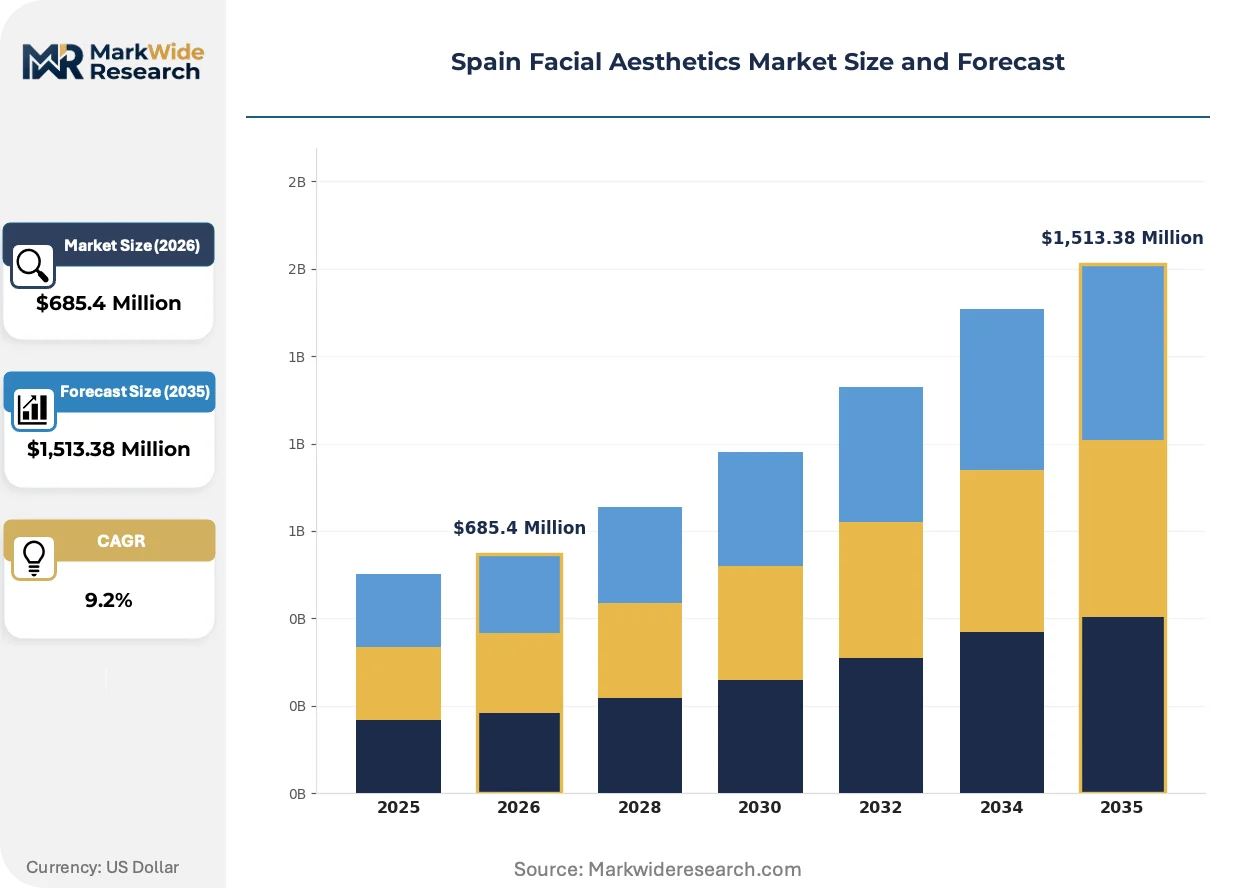
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dermal Fillers, Botulinum Toxin, Chemical Peels, Microneedling End User: Clinics, Dermatology Centers, Medical Spas, Hospitals Application: Wrinkle Reduction, Volume Restoration, Skin Rejuvenation, Acne Scarring Technology: Non-Surgical, Laser Treatments, Cryotherapy, Ultrasound |
| Companies Covered | AbbVie (Allergan Aesthetics), Galderma SA, Merz Aesthetics, Sinclair Pharma, Teoxane, Cutera Inc., Hologic Inc. (Cynosure), Bausch + Lomb (Solta Medical), Lumenis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Facial Aesthetics Market Trends and Innovations
Device economics and consumer channel preferences are restructuring how facial aesthetic services are delivered and monetized across Iberian clinic networks.
Microfocused ultrasound with visualization is overtaking traditional monopolar radiofrequency for non-surgical brow lifting and jawline contouring. Premium dermatology centers in Barcelona's Eixample district adopted this modality at accelerated pace during the past eighteen months. The technology is overtaking legacy tightening devices by enabling precise depth targeting that reduces treatment sessions and supports premium pricing tiers.
Spain's Ministry of Health is tightening interpretation of Royal Decree 1277/2003 training requirements through circular guidance to autonomous community health departments. This regulatory friction is elevating documentation burdens for clinic operators seeking to expand practitioner pools. The injectables segment faces the steepest compliance adjustment, with Madrid-based chains restructuring in-house training academies to preempt enforcement actions.
Subscription-based maintenance programs are displacing single-session transactional models among medical spa operators. Younger demographic cohorts in Barcelona and Madrid prefer predictable monthly outlays for toxin and filler touch-ups over episodic high-ticket purchases. This behavioral shift is most visible in Catalonia, where clinic chains have introduced tiered membership structures bundling skincare, injectables, and device treatments.
Spain Facial Aesthetics Market Segmentation
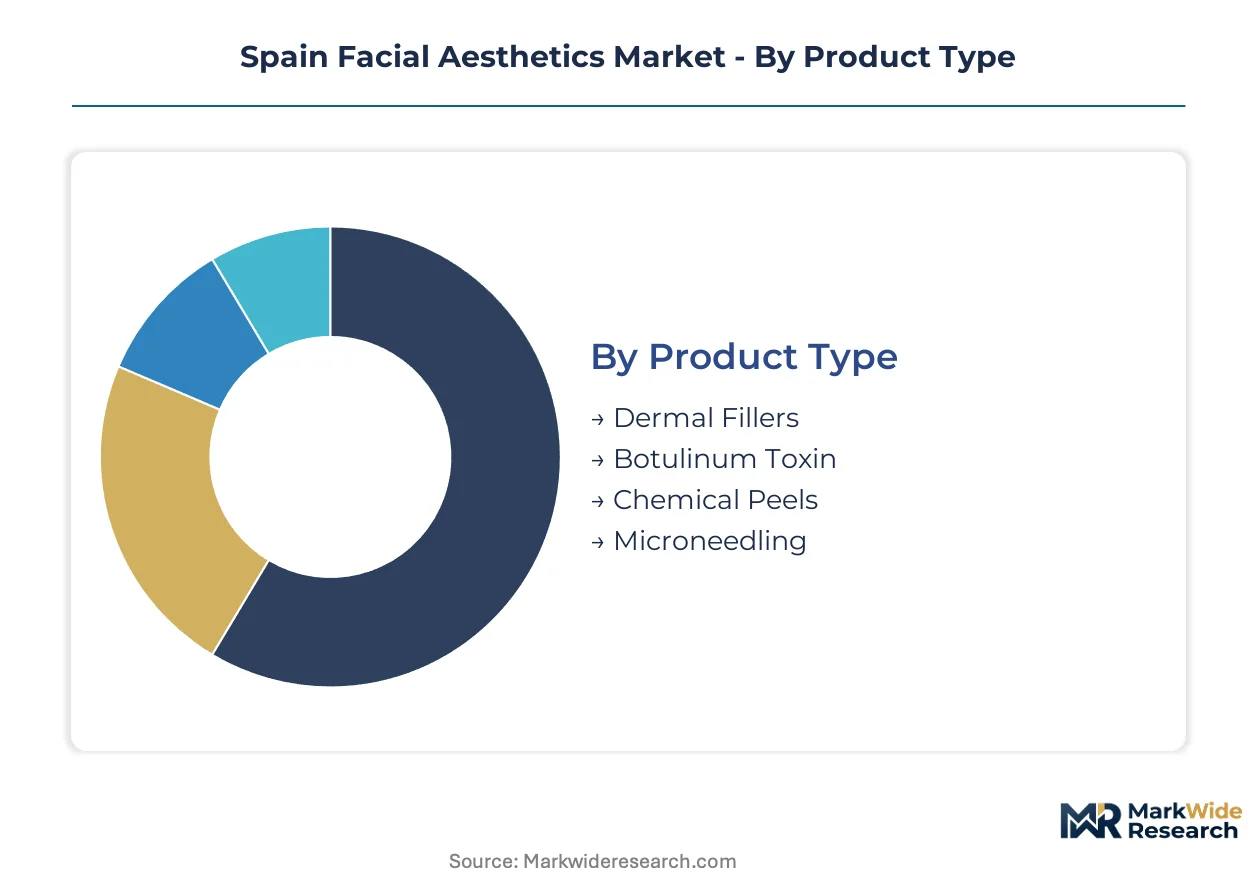
Spain's facial aesthetics market fragments across four critical dimensions that determine pricing power, regulatory exposure, and channel strategy. Product type and end-user concentration in Barcelona and Madrid create divergent margin structures, while application and technology choices reshape competitive positioning across autonomous communities.
Product Type:
Supply concentration for hyaluronic acid precursors and botulinum toxin manufacturing capacity shapes competitive dynamics across this category.
- Dermal Fillers:Cross-linked hyaluronic acid formulations dominate injectable volume procedures, with Barcelona's clinic corridor consuming disproportionate share of premium viscoelastic products. Galderma SA and AbbVie (Allergan Aesthetics) control formulation supply chains through specialized fermentation partnerships, constraining independent Spanish manufacturers.
- Botulinum Toxin:Neurotoxin formulations require cold-chain distribution infrastructure that concentrates around Madrid's pharmaceutical logistics hubs. Royal Decree 1277/2003 training requirements restrict administration rights to accredited physicians, capping treatment capacity expansion regardless of product availability.
- Chemical Peels:Acid-based resurfacing agents from Spanish compounding pharmacies serve price-sensitive segments in Andalusia.
- Microneedling:Collagen induction devices manufactured by Barcelona specialists penetrate medical spa channels through lower capital requirements.
Today's leader: Dermal Fillers. Tomorrow's challenger: Microneedling.
End User:
Channel economics and regulatory compliance burdens segment addressable market access across facility types.
- Medical Spas:Convenience-focused service models with extended operating hours capture younger demographics in Barcelona and Madrid through subscription-based maintenance programs. Flexible pricing structures and reduced clinical formality accelerate patient acquisition compared to traditional outpatient settings.
- Dermatology Centers:Integrated prescription skincare and injectable workflows in Barcelona's Eixample district command premium positioning for cross-border patients from Portugal and France. CE-marking compliance under EU MDR transition timelines elevates documentation burdens that favor established multi-specialty groups over independent operators.
- Clinics:Single-specialty aesthetic practices concentrate in Catalonia's autonomous community with dense practitioner accreditation.
- Hospitals:Traditional outpatient settings lose volume share to medical spas as reimbursement structures fail to match private-pay flexibility.
Medical Spas are climbing the fastest; Dermatology Centers retain pricing power through specialization depth.
Application:
Patient demographic expansion and treatment protocol standardization determine margin trajectories across indication areas.
- Wrinkle Reduction:Botulinum toxin protocols for glabellar and forehead lines represent the most standardized application with established reimbursement codes in private insurance frameworks. Treatment frequency creates predictable revenue streams that medical spa operators monetize through membership structures.
- Volume Restoration:Mid-face and lip augmentation procedures using hyaluronic acid fillers command highest per-session pricing in Barcelona's premium corridor. Technique-sensitive injection requirements elevate liability exposure and favor practitioners with specialized aesthetic medicine fellowships.
- Skin Rejuvenation:Combination protocols integrating chemical peels with energy-based devices gain traction in Madrid's clinic networks.
- Acne Scarring:Microneedling and fractional laser treatments address underserved demand among younger Spanish demographics.
Volume Restoration leads revenue concentration; Acne Scarring offers steepest expansion trajectory as awareness spreads.
Technology:
Device capital intensity and consumable attachment rates structure profitability differently across modality categories.
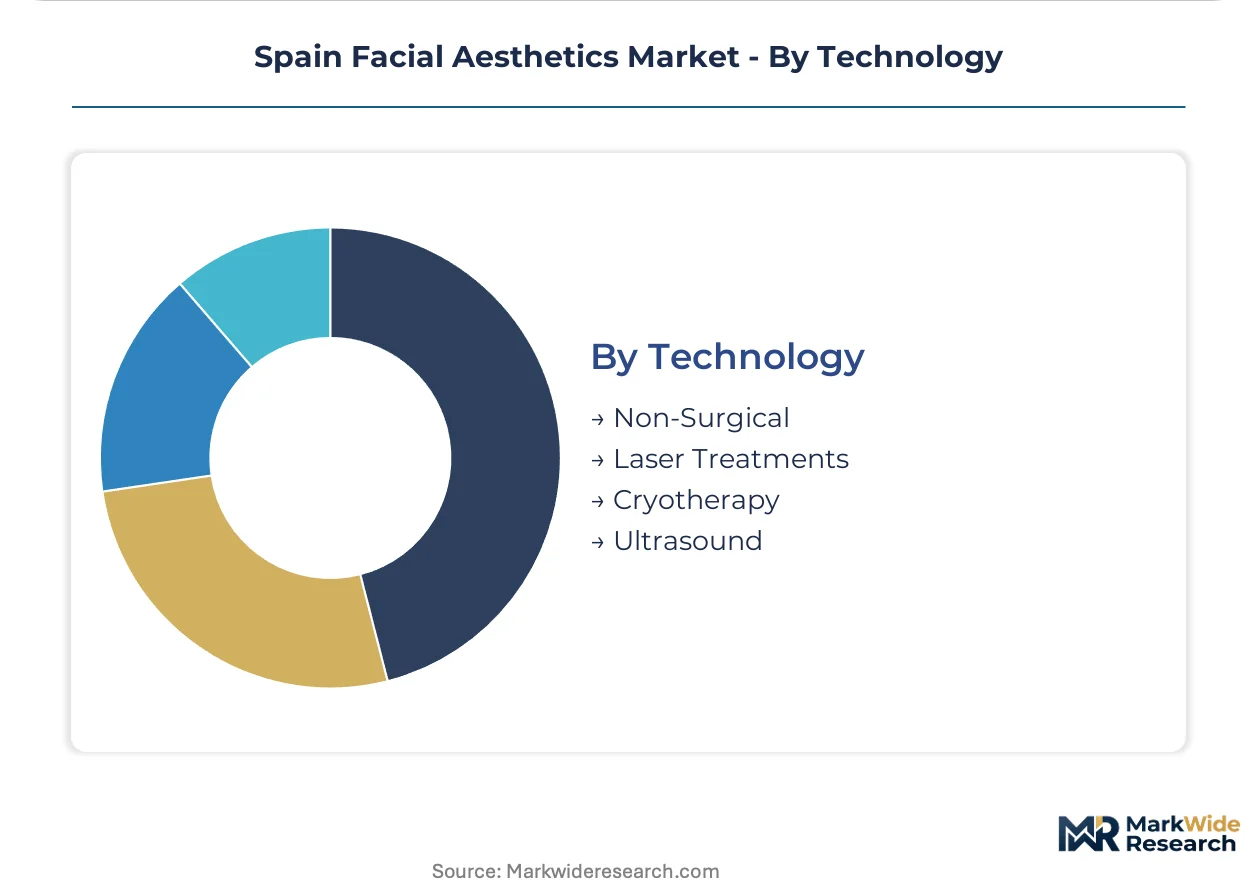
- Non-Surgical:Injectable biologics and topical agents require minimal capital equipment, enabling rapid service rollout in underpenetrated Andalusian markets. Royal Decree 1277/2003 practitioner restrictions apply most stringently to this technology category.
- Laser Treatments:Fractional and vascular laser platforms from Barcelona manufacturers compete with imported devices as EU MDR documentation burdens delay new introductions. Declining device costs and standardized protocols expand addressable patient base beyond premium dermatology centers.
- Ultrasound:Microfocused ultrasound with visualization overtakes radiofrequency for brow lifting in Barcelona's Eixample district.
- Cryotherapy:Localized fat reduction and skin tightening applications gain medical spa adoption through lower training barriers.
Non-Surgical dominates current volume; Ultrasound gains share fastest through precision targeting advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's facial aesthetics sector outpaces Portuguese and French neighbors in medical spa density, though cross-border patient flows concentrate demand in Barcelona's premium corridor rather than dispersing across Iberian markets.
Catalonia
Barcelona's Eixample district anchors the highest concentration of premium dermatology centers in Iberia, drawing Portuguese and French patients seeking specialized minimally invasive procedures. The autonomous community health department interprets Royal Decree 1277/2003 training requirements with particular stringency, elevating documentation burdens for clinic operators. Medical spa chains in Barcelona and Girona have introduced subscription-based maintenance programs that displace traditional single-session transactional models.
Madrid
The capital's pharmaceutical logistics hubs concentrate cold-chain distribution infrastructure for botulinum toxin formulations serving central Spain. Madrid-based clinic chains are restructuring in-house training academies to preempt enforcement actions from tightening regulatory interpretation. Premium dermatology centers in the Salamanca district compete with Barcelona for high-value cross-border patients from Latin American markets.
Basque Country
Health departments in Bilbao and San Sebastián currently interpret practitioner training minimums less stringently than Catalonia, enabling faster onboarding and service rollout. This regulatory arbitrage attracts Madrid-based clinic chains seeking to expand practitioner pools without equivalent compliance delays. The region's medical spa density remains underdeveloped relative to Barcelona-Madrid axis, offering positioning opportunities for convenience-focused service formats.
Andalusia
Málaga and Sevilla exhibit underdeveloped clinic density relative to the Barcelona-Madrid axis, creating first-mover positioning for premium service formats. Northern European seasonal residents generate concentrated demand during winter months, though year-round medical tourism infrastructure remains nascent. Andalusian compounding pharmacies supply acid-based resurfacing agents that serve price-sensitive segments unavailable in premium Catalonian corridors.
Spain Facial Aesthetics Market Competitive Landscape
Swiss and German producers anchor the premium device tier; Spanish and French specialists hold mid-market positioning through regional distribution relationships. The vendor base concentrates around three strategic archetypes: integrated dermatology platforms spanning prescription skincare to injectables, specialized energy-based device manufacturers with certified clinic networks, and pure-play dermal filler suppliers leveraging fermentation partnerships. Consolidation pressure is accelerating through M&A activity among device manufacturers and backward integration by clinic chains into training academy operations.
Among the integrated platform operators, AbbVie (Allergan Aesthetics), Galderma SA, and Merz Aesthetics exemplify the dominant competitive archetype in Iberian facial aesthetics. AbbVie occupies a position representing cross-linked hyaluronic acid formulation supply chains through specialized fermentation partnerships. Galderma SA anchors an integrated dermatology platform spanning prescription skincare to injectables. Merz Aesthetics sits within the ultrasound-based tightening systems segment, distributed through certified clinic networks concentrated in Barcelona and Madrid.
| Leading Market Players |
|---|
| AbbVie (Allergan Aesthetics) |
| Galderma SA |
| Merz Aesthetics |
| Sinclair Pharma |
| Teoxane |
| Cutera Inc. |
| Hologic Inc. (Cynosure) |
| Bausch + Lomb (Solta Medical) |
| Lumenis |
| Others |
Pricing and Supply Chain Analysis
Medical spa chains in Barcelona and Madrid command subscription-based pricing models that compress per-session margins while extending patient lifetime value. Royal Decree 1277/2003 training requirements elevate practitioner certification costs, forcing clinic operators to absorb compliance premiums or pass them through tiered service packages.
Pricing Analysis
Capacity additions in Andalusia are reshaping price floors for chemical peels and microneedling services as Málaga clinics compete for northern European seasonal residents. Three-tier pricing structure across premium, standard, and economy levels separates Barcelona's Eixample dermatology centers from Madrid's medical spa chains and Andalusian compounding pharmacy outlets. Price differentiation hinges on practitioner certification tier under General Council of Official Medical College standards and geographic delivery cost from pharmaceutical logistics hubs. Cost compression in standard-tier toxin and filler bundles is intensifying because Basque Country regulatory arbitrage enables faster practitioner onboarding. Price-sensitive patients concentrate in Andalusia, while least-sensitive buyers cluster in Barcelona's cross-border premium corridor.
Supply Chain Analysis
EU MDR domestic-content documentation mandates are reshaping sourcing toward Barcelona and Madrid manufacturers with established notified body relationships. Raw material supply draws from Swiss fermentation partnerships for hyaluronic acid precursors, German precision optics for laser platforms, and Italian packaging specialists for cold-chain toxin distribution. Supply chain risk centers on single-source vulnerability in cross-linked hyaluronic acid fermentation capacity controlled by AbbVie and Galderma SA partnerships. Distribution runs through Madrid's pharmaceutical logistics hubs for neurotoxin cold-chain requirements, with secondary routing via Barcelona's clinic corridor for premium device installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's facial aesthetics sector offers margin expansion through declining energy-based device costs and premium-tier ultrasound adoption in Barcelona's Eixample district. Subscription-based maintenance programs shift revenue predictability upward while compressing acquisition spend per patient.
For Market Incumbents: Cement practitioner pool control by restructuring in-house training academies ahead of tightening Royal Decree 1277/2003 enforcement. Secure backward integration into hyaluronic acid precursor supply through specialized fermentation partnerships to defend against Galderma SA and AbbVie supply dominance. Energy-based device substitution from ultrasound tightening systems threatens filler margin pools in mature urban markets.
For New Entrants and Emerging Players: Capture underdeveloped medical spa density in Málaga and Sevilla relative to the Barcelona-Madrid axis, where northern European seasonal residents generate concentrated winter demand. Target Basque Country regulatory arbitrage for faster practitioner onboarding than Catalonia permits. Deploy convenience-focused subscription service formats with extended operating hours to differentiate from traditional hospital outpatient settings.
For Investors and Strategic Acquirers: Integrated dermatology platforms spanning prescription skincare to injectables are the most active acquirer in this space, consolidating backward integration into training academy operations. Long-term viability hinges on capturing lifetime patient value through converged service workflows rather than single-modality exposure. Watch EU MDR CE-marking certification timelines as inflection indicator for competitive windows in novel energy-based modalities.
| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Training Academy Acquisition | Secures Royal Decree 1277/2003 compliance capacity ahead of autonomous community enforcement divergence. |
| CE Marking Pathway Acceleration | EU MDR documentation advantages favor domestic Barcelona manufacturers with notified body relationships. |
| Medical Spa Chain Partnership | Captures subscription-based revenue predictability displacing transactional hospital outpatient models. |
| Hyaluronic Acid Fermentation Partnership | Reduces batch consistency risk from concentrated Swiss and German precursor supply chains. |
| Cross-Border Patient Acquisition Program | Portuguese and French consumers seeking specialized procedures anchor Barcelona Eixample premium pricing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aesthetic medicine practitioners, medical spa operators, dermatology center medical directors, and pharmaceutical distribution specialists with secondary validation. Primary sources included clinic chain executives, autonomous community health department officials, and biomedical device procurement managers. Secondary data drew from Spanish Agency for Medicines and Health Products filings, EU MDR transition documentation, General Council of Official Medical College accreditation records, and autonomous community health department circular guidance. Bottom-up service volume estimates triangulated against top-down pharmaceutical logistics flow data.
Historical reference periods anchored the forecast window through procedure volume baselines from medical spa expansion phases and energy-based device adoption curves. Segmentation dimensions modeled encompassed product type, end-user channel, application indication, and technology modality across the projection horizon. CAGRs derived from compounded annual procedure growth adjusted for practitioner supply constraints under evolving training interpretations. Forecast inputs included EU MDR compliance timeline assumptions and autonomous community regulatory enforcement divergence patterns.
Regulatory reinterpretation, raw material supply disruption, and cross-border patient flow volatility are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around training hour standardization and device certification pacing without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Radio Frequency Beauty Equipment Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Global Buttock Augmentation Market