
 Thin Film Drug Manufacturing Market | 2026-2036
Thin Film Drug Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Drug Manufacturing Market Outlook
Specialized pharmaceutical formulation chemists with thin-film polymer expertise is redrawing competitive boundaries across the value chain. Aquestive Therapeutics leverages its proprietary PharmFilm platform to dominate oral soluble film development for CNS and addiction therapies. LTS Lohmann Therapie-Systeme AG anchors European supply through integrated transdermal and oral film manufacturing in Germany and the United States. IntelGenx Corp. competes by specializing in vertically integrated R&D-to-commercial production for complex generic films.
Thin film drug manufacturing produces pharmaceutical dosage forms comprising active pharmaceutical ingredients embedded within polymeric matrices measuring typically 50 to 500 microns in thickness, designed for rapid dissolution or controlled permeation across mucosal or dermal surfaces. Solvent casting remains the dominant production method, though melt extrusion is displacing it for thermally stable APIs seeking continuous processing economies. Oral films lead volume consumption due to pediatric acceptance and dysphagia patient compliance advantages, while transdermal films sustain premium pricing through week-long dosing convenience in pain and hormone therapy. Immediate release formulations occupy the broadest addressable patient base, yet controlled release technology is capturing disproportionate R&D investment as patent cliffs erode conventional oral solid margins.
FDA's Quality by Design framework and EMA's Guideline on Pharmaceutical Development shape formulation standards and submission requirements for novel film products across the United States and European Union. The FDA's emerging guidance on 3D-printed pharmaceuticals and Japan's PMDA accelerated review pathways for pediatric-friendly dosage forms are creating differentiated regulatory tracks that favor manufacturers with pre-validated film platforms. Stakeholders must monitor how pharmacopeial standards for in-vitro dissolution testing evolve for non-conventional geometries, as harmonization gaps between USP, EP, and JP methods could fragment market access strategies.
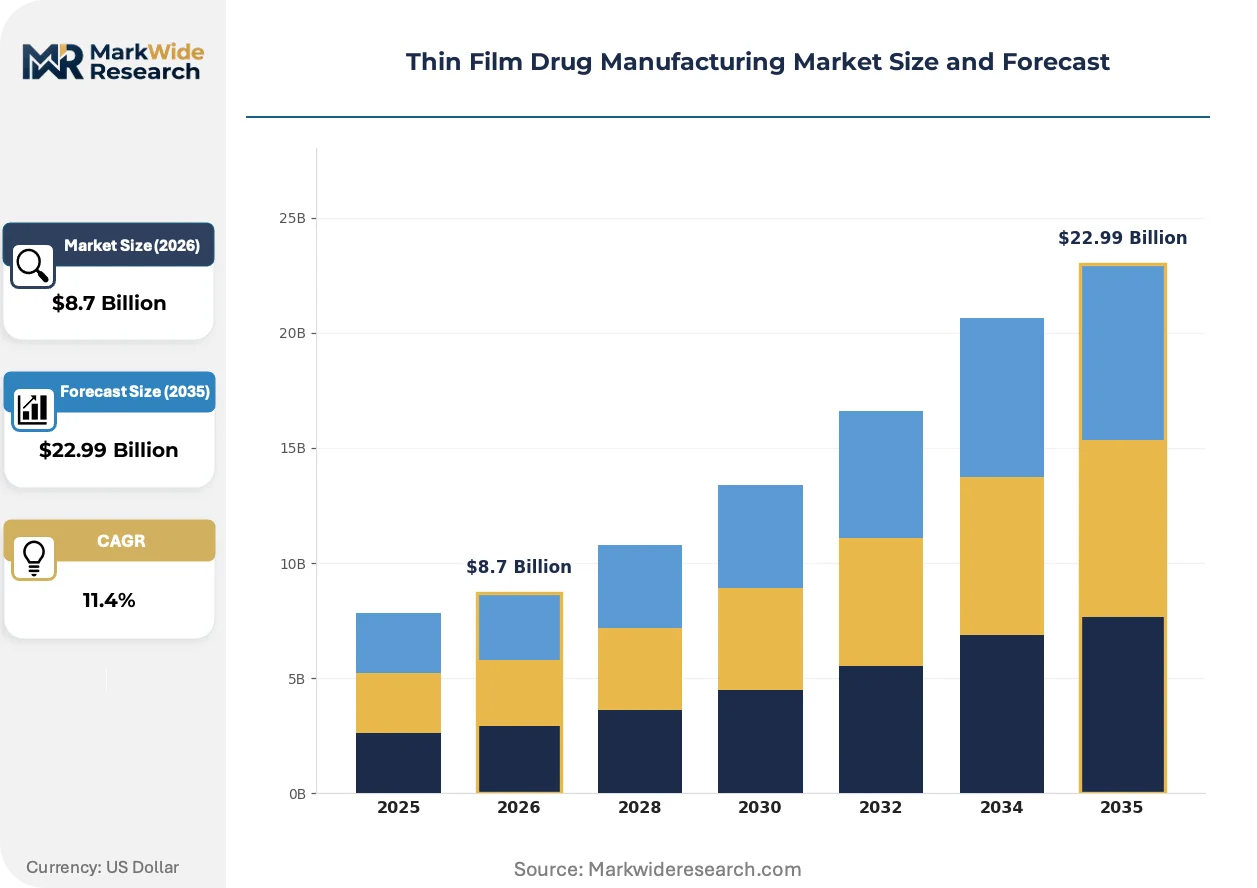
Market Dynamics
Solvent casting technology is ceding ground to continuous melt extrusion as manufacturers chase thermally stable API processing economies and reduced solvent-handling compliance burdens.
Growth Catalysts
- Pediatric Formulation Mandates:PMDA's accelerated review pathways for child-friendly dosage forms are pulling oral soluble films into Japan's pediatric therapeutic categories.
- EMA Guideline on Pharmaceutical Development:This framework streamlines novel film submission requirements across the European Union, compressing time-to-market for validated platform technologies.
- Dysphagia Patient Populations:Geriatric demographics in Germany and the United States are driving demand for orally disintegrating alternatives to conventional tablets.
Market Restraints
- Active Pharmaceutical Ingredient Thermal Sensitivity:Heat-labile compounds exclude roughly half of small-molecule candidates from melt extrusion processing, constraining platform scalability.
- Polymer Supply Concentration:Specialty hydroxypropyl methylcellulose grades for film substrates concentrate among three European chemical suppliers, creating input vulnerability.
- Harmonization Gaps in Dissolution Testing:Divergent USP, EP, and JP methods for non-conventional geometries force redundant validation studies for multi-territory launches.
Strategic Opportunities
- 3D-Printed Pharmaceuticals:FDA's emerging guidance on additive manufacturing for personalized dosing creates a differentiated regulatory track for precision film geometries.
- Transdermal Pain Therapy:Week-long controlled permeation formulations command premium pricing in Japan's aging demographic segments.
- Addiction Therapy Applications:Buprenorphine-naloxone films for opioid use disorder represent an underpenetrated therapeutic vertical with established reimbursement pathways in the United States.
Industry Challenges
- Thin-Film Polymer Expertise Scarcity:Formulation chemists with simultaneous mastery of API stability, mucosal adhesion, and continuous processing command salaries that compress mid-tier manufacturer margins.
- In-Vitro Dissolution Standardization Delays:Pharmacopeial method divergence between USP 4 flow-through cells and EP reciprocating cylinder apparatus forces parallel development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Drug Manufacturing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Films, Transdermal Films, Sublingual Films, Buccal Films Technology: Solvent Casting, Melt Extrusion, 3D Printing, Spray Coating End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals Formulation Type: Immediate Release, Controlled Release, Sustained Release, Combination Therapy |
| Companies Covered | IntelGenx Corp., Aquestive Therapeutics, Inc., ZIM Laboratories Limited, Tesa Labtec GmbH, LTS Lohmann Therapie-Systeme AG, Pfizer, Inc., Indivior PLC, Sumitomo Pharma Co., Ltd, NAL Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Drug Manufacturing Market Strategic Shifts
Melt extrusion equipment is bifurcating the production landscape as continuous processing economics reshape capital deployment patterns across formulation development.
Hot-melt extrusion technology embeds thermally stable APIs directly into polymer matrices without solvent recovery infrastructure. Chronic disease manufacturers in Germany and the United States are adopting twin-screw systems at accelerating pace. This shift is bifurcating the vendor base between solvent-casting incumbents and continuous-processing specialists.
REACH registration requirements for residual solvent classifications are tightening environmental compliance thresholds across European Union manufacturing sites. Film producers now face elevated documentation burdens for dichloromethane and ethanol handling. Transdermal manufacturing in Germany is responding by retrofitting closed-loop recovery systems ahead of 2025 substance evaluation deadlines.
Hospital formulary committees are consolidating purchasing authority for CNS and addiction therapy films under centralized pharmacy and therapeutics review. Specialty distributors in the United States are losing direct access to individual prescriber networks. This concentration is most visible in Veterans Health Administration procurement, where single-source agreements now cover multiple soluble film indications.
Thin Film Drug Manufacturing Market Segmentation
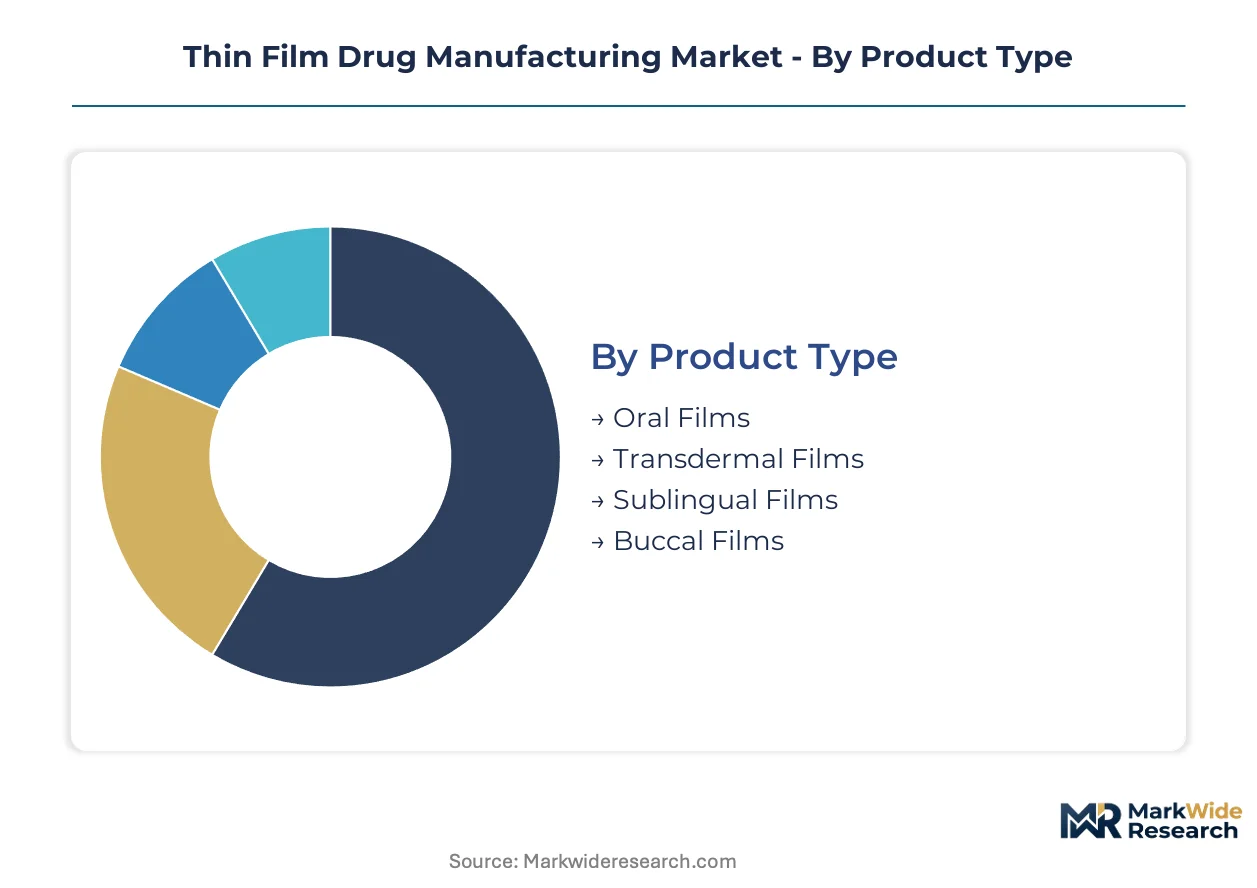
Thin film drug manufacturing segments reflect divergent technical requirements and regulatory pathways across patient populations. Manufacturers align production capabilities with specific film geometries and dissolution profiles to capture differentiated therapeutic applications.
Product Type:
Domestic demand concentrates in oral and transdermal formats across the United States, Germany, and Japan, while sublingual and buccal films serve export-led specialty therapeutic niches.
- Oral Films:Polymeric matrices measuring 50-500 microns dissolve rapidly on the tongue without water. Pediatric and geriatric dysphagia patients in the United States and Germany drive volume adoption for CNS and allergy therapies.
- Transdermal Films:Multi-layer adhesive systems enable controlled permeation across dermal surfaces for 7-day dosing cycles. Japan's aging demographic sustains premium pricing for pain and hormone replacement applications.
- Sublingual Films:Rapid mucosal absorption bypasses hepatic first-pass metabolism for emergency cardiovascular and antiemetic indications.
- Buccal Films:Adhesive formulations adhere to gingival tissue for localized or systemic delivery in dental and periodontal therapeutic categories.
Oral films command the established base. The steepest expansion runs through transdermal pain therapy segments in Japan's geriatric market.
Technology:
Cost tier differentiation separates capital-intensive continuous processing from batch solvent-casting infrastructure, with 3D printing occupying an emerging precision-dosing premium tier.
- Solvent Casting:Batch processing of API-polymer solutions onto release liners remains dominant for heat-labile compounds. REACH registration requirements for residual dichloromethane and ethanol handling elevate compliance costs across European Union manufacturing sites.
- Melt Extrusion:Twin-screw continuous processing embeds thermally stable APIs directly into polymer matrices without solvent recovery infrastructure. German and United States chronic disease manufacturers adopt these systems for thermally stable small molecules.
- 3D Printing:Additive manufacturing enables personalized dosing geometries with precision layer deposition. FDA emerging guidance creates a differentiated regulatory track for precision film production.
- Spray Coating:Atomized polymer deposition onto rotating substrates suits thin, uniform coatings for immediate-release applications with high surface-area requirements.
Solvent casting retains the volume base. The steepest technology shift runs through melt extrusion adoption for thermally stable API portfolios.
End User:
Customer type determines procurement authority concentration, with pharmaceutical companies consolidating formulation development while contract manufacturers capture outsourced commercial production.
- Pharmaceutical Companies:Integrated R&D-to-commercial operations control proprietary film platforms for CNS and addiction therapeutic verticals. Internal manufacturing protects process intellectual property for validated polymer matrices.
- Contract Manufacturers:Dedicated thin-film facilities serve mid-tier pharmaceutical clients lacking solvent-handling infrastructure or polymer formulation expertise. Capacity concentrates among German and United States specialists with integrated transdermal and oral film lines.
- Research Institutions:Academic and government laboratories develop novel mucoadhesive polymers and permeation enhancers for preclinical film characterization.
- Hospitals:Centralized pharmacy and therapeutics committees consolidate formulary purchasing for addiction therapy and emergency medicine film stocks.
Pharmaceutical companies anchor the revenue base. The steepest expansion trajectory runs through contract manufacturing partnerships for complex generic film launches.
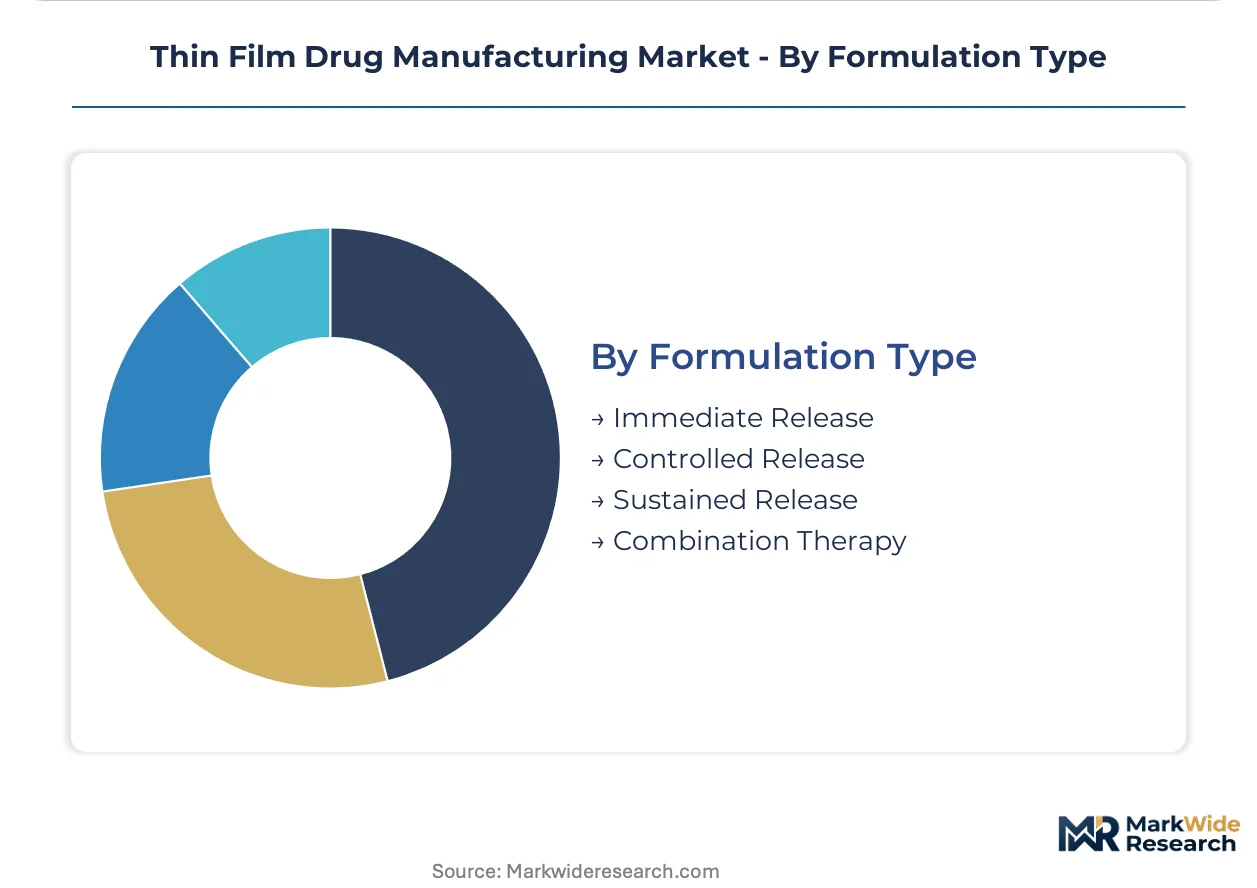
Formulation Type:
Maturity gradients separate established immediate-release formats from development-stage controlled-release platforms seeking patent-protected lifecycle extensions.
- Immediate Release:Rapid dissolution films disintegrate within seconds for acute symptom relief and pediatric compliance. Broadest addressable patient base spans allergy, nausea, and acute pain indications across United States and European Union markets.
- Controlled Release:Matrix or reservoir architectures modulate API diffusion kinetics for 12-24 hour plasma concentration profiles. Disproportionate R&D investment flows here as patent cliffs erode conventional oral solid margins.
- Sustained Release:Transdermal patch technologies maintain therapeutic levels across week-long wear periods for chronic pain and hormone replacement in Japan's aging population segments.
- Combination Therapy:Multi-API films deliver synergistic pharmacokinetic profiles for addiction therapy and cardiovascular disease management.
Immediate release formulations dominate the volume base. The steepest expansion runs through controlled-release platforms targeting chronic disease maintenance therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Quality by Design framework anchors the United States as the regulatory benchmark for thin film drug manufacturing, with EMA and PMDA pathways creating differentiated access corridors across Germany and Japan. Demand concentrates where pediatric formulation mandates and geriatric dysphagia populations intersect with validated polymer platforms.
United States
Veterans Health Administration procurement centralizes addiction therapy film purchasing under single-source agreements. FDA's emerging guidance on 3D-printed pharmaceuticals creates accelerated review tracks for personalized dosing geometries. Greater Philadelphia and Research Triangle Park host integrated oral soluble film development clusters serving CNS therapeutic verticals.
Germany
Geriatric dysphagia demographics in Bavaria and North Rhine-Westphalia drive demand for orally disintegrating alternatives to conventional tablets. REACH registration requirements for residual dichloromethane handling elevate compliance costs across solvent-casting facilities. The Lohmann group anchors European supply through integrated transdermal and oral film manufacturing in Andernach.
Japan
PMDA's accelerated review pathways for child-friendly dosage forms pull oral soluble films into pediatric therapeutic categories. METI's support for advanced manufacturing technologies underpins melt extrusion adoption for thermally stable APIs. Osaka-Kobe pharmaceutical corridor concentrates transdermal pain therapy production for week-long controlled permeation formulations.
India
CDSCO's streamlined approval pathways for complex generic films attract contract manufacturing partnerships from mid-tier pharmaceutical clients. Domestic demand for affordable oral disintegrating formats rises in pediatric and geriatric populations across Maharashtra and Gujarat. Ahmedabad and Hyderabad clusters specialize in solvent-casting infrastructure for heat-labile API portfolios.
Switzerland
Swissmedic's alignment with EMA guidelines enables concurrent EU market access for validated film platforms. Precision polymer formulation expertise concentrates in Basel's pharmaceutical corridor alongside legacy transdermal manufacturing capabilities. The country's chemical suppliers anchor specialty hydroxypropyl methylcellulose grades for European film substrate production.
Thin Film Drug Manufacturing Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in thin film drug manufacturing. Platform technology ownership separates proprietary film developers from contract manufacturing organizations lacking validated polymer matrices. Three archetypes dominate: integrated pharmaceutical companies with captive film platforms, dedicated thin-film specialists with end-to-end R&D-to-commercial capabilities, and regional contract manufacturers serving generic film launches. Competitive moves center on capacity expansion for continuous melt extrusion systems and strategic partnerships securing specialty polymer supply.
Within the integrated specialist tier, Aquestive Therapeutics and LTS Lohmann Therapie-Systeme AG exemplify platform-centric positioning through proprietary film technologies spanning multiple therapeutic categories. IntelGenx Corp. occupies a position among vertically integrated developers focusing on complex generic film commercialization. These three entities anchor competitive dynamics across North American and European supply corridors.
| Leading Market Players |
|---|
| IntelGenx Corp. |
| Aquestive Therapeutics, Inc. |
| ZIM Laboratories Limited |
| Tesa Labtec GmbH |
| LTS Lohmann Therapie-Systeme AG |
| Pfizer, Inc. |
| Indivior PLC |
| Sumitomo Pharma Co., Ltd |
| NAL Pharma |
| Others |
Value Chain & Pricing Dynamics
Twin-screw melt extrusion capacity utilization above 85% in Germany and the United States creates scale economies that compress unit costs for thermally stable APIs while simultaneously elevating price floors for solvent-casting batches handling heat-labile compounds. This bifurcation concentrates pricing power among continuous-processing specialists and fragments margin structures across batch-dependent manufacturers facing REACH compliance burdens.
Pricing Analysis
United States-Germany-Japan price spreads of 15-25% separate premium transdermal pain therapy films from standard oral soluble formats, with three-tier pricing structure across premium, standard, and economy levels anchored by formulation complexity and regulatory validation tier. FDA-validated platforms command brand premiums over CE-marked equivalents, while volume scale in Veterans Health Administration procurement drives cost compression in addiction therapy categories. Pricing pressure stems from polymer supply concentration among three European chemical suppliers, with contract manufacturers showing highest price sensitivity versus integrated pharmaceutical captives.
Supply Chain Analysis
Germany, the United States, and Switzerland anchor specialty hydroxypropyl methylcellulose substrate production for oral and transdermal film matrices. Raw material dependencies center on pharmaceutical-grade polymers, release liner substrates, and precision coating equipment sourced from established chemical and capital goods suppliers. Single-source vulnerability concentrates in specialty HPMC grades, with tariff exposure running through European Union REACH documentation requirements. Distribution runs through pharmaceutical company captive networks and contract manufacturing organizations serving mid-tier clients lacking in-house formulation infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation development services and regulatory submission support are expanding faster than base manufacturing revenues, creating attach-rate opportunities for platform-technology owners across the thin film value chain.
For Market Incumbents: Consolidate polymer formulation expertise through selective acquisition of specialty chemical suppliers in Switzerland and Germany, reducing exposure to three-supplier concentration in HPMC substrates. Expand twin-screw melt extrusion capacity in Research Triangle Park and Andernach to capture thermally stable API volume migrating from solvent casting. Defensive positioning requires pre-validation of polymer matrices against evolving FDA Quality by Design standards before patent cliffs erode oral solid margins. For New Entrants and Emerging Players: Complex generic film regulatory submission services represent an under-served layer where incumbents under-serve mid-tier pharmaceutical clients lacking thin-film polymer expertise. Target CDSCO-streamlined approval pathways in India for affordable oral disintegrating formats in pediatric and geriatric populations. Go-to-market positioning should emphasize vertically integrated R&D-to-commercial production capabilities that compress time-to-market versus platform-licensing dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with validated film platforms and long-term offtake agreements from pharmaceutical companies seeking to outsource solvent-handling infrastructure. Five-to-ten year viability favors specialists with simultaneous mastery of API stability, mucosal adhesion, and continuous processing. The acquisition target archetype combines proprietary PharmFilm-type platforms with established reimbursement pathways in CNS and addiction therapy verticals. Monitor pharmacopeial harmonization progress between USP, EP, and JP dissolution methods as inflection indicator for multi-territory launch scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Melt Extrusion Scale-Up | Twin-screw adoption in Germany and the United States captures thermally stable API volume from solvent casting. |
| Polymer Supply Backward Integration | Captive HPMC substrate production in Switzerland reduces dependency on three-supplier European concentration. |
| Regulatory Platform Pre-Validation | FDA Quality by Design alignment ahead of submission protects against evolving dissolution testing standards. |
| Pediatric Formulation Service Expansion | PMDA accelerated review pathway expertise in Japan creates differentiated access for child-friendly dosage forms. |
| Complex Generic Film Partnership | CDSCO streamlined approvals in India attract mid-tier pharmaceutical clients seeking outsourced commercial production. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with drug development executives, regulatory affairs leads, formulary directors at Veterans Health Administration and hospital pharmacy committees, and contract manufacturing organization operations heads. Secondary validation drew from FDA 510(k) and NDA filings, EMA marketing authorization applications, ClinicalTrials.gov protocol registries, and USP pharmacopeial method development records. Bottom-up patient population sizing for dysphagia and pediatric therapeutic categories was triangulated against top-down pharmaceutical company R&D pipeline disclosures.
Across the analysis window, volume and value outputs were modeled through segmented frameworks spanning product type, technology platform, end-user archetype, and formulation release profile, with regional regulatory clusters treated as distinct adoption corridors. CAGRs were derived from fitted growth curves calibrated to historical capacity expansion patterns and patent cliff timing for conventional oral solids. Forecast inputs incorporated REACH registration deadline impacts on solvent-casting economics and PMDA pediatric formulation mandate implementation trajectories.
Underlying assumptions cover stable polymer supply availability, regulatory pathway continuity, and API thermal stability profiles, with deviation risk concentrated in pharmacopeial harmonization delays and specialty chemical supplier consolidation. Recalibration cycles align with material shifts in FDA guidance issuance, EMA guideline revisions, and major pharmaceutical company platform technology licensing announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Alirocumab Market