
 Dental Crown Removal Market | 2026-2036
Dental Crown Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Crown Removal Market Outlook
Dental supply distribution through group purchasing organizations is reshaping how crown removal instruments reach clinics. Hu-Friedy (Steris Corporation) leverages its sterilization heritage to anchor credibility in infection-controlled environments. Dentsply Sirona competes through integrated digital workflows that bundle removal tools with CAD/CAM systems. Straumann Group extends its implantology dominance into adjacent restorative procedures, including crown management protocols.
Dental crown removal encompasses the controlled disengagement of fixed prosthetic restorations from prepared tooth structures, typically employing carbide burs, ultrasonic oscillating tips, or laser ablation systems operating at specific wavelength parameters to preserve underlying dentin integrity. The procedure type dimension shows ultrasonic removal gaining preference among clinicians seeking reduced patient trauma and faster chairside turnaround, while conventional extraction retains volume in cost-sensitive settings. Material type segmentation reveals ceramic crowns driving specialized instrument demand due to their brittle fracture behavior and zirconia's high flexural strength, which demands diamond-coated tips rather than standard carbide configurations.
The FDA's 510(k) clearance framework governs dental handpiece and laser device classifications in the United States, while the EU MDR and CE marking requirements regulate market access across European member states, with notified bodies intensifying scrutiny of active surgical instruments. Germany's KBA-equivalent medical device regulator, BfArM, coordinates with EMA-aligned standards for laser safety classifications in dental applications. Stakeholders must monitor evolving MDR technical documentation requirements and FDA guidance on ultrasonic device biocompatibility testing as these will determine which instrument portfolios retain commercial viability across major jurisdictions.
Market Dynamics
The transition from mechanical extraction to ultrasonic and laser-based crown removal is compressing procedure times while elevating capital requirements for general dentistry practices and specialized clinics.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter CE marking requirements for active surgical instruments are filtering out marginal manufacturers, concentrating demand among validated suppliers with established quality management systems.
- Zirconia crown proliferation:The material's superior flexural strength necessitates diamond-coated ultrasonic tips, expanding the addressable instrument market beyond standard carbide configurations.
- Germany's dense dental clinic network:High procedural volumes in Bavaria and North Rhine-Westphalia create concentrated demand pockets for premium removal systems.
Market Restraints
- Capital intensity of laser systems:Erbium and diode laser platforms require substantial upfront investment, limiting adoption to high-volume practices and creating a two-tier equipment landscape.
- Diamond abrasive supply concentration:Synthetic diamond coating supply chains cluster in specific manufacturing regions, exposing instrument makers to input cost volatility and qualification delays.
- FDA 510(k) clearance timelines:Biocompatibility testing requirements for ultrasonic device materials extend regulatory pathways, compressing effective product lifecycles before obsolescence.
Strategic Opportunities
- Digital workflow integration:CAD/CAM system convergence with crown removal protocols enables bundled instrumentation sales and recurring consumable revenue streams.
- Group purchasing organization channel expansion:Consolidated procurement through dental supply networks reduces customer acquisition costs for instrument manufacturers.
- Ultrasonic tip standardization:Emerging ISO compatibility standards create openings for aftermarket tip suppliers to challenge OEM lock-in strategies.
Industry Challenges
- Laser safety certification complexity:Operator training requirements and facility compliance with wavelength-specific safety protocols slow chairside adoption despite clinical benefits.
- Legacy handpiece interoperability:Multi-brand dental unit installations create integration friction for standardized removal system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Crown Removal Market |
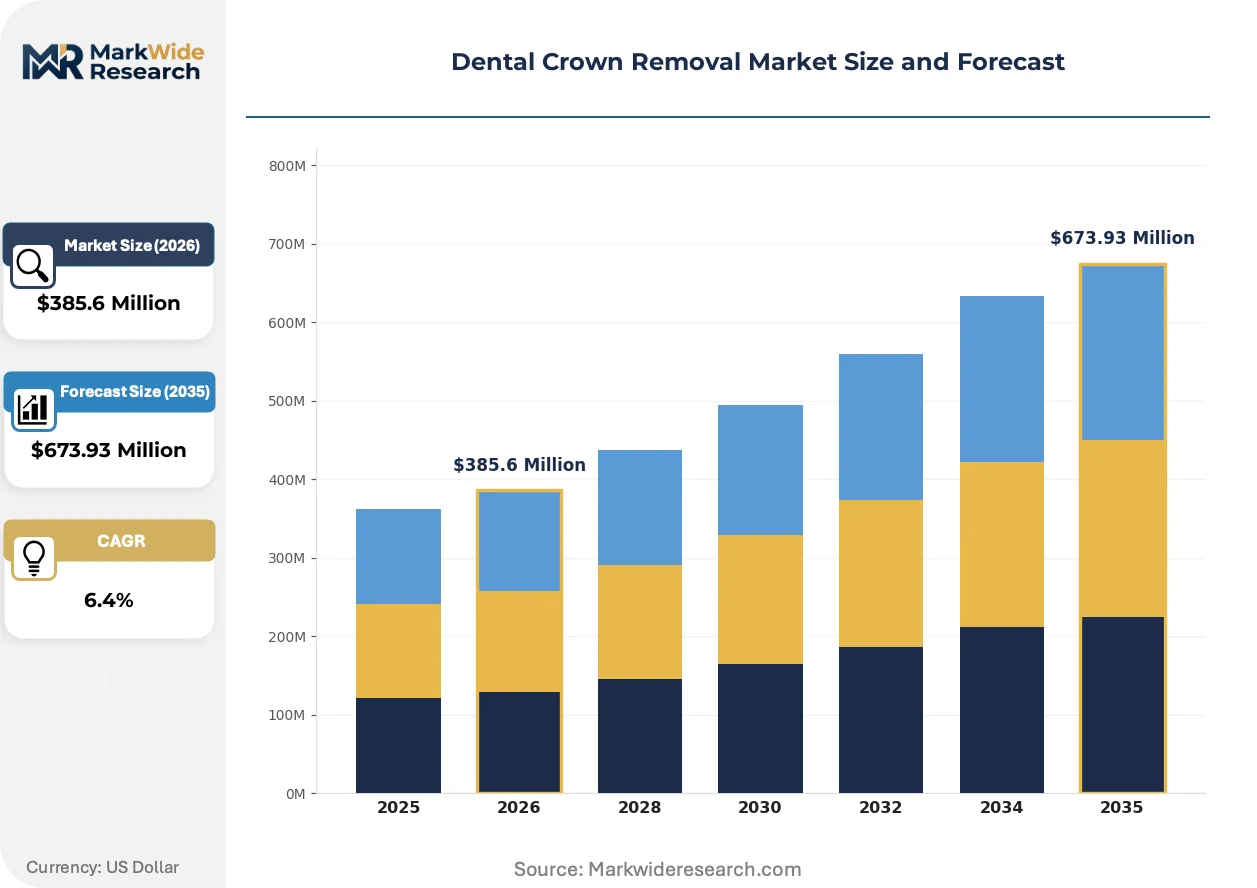
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Conventional Extraction, Ultrasonic Removal, Mechanical Removal, Laser Removal Material Type: Ceramic, Metal, Resin, Composite End User: Dentists, Oral Surgeons, Dental Clinics, Dental Labs Patient Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Komet Dental, 3M Company, Hu-Friedy (Steris Corporation), NSK Dental, J&J Instruments, Inc., Planmeca Group, Straumann Group, A.Titan Instruments, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Crown Removal Market Strategic Shifts
Ultrasonic oscillation technology is displacing conventional rotary instrumentation as clinicians prioritize dentin preservation and reduced patient trauma.
Piezoelectric ultrasonic systems operating at 25-30 kHz frequencies deliver controlled mechanical energy that fractures cement layers without compromising underlying tooth structure. General dentistry practices in Germany and the United States are retrofitting existing handpiece connections to accommodate these platforms. The technology is rendering obsolete high-speed carbide bur protocols that risk iatrogenic damage during forceful crown elevation.
The EU MDR's intensified scrutiny of active surgical instruments is extending technical documentation requirements for ultrasonic and laser devices. Notified bodies now demand comprehensive biocompatibility dossiers and clinical performance data that exceed previous CE marking thresholds. German manufacturers leveraging existing ISO 13485 quality systems are accelerating certification timelines while smaller competitors face portfolio rationalization pressures.
Group purchasing organizations are consolidating procurement decisions for crown removal instruments across multi-clinic dental networks. Independent practices in cost-sensitive regions are surrendering individual vendor relationships to access volume-negotiated pricing tiers. This concentration is most visible in the United States, where DSO-affiliated locations now represent a dominant share of ultrasonic system installations.
Dental Crown Removal Market Segmentation
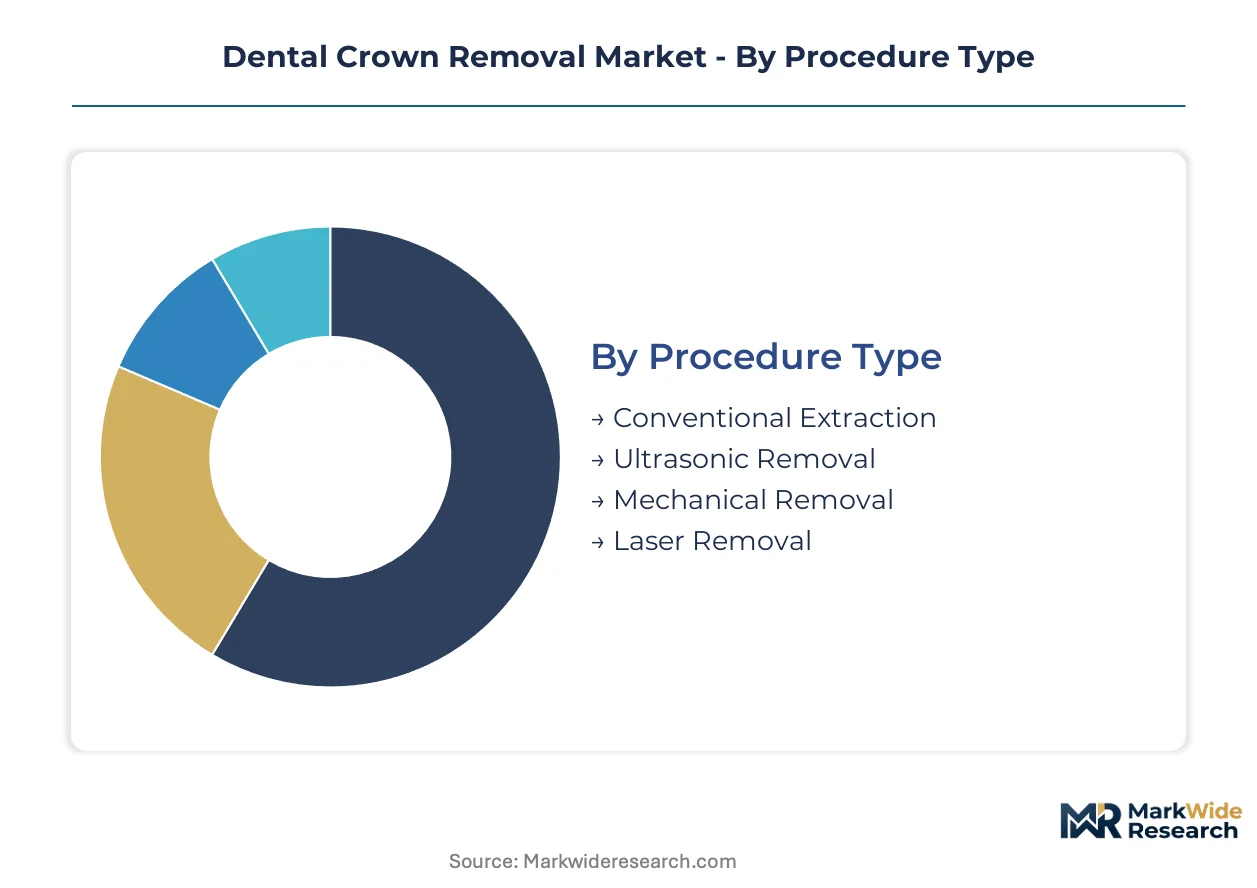
Segmentation in the dental crown removal market reveals distinct procurement patterns across clinical settings and patient populations. Procedure complexity, material brittleness, and operator specialization drive instrument selection at the point of care.
Procedure Type:
The use-case spectrum spans from high-speed mechanical disruption to precision energy-based separation, with each modality matching specific crown-cement combinations and preservation priorities.
- Ultrasonic Removal:Piezoelectric systems operating at 25-30 kHz frequencies fracture cement layers through controlled mechanical oscillation. German general dentistry practices in Bavaria and North Rhine-Westphalia are retrofitting handpiece connections to accommodate these platforms, prioritizing dentin preservation and reduced patient trauma.
- Laser Removal:Erbium and diode laser platforms deliver wavelength-specific energy for photochemical cement degradation. Adoption concentrates in high-volume US practices seeking faster chairside turnaround, constrained by capital intensity and FDA 510(k) clearance timelines for biocompatibility testing.
- Conventional Extraction:Rotary carbide burs remain prevalent in cost-sensitive settings where equipment retrofitting is deferred.
- Mechanical Removal:Crown elevators and forceps-based protocols persist for provisional restorations and emergency scenarios.
The dominant share belongs to conventional extraction, while ultrasonic removal is closing the gap fastest.
Material Type:
Material brittleness and flexural strength dictate instrument coating specifications and tip geometries across manufacturing tiers.
- Ceramic:Brittle fracture behavior of feldspathic and lithium disilicate crowns demands specialized diamond-coated ultrasonic tips rather than standard carbide configurations. Zirconia's superior flexural strength expands addressable instrument markets beyond legacy configurations.
- Metal:Precious and non-precious alloy crowns accommodate broader instrument compatibility, sustaining volume in traditional extraction protocols.
- Resin:Provisional polymer-based restorations yield to lower-force mechanical removal.
- Composite:Direct composite provisional crowns require minimal intervention instrumentation.
Ceramic crowns command the premium instrument tier, with zirconia variants expanding most quickly.
End User:
Procurement authority and volume scale separate institutional purchasers from independent operators across the supply chain.
- Dental Clinics:Multi-chair facilities and dental service organizations consolidate procurement through group purchasing organizations, negotiating volume-tiered pricing for ultrasonic system installations.
- Dentists:Independent general practitioners retain individual vendor relationships in cost-sensitive regions, though DSO-affiliated locations now represent dominant share in the United States.
- Oral Surgeons:Hospital-based and ambulatory surgical centers prioritize laser platforms for complex cases.
- Dental Labs:Removable prosthesis fabricators influence upstream instrument specification through restoration design feedback.
Dental clinics capture the dominant procurement volume, while dental service organization consolidation is gaining share fastest.
Patient Age Group:
Anatomical variation and restoration longevity expectations shape procedural approach selection across demographic cohorts.
- Adult:Working-age patients with mixed restoration histories generate the highest procedural volumes, balancing preservation priorities with time constraints.
- Geriatric:Aging populations with decades-old cemented crowns present complex removal scenarios involving compromised dentin and multi-unit prostheses.
- Pediatric:Primary tooth stainless steel crowns and preformed pediatric restorations require specialized miniature instrument configurations.
- Others:Patients with developmental anomalies or trauma-related provisional restorations fall outside standard demographic classification.
The adult segment anchors procedure volume, while geriatric cases are climbing the fastest as restoration cohorts age into removal windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's 510(k) clearance framework governs dental handpiece and laser device classifications in the United States, while parallel regulatory architectures in Germany and Japan shape instrument certification pathways across their respective domestic markets.
United States
High-volume dental service organizations in Texas and Florida are consolidating procurement decisions for ultrasonic removal systems through group purchasing organizations. The FDA's biocompatibility testing requirements for ultrasonic device materials extend regulatory pathways, compressing effective product lifecycles. California's dense network of specialized dental clinics in Los Angeles and San Francisco generates concentrated demand pockets for premium laser platforms.
Germany
Bavaria and North Rhine-Westphalia host dense concentrations of specialized dental clinics performing high procedural volumes of crown removal. The BfArM coordinates with EMA-aligned standards for laser safety classifications in dental applications. Stuttgart's precision manufacturing cluster supplies diamond-coated ultrasonic tips to instrument makers serving the broader European market.
Japan
Tokyo and Osaka metropolitan areas concentrate demand for minimally invasive crown removal technologies among aging patient populations. The PMDA oversees medical device approvals under harmonized IMDRF guidelines, with METI supporting domestic manufacturing competitiveness. Nagoya's industrial belt hosts suppliers of piezoelectric ceramics for ultrasonic handpiece fabrication.
China
Shanghai and Beijing dental hospitals are piloting laser-based removal protocols for complex zirconia crown cases. The NMPA's medical device classification system governs market access, with provincial procurement platforms increasingly centralizing purchasing decisions. Shenzhen's electronics manufacturing ecosystem supplies control circuitry for ultrasonic system OEMs.
South Korea
Seoul Capital Area clinics are retrofitting handpiece connections to accommodate 25-30 kHz piezoelectric systems. The MFDS maintains stringent active surgical instrument standards aligned with EU MDR technical documentation requirements. Busan's medical device manufacturing zone produces ultrasonic generators for regional export markets.
Dental Crown Removal Market Competitive Environment
Integrated dental technology conglomerates and specialized instrument fabricators split the market between bundled digital workflow solutions and focused removal system expertise. The vendor landscape exhibits moderate consolidation, with sterilization heritage players leveraging infection-control credibility against CAD/CAM-integrated competitors. Two strategic archetypes dominate: full-platform dental technology providers and precision instrument specialists. Competitive moves center on digital workflow bundling and group purchasing organization channel penetration.
Among US-based multinationals, 3M Company and Dentsply Sirona exemplify the platform-integrated archetype, while Hu-Friedy (Steris Corporation) occupies a position anchored in sterilization heritage. Straumann Group represents the implantology-extended archetype, applying adjacent restorative expertise to crown management protocols. These three companies illustrate the competitive tension between bundled system sales and specialized instrument focus.
| Leading Market Players |
|---|
| Komet Dental |
| 3M Company |
| Hu-Friedy (Steris Corporation) |
| NSK Dental |
| J&J Instruments, Inc. |
| Planmeca Group |
| Straumann Group |
| A.Titan Instruments |
| Dentsply Sirona |
| Others |
Value Chain & Pricing Dynamics
Synthetic diamond coating production clusters in Stuttgart's precision manufacturing belt and select East Asian industrial zones, anchoring margin capture among instrument makers who control abrasive supply relationships with dental OEMs. This upstream concentration shapes downstream pricing power, as diamond-coated ultrasonic tip specifications command premium positioning against standard carbide configurations.
Pricing Analysis
German clinics pay 15-25% above US Midwest averages for identical ultrasonic handpiece platforms, reflecting VAT-inclusive procurement and stricter MDR documentation costs passed through by CE-marked suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified manufacturers from regional assemblers and gray-market imports. Pricing pressure stems from group purchasing organization consolidation in US dental service organizations, squeezing independent vendor margins. Independent general practitioners exhibit highest price sensitivity, while hospital-based oral surgery centers prioritize performance over acquisition cost.
Supply Chain Analysis
Contract manufacturing for piezoelectric ceramic transducers concentrates at Nagoya's industrial belt suppliers and Busan's medical device zone, with final instrument assembly distributed across German, US, and South Korean OEM facilities. Raw material dependencies encompass synthetic diamond abrasives, zirconia ceramic substrates, and precision-machined titanium handpiece housings. Single-source vulnerability in diamond coating qualification exposes instrument makers to six-month revalidation delays if primary suppliers falter. Distribution runs through dental supply group purchasing organizations and specialized instrument distributors serving multi-clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-based crown removal platforms threaten ultrasonic system incumbents by compressing procedure times further, forcing established players to defend installed base through workflow integration and tip standardization strategies.
For Market Incumbents: Entrench market position by securing exclusive group purchasing organization contracts that bundle ultrasonic generators with proprietary tip cartridges, creating switching costs against laser alternatives. Deepen backward integration into diamond coating capabilities to insulate margin from synthetic abrasive supply volatility. Prioritize ISO 13485 certification maintenance to accelerate EU MDR technical documentation against smaller competitors facing portfolio rationalization. For New Entrants and Emerging Players: Mid-market dental clinics in China's provincial capitals represent the most penetrable entry point, as centralized hospital procurement pilots create reference sites for laser platform adoption. Aftermarket ultrasonic tip manufacturing for legacy handpiece connections offers lower capital barrier to revenue, exploiting emerging ISO compatibility standards that weaken OEM lock-in. Target value-engineered piezoelectric systems priced between premium German platforms and economy-tier alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward precision instrument specialists with captive diamond coating technology and established FDA 510(k) clearance track records, as regulatory barriers widen moats against commoditization. Long-term viability hinges on digital workflow convergence capabilities that position crown removal tools within CAD/CAM ecosystem bundling. Monitor EU MDR notified body backlog resolution as inflection signal for European market access timelines and competitive consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Early MDR technical documentation submission secures priority queue positioning against competitor portfolio delays. |
| Group Purchasing Organization Partnership | Exclusive supply agreements with DSO-affiliated networks lock in recurring consumable revenue streams. |
| Diamond Coating Backward Integration | In-house abrasive qualification reduces input cost volatility and accelerates tip development cycles. |
| Digital Workflow Integration | CAD/CAM system bundling positions removal instruments within comprehensive restorative protocol suites. |
| Ultrasonic Tip Standardization Drive | ISO compatibility advocacy opens aftermarket challenge to OEM proprietary connection strategies. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) device filings, EU MDR notified body documentation, and dental supply procurement databases. Primary interviews encompassed clinicians in German specialized clinics, biomedical engineers at ultrasonic handpiece OEMs, group purchasing organization contracts managers, and dental service organization procurement directors. Secondary validation drew from BfArM laser safety classifications, PMDA medical device approval records, and hospital procurement platform disclosures. Bottom-up instrument shipment data triangulated against top-down dental procedure volume estimates.
Forecast inputs span procedure type substitution rates, material-specific instrument demand coefficients, and regulatory pathway duration assumptions across the projection horizon. Segmentation dimensions modeled encompass procedure modality, crown material composition, end-user procurement authority, and patient age cohort. CAGRs derived from logistic diffusion curves fitted to ultrasonic adoption patterns, adjusted for capital intensity constraints in cost-sensitive settings. Industry-specific inputs include zirconia crown proliferation rates and dental service organization consolidation trajectories.
Practitioners should monitor EU MDR notified body capacity constraints, FDA biocompatibility testing guideline revisions, and synthetic diamond supply chain disruptions for early signals of forecast deviation. Quarterly review of group purchasing organization contract awards and ultrasonic system retrofit installation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Root Canal Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Global Dental Labs Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental CAD Market
Dental Devices
Dental Laboratories Market
Dental Devices
Dental Floss Market
Dental Devices
Dental Impression System Market