
 Telogen Effluvium Treatment Market | 2026-2036
Telogen Effluvium Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Telogen Effluvium Treatment Market Analytics
Specialty dermatology distribution is fragmenting as telehealth platforms and direct-to-consumer channels erode traditional clinic-centric prescribing. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf presence across retail pharmacy networks. Merck & Co. anchors its position through prescription-grade formulations targeted at clinic-administered protocols. Pfizer competes by extending its dermatology portfolio into combination therapies that address underlying metabolic triggers.
Telogen effluvium treatment encompasses pharmacological and device-based interventions designed to arrest excessive hair shedding and restore normal follicular cycling, typically involving topical minoxidil formulations at concentrations between two and five percent, oral nutritional supplementation, and low-level laser devices operating at wavelengths of 630 to 660 nanometers. Oral supplements and prescription-grade topical solutions capture the deepest margin pools due to recurring purchase patterns and physician gatekeeping. Hair growth devices represent the fastest-expanding delivery mode as at-home laser caps and combs gain clinical validation and reimbursement traction in select markets.
The FDA regulates topical minoxidil and laser devices under distinct pathways, with the latter requiring 510(k) clearance that shapes product development timelines and marketing claims. EMA's Medical Device Regulation imposes stricter clinical evidence standards on European manufacturers, while India's CDSCO oversees import licensing for active pharmaceutical ingredients used in generic formulations. Stakeholders must monitor evolving device classification precedents and reimbursement coding decisions that will determine which delivery modes achieve scalable clinical adoption.
Market Dynamics
Specialty dermatology clinics are consolidating diagnostic and therapeutic workflows into integrated hair wellness protocols, compressing patient pathways from initial consultation to treatment initiation while elevating physician gatekeeping over self-directed consumer purchases.
Growth Catalysts
- Low-level laser therapy clinical validation:FDA 510(k) clearance pathways for at-home laser caps and combs are accelerating device commercialization and expanding reimbursable indications beyond clinic-administered protocols.
- Metabolic trigger recognition:Endocrinology practices are integrating hair shedding assessment into thyroid and insulin resistance workups, expanding referral volumes into dermatology channels.
- India CDSCO import licensing reforms:Streamlined active pharmaceutical ingredient approvals for generic minoxidil formulations are reducing supply bottlenecks and enabling cost-accessible topical solutions.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India dominate minoxidil API manufacturing, creating geopolitical exposure and price volatility for finished topical formulators.
- Laser device reimbursement coding gaps:CMS and private payers lack consistent Category III CPT codes for at-home photobiomodulation, limiting patient out-of-pocket conversion rates.
- Oral supplement efficacy skepticism:Biotin and zinc formulations face substitution pressure from prescription-grade alternatives as clinicians prioritize evidence-based protocols.
Strategic Opportunities
- Telehealth platform integration:Virtual dermatology consultations are opening direct-to-patient prescribing channels that bypass traditional clinic wait times and geographic access barriers.
- Combination therapy protocols:Convergence of topical minoxidil with low-level laser devices and oral nutritional supplementation is creating premium service bundles with recurring revenue structures.
- EMA Medical Device Regulation harmonization:Stricter European clinical evidence standards are creating competitive moats for manufacturers with robust trial data, disadvantaging low-cost entrants.
Industry Challenges
- Follicular biology expertise scarcity:Dermatology practices struggle to recruit clinicians with specialized trichology training, limiting protocol standardization and patient throughput capacity.
- Laser device manufacturing capex intensity:Precision wavelength calibration and optical component sourcing require significant upfront investment, constraining mid-scale market entry.
- 510(k) predicate device navigation:FDA clearance pathways demand extensive equivalence demonstrations that extend development timelines and compress marketing claim flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telogen Effluvium Treatment Market |
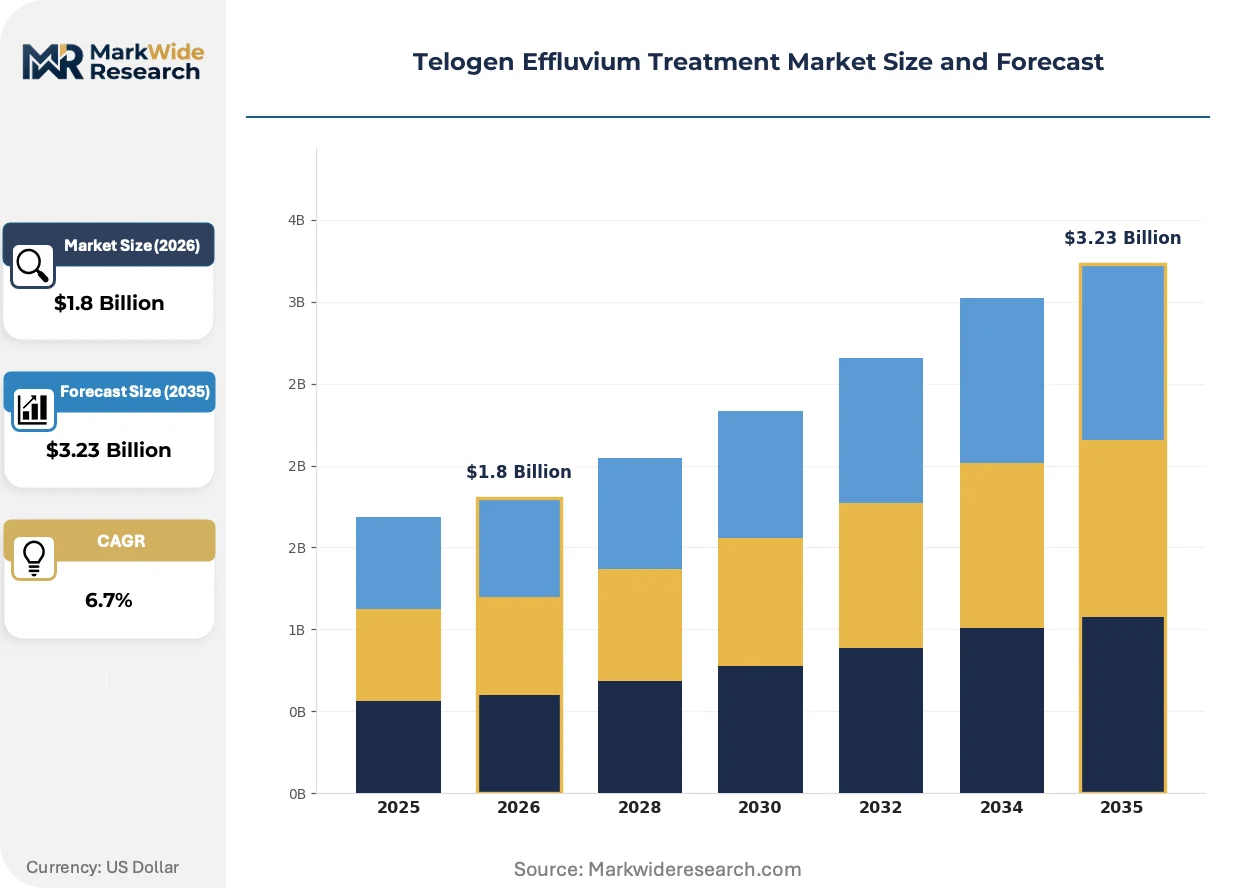
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Oral Supplements, Hair Growth Devices, Shampoo Delivery Mode: Prescription, Over-the-Counter, Home Remedies, Professional Treatment End User: Individuals, Dermatology Clinics, Wellness Centers, Pharmacies Application: Preventive Treatment, Regrowth, Maintenance, Hair Restoration |
| Companies Covered | Johnson & Johnson, Merck & Co., Inc., Pfizer Inc., Eli Lilly and Company, Cipla Limited, Sun Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd, GlaxoSmithKline plc, Lexington International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telogen Effluvium Treatment Market Evolving Landscape
Photobiomodulation technology is converging with digital health monitoring, creating connected treatment ecosystems that track adherence and physiological response while reshaping how clinicians and patients manage chronic hair shedding conditions.
Low-level laser therapy is hybridizing with scalp microbiome analysis and biomarker tracking to create personalized treatment algorithms. Dermatology chains and medispas are adopting these integrated platforms to differentiate service offerings and improve patient retention. The convergence is compressing margins for standalone device manufacturers while elevating subscription-based platform providers.
EMA's Medical Device Regulation is imposing stricter post-market surveillance and clinical evidence requirements on European laser device manufacturers. Companies must now maintain active registries and periodic safety reporting that increase compliance overhead. Smaller device makers are exiting the European market or seeking notified body partnerships in Switzerland and the United Kingdom.
Patients are gravitating toward physician-supervised regimens over self-directed retail purchases, reversing earlier direct-to-consumer momentum. Telehealth platforms and concierge dermatology practices are capturing this preference shift through membership models that bundle diagnostics, prescription topicals, and device access. The United States exhibits the strongest concentration of this behavior, with urban coastal markets leading subscription enrollment rates.
Telogen Effluvium Treatment Market Segmentation
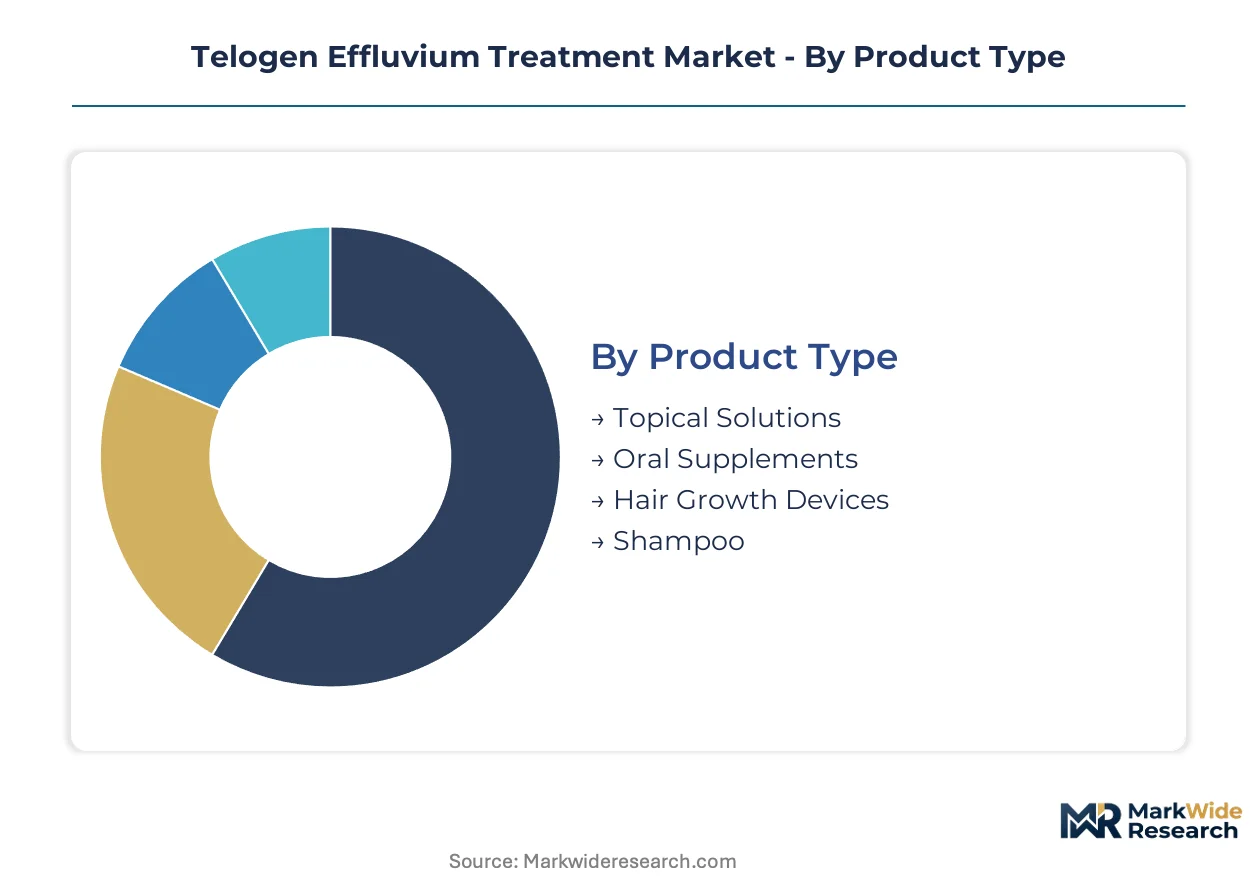
Segmentation in telogen effluvium treatment reveals how patient preferences, clinical settings, and reimbursement pathways fragment demand across distinct commercial channels. Understanding these divisions exposes where margin pools concentrate and which delivery modes face substitution pressure from adjacent categories.
Product Type:
Cost tiers within this category stratify sharply between commodity formulations and premium device-based interventions, with recurring purchase patterns and clinical validation levels determining profitability.
- Topical Solutions:Minoxidil-based formulations at two to five percent concentration dominate prescription and retail channels. Physician gatekeeping in the United States sustains premium pricing for clinic-dispensed variants against mass-market alternatives.
- Oral Supplements:Biotin, zinc, and iron formulations target nutritional deficiency triggers. Efficacy skepticism from clinicians limits expansion as prescription-grade alternatives gain protocol preference.
- Hair Growth Devices:Low-level laser caps and combs operating at 630 to 660 nanometers. FDA 510(k) clearance accelerates commercialization while reimbursement coding gaps constrain patient conversion.
- Shampoo:Ketoconazole and caffeine-infused formulations serve adjunctive maintenance roles. Pharmacy retail networks capture volume through impulse placement alongside core therapies.
Topical solutions command the established base. The steepest expansion runs through hair growth devices.
Delivery Mode:
Application context determines regulatory burden, pricing flexibility, and patient adherence monitoring capabilities across this dimension.
- Prescription:Clinic-administered protocols and physician-dispensed formulations require FDA or EMA marketing authorization. The United States exhibits strongest concentration as consumers seek supervised regimens over self-directed care.
- Over-the-Counter:Retail pharmacy and e-commerce channels for minoxidil and supplement formulations. Johnson & Johnson leverages consumer health infrastructure to sustain shelf presence across these networks.
- Home Remedies:Unregulated botanical and essential oil preparations. Substitution pressure intensifies as clinical validation standards rise and telehealth platforms steer patients toward evidence-based alternatives.
- Professional Treatment:Medispa and dermatology clinic protocols combining devices with topical application. Membership models bundling diagnostics and device access are climbing the fastest in urban coastal markets.
Over-the-counter channels anchor volume throughput. Professional treatment modalities are gaining share fastest through subscription-based platform expansion.
End User:
Customer type fragmentation reflects the tension between convenience-seeking individual purchasers and clinically supervised institutional protocols.
- Individuals:Direct-to-consumer purchasers through retail and telehealth channels. Geographic access barriers and wait times increasingly drive migration toward virtual dermatology consultations.
- Dermatology Clinics:Specialty practices consolidating diagnostic and therapeutic workflows into integrated hair wellness protocols. Follicular biology expertise scarcity limits patient throughput capacity.
- Wellness Centers:Medispa and aesthetic chains adopting photobiomodulation with scalp microbiome analysis. These platforms differentiate through personalized treatment algorithms and biomarker tracking.
- Pharmacies:Community and retail chains dispensing OTC formulations and fulfilling telehealth prescriptions. Inventory concentration in topical minoxidil and oral supplements sustains recurring foot traffic.
Dermatology clinics retain the premium positioning anchor. Wellness centers are expanding most quickly as aesthetic chains capture preference shifts toward bundled service experiences.
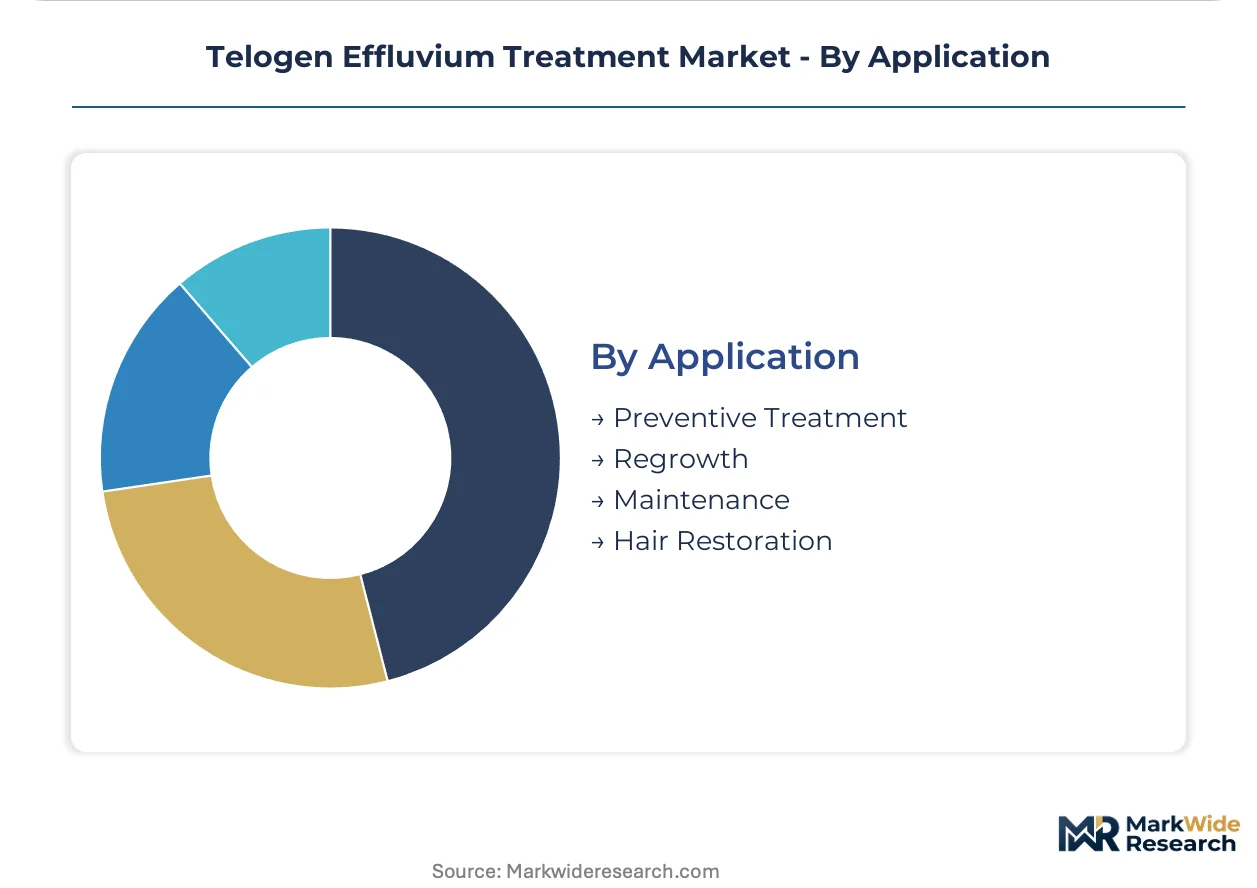
Application:
Volume distribution across this category tracks disease progression stages and patient lifecycle value, with preventive and maintenance phases offering superior recurring revenue economics.
- Preventive Treatment:Early intervention for stress-triggered or postpartum shedding before follicular miniaturization advances. Endocrinology practices in the United States are integrating hair assessment into thyroid and insulin resistance workups, expanding referral volumes.
- Regrowth:Active restoration protocols targeting visible thinning and scalp coverage deficits. Combination therapy convergence of topical minoxidil with laser devices and oral supplementation creates premium service bundles.
- Maintenance:Long-term adherence programs to sustain anagen phase extension and prevent relapse. Subscription models and connected treatment ecosystems improve retention through adherence tracking.
- Hair Restoration:Adjunctive support for surgical transplant recipients. Clinic-administered protocols dominate as surgeons require standardized pre- and post-operative care pathways.
Regrowth applications capture the highest per-patient revenue concentration. Preventive treatment is climbing the fastest as metabolic trigger recognition expands diagnostic touchpoints upstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution infrastructure underwrites Europe's role in finished formulation logistics, while Singapore's Changi cargo hub anchors Asia-Pacific API transshipment. These physical networks determine where regulatory filings concentrate and which markets achieve first-mover device clearance.
United States
Telehealth platforms and concierge dermatology practices drive preference for physician-supervised regimens over self-directed retail purchases. FDA 510(k) clearance pathways for low-level laser devices reshape product development timelines and marketing claims flexibility. Urban coastal markets lead subscription enrollment rates for bundled diagnostics and device access protocols.
Germany
EMA Medical Device Regulation imposes stricter post-market surveillance requirements on laser device manufacturers, increasing compliance overhead. Munich and Frankfurt host notified body partnerships that smaller device makers seek to maintain European market presence. Clinical evidence standards create competitive moats for manufacturers with robust trial data.
India
CDSCO import licensing reforms for active pharmaceutical ingredients reduce supply bottlenecks for generic minoxidil formulations. Hyderabad and Ahmedabad concentrate finished topical manufacturing capacity serving export markets. Cost-accessible solutions enable volume expansion across price-sensitive patient segments.
Japan
PMDA marketing authorization requirements sustain premium pricing for prescription-grade formulations against mass-market alternatives. Tokyo-Osaka corridor dermatology chains consolidate diagnostic and therapeutic workflows into integrated hair wellness protocols. Metabolic trigger recognition expands endocrinology referrals into specialty channels.
United Kingdom
Post-Brexit regulatory divergence from EMA MDR creates parallel compliance pathways for device manufacturers. London's Harley Street medical district anchors premium clinic-administered protocol demand. Telehealth platform integration opens direct-to-patient prescribing channels that bypass traditional geographic access barriers.
Telogen Effluvium Treatment Market Competitive Landscape
On the supply side, the industry is tiered between multinational pharmaceutical conglomerates with prescription-grade portfolios, consumer health specialists leveraging retail pharmacy infrastructure, and emerging device manufacturers navigating 510(k) clearance pathways. Three archetypes dominate: legacy drug makers with dermatology divisions, diversified consumer health platforms, and precision photobiomodulation specialists. Consolidation pressure intensifies through strategic partnerships combining pharmaceutical formulations with connected device ecosystems, while geographic expansion targets regulatory harmonization arbitrage between FDA and EMA jurisdictions.
Among US-based pharmaceutical conglomerates, Johnson & Johnson, Merck & Co., Inc., and Pfizer Inc. exemplify distinct competitive positioning archetypes. Johnson & Johnson occupies the consumer health infrastructure anchor role, Merck & Co., Inc. sits within the prescription-grade formulation specialist tier, and Pfizer Inc. represents the diversified dermatology portfolio extender. Each structure determines channel access and pricing flexibility against evolving reimbursement coding decisions.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Cipla Limited |
| Sun Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd |
| GlaxoSmithKline plc |
| Lexington International LLC |
| Others |
Value Network & Pricing Analysis
China and India dominate minoxidil active pharmaceutical ingredient manufacturing, concentrating upstream supply power in the hands of a limited supplier base and compressing margin pools for finished topical formulators downstream. This geographic concentration creates tiered pricing power where API contract terms directly shape profitability across prescription and retail channels.
Pricing Analysis
Volume-discount tiering structures separate clinic-dispensed prescription formulations from mass-market retail alternatives, with physician gatekeeping sustaining premium positioning for supervised protocols. Price differentiation rests on FDA marketing authorization status and clinical validation depth, with certified 510(k) laser devices commanding substantial premiums over uncertified imports. Cost compression in generic topical segments is intensifying because CDSCO licensing reforms expanded API supplier pools. Individual consumers through direct-to-consumer channels exhibit highest price sensitivity, while dermatology clinic procurement committees prioritize clinical evidence over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with Hyderabad and Ahmedabad-based finished topical producers serving export markets alongside precision optical component foundries in Taiwan and South Korea for laser device assembly. Raw material dependencies include minoxidil API, biotin compounds, and 630-660 nanometer laser diodes. Single-source vulnerability runs through concentrated API supply from Chinese manufacturers facing geopolitical exposure. Distribution runs through specialty dermatology clinics and telehealth platforms for prescription protocols, with retail pharmacy networks handling over-the-counter volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telogen effluvium treatment is approaching a platform-economics inflection as connected photobiomodulation devices integrate with digital adherence monitoring and scalp biomarker analytics. Interoperability between hardware sensors and clinical workflow software is reshaping competitive moats.
For Market Incumbents: Entrench diagnostic-therapeutic workflow integration by acquiring telehealth infrastructure and securing exclusive clinic network partnerships. Device manufacturers face substitution pressure from subscription-based platform providers bundling diagnostics with hardware access. Priority lever: backward integration into scalp microbiome testing capabilities to capture upstream diagnostic touchpoints and lock in recurring revenue structures.
For New Entrants and Emerging Players: Establish a beachhead in preventive treatment protocols targeting endocrinology referral channels before follicular miniaturization advances. The most penetrable segment sits with metabolic trigger recognition workflows in United States urban coastal markets where insulin resistance and thyroid assessments already incorporate hair shedding screening. Go-to-market angle: white-label photobiomodulation hardware for wellness center chains seeking differentiated aesthetic service bundles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermatology clinic consolidators and connected device platform operators with proven 510(k) clearance pathways. Long-term viability over a multi-year horizon hinges on regulatory harmonization arbitrage between FDA and EMA jurisdictions. Target acquisition archetype: precision photobiomodulation specialists with active European notified body partnerships. Signal to monitor: CMS Category III CPT code establishment for at-home laser therapy, which would trigger reimbursement-driven demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Clearance Pathway Navigation | FDA marketing authorization accelerates commercialization timelines and expands reimbursable indications for laser devices. |
| Telehealth Platform Integration | Virtual dermatology consultations bypass geographic access barriers and enable direct-to-patient prescribing channels. |
| EMA Notified Body Partnership | European regulatory relationships create competitive moats as MDR compliance overhead disadvantages low-cost entrants. |
| Combination Therapy Protocol Development | Convergence of topical minoxidil with laser devices and oral supplementation builds premium recurring revenue bundles. |
| Scalp Microbiome Testing Capability | Diagnostic upstream integration captures preventive treatment touchpoints and improves patient retention through personalization. |
Research Methodology
Operator-level perspectives from dermatology clinic directors, trichology specialists, medical device regulatory consultants, and pharmacy procurement managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, CDSCO import licensing records, and hospital procurement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions covering product type, delivery mode, end user, and application stage. CAGRs derived from procedure volume trends, pricing trajectory assumptions, and regulatory approval pipeline velocity. Forecast inputs incorporated telehealth adoption curves, metabolic trigger recognition expansion rates, and laser device reimbursement coding developments.
Stress conditions across API supply disruption, FDA clearance timeline delays, and CMS reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about patient preference evolution and regulatory harmonization progress. Quarterly review of 510(k) clearance announcements, CPT code update releases, and CDSCO licensing reform implementations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermabrasion Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Acne Vulgaris Market
Dermatology
Immunodermatology Market
Dermatology
Japan Scar Treatment Market
Dermatology
Folliculitis Treatment Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Dermatology Drugs Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Darier Disease Drugs Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Dermatology Devices Market