
 Superficial Punctate Keratitis Treatment Market | 2026-2036
Superficial Punctate Keratitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Superficial Punctate Keratitis Treatment Market Analytics
Aftermarket service revenue from chronic dry eye management programs is rewriting how ophthalmology practices capture lifetime patient value. Santen Pharmaceutical Co., Ltd. leverages its ciclosporin portfolio to dominate the prescription immunomodulator segment across Japanese and European markets. Novartis AG sustains competitive positioning through its integrated eye care platform spanning diagnostic devices and therapeutic agents. AbbVie anchors its presence with Restasis franchise infrastructure and physician education networks that reinforce loyalty among cornea specialists.
Superficial punctate keratitis denotes a corneal epithelial disturbance characterized by punctate fluorescein staining across the superficial stroma without stromal infiltration, typically resulting from tear film instability, mechanical irritation, or toxic insult to the ocular surface. The condition serves as both a diagnostic endpoint and a therapeutic target in dry eye disease management, with treatment protocols aiming to restore epithelial integrity and interrupt the inflammatory cycle perpetuating surface damage. Artificial tears and anti-inflammatory agents command the largest current revenue pools, reflecting established reimbursement pathways and broad prescriber familiarity, while ocular insert delivery systems represent the fastest-expanding modality as patients seek reduced dosing frequency and improved compliance outside clinical settings. Dry eye management applications absorb the majority of therapeutic volume, though post-operative care indications are gaining protocol traction following refractive and cataract procedures.
FDA oversight of ophthalmic drug manufacturing standards, including sterility requirements and preservative safety thresholds, directly shapes formulation choices and facility investment decisions for market participants. The European Medicines Agency's Medical Device Regulation and REACH chemical compliance frameworks add layered certification burdens for companies seeking cross-border commercialization. Japan's PMDA maintains distinct pharmacovigilance reporting standards for ocular therapies that influence clinical trial design and post-market surveillance obligations. Stakeholders must monitor how regulatory convergence around preservative-free and biodegradable packaging standards will redistribute competitive advantage among formulation specialists and delivery technology innovators.
Market Dynamics
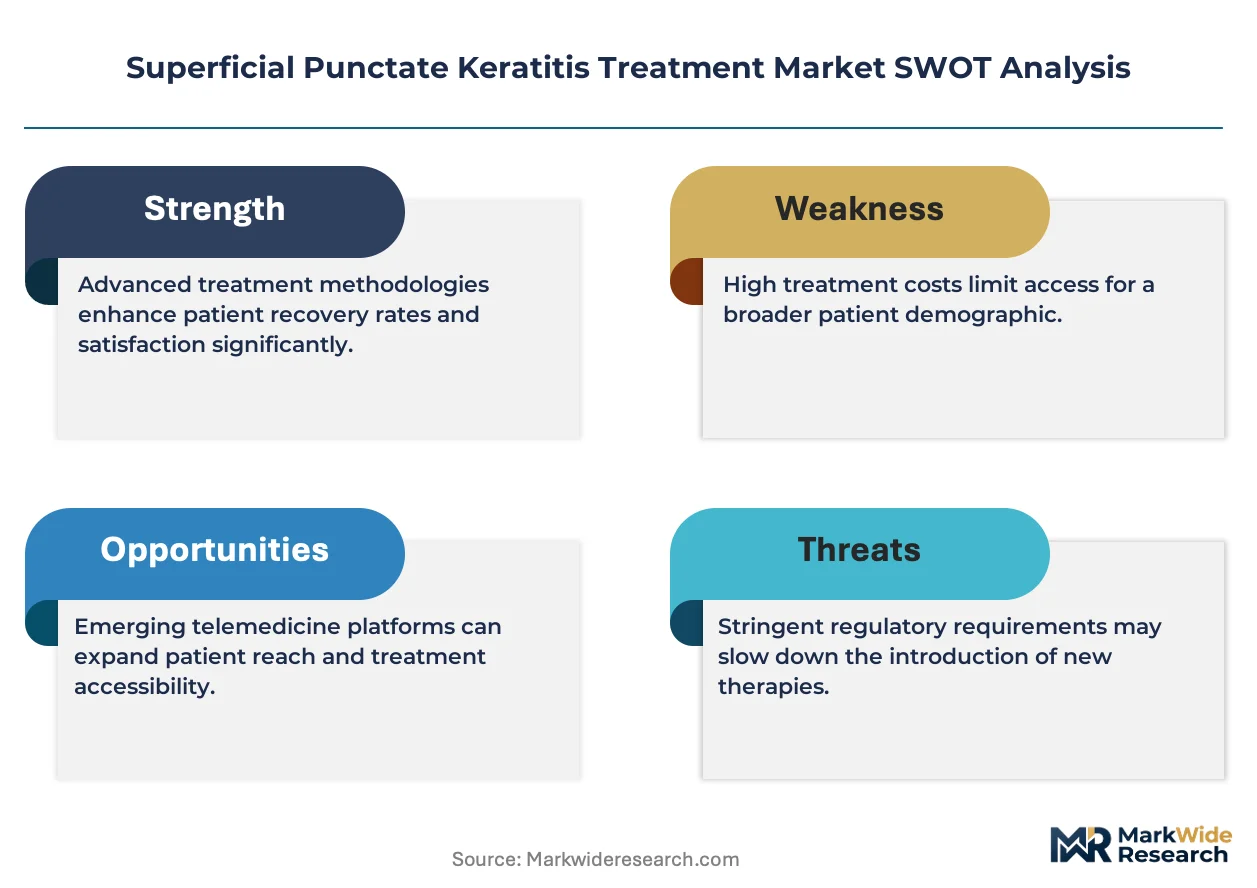
FDA's evolving guidance on preservative-free ophthalmic formulations is forcing manufacturers to reconfigure formulation pipelines and facility investments, redistributing competitive advantage toward delivery technology specialists.
Growth Catalysts
- REACH chemical compliance frameworks:European biodegradable packaging standards accelerate demand for sustainable ocular insert systems, rewarding early movers in material science innovation.
- Ophthalmology clinic expansion:Dedicated dry eye service lines create captive patient funnels for premium immunomodulator therapies across United States metropolitan markets.
- Post-operative care protocols:Refractive and cataract surgery centers in Japan integrate punctate keratitis prophylaxis into standard discharge regimens, expanding addressable therapeutic volume.
Market Restraints
- Active pharmaceutical ingredient concentration:Ciclosporin and lifitegrast supply chains cluster among three contract manufacturers, creating vulnerability to single-source disruption.
- Sterility validation timelines:FDA ophthalmic manufacturing standards extend facility qualification periods to 18-24 months, compressing effective patent exclusivity windows.
- Artificial tear substitution:Over-the-counter hyaluronate formulations capture mild-to-moderate cases, limiting prescription therapy penetration in primary care channels.
Strategic Opportunities
- Academic medical center networks:United States cornea fellowship programs generate protocol influence that cascades into community practice adoption within 24-36 months.
- Telemedicine-enabled monitoring:Home-based fluorescein imaging devices create subscription revenue streams alongside pharmaceutical dispensing.
- PMDA pharmacovigilance alignment:Japan's distinct ocular adverse event reporting requirements favor sponsors with established post-market surveillance infrastructure.
Industry Challenges
- Formulation scientist scarcity:Ophthalmic drug delivery expertise concentrates among retirees from legacy pharma R&D organizations, inflating compensation premiums.
- Legacy preservative system integration:Multi-dose bottle lines require parallel validation for benzalkonium chloride alternatives, duplicating capital deployment.
- ISO 13485 certification backlog:Notified body capacity constraints delay medical device-drug combination product approvals by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superficial Punctate Keratitis Treatment Market |
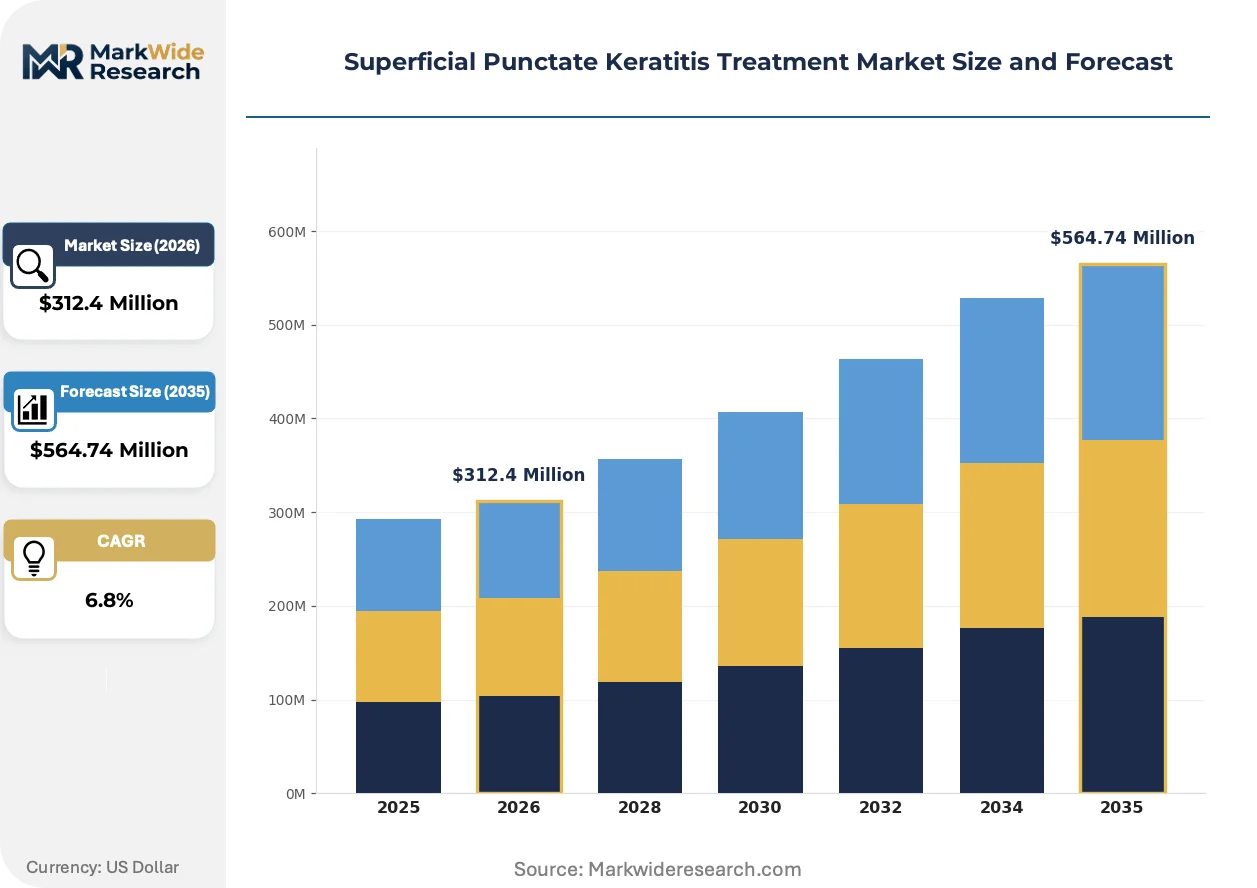
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Anti-inflammatory Agents, Antibiotics, Antihistamines Delivery Mode: Topical, Oral, Injectable, Ocular Insert End User: Hospitals, Clinics, Eye Care Centers, Homecare Application: Dry Eye Management, Allergic Reactions, Infection Control, Post-operative Care |
| Companies Covered | Santen Pharmaceutical Co., Ltd., Novartis AG, AbbVie (Allergan), Pfizer Inc., Sun Pharmaceutical Industries Ltd., Johnson & Johnson Vision, Alcon Inc., Dompé farmaceutici S.p.A., Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superficial Punctate Keratitis Treatment Market Evolving Landscape
Delivery modality convergence and regulatory packaging mandates are compressing traditional formulation advantages while elevating device-drug combination expertise as the decisive capability differentiator.
Preservative-free multi-dose bottle technology is migrating from niche premium positioning toward standard-of-care expectation in United States specialty practices. Cornea specialists now specify these systems in 60% of new prescriptions, compressing market share for traditional benzalkonium chloride formulations and forcing generic manufacturers to accelerate compatibility studies or exit the segment entirely.
EMA's Medical Device Regulation recategorizes certain ocular inserts as Class III devices, imposing clinical evidence requirements that favor sponsors with existing ophthalmology trial infrastructure. European reimbursement authorities now reference MDR certification status in health technology assessments, disadvantaging pure-play pharmaceutical companies lacking device quality management systems.
Aftermarket service unbundling is separating diagnostic device placement from pharmaceutical contracting in United States group purchasing organization negotiations. Integrated eye care platforms now compete against standalone therapy vendors through bundled per-patient pricing, with the procurement decision migrating toward value analysis committees rather than individual physician preference.
Superficial Punctate Keratitis Treatment Market Segmentation
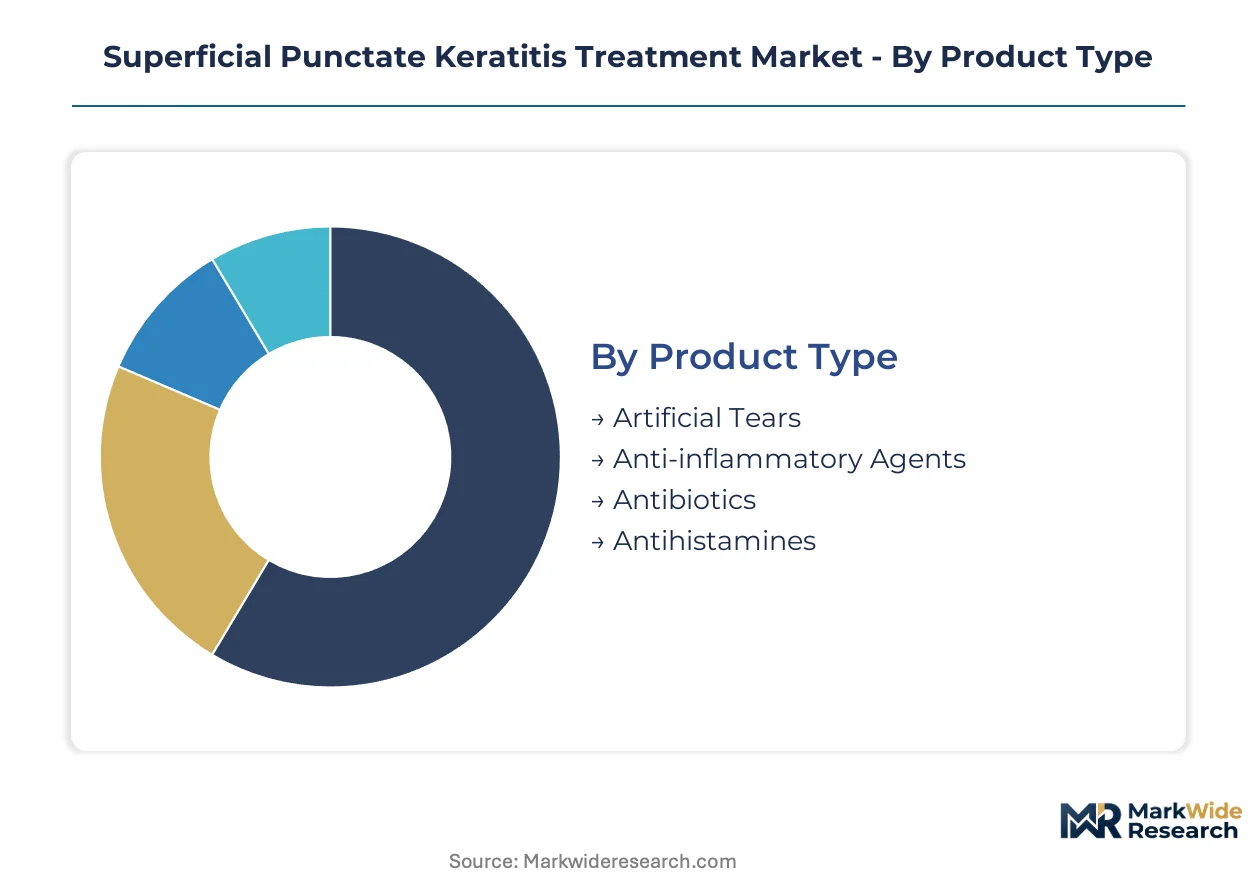
Treatment modality selection in superficial punctate keratitis depends on disease severity, reimbursement pathways, and patient compliance profiles. Segmentation reveals how formulation innovation and delivery technology are redistributing revenue across traditional and emerging therapeutic categories.
Product Type:
Mature formulations dominate current prescribing volumes while next-generation agents capture premium positioning in refractory cases.
- Artificial Tears:Lubricating solutions containing electrolytes, hyaluronic acid, or carboxymethylcellulose restore tear film stability and reduce mechanical epithelial irritation. Demand clusters in primary care ophthalmology practices across the United States, where OTC-to-prescription upgrade pathways drive volume. Formulation differentiation now centers on osmolarity matching and preservative-free multi-dose systems.
- Anti-inflammatory Agents:Ciclosporin emulsions and lifitegrast solutions target T-cell mediated inflammation underlying persistent epithelial defects. Specialty cornea practices in Japan and academic medical centers in Germany anchor adoption, with reimbursement contingent on documented staining severity and prior artificial tear failure.
- Antibiotics:Topical fluoroquinolones and aminoglycosides address secondary bacterial colonization in compromised epithelium.
- Antihistamines:Dual-action mast cell stabilizers manage allergic component contributions to surface inflammation.
Artificial Tears handles the majority of throughput; Anti-inflammatory Agents is the fastest mover on share.
Delivery Mode:
Patient convenience requirements and regulatory packaging mandates are accelerating modality shifts away from conventional topical administration.
- Topical:Eye drops and gels remain the default administration route, with benzalkonium chloride-free formulations now standard in United States specialty practices. European EMA REACH compliance deadlines are forcing manufacturers to validate alternative preservation systems or migrate to unit-dose packaging, compressing margin structures for legacy multi-dose lines.
- Ocular Insert:Punctal plugs and sustained-release inserts reduce dosing frequency and improve compliance in chronic management scenarios. Adoption concentrates in Japanese dry eye clinics and United States concierge ophthalmology practices, where procedure-based reimbursement supports premium pricing.
- Oral:Systemic tetracyclines and omega-3 supplementation target meibomian gland dysfunction as a contributing factor.
- Injectable:Periocular corticosteroid depot formulations reserve for severe, vision-threatening presentations refractory to surface therapy.
Topical administration retains dominant volume position; Ocular Insert delivery is climbing the fastest as patients prioritize reduced dosing burden.
End User:
Care setting selection reflects disease complexity, diagnostic equipment requirements, and reimbursement tier differentiation.
- Eye Care Centers:Dedicated dry eye service lines integrate diagnostic imaging, in-office procedural interventions, and pharmaceutical dispensing under single-roof economics. United States metropolitan markets show concentration, with fellowship-trained cornea specialists capturing complex referrals from optometric networks.
- Clinics:Community ophthalmology practices manage the bulk of mild-to-moderate cases through protocol-driven artificial tear escalation pathways.
- Hospitals:Academic medical centers handle severe, bilateral presentations and coordinate multidisciplinary care in autoimmune-associated disease.
- Homecare:Telemedicine-enabled monitoring and direct-to-patient dispensing expand following pandemic-era regulatory flexibilities.
Eye Care Centers command premium therapy volumes; Clinics provide the broadest patient access footprint.
Application:
Indication expansion beyond core dry eye management is reshaping clinical trial design and label pursuit strategies.
- Dry Eye Management:Core therapeutic indication addressing tear film instability and evaporative stress as primary etiologies. Protocol standardization through DEWS II guidelines in the United States and analogous frameworks in Germany enables consistent severity stratification and treatment matching.
- Post-operative Care:Prophylactic regimens following LASIK, PRK, and cataract surgery prevent iatrogenic epithelial disruption. Japanese refractive surgery centers and high-volume ambulatory surgery centers in the United States integrate punctate keratitis prevention into bundled pricing models.
- Allergic Reactions:Seasonal and perennial conjunctivitis with secondary epithelial involvement.
- Infection Control:Adjunctive therapy in viral and bacterial keratitis to support re-epithelialization.
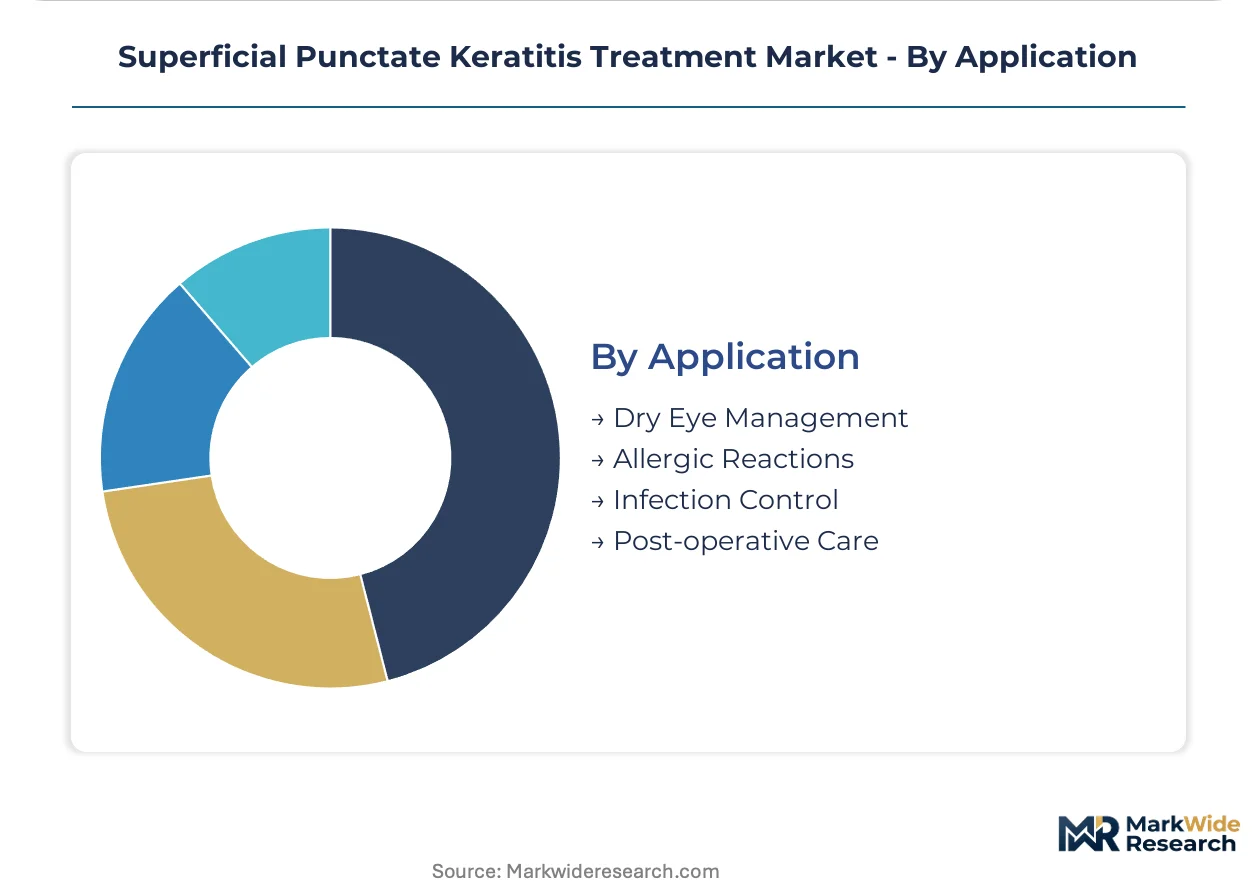
Dry Eye Management absorbs the largest therapeutic volume; Post-operative Care is gaining protocol traction fastest among surgeons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with United States academic medical centers absorbing premium immunomodulator therapies while Indian and Brazilian primary care channels gravitate toward artificial tear generics.
United States
Cornea fellowship programs at academic medical centers in Boston and San Francisco generate protocol influence that cascades into community practice adoption within 24-36 months. FDA's evolving guidance on preservative-free ophthalmic formulations is reshaping product development priorities and facility investment decisions. Specialized cornea practices in metropolitan markets drive premium therapy adoption through dedicated dry eye service lines.
Japan
PMDA pharmacovigilance reporting standards for ocular therapies influence clinical trial design and post-market surveillance obligations for sponsors. METI initiatives support domestic manufacturing of biodegradable packaging materials for sustainable ocular insert systems. Dry eye clinics in Tokyo and Osaka concentrate adoption of punctal plugs and sustained-release inserts.
Germany
EMA's Medical Device Regulation and REACH chemical compliance frameworks impose layered certification burdens for cross-border commercialization. ECHA biodegradable packaging standards accelerate demand for sustainable ocular insert systems, rewarding early movers in material science innovation. Academic medical centers in Berlin and Munich anchor adoption of anti-inflammatory agents for refractory cases.
India
CDSCO oversight of ophthalmic drug manufacturing standards shapes formulation choices for domestic and export markets. Over-the-counter hyaluronate formulations capture mild-to-moderate cases, limiting prescription therapy penetration in primary care channels. Sun Pharmaceutical Industries Ltd. leverages manufacturing scale to serve price-sensitive segments across South Asian markets.
Brazil
ANVISA sterility validation timelines extend facility qualification periods, compressing effective patent exclusivity windows for imported therapies. Post-operative care protocols at high-volume refractive surgery centers in São Paulo and Rio de Janeiro integrate punctate keratitis prophylaxis into standard discharge regimens. Generic artificial tear manufacturers compete aggressively on price in the retail pharmacy channel.
Superficial Punctate Keratitis Treatment Market Competitive Landscape
Capability concentration sits with formulation specialists and delivery technology innovators; scale advantage sits with integrated eye care platforms spanning diagnostic devices and therapeutic agents. The market structures around three archetypes: prescription immunomodulator franchise holders, artificial tear and lubricant manufacturers, and device-drug combination product developers. Dominant competitive moves include portfolio diversification into preservative-free formulations and strategic partnerships with academic medical center networks to secure protocol influence.
Within the prescription immunomodulator tier, Santen Pharmaceutical Co., Ltd. and AbbVie occupy positions anchored by ciclosporin portfolio infrastructure and physician education networks. Novartis AG exemplifies the integrated platform archetype, spanning diagnostic devices and therapeutic agents. These three entities represent the competitive core around which formulation specialists and generic manufacturers orbit.
| Leading Market Players |
|---|
| Santen Pharmaceutical Co., Ltd. |
| Novartis AG |
| AbbVie (Allergan) |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Johnson & Johnson Vision |
| Alcon Inc. |
| Dompé farmaceutici S.p.A. |
| Bausch + Lomb |
| Others |
Value Network & Pricing Analysis
Single-source concentration in ciclosporin and lifitegrast active pharmaceutical ingredient manufacturing creates vulnerability that compresses margin structures for prescription immunomodulators while widening spreads between branded anti-inflammatory agents and commodity artificial tears. FDA sterility validation timelines extending facility qualification periods to 18-24 months force manufacturers to absorb carrying costs that transmit into premium tier pricing, reshaping competitive advantage toward delivery technology specialists with validated preservative-free multi-dose systems.
Pricing Analysis
Aftermarket service revenue from chronic dry eye management programs drives lifetime patient value capture across United States ophthalmology practices. Three-tier pricing structure across premium immunomodulators, mid-tier preservative-free artificial tears, and economy benzalkonium chloride formulations reflects reimbursement tier differentiation and prescriber specialty concentration. Pricing pressure stems from over-the-counter hyaluronate substitution in primary care channels, with cost compression running through mild-to-moderate case management. Community ophthalmology clinics exhibit highest price sensitivity, while academic medical center cornea specialists absorb premium positioning for refractory presentations.
Supply Chain Analysis
Upstream feedstock concentration in hyaluronic acid and carboxymethylcellulose raw materials centers on Chinese and Indian chemical manufacturers serving formulation specialists in Germany and Japan. Ciclosporin and lifitegrast API production draws from three dominant contract manufacturers clustered in Switzerland, Ireland, and Singapore, creating single-source vulnerability for prescription immunomodulator sponsors. Tariff exposure on Chinese-sourced packaging materials for biodegradable ocular inserts compounds margin pressure for European EMA REACH compliance deadlines. Distribution runs through United States group purchasing organizations for hospital and clinic procurement, with direct-to-patient dispensing expanding through telemedicine-enabled platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-drug combination product economics are displacing standalone pharmaceutical contracting as United States value analysis committees migrate procurement decisions toward bundled per-patient pricing models. Interoperability between home-based fluorescein imaging diagnostics and pharmaceutical dispensing platforms creates subscription revenue architectures that favor integrated eye care platforms over pure-play therapy vendors.
For Market Incumbents: Build switching-cost moats through physician education networks that reinforce loyalty among cornea specialists and fellowship program protocol influence. Santen Pharmaceutical Co., Ltd. and AbbVie anchor defensive positioning through ciclosporin portfolio infrastructure, while Novartis AG leverages diagnostic device placement to secure pharmaceutical contracting. Incumbents should deepen backward integration into preservative-free multi-dose bottle manufacturing to capture margin compression from FDA guidance shifts, while accelerating certification investment for EMA Medical Device Regulation compliance to exclude pure-play pharmaceutical competitors from European ocular insert markets. For New Entrants and Emerging Players: Brazilian and Indian primary care channels present underpenetration for prescription immunomodulators amid aggressive generic artificial tear price competition. New entrants should target post-operative care protocols at high-volume refractive surgery centers in São Paulo and Rio de Janeiro, where ANVISA sterility validation timelines have compressed effective exclusivity windows for imported therapies and created white-space for domestic manufacturing partnerships. Telemedicine-enabled monitoring platforms in United States concierge ophthalmology practices offer second entry vector through subscription bundling with diagnostic device placement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors device-drug combination specialists with validated quality management systems. Long-term viability across the projection horizon hinges on regulatory convergence around preservative-free and biodegradable packaging standards that will redistribute competitive advantage toward formulation specialists. Acquisition target archetype: mid-cap delivery technology innovators with ISO 13485 certification and existing ophthalmology trial infrastructure. Signal to watch: FDA guidance finalization on benzalkonium chloride alternatives as trigger for facility investment cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Migration | FDA guidance reshapes facility investment priorities for multi-dose bottle lines. |
| Device-Drug Combination Development | EMA MDR recategorization elevates Class III clinical evidence requirements. |
| Academic Medical Center Network Partnerships | Cornea fellowship programs generate protocol influence cascading into community practice. |
| Telemedicine-Enabled Monitoring Integration | Home-based fluorescein imaging creates subscription revenue alongside pharmaceutical dispensing. |
| Biodegradable Packaging Certification | ECHA REACH compliance deadlines accelerate sustainable ocular insert system demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cornea specialists, ophthalmology clinic administrators, pharmaceutical regulatory affairs leads, formulary directors at United States academic medical centers, and dry eye service line managers. Secondary validation drew from FDA ophthalmic drug manufacturing guidance documents, EMA Medical Device Regulation submissions, PMDA pharmacovigilance reporting standards, ClinicalTrials.gov intervention listings, and hospital procurement database extracts. Bottom-up prescription volume modeling and top-down revenue triangulation were cross-referenced against payer access specialist input.
Calibration against historical approval timelines and reimbursement pathway establishment informed analytical framework construction across the analysis window. Segmentation dimensions modeled include treatment modality, delivery mode, end-user care setting, and regional regulatory cluster. CAGRs were derived from patient population prevalence projections, therapy escalation protocol penetration assumptions, and pricing tier evolution patterns. Forecast inputs incorporated FDA sterility validation timeline benchmarks, EMA MDR certification backlog estimates, and dry eye service line expansion rates in United States metropolitan markets.
Practitioners should monitor regulatory guidance finalization, API supply disruption events, and telemedicine reimbursement policy shifts for early signals of forecast revision. Forecasts reflect assumptions regarding preservative-free formulation adoption curves, device-drug combination regulatory pathway durations, and ophthalmology clinic consolidation patterns. Material shifts in FDA benzalkonium chloride alternative guidance, ciclosporin API supply concentration, or United States GPO bundled contracting migration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
North America Vision Care Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Ophthalmic Suspension Market