
 Immunodermatology Market | 2026-2036
Immunodermatology Market Size, Share, and Industry Trends Forecast 2026-2036
Immunodermatology Market Foresight
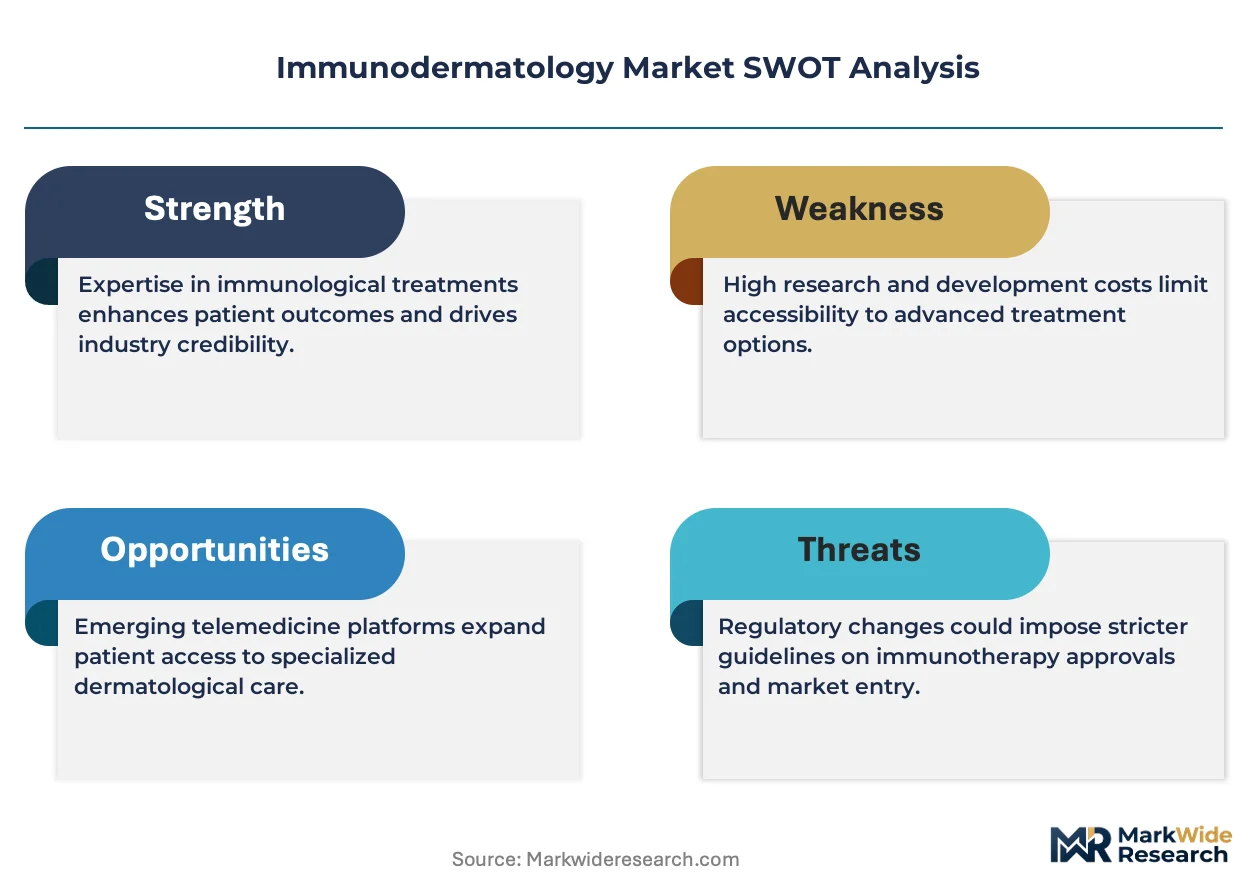
MDR is decoupling legacy product portfolios from European market access, forcing manufacturers to rebuild clinical dossiers around post-market surveillance and notified body recertification timelines. Regeneron Pharmaceuticals leverages its trap-antibody manufacturing infrastructure to sustain supply continuity for atopic dermatology biologics. Pfizer anchors its position through integrated development of JAK inhibitors across inflammatory skin conditions. AbbVie differentiates via dual-pathway coverage in both TNF-alpha and IL-23 blockade for psoriatic disease.
Immunodermatology encompasses the clinical and therapeutic management of immune-mediated skin disorders through targeted modulation of T-cell responses, cytokine signaling, and autoantibody pathways, employing monoclonal antibodies, small-molecule inhibitors, and phototherapeutic modalities with dosing regimens calibrated to disease severity indices. The field serves primarily to interrupt pathological inflammation while preserving cutaneous barrier integrity in chronic relapsing conditions. Biologics command the deepest margin pools due to biosimilar lag and manufacturing complexity, while topical agents retain volume leadership in first-line community practice. Application demand clusters around psoriasis and eczema, where payer formularies have matured, leaving autoimmune disorders as the segment where novel mechanism expansion is most active.
FDA, EMA, and the EU MDR collectively shape immunodermatology through divergent evidentiary standards for biologic licensing, post-authorization safety monitoring, and device-drug combination oversight. These frameworks determine trial design costs, label expansion feasibility, and competitive entry timelines across jurisdictions. Stakeholders must monitor how IL-17 and IL-23 pathway congestion affects payer willingness to add novel mechanisms without head-to-head outcomes data.
Market Dynamics
The EU MDR recertification wave is severing legacy immunodermatology devices from European market access, forcing manufacturers to reconstruct clinical dossiers around post-market surveillance data while academic medical centers in the United States absorb escalating patient volumes for complex autoimmune skin conditions.
Growth Catalysts
- Hospital-based biologic therapy adoption:Dermatology departments across academic medical centers are integrating monoclonal antibody infusion suites, creating dedicated infrastructure for TNF-alpha and IL-23 pathway blockers that anchors referral networks for severe psoriatic disease.
- FDA accelerated approval pathways:The agency's breakthrough therapy designation for novel JAK inhibitors compresses development timelines, enabling earlier commercial entry for small-molecule candidates targeting atopic dermatitis and alopecia areata.
- Phototherapeutic modality expansion:Narrowband UVB and excimer laser systems are penetrating community dermatology practices, extending access beyond tertiary centers into ambulatory settings serving moderate plaque psoriasis populations.
Market Restraints
- Biologic manufacturing concentration:Trap-antibody production capacity clusters among a limited set of contract manufacturing organizations with mammalian cell culture expertise, creating supply vulnerability for atopic dermatology therapeutics.
- EU MDR clinical evidence requirements:The framework mandates prospective post-market surveillance studies for legacy immunodermatology devices, imposing documentation burdens that delay notified body recertification and market re-entry.
- Topical corticosteroid substitution:First-line community practice retains high-volume generic prescribing for mild-to-moderate eczema, constraining revenue capture for novel mechanism biologics in the largest patient segment.
Strategic Opportunities
- Autoimmune skin disorder expansion:Bullous pemphigoid, dermatomyositis, and cutaneous lupus erythematosus represent underpenetrated indications where payer formularies remain immature and novel mechanism trials face less pathway congestion.
- Device-drug combination convergence:Integration of biologic delivery systems with connected adherence monitoring creates differentiated positioning for home-administered therapies, bypassing infusion center capacity constraints.
- IRActherapeutic pricing provisions:The Inflation Reduction Act's Medicare negotiation authority for high-expenditure biologics creates incentives for manufacturers to accelerate indication expansion ahead of price-setting eligibility windows.
Industry Challenges
- Immunology-dermatology specialist recruitment:Fellowship-trained physicians capable of managing complex biologic therapy in autoimmune skin conditions remain concentrated at academic centers, limiting community practice capability buildout.
- IL-17 and IL-23 pathway congestion:Payer willingness to add novel mechanisms without head-to-head outcomes data is compressing, requiring expensive comparator trials that strain development budgets.
- Legacy system integration:Electronic health record interoperability between dermatology-specific severity scoring tools and payer prior authorization platforms creates administrative friction that delays therapy initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunodermatology Market |
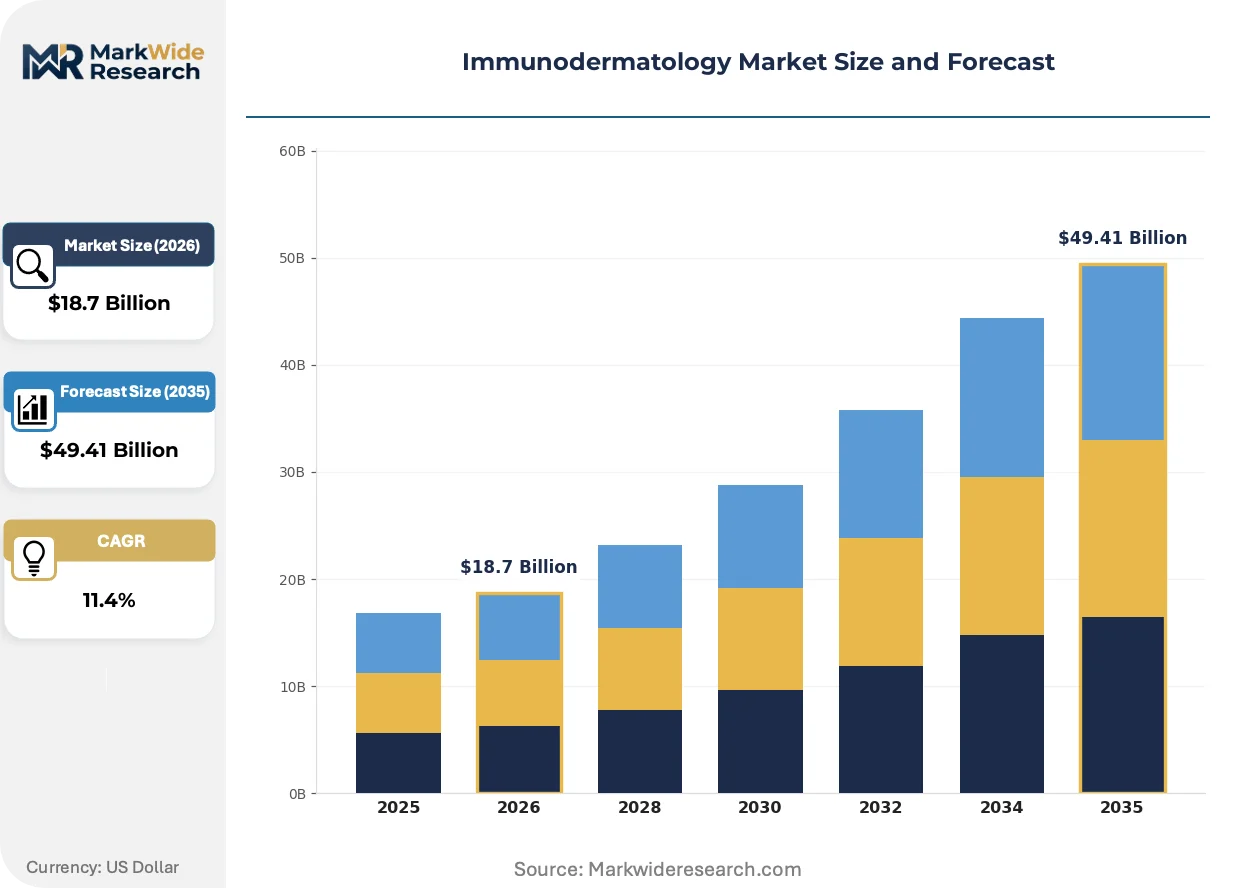
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Topical Agents, Systemic Agents, Phototherapy Application: Psoriasis, Eczema, Autoimmune Disorders, Allergic Dermatitis End User: Hospitals, Clinics, Research Laboratories, Homecare Treatment Method: Immunotherapy, Corticosteroids, Antihistamines, Biologic Therapy |
| Companies Covered | Regeneron Pharmaceuticals, Inc., Pfizer Inc., AbbVie Inc., Amgen Inc., Eli Lilly and Company, Novartis AG, Sanofi S.A., Galderma S.A., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunodermatology Market Shifts & Advancements
Targeted cytokine pathway modulation is fragmenting competitive positioning across immunodermatology, with convergence between biologic manufacturing scale and precision dosing technologies reshaping how therapies reach patient populations.
Bispecific antibody engineering is consolidating therapeutic targeting by enabling simultaneous blockade of IL-13 and IL-31 pathways in a single molecular entity. Academic medical centers with established biologic infusion infrastructure are piloting these candidates in severe atopic dermatitis populations. This consolidation is compressing development timelines for sequential monotherapy approaches while raising manufacturing complexity barriers for competitors lacking trap-antibody production expertise.
The EU MDR's post-market clinical follow-up requirements are restructuring device commercialization by mandating prospective safety registries for phototherapy systems and dermal drug delivery platforms. Manufacturers must now embed real-world evidence generation into product lifecycles rather than treating surveillance as a reactive obligation. Dermatology device portfolios with legacy CE markings face the steepest compliance cliffs, particularly those lacking randomized controlled trial data from pre-2021 regulatory epochs.
Academic medical centers are consolidating complex autoimmune skin condition referrals through integrated multidisciplinary clinics combining dermatology, rheumatology, and pathology expertise. Community dermatologists are ceding severe disease management to these hubs, concentrating biologic prescribing authority and clinical trial access. This geographic concentration is most visible across the United States, where payer prior authorization requirements for specialty pharmacy dispensing reinforce tertiary center lock-in.
Immunodermatology Market Segmentation
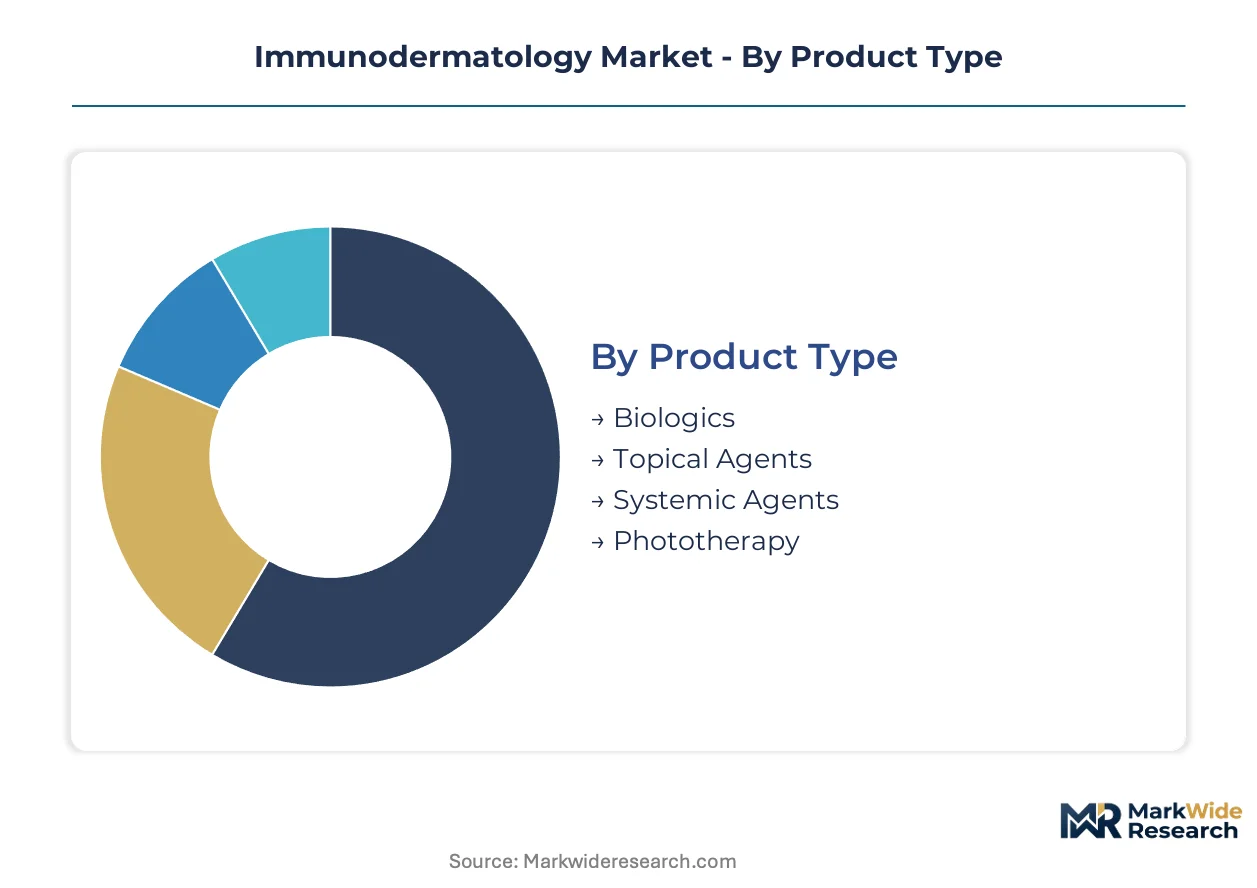
Immunodermatology segmentation reveals how manufacturing complexity and clinical infrastructure shape competitive access across patient populations. Product categories diverge sharply in margin structure, while application and end-user dimensions expose where biologic therapy penetration meets reimbursement and specialist availability constraints.
Product Type:
Supply concentration clusters around mammalian cell culture capacity for monoclonal antibodies, while small-molecule manufacturing disperses across contract chemistry networks.
- Biologics:Trap-antibody and recombinant protein therapeutics targeting IL-17, IL-23, and IL-4/IL-13 pathways dominate revenue pools. Academic medical centers in the United States anchor demand through dedicated infusion infrastructure for severe psoriatic and atopic disease.
- Topical Agents:Corticosteroid and calcineurin inhibitor formulations serve first-line community practice. Volume concentrates in generic prescribing for mild-to-moderate eczema, constraining novel mechanism penetration despite larger patient denominators.
- Systemic Agents:Oral small-molecule immunosuppressants including methotrexate and cyclosporine bridge biologic-ineligible patients.
- Phototherapy:Narrowband UVB and excimer laser systems require capital investment that concentrates in tertiary dermatology departments.
Today's leader: Biologics. Tomorrow's challenger: Phototherapy.
Application:
Cost tier stratification separates mature payer formularies from indication expansion opportunities where clinical evidence requirements remain less congested.
- Psoriasis:IL-17 and IL-23 pathway blockers command premium pricing with established prior authorization pathways. United States academic centers concentrate severe disease referrals where biologic penetration reaches highest levels.
- Eczema:Dupilumab and emerging JAK inhibitors reshape treatment hierarchies. Community dermatologists retain volume leadership for topical-first protocols while biologic adoption climbs in refractory populations.
- Autoimmune Disorders:Bullous pemphigoid, dermatomyositis, and cutaneous lupus erythematosus represent underpenetrated indications with immature payer frameworks.
- Allergic Dermatitis:Contact and atopic variants overlap with eczema segmentation, creating indication definition challenges for trial design.
Psoriasis commands current revenue concentration. Autoimmune disorders offer the steepest expansion trajectory for novel mechanism entry.
End User:
Customer type determines therapy modality access, with infusion center infrastructure creating sharp divides between institutional and ambulatory care settings.
- Hospitals:Academic medical centers integrate biologic infusion suites with multidisciplinary autoimmune clinics. FDA breakthrough therapy designations accelerate pipeline access at these sites.
- Clinics:Community dermatology practices concentrate topical prescribing and phototherapy administration. Prior authorization platforms create administrative friction that delays biologic initiation.
- Research Laboratories:Clinical trial sites for bispecific antibodies and novel JAK inhibitors cluster at NIH-funded institutions.
- Homecare:Subcutaneous biologic delivery and connected adherence monitoring expand beyond infusion center dependency.
Hospitals retain biologic prescribing authority. Homecare represents the fastest-climbing channel for administration modality shift.
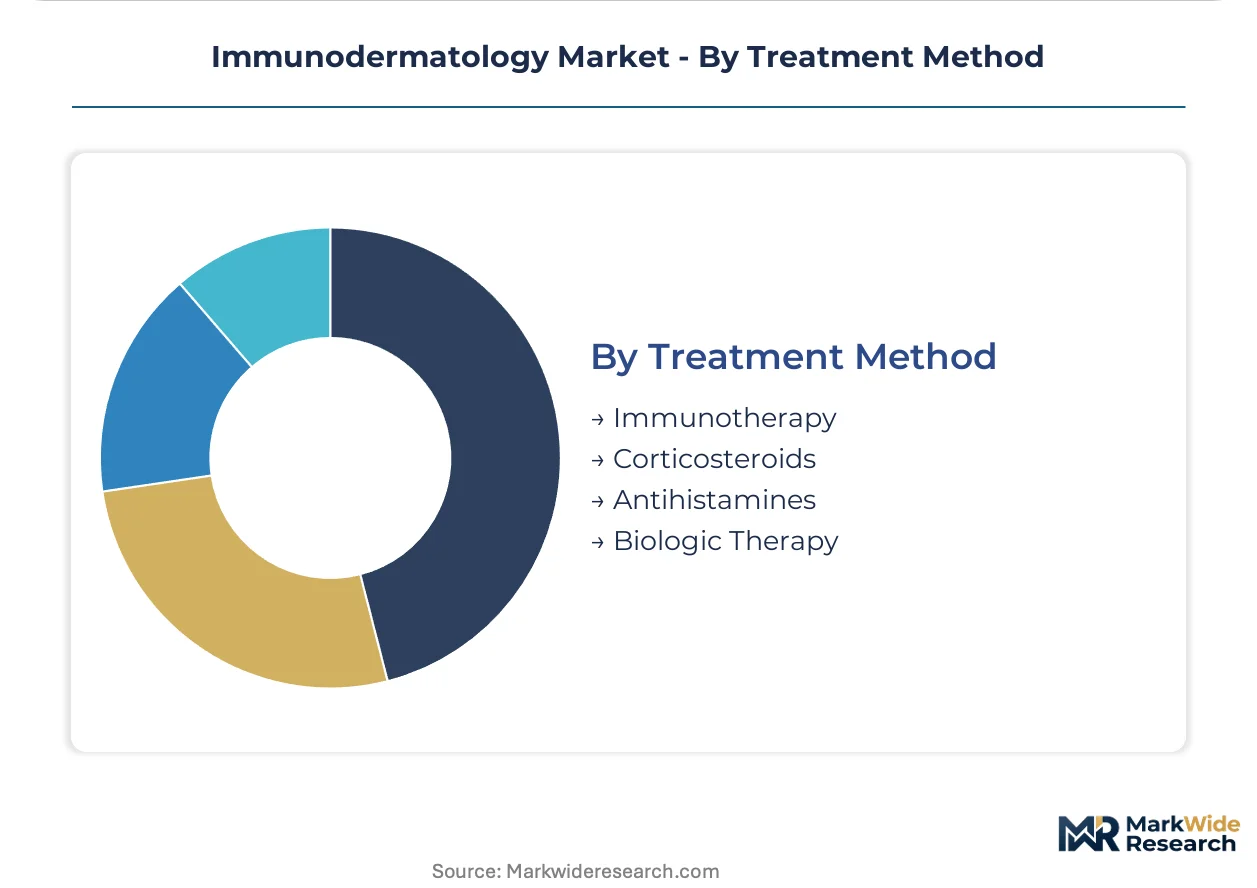
Treatment Method:
Maturity gradients separate decades-old protocols from mechanism-driven innovation, with regulatory pathway differentiation shaping development investment returns.
- Immunotherapy:Desensitization protocols and allergen immunotherapy address specific allergic dermatitis subtypes. Demand concentrates in specialized centers with immunology-dermatology cross-training.
- Corticosteroids:Generic topical and systemic formulations retain volume leadership across all geographies. Substitution pressure constrains novel agent pricing power in mild-to-moderate segments.
- Antihistamines:H1-blockers serve symptomatic relief in urticaria and pruritus without disease modification.
- Biologic Therapy:Monoclonal antibodies and fusion proteins command deepest margins through manufacturing complexity barriers and biosimilar lag.
Biologic therapy captures development investment. Immunotherapy awaits indication expansion evidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained immunodermatologists cluster at academic medical centers across select countries, concentrating biologic prescribing authority and clinical trial access for complex autoimmune skin conditions.
United States
Academic medical centers anchor referral networks for severe psoriatic and atopic disease, with dedicated biologic infusion suites driving adoption of IL-17 and IL-23 pathway blockers. FDA breakthrough therapy designations compress development timelines for novel JAK inhibitors. The Boston-Cambridge corridor concentrates clinical trial sites for bispecific antibody candidates.
Germany
University hospitals in Munich and Heidelberg integrate multidisciplinary autoimmune clinics combining dermatology, rheumatology, and pathology expertise. The EU MDR framework mandates prospective post-market surveillance studies for phototherapy systems, forcing manufacturers to reconstruct clinical dossiers. Baden-Württemberg hosts concentrated device manufacturing expertise for dermal drug delivery platforms.
Switzerland
Swissmedic's alignment with EMA standards accelerates biologic licensing for trap-antibody therapeutics while maintaining distinct national pricing autonomy. Basel anchors pharmaceutical manufacturing infrastructure for monoclonal antibody production. The country's precision dosing technology clusters support connected adherence monitoring for home-administered therapies.
Japan
PMDA's conditional early approval system enables accelerated market entry for novel mechanisms targeting treatment-refractory autoimmune skin disorders. The Kanto region concentrates dermatology-specific severity scoring tool development. Tokyo-based academic centers pilot phototherapeutic modality expansion into community dermatology practices.
United Kingdom
NHS England's specialized commissioning frameworks concentrate biologic therapy access at designated tertiary centers in London and Manchester. The MHRA's post-Brexit regulatory autonomy creates divergence from EU MDR timelines for immunodermatology device recertification. The Oxford-Cambridge arc clusters research laboratory capacity for novel mechanism trials.
Immunodermatology Market Competitive Landscape
The competitive structure tilts toward biologic manufacturers with captive mammalian cell culture capacity. Three tiers separate trap-antibody specialists from small-molecule developers and device-drug combination platforms. Dominant competitive moves include indication expansion ahead of IRA price-setting windows and strategic partnerships to secure infusion center networks.
Among US-based biologic developers, Regeneron Pharmaceuticals, Inc. and AbbVie Inc. exemplify the manufacturing-integrated archetype, while Pfizer Inc. occupies a position spanning both small-molecule and biologic modalities. These entities represent the concentration of development investment around IL-17, IL-23, and JAK inhibitor pathways where payer formularies have matured.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals, Inc. |
| Pfizer Inc. |
| AbbVie Inc. |
| Amgen Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Sanofi S.A. |
| Galderma S.A. |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Prior authorization consolidation among United States payers is compressing reimbursement timelines for biologic therapies, forcing manufacturers to absorb administrative costs while maintaining infusion center partnerships that anchor premium pricing for IL-23 pathway blockers.
Pricing Analysis
Biologic therapy bundles separate drug acquisition costs from infusion administration fees, creating unbundled service pricing for hospital-based delivery versus packaged pricing for home-administered subcutaneous alternatives. Price differentiation hinges on manufacturing complexity tiers and FDA breakthrough therapy designation status, with trap-antibody production commanding premium positioning over small-molecule alternatives. Pricing pressure stems from the Inflation Reduction Act's Medicare negotiation eligibility windows accelerating indication expansion investments. Community dermatology practices exhibit highest price sensitivity due to generic topical substitution, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Regional distribution centers for temperature-controlled biologics concentrate in Switzerland, Germany, and the United States, with hub-and-spoke patterns radiating from Basel and Boston-Cambridge manufacturing clusters. Mammalian cell culture capacity draws from contract manufacturing organizations in Switzerland and Ireland, while JAK inhibitor active pharmaceutical ingredients source from specialized chemistry networks in India and China. Single-source vulnerability concentrates around trap-antibody production expertise limited to select facilities with biosafety level compliance. Distribution runs through specialty pharmacy channels with cold-chain integrity requirements for biologic integrity maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR recertification burdens create competitive exit windows that United States-based manufacturers can exploit through accelerated FDA breakthrough designations.
For Market Incumbents: Acquire phototherapy device portfolios with legacy CE markings facing EU MDR compliance cliffs. Consolidate manufacturing capacity in Switzerland to secure mammalian cell culture expertise ahead of biosimilar entry. Build backward integration into trap-antibody production to defend margin position against contract manufacturing organization concentration risk.
For New Entrants and Emerging Players: Enter via autoimmune skin disorder indications where payer formularies remain immature and IL-17 pathway congestion is absent. Target bullous pemphigoid and dermatomyositis segments with novel mechanism trials facing less comparator trial burden. Deploy connected adherence monitoring platforms as differentiated go-to-market positioning for home-administered therapies.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision dosing technology developers serving subcutaneous biologic delivery. Five-to-ten year viability hinges on indication expansion velocity ahead of IRA price-setting windows. Monitor PMDA conditional early approval decisions in Japan as inflection signal for novel mechanism regulatory receptivity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Prospective post-market surveillance studies enable continued European market access for phototherapy systems. |
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Basel secures supply continuity for IL-23 blockers. |
| Indication Expansion | Autoimmune disorder trials in bullous pemphigoid bypass IL-17 pathway payer congestion. |
| Hospital System Partnership | Academic medical center infusion suite integration anchors biologic prescribing authority. |
| Reimbursement Strategy | Prior authorization platform interoperability investments compress therapy initiation delays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored value estimates.
Segment-weighting approaches applied treatment line, administration route, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from epidemiological prevalence trajectories, biologic penetration curves, and payer formulary adoption timelines. Forecast inputs incorporated IL-17 pathway congestion indices and EU MDR recertification completion rates.
Inputs from notified body documentation and payer prior authorization platforms were available through the study window; gaps in real-world evidence generation timelines for novel bispecific antibodies introduce uncertainty bands around adoption curve assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Keloid Treatment Market
Dermatology
Microdermabrasion Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Dermatology Software Market
Dermatology
Global Hirsutism Market
Dermatology
Global Rosacea Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Scar Treatment Oils Market
Dermatology
Common Warts Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market