
 Middle East and Africa Aesthetic Dermatology Market | 2026-2036
Middle East and Africa Aesthetic Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aesthetic Dermatology Market Foresight
The split between premium energy-based platforms and commodity injectable tiers is realigning procurement patterns across the Middle East and Africa. Merz Pharma leverages its R&D depth to sustain premium positioning in botulinum toxin and filler portfolios. Alma Lasers anchors regional distribution through Dubai-based service infrastructure and localized training academies.
Aesthetic dermatology encompasses minimally invasive and non-invasive procedures employing energy-based devices, injectable biologics, and topical agents to modify skin appearance, with laser systems typically operating at wavelengths between 532 nm and 10,600 nm depending on chromophore targeting. Its commercial purpose centers on elective cosmetic enhancement, scar revision, and photoaging correction delivered through outpatient clinical settings. Laser therapy and radiofrequency platforms command the dominant technology share due to their versatility across skin types prevalent in the region, while botulinum toxin and dermal fillers represent the most penetrated product categories where margin pools concentrate in high-repeat-rate maintenance regimens. Facial rejuvenation applications attract the majority of procedural volume, though hair removal retains strong growth in Gulf markets where cultural preferences elevate demand.
SFDA in Saudi Arabia and the UAE's MOHAP enforce medical device registration and practitioner licensing requirements that filter market access toward established multinationals with regulatory bandwidth. South Africa's Health Products Regulatory Authority applies parallel standards for energy-emitting devices, creating a compliance overlay that favors suppliers with dedicated African regulatory teams. Stakeholders must weigh the trade-off between Gulf premium pricing and sub-Saharan volume scalability when allocating commercial resources.
Market Dynamics
The Middle East and Africa aesthetic dermatology market is being reshaped by a regulatory tightening wave that is filtering market access toward established multinationals with dedicated compliance infrastructure and regional regulatory teams.
Growth Catalysts
- SFDA Registration Protocols:Saudi Arabia's medical device registration requirements are elevating standards for energy-based platform entry, filtering out undercapitalized entrants and concentrating procurement among compliant suppliers.
- Gulf Urban Wealth Concentration:High-net-worth individuals in Dubai, Riyadh, and Abu Dhabi are driving procedural demand for premium facial rejuvenation and hair removal services.
- Localized Training Infrastructure:Dubai-based service academies are accelerating practitioner certification timelines and expanding addressable clinician pools across the GCC.
Market Restraints
- MOHAP Compliance Costs:The UAE's tightened device registration protocols are elevating fixed costs for market entrants without existing regulatory bandwidth.
- Sub-Saharan Supply Fragmentation:South Africa absorbs disproportionate aesthetic service volume, yet distribution infrastructure beyond Johannesburg and Cape Town remains thin.
- Skin Type Technical Limitations:Laser systems operating at shorter wavelengths face efficacy constraints on darker skin phototypes prevalent across the region, compressing addressable indications for certain platforms.
Strategic Opportunities
- North African Expansion:Egypt and Morocco remain underpenetrated relative to Gulf saturation, offering volume scalability for injectable biologics and mid-tier energy devices.
- Radiofrequency-Convergent Platforms:Combination systems integrating radiofrequency with microneedling are opening new indications in scar revision and skin tightening beyond traditional laser boundaries.
- Direct-to-Clinic Distribution:Bypassing traditional distributor markups through manufacturer-owned service infrastructure is compressing procurement costs for high-volume clinic chains in Saudi Arabia.
Industry Challenges
- Practitioner Certification Bottlenecks:MOHAP and SFDA licensing requirements for energy-emitting device operators are creating credentialing backlogs that constrain clinic expansion timelines.
- Device Integration Complexity:Legacy clinic management systems in South Africa's fragmented private practice landscape resist seamless connectivity with new platform telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aesthetic Dermatology Market |
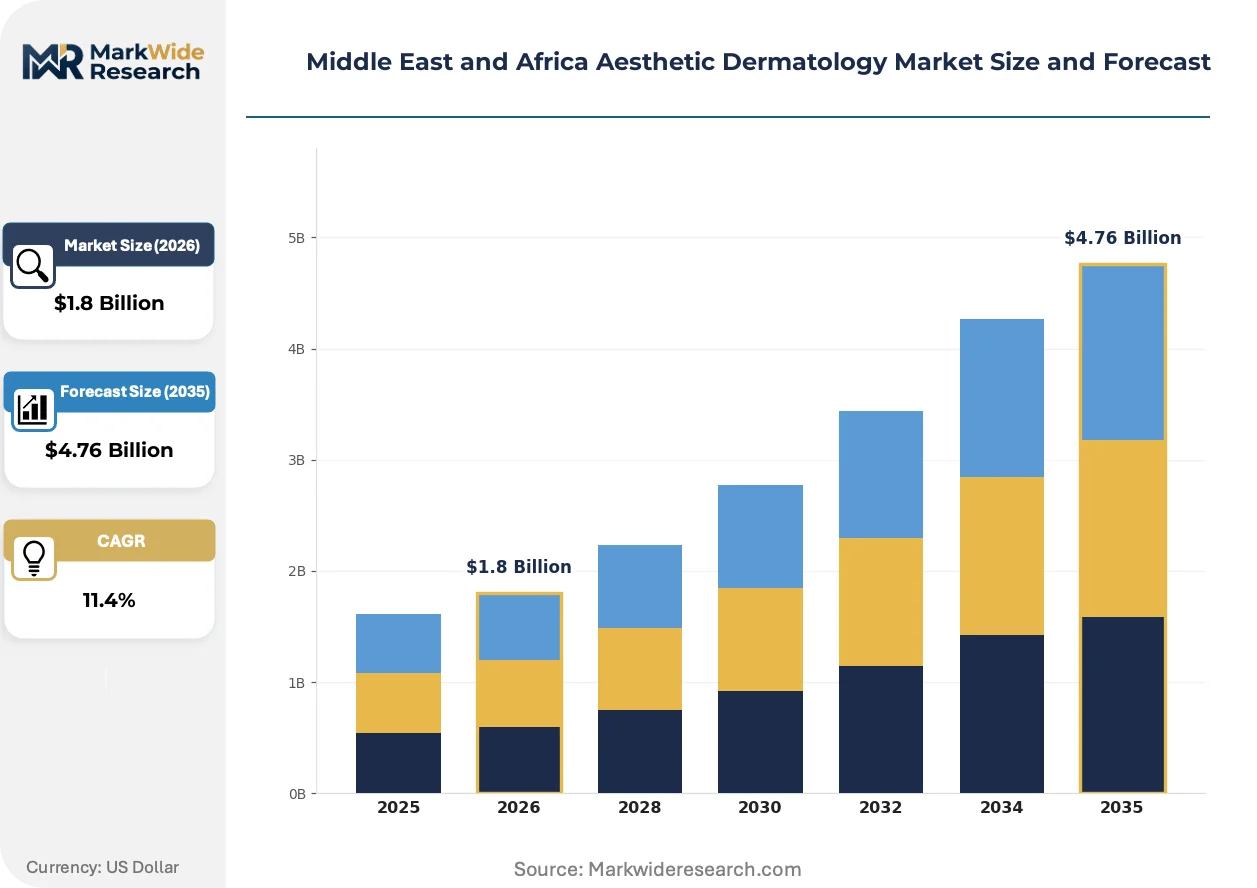
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Dermal Fillers, Laser Devices, Chemical Peels Technology: Laser Therapy, Radiofrequency, Ultrasound, Cryotherapy Application: Facial Rejuvenation, Acne Scars, Stretch Marks, Hair Removal End User: Clinics, Spas, Hospitals, Home Care |
| Companies Covered | Merz Pharma, Cutera, Allergan, Cynosure, Alma Lasers, Galderma, Bausch Health Companies, Venus Concept, Lumenis, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aesthetic Dermatology Market Shifts & Advancements
Technology convergence and regulatory differentiation are compressing competitive timelines across the Middle East and Africa aesthetic dermatology landscape.
Picosecond laser systems are overtaking nanosecond platforms in tattoo removal and pigmentation correction applications across Gulf dermatology chains. High-volume clinics in Dubai and Riyadh are retrofitting existing treatment rooms with picosecond units at accelerated replacement cycles. This wavelength precision compression is overtaking legacy Q-switched devices and narrowing the premium pricing window for older technology tiers.
MOHAP's 2023 device registration amendments are mandating enhanced clinical evidence packages for energy-based platforms entering the UAE market. Manufacturers must now submit expanded safety profiling for darker skin phototypes, extending approval timelines. Injectable biologics with existing European CE marking are navigating this friction more smoothly than novel energy devices lacking comparable regulatory precedent.
Clinic procurement committees in Saudi Arabia are unbundling after-sales service contracts from capital equipment purchases. Large hospital-affiliated dermatology departments in Riyadh are negotiating standalone maintenance agreements with third-party technical providers. This service unbundling is most visible among high-repeat-rate injectable buyers seeking to compress total cost of ownership across multi-year maintenance regimens.
Middle East and Africa Aesthetic Dermatology Market Segmentation
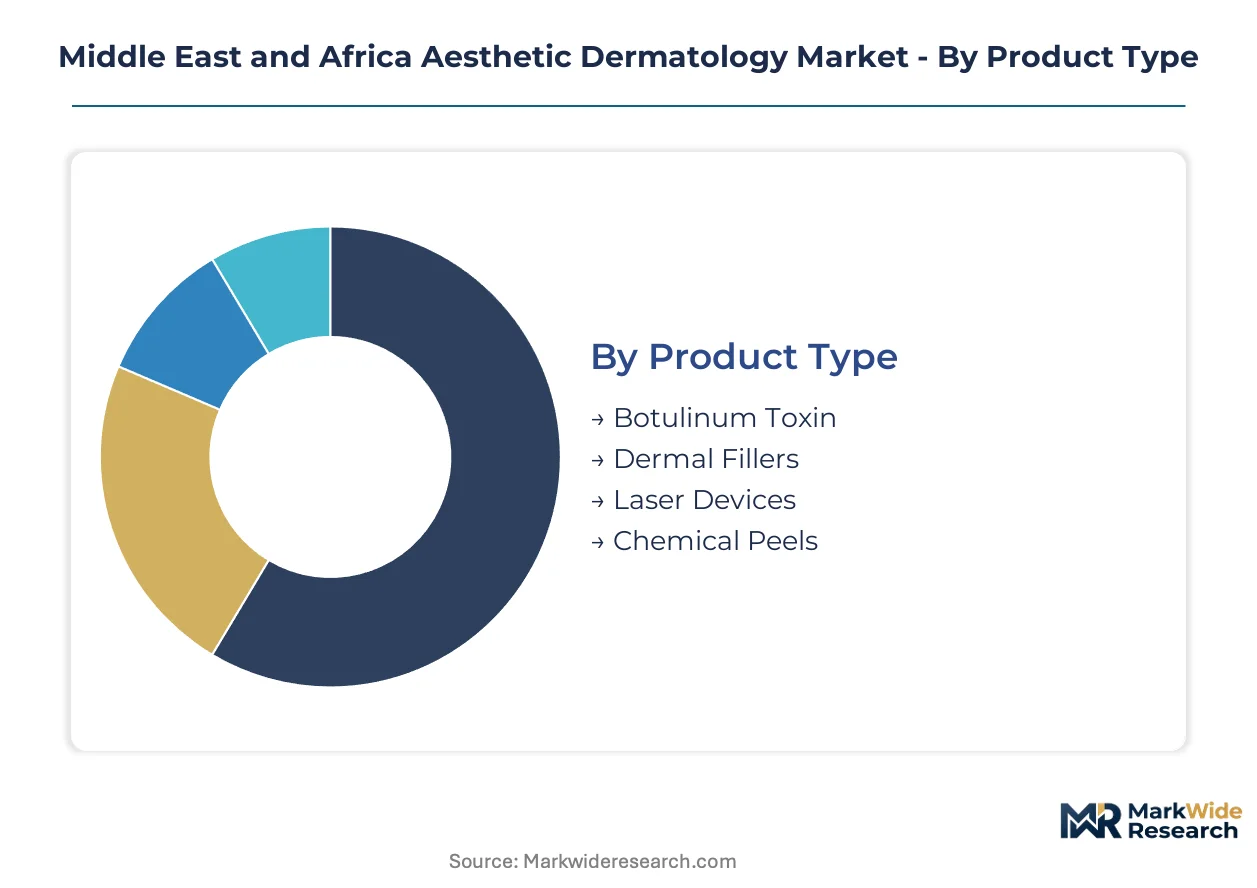
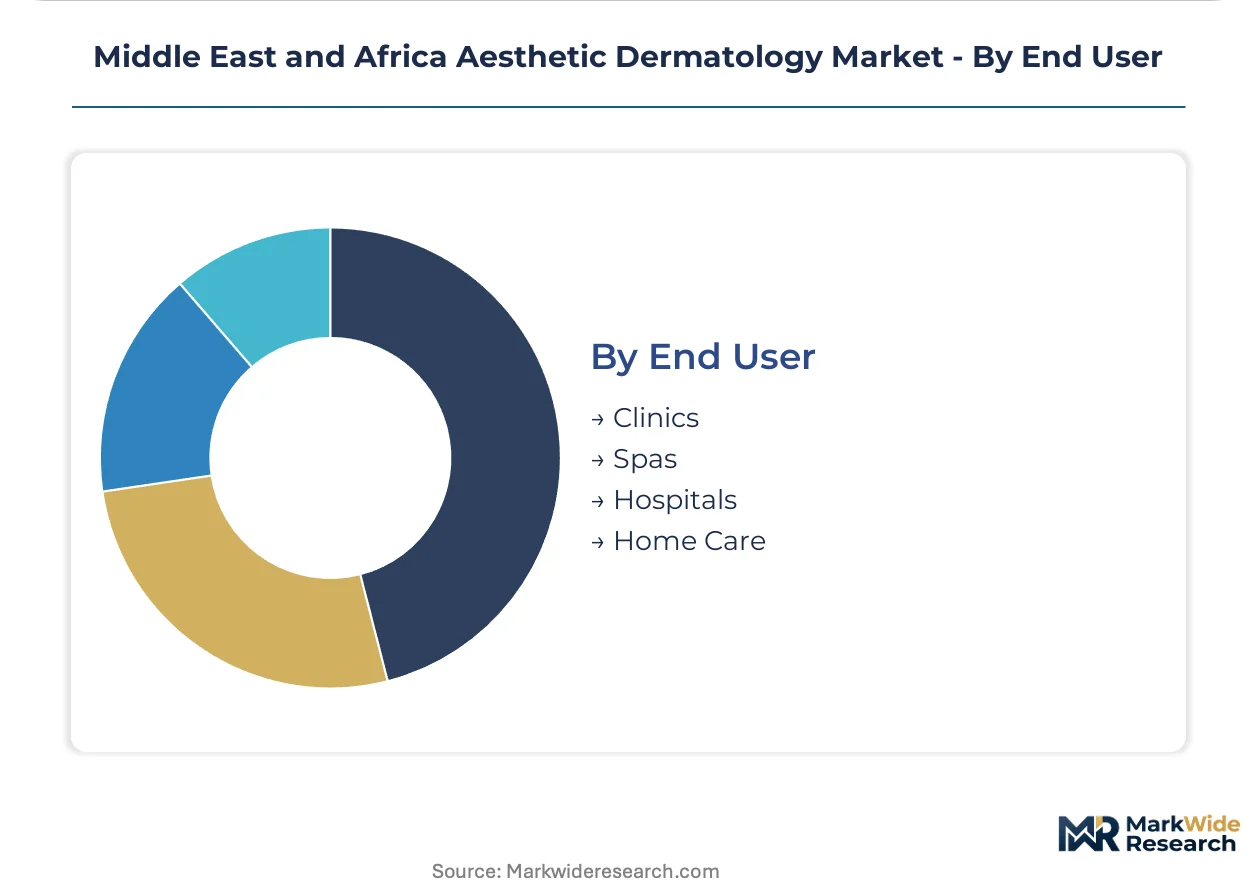
Segmentation reveals how regulatory burden and clinical sophistication concentrate margin pools across the Middle East and Africa aesthetic dermatology landscape. Procurement committees in Dubai and Riyadh weight certification requirements differently by product category, reshaping supplier prioritization.
Product Type:
SFDA and MOHAP registration protocols impose divergent compliance costs across injectable biologics versus energy-emitting hardware, filtering market access toward established multinationals with dedicated regulatory bandwidth.
- Botulinum Toxin:Purified neurotoxin formulations temporarily inhibit acetylcholine release at neuromuscular junctions, smoothing dynamic rhytides. Gulf clinic chains in Dubai and Abu Dhabi drive repeat-purchase volumes through maintenance regimens requiring quarterly retreatment.
- Dermal Fillers:Cross-linked hyaluronic acid and calcium hydroxylapatite gels restore volume loss and contour facial anatomy. Saudi Arabia's hospital-affiliated dermatology departments concentrate demand for premium cohesive polydensified matrix products.
- Laser Devices:Energy platforms operating across 532 nm to 10,600 nm wavelengths target specific chromophores for lesion removal and resurfacing.
- Chemical Peels:Acid-based exfoliating solutions ranging from superficial glycolic to deep phenol formulations address photodamage and dyschromia.
Botulinum toxin sits at the top of the volume ranking, with dermal fillers climbing the fastest across North African expansion markets.
Technology:
Capital intensity and service infrastructure requirements stratify technology adoption between Gulf premium tiers and sub-Saharan volume plays.
- Laser Therapy:Solid-state and diode laser systems deliver selective photothermolysis for pigmentation, vascular lesions, and hair reduction. South Africa's Johannesburg clinic clusters absorb disproportionate installed base despite wavelength limitations on darker phototypes.
- Radiofrequency:Electromagnetic energy devices generate dermal heating through tissue resistance, enabling non-ablative skin tightening. Riyadh's high-volume chains are retrofitting treatment rooms with microneedling-convergent platforms for scar revision indications.
- Ultrasound:Microfocused ultrasound energy penetrates to fascial planes for non-surgical lifting applications.
- Cryotherapy:Controlled cold exposure devices target adipocyte apoptosis and superficial lesion destruction.
Laser therapy commands the largest installed base, though radiofrequency platforms are gaining share fastest through combination system deployments.
Application:
Clinical indication breadth and reimbursement-adjacent positioning determine addressable patient pools across the region's fragmented provider landscape.
- Facial Rejuvenation:Comprehensive treatment protocols combining neuromodulators, fillers, and energy devices address photoaging and volume loss. Dubai's medical tourism corridors concentrate international patient demand for multi-modality rejuvenation packages.
- Hair Removal:Laser and intense pulsed light systems target melanin-rich follicles for permanent reduction. Cultural preferences in Gulf markets elevate procedural frequency, with Riyadh and Abu Dhabi clinics reporting elevated male patient volumes.
- Acne Scars:Fractional resurfacing and subcision techniques address atrophic scarring from prior inflammatory disease.
- Stretch Marks:Laser and microneedling interventions target dermal rupture and collagen remodeling in striae distensae.
Facial rejuvenation dominates procedural volume, with hair removal expanding most quickly through male demographic penetration in Saudi Arabia.
End User:
Facility accreditation standards and capital access stratify procurement patterns across institutional tiers.
- Clinics:Dedicated dermatology and aesthetic medicine practices concentrate procedural volume and technology investment. Dubai-based clinic chains are unbundling after-sales service contracts to compress total cost of ownership across multi-year equipment cycles.
- Hospitals:Hospital-affiliated dermatology departments in Saudi Arabia leverage procurement scale for direct manufacturer negotiations, bypassing traditional distributor markups.
- Spas:Wellness-oriented facilities operate under lighter regulatory supervision with restricted device classes.
- Home Care:Consumer-grade devices and topical systems address maintenance between professional treatments.
Clinics absorb the dominant share of premium device procurement, with hospitals expanding their aesthetic service portfolios fastest through integrated delivery networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium procedural pricing while South Africa absorbs disproportionate volume across sub-Saharan territories, creating divergent commercial resource allocation imperatives for suppliers.
United Arab Emirates
MOHAP's 2023 device registration amendments mandate enhanced clinical evidence packages for energy-based platforms entering the UAE market. Dubai's medical tourism corridors concentrate international patient demand for multi-modality rejuvenation packages, with high-net-worth individuals driving premium facial rejuvenation and hair removal services.
Saudi Arabia
SFDA registration protocols elevate standards for energy-based platform entry, filtering out undercapitalized entrants and concentrating procurement among compliant suppliers. Riyadh's hospital-affiliated dermatology departments leverage procurement scale for direct manufacturer negotiations, bypassing traditional distributor markups through unbundled after-sales service contracts.
South Africa
Health Products Regulatory Authority standards for energy-emitting devices create compliance overlays favoring suppliers with dedicated African regulatory teams. Johannesburg clinic clusters absorb disproportionate installed base despite wavelength limitations on darker phototypes, while distribution infrastructure beyond Johannesburg and Cape Town remains thin.
Egypt
Underpenetrated aesthetic service markets relative to Gulf saturation offer volume scalability for injectable biologics and mid-tier energy devices. Cairo's expanding private dermatology practice networks are retrofitting treatment rooms with radiofrequency-convergent platforms for scar revision indications.
Morocco
Casablanca's emerging clinic chains are accelerating practitioner certification timelines through localized training partnerships. The country's national pharmaceutical regulator applies parallel standards for device registration, creating procurement friction that favors established multinationals with regional regulatory bandwidth.
Middle East and Africa Aesthetic Dermatology Market Competitive Landscape
Top-tier vendors anchor premium energy-based and injectable portfolios, while mid-tier specialists concentrate on radiofrequency-convergent platforms and regional distribution infrastructure. Market structure tilts toward consolidation among established multinationals with dedicated compliance bandwidth across SFDA and MOHAP jurisdictions. Three strategic archetypes dominate: R&D-anchored biologics developers, Dubai-based service infrastructure deployers, and direct-to-clinic distribution builders. Competitive moves concentrate on unbundling after-sales service contracts and compressing total cost of ownership across multi-year equipment cycles.
Among the named participants, Merz Pharma and Alma Lasers occupy distinct archetype positions. Merz Pharma exemplifies the R&D-anchored biologics developer with sustained premium positioning in botulinum toxin and filler portfolios. Alma Lasers sits within the service infrastructure deployer category, anchoring regional distribution through Dubai-based service infrastructure and localized training academies. Cutera represents the specialty energy platform segment, occupying a position among laser and radiofrequency device fabricators targeting high-volume clinic chains.
| Leading Market Players |
|---|
| Merz Pharma |
| Cutera |
| Allergan |
| Cynosure |
| Alma Lasers |
| Galderma |
| Bausch Health Companies |
| Venus Concept |
| Lumenis |
| Others |
Supply & Pricing Matrix
Imported laser resonator components from Germany and diode arrays from the United States feed into Dubai-based assembly operations, with SFDA and MOHAP certification costs layering onto landed equipment prices before distribution to Riyadh clinic chains and Johannesburg dermatology practices.
Pricing Analysis
Capacity additions in South Africa are reshaping price floors for mid-tier radiofrequency platforms serving sub-Saharan expansion markets. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement across Gulf hospital-affiliated departments, independent Dubai clinics, and North African private practices. Price differentiation rests on after-sales service bundling and MOHAP registration tier, with economy-tier buyers in Egypt and Morocco exhibiting acute sensitivity to unbundled maintenance contracts while Saudi hospital systems absorb premium pricing for direct manufacturer relationships.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia are redirecting procurement toward regional assembly partners for energy-based devices, compressing lead times for SFDA-registered platforms. Sourcing concentrates in Germany, the United States, and Israel for solid-state laser components, with hyaluronic acid raw material for dermal fillers drawing from Chinese and European fermentation facilities. Single-source vulnerability in picosecond laser crystal supply creates exposure for high-volume Dubai chains, while distribution runs through manufacturer-owned service infrastructure in the GCC and fragmented distributor networks in sub-Saharan territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory credential accumulation, with MOHAP's 2023 device registration amendments accelerating demand for compliant supplier relationships across UAE clinic procurement committees.
For Market Incumbents: Hedge against service unbundling trends by anchoring multi-year maintenance contracts through direct-to-clinic distribution investments in Saudi Arabia. Acquire dedicated African regulatory teams to defend South African installed base against emerging entrants with localized compliance infrastructure. Prioritize certification investment for darker skin phototype safety profiling to sustain premium positioning under tightening MOHAP evidence requirements.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in North African markets creates white-space opportunity for mid-tier radiofrequency platforms with simplified service architectures. Target Egypt's Cairo private practice networks and Morocco's Casablanca clinic chains with direct technical training partnerships that compress practitioner certification timelines. Pursue go-to-market positioning around unbundled after-sales contracts that undercut incumbent total cost of ownership structures.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory bandwidth concentrates procurement among SFDA-compliant suppliers with dedicated Middle East infrastructure. Frame long-term viability around credential accumulation moats across multi-jurisdictional registration portfolios. Target acquisition profiles emphasizing Dubai-based service infrastructure deployers with established training academy networks. Watch picosecond laser replacement cycles in Gulf dermatology chains as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Investment | Accelerates market access for energy-based platforms entering Saudi hospital procurement pipelines. |
| Direct-to-Clinic Distribution Buildout | Compresses distributor markups for high-volume Riyadh clinic chains unbundling service contracts. |
| Localized Training Academy Partnership | Expands addressable clinician pools across GCC markets facing MOHAP certification bottlenecks. |
| Dark Skin Phototype Safety Portfolio | Aligns with MOHAP 2023 evidence mandates for UAE energy-based device registrations. |
| North African Regulatory Team Deployment | Captures volume scalability in underpenetrated Egypt and Morocco injectable biologics markets. |
Research Methodology
Bottom-up clinic procurement modeling reconciled against top-down device shipment tracking forms the analytical core of this study. Primary interviews with dermatology department heads, biomedical engineers at hospital purchasing committees, GPO contracts managers, and regulatory affairs specialists at multinational device manufacturers combined with secondary validation against SFDA registration databases, MOHAP device approval listings, and customs import records for laser and radiofrequency equipment. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped energy-based device installations against injectable biologics consumption patterns across the analysis window. Segmentation dimensions modeled include product category, technology platform, clinical application, and facility accreditation tier, with CAGRs derived from regression analysis of historical procurement trajectories and regulatory milestone impacts. Forecast inputs incorporated MOHAP registration timeline extensions and SFDA protocol elevation effects on market entry velocity.
Caveats apply where regulatory amendment timelines or supply chain disruptions in laser component sourcing could materially shift the outlook. Forecasts reflect assumptions around certification backlog resolution and practitioner training pipeline expansion that remain sensitive to policy implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Dermal Fillers and Botulinum Toxin Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Brazil Aesthetic Facial Threads Market
Aesthetic Medicine
Photorejuvenation Market
Aesthetic Medicine
Chemical Peel Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Global Stretch Marks Treatment Market