
 United States Surveillance Analog Camera Market | 2026-2036
United States Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
United States Surveillance Analog Camera Market Insights
NDAA Section 889 compliance certification is rotating vendor eligibility for federal surveillance contracts, disqualifying equipment from certain overseas manufacturers. Hikvision Digital Technology Co., Ltd. navigates these restrictions through indirect channel structures and non-federal customer segments. Honeywell International Inc. leverages its domestic manufacturing footprint to sustain eligibility for government and critical infrastructure projects. Bosch Sicherheitssysteme GmbH anchors its position through German-engineered reliability credentials that appeal to premium security integrators.
United States surveillance analog cameras employ coaxial cable transmission of continuous electrical video signals, typically operating at resolutions up to 960H or 720TVL with composite video output for direct monitor or DVR connection, serving environments where real-time latency-free monitoring outweighs analytics requirements. Dome cameras occupy the largest installed base across retail and commercial verticals due to vandal-resistant housings and discreet positioning advantages. Bullet cameras dominate perimeter and outdoor applications where weather-sealed enclosures and visible deterrence value justify their form factor. PTZ cameras retain specialized demand in government facilities and large industrial sites requiring operator-controlled directional coverage.
FCC equipment authorization rules govern RF emissions for wireless analog transmission variants, while NDAA procurement restrictions shape federal buyer vendor pools. The Department of Homeland Security's SAFETY Act certification influences product selection for critical infrastructure operators seeking liability protections. Stakeholders must monitor the trajectory of FCC spectrum reallocation proceedings and potential analog sunset mandates that could accelerate replacement timelines beyond current replacement-cycle assumptions.
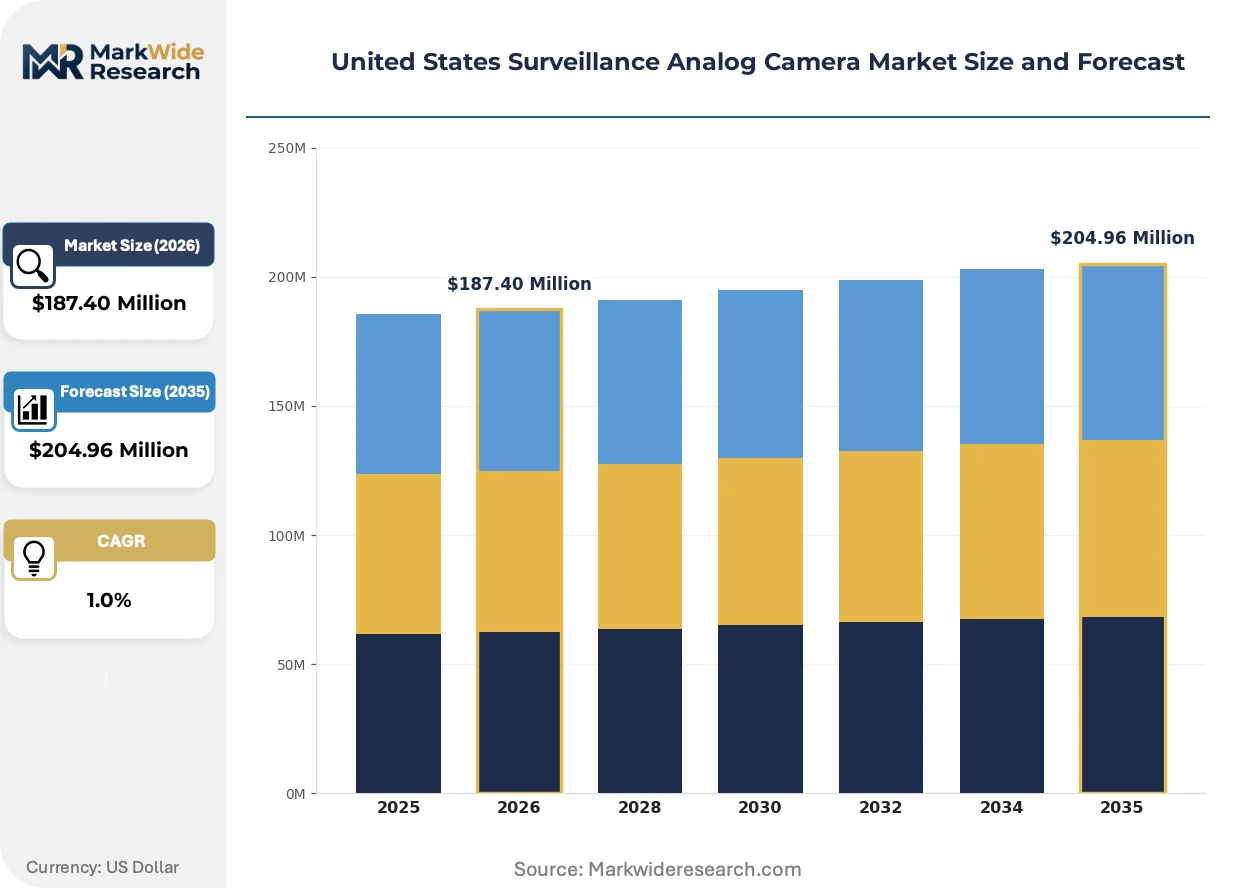
Market Dynamics
NDAA Section 889 procurement restrictions are forcing federal buyers to rebuild vendor pools while legacy coaxial infrastructure in correctional facilities and border installations sustains replacement demand for analog equipment.
Growth Catalysts
- Correctional facility refresh cycles:State and county detention centers maintain multi-year analog replacement schedules due to hardened infrastructure and staff familiarity with coaxial-based monitoring systems.
- FCC equipment authorization pathways:Wireless analog transmission variants gain compliance clarity through established RF emission certification frameworks, reducing time-to-market for manufacturers.
- Southwestern municipal retrofit programs:Arizona, Texas, and New Mexico border security installations preserve analog procurement flows through federally funded infrastructure grants.
Market Restraints
- Copper coaxial cable cost volatility:Raw material price swings for RG-59 and RG-6 cabling compress integrator margins on large-scale analog deployments.
- 960H resolution ceiling:Technical limitations prevent analog systems from meeting emerging evidentiary clarity standards in judicial and law enforcement applications.
- IP camera substitution pressure:Network-based surveillance systems with Power-over-Ethernet infrastructure threaten analog's cost advantage in greenfield commercial construction.
Strategic Opportunities
- Rural Midwest municipal underpenetration:Smaller Illinois, Ohio, and Indiana jurisdictions with limited IT staffing favor analog's plug-and-play maintenance profile over complex networked alternatives.
- Hybrid DVR-analog convergence:Tribrid recording platforms supporting analog, HD-TVI, and IP inputs simultaneously extend equipment lifecycles while enabling phased migration.
- Department of Homeland Security SAFETY Act certification:Liability protection incentives drive critical infrastructure operators toward certified analog vendors for perimeter monitoring applications.
Industry Challenges
- Coaxial splicing technician scarcity:Declining vocational training programs for BNC connector installation and cable termination create field service bottlenecks.
- NDAA compliance documentation burden:Federal contractors face extended vetting timelines to certify supply chain provenance and manufacturing origin for each component.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Surveillance Analog Camera Market |
| Market Size in 2026 | $187.40 Million |
| Market Size in 2035 | $204.96 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Box Cameras Technology: Standard Definition, High Definition, Infrared, Networked End User: Retail Stores, Government Facilities, Residential Properties, Industrial Sites Installation Type: Wired, Wireless, Surface Mount, Ceiling Mount |
| Companies Covered | Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Hanwha Vision America, Honeywell International Inc., Bosch Sicherheitssysteme GmbH, Motorola Solutions (Pelco), Axis Communications AB, Johnson Controls International plc, IDIS Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Surveillance Analog Camera Market Trends and Innovations
Technology trajectories in the United States surveillance analog camera market center on extending legacy infrastructure relevance while regulatory compliance reshapes competitive eligibility.
HD-TVI (High Definition Transport Video Interface) signal processors are displacing standard-definition analog chipsets in dome and bullet camera assemblies. Correctional facilities in Texas and Arizona are adopting these hybrid-capable units at replacement-cycle pace. This displacement compresses pure analog component demand while preserving coaxial cable investments.
FCC spectrum reallocation proceedings for the 600 MHz band are forcing wireless analog transmission equipment redesigns. Manufacturers must retune RF modules to avoid interference with cellular services. Border patrol installations in the Southwest are most affected, with integrators stockpiling legacy-frequency inventory ahead of sunset deadlines.
Buyer preference for equipment unbundling from installation services is fragmenting traditional distribution relationships. Security integrators in the Mountain West states are sourcing cameras directly through wholesale distributors rather than manufacturer representatives. This channel compression is most visible among mid-sized municipal customers seeking price transparency on replacement projects.
United States Surveillance Analog Camera Market Segmentation
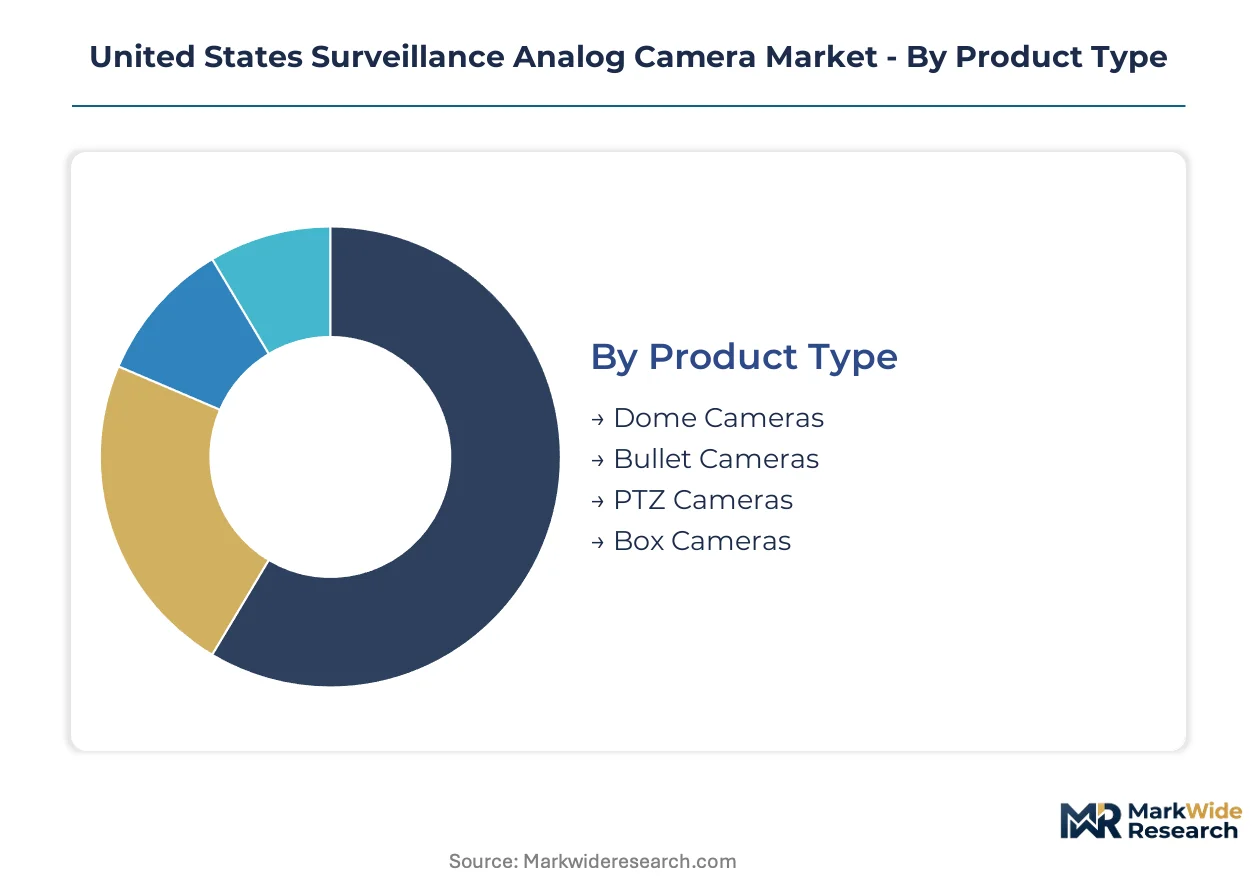
Segmentation in the United States surveillance analog camera market reveals how procurement patterns diverge across institutional buyers with varying infrastructure constraints. Federal compliance requirements and legacy system compatibility create distinct margin profiles that favor certain configurations over others.
Product Type:
Margin pools concentrate in vandal-resistant form factors serving high-turnover commercial environments where replacement frequency sustains recurring revenue.
- Dome Cameras:Vandal-resistant housings with discreet positioning capabilities serve retail and commercial verticals. Demand clusters in Texas and Arizona retail corridors where discreet positioning outweighs visible deterrence requirements.
- Bullet Cameras:Weather-sealed enclosures with visible deterrence value dominate Southwestern border installations and perimeter applications. Arizona correctional facilities specify these for exterior coverage where environmental sealing justifies procurement premiums.
- PTZ Cameras:Operator-controlled directional coverage retains specialized demand in federal facilities and large industrial sites.
- Box Cameras:Modular lens configurations serve custom integration projects requiring specialized focal lengths.
Dome cameras hold installed capacity. Bullet cameras are rotating up the share rankings.
Technology:
Resolution tiers separate replacement-cycle timing across federal, municipal, and commercial buyer pools with different evidentiary requirements.
- Standard Definition:960H and 720TVL composite video output serves cost-constrained municipal retrofits. Illinois and Ohio counties maintain these systems where IT staffing limitations favor plug-and-play maintenance over networked complexity.
- High Definition:HD-TVI signal processors preserve coaxial investments while meeting emerging clarity standards. Texas correctional facilities are adopting these hybrid-capable units at replacement-cycle pace to bridge legacy and evidentiary requirements.
- Infrared:Low-light imaging modules extend operational hours for perimeter monitoring applications.
- Networked:Hybrid transmission variants support phased infrastructure migration paths.
Standard Definition retains the largest installed base. High Definition is climbing the fastest among technology tiers.
End User:
Budget cycles and compliance burdens fragment procurement authority across institutional buyers with divergent vendor qualification requirements.
- Government Facilities:NDAA Section 889 compliance mandates reshape federal vendor pools. Department of Homeland Security SAFETY Act certification drives selection for critical infrastructure operators seeking liability protections.
- Retail Stores:Loss prevention departments prioritize vandal-resistant dome configurations with minimal maintenance requirements.
- Residential Properties:Small-scale installations favor wireless variants reducing cabling labor costs.
- Industrial Sites:Harsh environment specifications demand weather-sealed enclosures with extended temperature operating ranges.
Government Facilities anchor procurement volume. Retail Stores are gaining share fastest as loss prevention budgets recover.
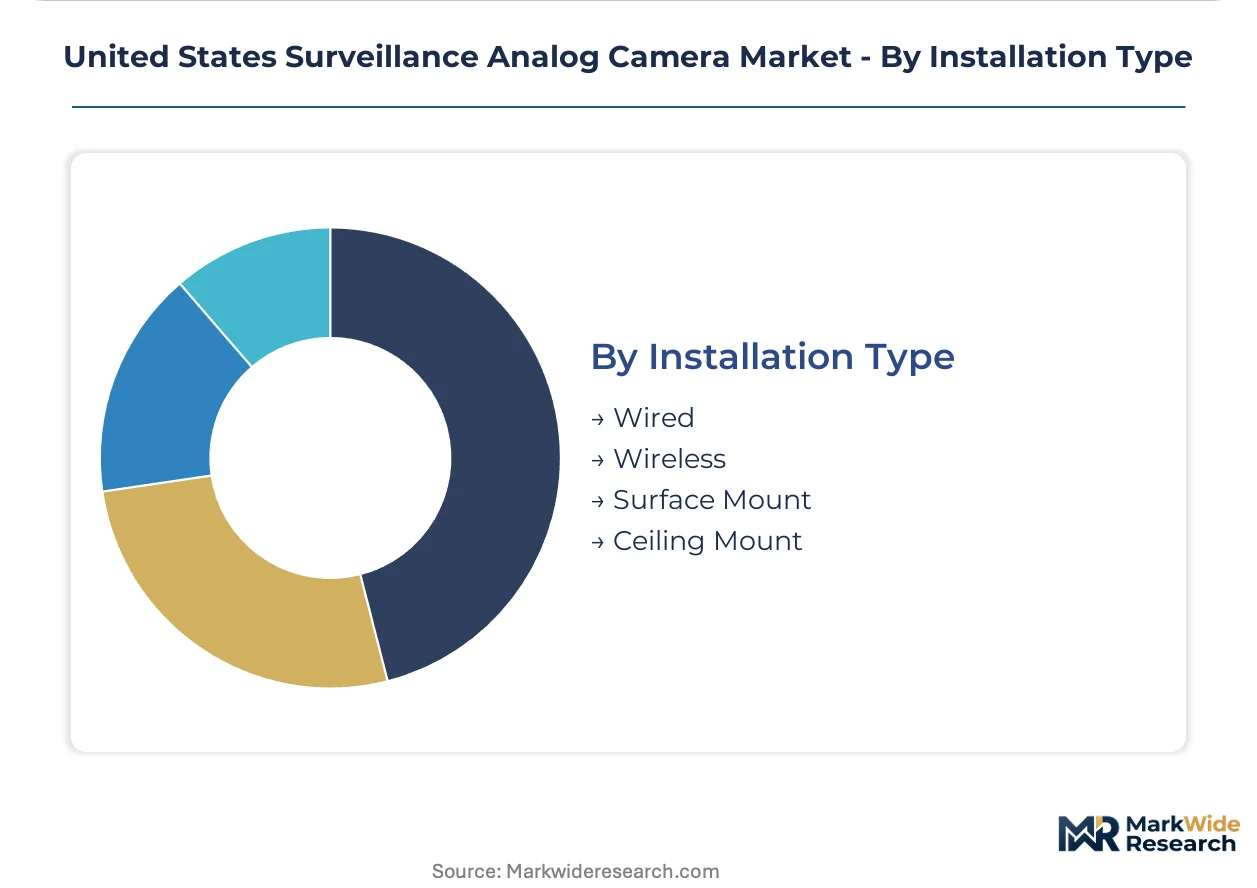
Installation Type:
Labor availability and infrastructure age determine whether buyers prioritize cabling minimization or signal reliability.
- Wired:Coaxial cable transmission of continuous electrical signals serves hardened infrastructure in correctional facilities. Texas and Arizona detention centers maintain these systems where staff familiarity with BNC-terminated RG-59 cabling reduces training burdens.
- Wireless:RF transmission variants require FCC equipment authorization for compliance. Southwestern border patrol installations face redesign pressures from 600 MHz spectrum reallocation proceedings.
- Surface Mount:Exposed positioning suits applications where visible deterrence value matters.
- Ceiling Mount:Recessed positioning supports discreet retail and commercial deployments.
Wired installations hold capacity dominance. Wireless is expanding most quickly as labor constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure grants and NDAA compliance mandates are redistributing procurement authority across state and municipal buyers, concentrating equipment flows in jurisdictions with hardened legacy installations and border security priorities.
Southwest
Texas and Arizona detention centers sustain multi-year analog replacement schedules where coaxial infrastructure and staff familiarity outweigh migration costs. FCC spectrum reallocation proceedings for the 600 MHz band are forcing wireless transmission equipment redesigns in border patrol installations. El Paso and Tucson security integrators are stockpiling legacy-frequency inventory ahead of sunset deadlines.
Midwest
Illinois and Ohio counties with limited IT staffing favor plug-and-play analog maintenance over networked complexity. State procurement offices in these jurisdictions maintain standardized equipment lists that preserve coaxial-based vendor relationships. Cleveland and Columbus municipal retrofit programs channel federal grants toward correctional facility infrastructure refresh cycles.
Southeast
Florida and Georgia retail corridors generate recurring demand for vandal-resistant dome configurations in loss prevention applications. State-level detention facility standards in these jurisdictions specify hardened analog systems for operational reliability. Miami-Dade and Atlanta metropolitan integrators report sustained procurement volumes from commercial security upgrades.
Mountain West
Colorado and Utah municipalities with dispersed geographic footprints prioritize wireless analog variants to minimize cabling labor across remote installations. FCC equipment authorization requirements shape product selection for RF-emitting devices in these jurisdictions. Denver security distributors report direct sourcing trends among mid-sized municipal customers seeking price transparency.
Northeast
New York and Massachusetts correctional facilities maintain legacy coaxial infrastructure where judicial evidentiary requirements have delayed full IP migration. State procurement compliance offices in these jurisdictions enforce NDAA Section 889 vendor vetting for federally funded projects. Boston and Albany integrators specialize in hybrid DVR-analog convergence for phased infrastructure upgrades.
United States Surveillance Analog Camera Market Competitive Landscape
Player mix skews toward diversified security conglomerates with domestic manufacturing footprints and specialized video surveillance pure-plays with indirect channel structures. Market structure reflects tiered competitive positioning where federal eligibility requirements separate qualified from restricted vendor pools. Two strategic archetypes dominate: domestic manufacturers leveraging NDAA compliance for government access, and international suppliers routing through non-federal channels. Competitive moves center on supply chain provenance documentation and hybrid product portfolio expansion to bridge legacy and networked demand.
Among China-based manufacturers, Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. occupy positions shaped by federal procurement restrictions, channeling equipment through indirect structures and commercial segments. Honeywell International Inc. represents the domestic manufacturing archetype with eligibility for government and critical infrastructure projects. Bosch Sicherheitssysteme GmbH anchors the premium engineering tier through German-engineered reliability credentials that appeal to security integrators seeking liability protections.
| Leading Market Players |
|---|
| Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Hanwha Vision America |
| Honeywell International Inc. |
| Bosch Sicherheitssysteme GmbH |
| Motorola Solutions (Pelco) |
| Axis Communications AB |
| Johnson Controls International plc |
| IDIS Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
NDAA Section 889 compliance certification gates both vendor qualification and price differentiation simultaneously, restricting federal contract access to domestic manufacturers while channeling international suppliers toward commercial segments with compressed margin profiles. Equipment flows bifurcate between premium-priced SAFETY Act-certified units for critical infrastructure and economy-tier alternatives serving municipal retrofit programs with limited procurement authority.
Pricing Analysis
Certification level creates the primary spread between premium SAFETY Act-certified analog cameras and standard commercial-grade alternatives. Pricing stratifies across premium, standard, and economy tiers based on compliance documentation burden and after-sales service bundling. Cost compression in the standard tier is intensifying because copper coaxial cable volatility squeezes integrator margins on large-scale detention center deployments. Municipal buyers in the Midwest exhibit highest price sensitivity due to constrained tax-base funding, while federal critical infrastructure operators prioritize liability protection over unit cost.
Supply Chain Analysis
Inventory stockpiling of legacy 600 MHz wireless transmission modules precedes FCC sunset deadlines, extending lead times for border patrol installations in Texas and Arizona. Component sourcing draws from Taiwan for signal processors, China for infrared imaging sensors, and Mexico for weather-sealed enclosures. Single-source vulnerability concentrates in RF module suppliers facing forced redesign cycles. Distribution runs through security integrators in the Southwest and Mountain West, with direct wholesale sourcing fragmenting traditional manufacturer representative relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Correctional facility refresh cycles position this market for cyclical recovery as state and county detention centers advance multi-year replacement schedules deferred during budget constraints.
For Market Incumbents: Secure NDAA compliance documentation for all component provenance to defend federal vendor pool eligibility against emerging domestic challengers. Deepen backward integration into coaxial cable assembly to offset copper price volatility compressing margins on large-scale municipal projects. Prioritize SAFETY Act certification investment for perimeter monitoring product lines serving critical infrastructure operators.
For New Entrants and Emerging Players: Anchor in rural Midwest municipal jurisdictions where IT staffing scarcity favors plug-and-play analog maintenance over networked complexity. Target Illinois and Ohio counties with standardized equipment lists preserving coaxial-based vendor relationships. Pursue hybrid DVR-analog convergence partnerships with established security integrators to bypass direct federal procurement restrictions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized video surveillance divisions lacking dedicated federal compliance infrastructure. Long-term viability hinges on replacement-cycle sustainability rather than greenfield expansion. Monitor FCC spectrum reallocation proceeding outcomes as the inflection signal for wireless analog equipment obsolescence timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| SAFETY Act Certification Investment | Opens liability-protected procurement pathways for critical infrastructure operators seeking risk mitigation. |
| Hybrid DVR Platform Development | Extends coaxial infrastructure relevance while enabling phased IP migration for budget-constrained municipalities. |
| Domestic Manufacturing Footprint Expansion | Preserves NDAA Section 889 eligibility for federal detention center and border security contracts. |
| RF Module Retuning for 600 MHz Compliance | Avoids FCC interference penalties while maintaining wireless analog transmission for remote Southwest installations. |
| Direct Wholesale Distribution Partnership | Bypasses manufacturer representative markups to capture price-sensitive municipal retrofit demand in the Mountain West. |
Research Methodology
Cross-validation between primary interviews with security integrators and secondary validation through FCC equipment authorization databases anchors the qualitative findings. Conversations with detention center facilities managers, federal procurement officers, municipal IT directors, and coaxial cabling technicians inform infrastructure constraint assessments. Secondary sources include Department of Homeland Security SAFETY Act certification records, state procurement office standardized equipment lists, and SEC filings from diversified security conglomerates. Bottom-up demand modeling triangulates against top-down federal infrastructure grant allocations.
Sensitivity analysis around copper price trajectories and FCC spectrum reallocation timing shapes the analytical framework across the projection horizon. Segmentation dimensions include product form factor, resolution technology, end-user compliance tier, installation infrastructure type, and regional procurement authority cluster. CAGRs derive from replacement-cycle pacing analysis and federal grant flow projections. Industry-specific inputs encompass correctional facility bed-count expansion plans and border patrol technology refresh schedules.
Decision-makers should treat outputs as directional under sustained federal infrastructure funding and stable copper commodity pricing assumptions; material deviation would warrant model refresh. Specific risks include accelerated analog sunset mandates and tariff disruption to coaxial cable supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
AI Surveillance System Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market