
 Europe Enterprise Biometrics Market | 2026-2036
Europe Enterprise Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Enterprise Biometrics Market Insights
Banking is recalibrating the demand profile for enterprise biometrics across Europe, with financial institutions replacing legacy password systems with multimodal authentication at branch and digital touchpoints. IDEMIA leverages its position in government credentialing to extend into commercial banking contracts across France and Benelux. NEC Corporation anchors its European presence through facial recognition deployments in UK transportation hubs and border infrastructure. Thales Group competes on hardware-software integration, supplying fingerprint and iris modules to critical national infrastructure operators.
Enterprise biometrics encompasses physiological and behavioral measurement systems that capture, process, and match unique human characteristics against enrolled templates, typically operating with false acceptance rates below 0.001% in high-security configurations. These systems serve commercial and governmental organizations seeking to eliminate credential sharing, reduce fraud exposure, and audit physical and logical access events. Fingerprint recognition occupies the largest installed base due to mature sensor economics and consumer familiarity, while facial recognition registers the fastest expansion as liveness detection algorithms neutralize presentation attacks. Cloud-based solutions are capturing disproportionate investment as European enterprises prioritize scalable identity platforms over on-premises appliance deployments.
GDPR and the EU AI Act constrain biometric deployment through purpose limitation mandates, explicit consent requirements, and prohibitions on real-time remote identification in publicly accessible spaces. ETSI standards and ISO/IEC 30107-3 liveness testing protocols shape product certification pathways for vendors seeking EU market access. Stakeholders must monitor evolving national implementations of the AI Act, as Germany's BfDI and France's CNIL develop divergent enforcement postures that will fragment compliance architectures across the continent.
Market Dynamics
The EU AI Act's risk-classification framework for biometric systems is forcing European enterprises to rearchitect their identity infrastructure around privacy-by-design principles, creating immediate compliance-driven procurement cycles.
Growth Catalysts
- GDPR Article 9 Processing Grounds:Banking and healthcare sectors leverage explicit consent exemptions for authentication purposes, expanding lawful deployment in customer-facing applications.
- Manufacturing Automation:Germany's automotive and industrial equipment producers deploy multimodal access control to eliminate credential sharing on production floors.
- Behavioral Biometrics:Continuous authentication based on keystroke dynamics and gait analysis gains traction among financial services firms seeking frictionless fraud detection.
Market Restraints
- Silicon Sensor Concentration:Fingerprint and iris module production concentrates in East Asian foundries, exposing European integrators to supply disruption and extended lead times.
- EU AI Act Prohibited Practices:Real-time remote biometric identification in public spaces faces outright bans, eliminating law enforcement and smart city revenue streams for vendors.
- Template Storage Costs:On-premise encrypted biometric database infrastructure requires substantial capital deployment, slowing SME adoption across Southern Europe.
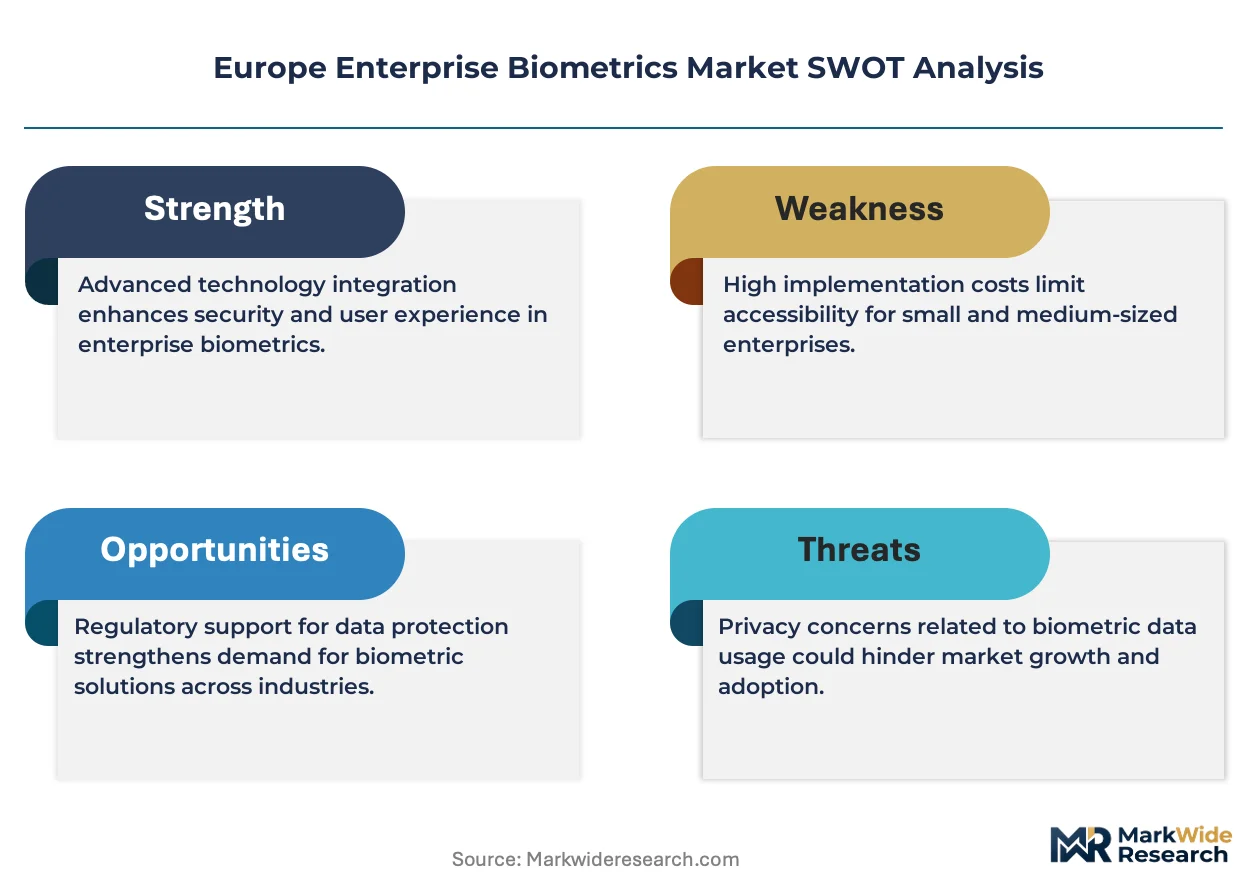
Strategic Opportunities
- Edge AI Convergence:On-device neural processing units combined with liveness detection algorithms enable offline authentication for critical infrastructure operators.
- Nordic Banking Consortiums:Sweden, Norway, and Denmark's collaborative digital identity frameworks create standardized procurement pools for cross-border authentication services.
- CSRD Reporting Mandates:Corporate sustainability disclosure requirements accelerate cloud-based biometric SaaS adoption by eliminating energy-intensive on-premise server footprints.
Industry Challenges
- ISO/IEC 30107-3 Certification Timelines:Presentation attack detection validation creates 12-18 month product launch delays for vendors seeking EU market access.
- Legacy IAM Integration:Enterprise identity and access management systems require custom API development to accommodate biometric template federation.
- Biometric Data Breach Response:Irreversibility of compromised templates forces organizations to maintain costly revocation and re-enrollment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Enterprise Biometrics Market |
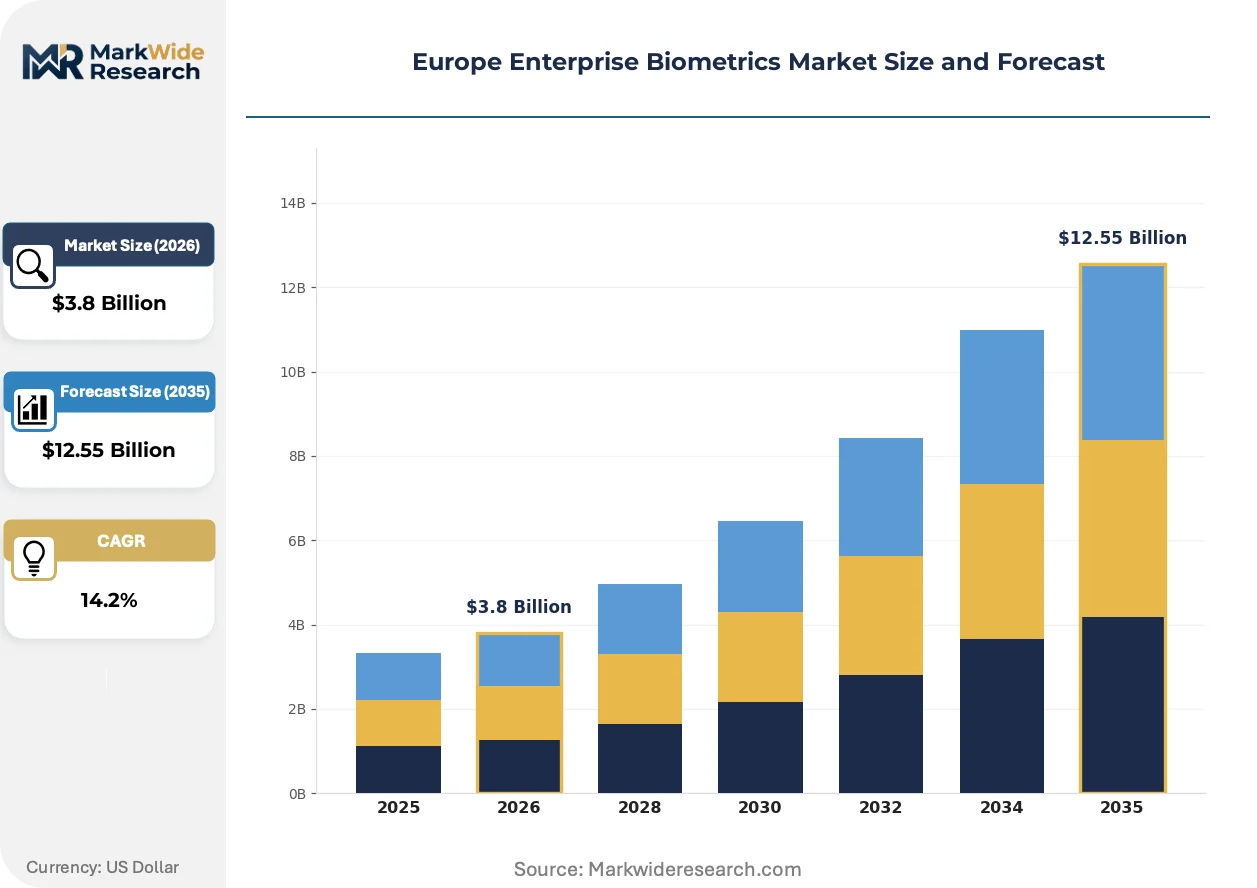
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Product Type: Hardware, Software, Cloud-Based Solutions, Integrated Systems End User: Banking, Government, Healthcare, Retail Application: Identity Verification, Access Control, Time & Attendance, Criminal Identification |
| Companies Covered | Aware, Inc., IDEMIA, NEC Corporation, DERMALOG Identification Systems GmbH, Cognitec Systems GmbH, Thales Group, Fujitsu Limited, Innovatrics, HID Global Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Enterprise Biometrics Market Trends and Innovations
Privacy-preserving cryptographic techniques are displacing raw template storage across European enterprise deployments, compressing breach exposure while complicating vendor architectures.
Contactless fingerprint sensing using ultrasonic and optical multispectral imaging is rewriting physical access control economics. Germany's critical infrastructure operators and France's healthcare campuses deploy these sensors at scale to eliminate surface contamination concerns. The technology compresses hardware replacement cycles from seven years to four as liveness detection requirements tighten.
The EU AI Act's conformity assessment obligations for high-risk biometric systems reshape vendor go-to-market strategies. Manufacturers must maintain technical documentation, risk management systems, and human oversight protocols to achieve CE marking. French and German national regulators develop divergent implementation guidance, fragmenting compliance architectures and forcing dual-track certification investments.
Financial institutions compress authentication friction by unbundling biometric verification from core banking platforms. Dutch and Belgian retail banks procure modular identity-as-a-service offerings through specialized fintech intermediaries rather than traditional security integrators. This channel shift concentrates purchasing power among cloud-native vendors with API-first architectures.
Europe Enterprise Biometrics Market Segmentation
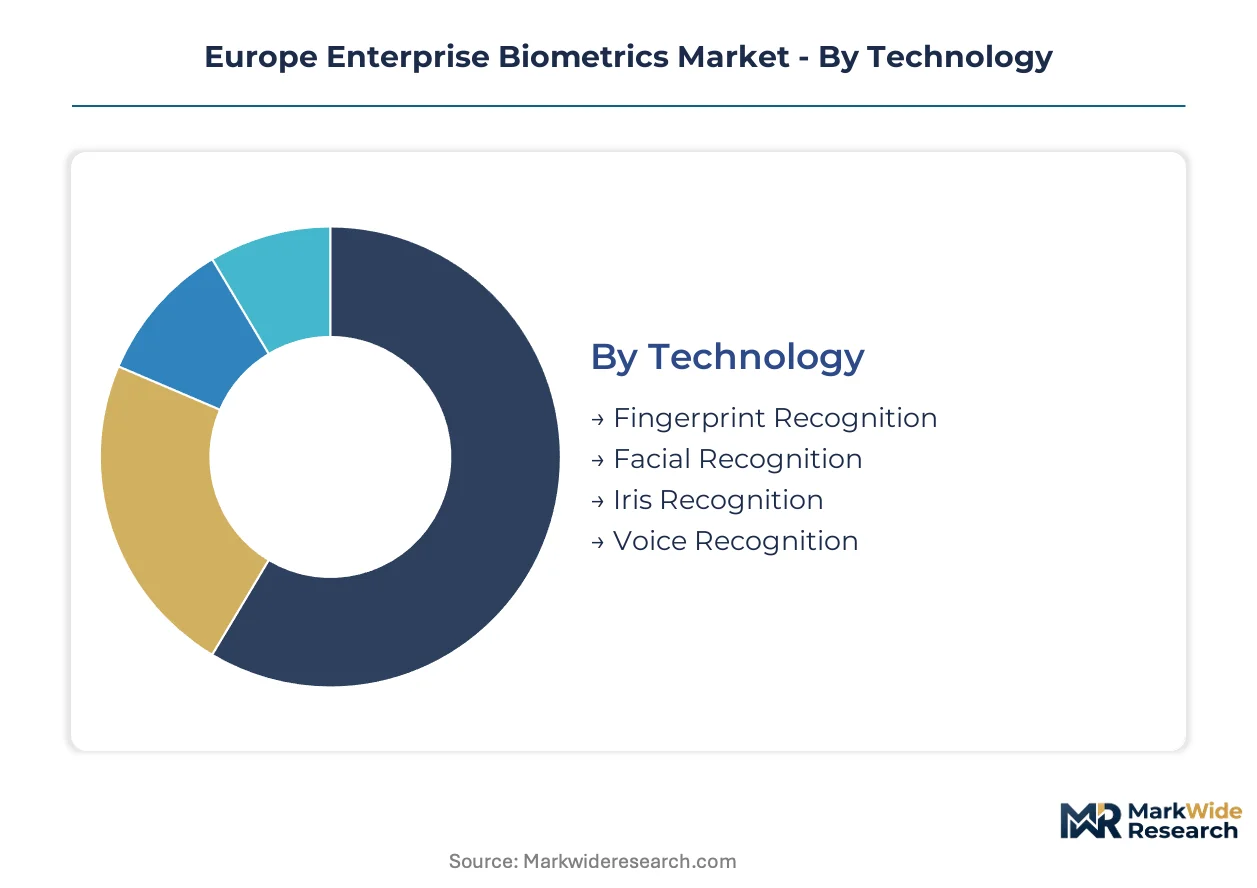
Biometric deployment patterns across European enterprises diverge sharply by technology maturity, regulatory exposure, and infrastructure integration requirements. Segmentation reveals where compliance burdens concentrate and which solution architectures capture disproportionate investment.
Technology:
ISO/IEC 30107-3 PAD certification requirements split this category between established modalities with streamlined approval pathways and emerging technologies facing extended validation timelines.
- Fingerprint Recognition:Mature sensor ecosystems using capacitive and ultrasonic acquisition dominate physical access deployments. German automotive manufacturers and French healthcare campuses standardize on multispectral imaging to eliminate surface contamination risks while satisfying GDPR data minimization principles.
- Facial Recognition:Neural network-based liveness detection algorithms now achieve sub-100 millisecond matching speeds at edge deployment. UK transportation hubs and border infrastructure drive demand despite EU AI Act prohibitions on real-time remote identification in publicly accessible spaces.
- Iris Recognition:Near-infrared acquisition systems deliver the lowest false acceptance rates for critical national infrastructure operators.
- Voice Recognition:Behavioral characteristics including cadence and pronunciation patterns enable remote authentication for call center operations.
Fingerprint recognition sits at the top of the volume ranking, with facial recognition climbing the fastest despite regulatory headwinds.
Product Type:
Capital deployment requirements and CSRD sustainability disclosure mandates are compressing demand toward subscription models that eliminate energy-intensive on-premise infrastructure.
- Hardware:Fingerprint sensors, iris cameras, and facial recognition terminals constitute the installed base. Supply concentration in East Asian foundries exposes European integrators to lead time volatility and tariff exposure.
- Software:Template matching algorithms and liveness detection modules run on standard compute infrastructure. Nordic banking consortiums in Sweden, Norway, and Denmark prioritize API-first architectures for cross-border interoperability.
- Cloud-Based Solutions:Identity-as-a-service platforms with GDPR-compliant EU data residency dominate new procurement. Dutch and Belgian retail banks favor modular procurement through specialized fintech intermediaries rather than traditional security integrators.
- Integrated Systems:Hardware-software bundles with pre-certified compliance documentation accelerate deployment timelines for risk-averse procurement teams.
Hardware retains the largest installed base, though cloud-based solutions are gaining share fastest as enterprises prioritize scalable identity platforms.
End User:
GDPR Article 9 processing grounds and sector-specific supervisory authority guidance fragment deployment permissibility across institutional categories.
- Banking:Multimodal authentication replaces legacy password systems at branch and digital touchpoints. Explicit consent exemptions for authentication purposes expand lawful customer-facing deployment under GDPR.
- Government:Credentialing and border infrastructure applications leverage IDEMIA's established position in national identity schemes. Real-time remote biometric identification prohibitions under the EU AI Act eliminate certain law enforcement revenue streams.
- Healthcare:Patient identification and staff access control in France's hospital campuses deploy contactless modalities to reduce infection transmission vectors.
- Retail:Frictionless payment authentication and loyalty program enrollment drive experimental deployments with elevated consent documentation requirements.
Banking commands the steepest expansion trajectory, with healthcare following as contactless modalities resolve contamination concerns.
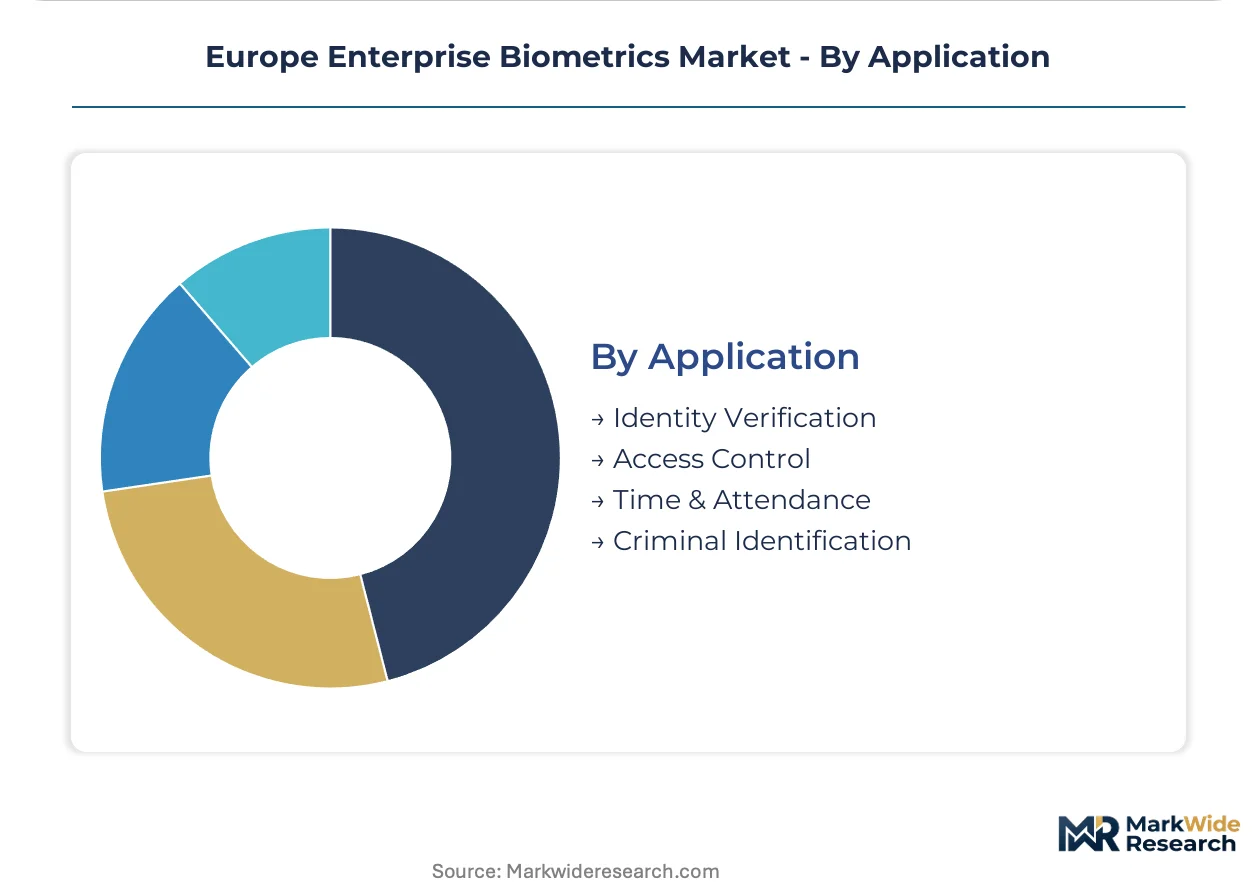
Application:
False acceptance rate requirements and audit trail specifications vary dramatically by use case, dictating sensor specification and architectural investment levels.
- Identity Verification:Customer onboarding and Know Your Customer compliance anchor demand in financial services. NEC Corporation's facial recognition deployments in UK transportation hubs exemplify high-throughput verification architectures.
- Access Control:Workforce entry management across Germany's industrial corridor eliminates credential sharing on production floors. Thales Group supplies fingerprint and iris modules to critical national infrastructure operators competing on hardware-software integration.
- Time & Attendance:Labor tracking applications in manufacturing and logistics environments prioritize speed over security tier specifications.
- Criminal Identification:Forensic matching against enrolled databases operates under strict judicial oversight and data retention limitations.
Identity verification leads volume rankings, with access control expanding most quickly as manufacturing automation accelerates multimodal deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting enterprise biometric procurement toward jurisdictions with streamlined AI Act conformity pathways. Germany and France absorb disproportionate investment as national regulators develop divergent implementation guidance, forcing vendors to maintain dual-track compliance architectures.
Germany
Automotive manufacturers and industrial equipment producers anchor multimodal access control demand across Bavaria and Baden-Württemberg. The BfDI enforces GDPR Article 9 processing grounds with explicit consent documentation requirements for workforce deployments. Stuttgart's manufacturing corridor eliminates credential sharing through fingerprint and iris modules at production facilities.
United Kingdom
Transportation hubs and border infrastructure drive facial recognition procurement despite post-Brexit regulatory divergence from EU AI Act frameworks. The Information Commissioner's Office maintains strict purpose limitation mandates for biometric data processing. London's financial district compresses authentication friction through modular identity-as-a-service platforms.
France
Healthcare campuses and critical national infrastructure operators standardize on contactless fingerprint sensing to reduce infection transmission vectors. The CNIL develops enforcement postures for high-risk biometric systems that diverge from German BfDI interpretations. Paris-based IDEMIA leverages government credentialing relationships into commercial banking contracts across the Benelux corridor.
Netherlands
Retail banks procure cloud-based authentication through specialized fintech intermediaries rather than traditional security integrators. The Dutch Data Protection Authority enforces GDPR data minimization principles for customer-facing biometric deployments. Amsterdam's digital identity consortiums create standardized procurement pools for cross-border Nordic banking services.
Sweden
Nordic collaborative digital identity frameworks concentrate demand for API-first biometric architectures among financial services firms. The Swedish Authority for Privacy Protection aligns with EU AI Act risk-classification frameworks for authentication systems. Stockholm's fintech cluster drives behavioral biometrics adoption for continuous fraud detection in digital banking channels.
Europe Enterprise Biometrics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hardware-software integrators commanding premium positioning in critical infrastructure while modular software vendors capture financial services growth. The vendor base concentrates among European-headquartered defense contractors and East Asian electronics conglomerates with established EU conformity assessment capabilities. Three archetypes dominate: government credentialing specialists extending into commercial markets, industrial automation suppliers with captive biometric divisions, and cloud-native identity platforms with API-first architectures. Competitive moves center on M&A activity targeting liveness detection algorithm developers and strategic partnerships with EU-based data residency providers.
Within the government credentialing tier, IDEMIA and Thales Group exemplify European-headquartered specialists with established national identity scheme relationships. NEC Corporation represents East Asian conglomerate positioning through transportation and border infrastructure deployments. DERMALOG Identification Systems GmbH and Cognitec Systems GmbH occupy mid-tier specialist positions with German GmbH structures and focused biometric algorithm development. These named entities anchor the competitive structure without exhaustively mapping market positions.
| Leading Market Players |
|---|
| Aware, Inc. |
| IDEMIA |
| NEC Corporation |
| DERMALOG Identification Systems GmbH |
| Cognitec Systems GmbH |
| Thales Group |
| Fujitsu Limited |
| Innovatrics |
| HID Global Corporation |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer pricing indices from East Asian foundries cascade through European biometric hardware tiers, compressing margins for fingerprint and iris module integrators while cloud-native vendors capture pricing power through subscription architectures insulated from component volatility.
Pricing Analysis
Distributor margins of 15-25% separate hardware-software bundles from direct OEM procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/IEC 30107-3 certification status and GDPR compliance documentation depth. Pricing pressure stems from CSRD-mandated sustainability disclosures accelerating cloud-based SaaS displacement of on-premise appliance sales. SMEs across Southern Europe exhibit acute price sensitivity due to template storage infrastructure capital requirements, while critical national infrastructure operators absorb premium positioning for liveness detection capabilities.
Supply Chain Analysis
Dual-sourcing requirements from German automotive manufacturers and French healthcare operators mandate qualified suppliers across both capacitive sensor and neural processing unit categories. Hardware production concentrates in Taiwan, South Korea, and mainland China, drawing from silicon wafers, near-infrared optics, and edge AI chipsets. Single-source vulnerability in ultrasonic fingerprint sensor foundries exposes European integrators to 12-18 month certification timeline disruptions. Distribution runs through specialized security integrators in Northern Europe and fintech intermediaries in the Benelux corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Enterprise Biometrics Market functions as a regulatory compounder where EU AI Act conformity assessment obligations create sustained procurement cycles for privacy-preserving authentication architectures.
For Market Incumbents: Cement defensible positioning through captive liveness detection algorithm development and dual-track BfDI-CNIL certification investments. Vertical integration into EU-based data residency infrastructure neutralizes cloud vendor encroachment. Threat concentration sits with API-first identity platforms unbundling verification from core banking systems.
For New Entrants and Emerging Players: Edge AI convergence with on-device neural processing units offers technology-first wedge into critical infrastructure operator procurement. Behavioral biometrics for continuous authentication represents the most penetrable white-space target among Nordic banking consortiums. Channel strategy should prioritize fintech intermediary relationships over traditional security integrator networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native identity platforms possessing GDPR-compliant EU data residency and modular API architectures. Long-term viability hinges on sustained regulatory fragmentation between German and French AI Act implementations. Acquisition target archetype: liveness detection algorithm developers with ISO/IEC 30107-3 certification pathways. Signal to watch: divergence in national regulator enforcement postures accelerating dual-track compliance investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 30107-3 Certification Investment | Accelerates CE marking timelines for high-risk biometric systems under EU AI Act frameworks. |
| Privacy-Preserving Cryptographic Development | Displaces raw template storage architectures, compressing breach exposure for GDPR compliance. |
| EU Data Residency Infrastructure Buildout | Satisfies GDPR data localization mandates for cloud-based identity-as-a-service platforms. |
| Behavioral Biometrics R&D Partnership | Enables continuous authentication deployment for frictionless fraud detection in digital banking. |
| Multi-Modal Sensor Integration | Combines fingerprint, iris, and facial recognition for workforce access in German manufacturing corridors. |
Research Methodology
Coverage spans Western Europe, Northern Europe, and Southern Europe, with primary inputs from each regional cluster combining structured interviews with biometric solution architects, data protection officers at financial institutions, critical infrastructure security directors, and fintech platform engineers. Secondary validation draws from ETSI standards documentation, EU AI Act implementing acts, GDPR enforcement decisions by BfDI and CNIL, and ISO/IEC certification registries. Bottom-up demand modeling triangulates against top-down market sizing across technology, product type, and end-user segments.
Granularity-level modeling distinguishes hardware, software, cloud-based, and integrated system product categories with separate pricing architectures and procurement cycle assumptions. Deployment models, organization size tiers, vertical industry exposure, and regional regulatory cluster patterns shape volume and value outputs across the projection horizon. CAGR derivation incorporates technology substitution curves for contactless modalities, compliance-driven replacement cycles, and behavioral biometrics adoption slopes in financial services.
The model holds under sustained EU AI Act implementation timelines and stable GDPR enforcement postures; deviation in national regulator divergence or East Asian supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market