
 Latin America Card-Based Access Control Market | 2026-2036
Latin America Card-Based Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Card-Based Access Control Market Insights
Brazil's manufacturing capacity for secure credential components is reshaping supply dynamics across the Latin America card-based access control landscape. HID Global Corporation leverages its established credential production footprint to sustain regional availability. ASSA ABLOY AB anchors its position through door hardware integration with card reader systems. Allegion PLC differentiates via electronic access hardware tailored to commercial building retrofits.
Card-based access control systems employ encoded credentials—typically operating at 125 kHz for proximity or 13.56 MHz for smart card applications—to authenticate identities against centralized databases and release physical entry points. These systems serve primary commercial purposes in facility security, workforce management, and audit trail generation across multi-site enterprises. RFID-based technology leads installed volumes due to legacy infrastructure prevalence, while NFC-enabled credentials represent the fastest-growing segment as mobile wallet integration expands. Cloud-based installation architectures are capturing margin pools through recurring software revenue models that offset hardware commoditization.
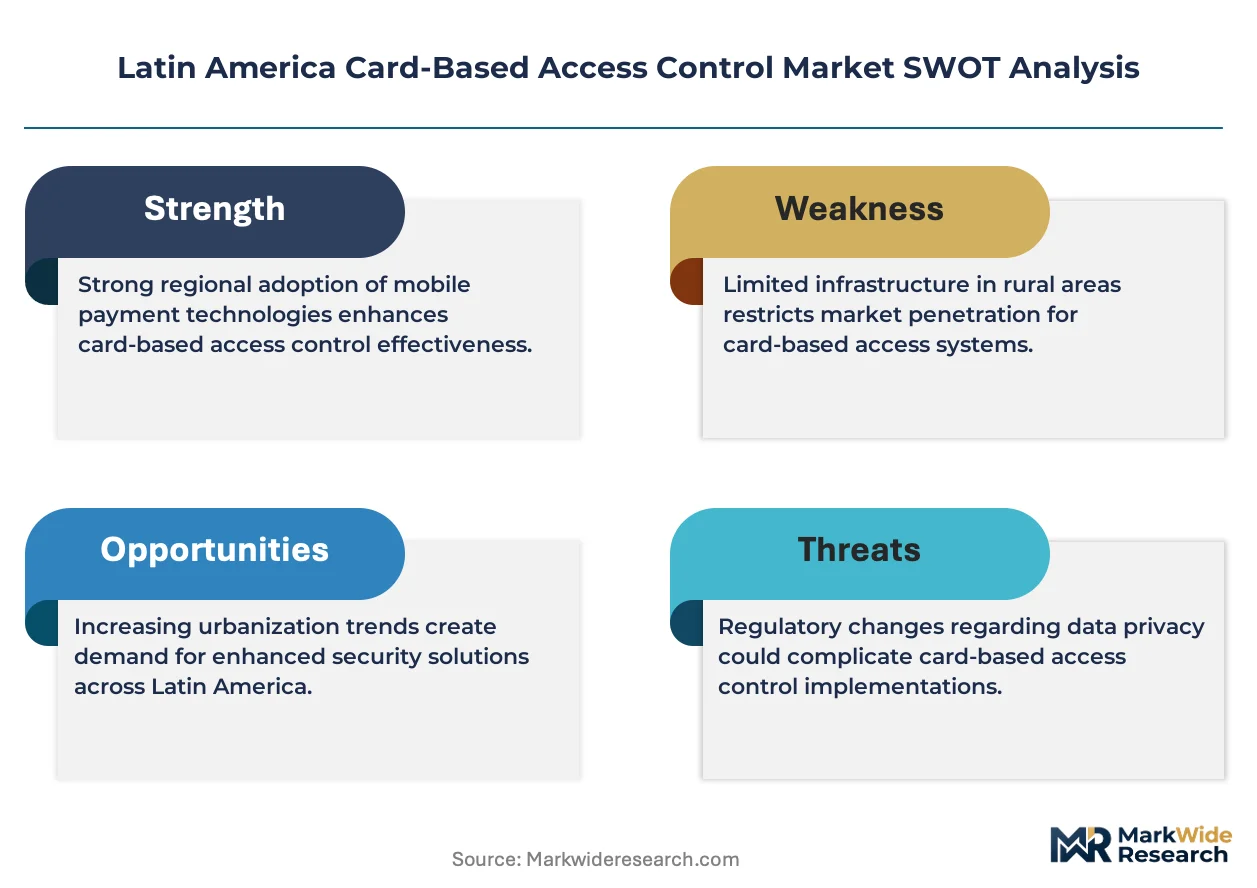
Mexico's INAI data protection standards and Brazil's LGPD framework shape product requirements for encrypted credential storage and access log retention. ANATEL certification requirements in Brazil further constrain market entry for non-compliant hardware suppliers. Stakeholders must monitor convergence between physical access credentials and digital identity wallets, as this interface will determine next-generation product specifications and partnership structures.
Market Dynamics
The convergence of Brazil's LGPD data protection mandates with Mexico's INAI standards is compressing credential encryption requirements across the Latin America card-based access control landscape. This regulatory overlay is forcing hardware suppliers to reengineer product architectures for encrypted storage and extended audit retention.
Growth Catalysts
- Corporate Security Budget Expansion:Brazil's corporate offices are allocating larger physical security expenditures as data breach liabilities escalate under LGPD enforcement.
- NFC Migration Mandates:Mexico's federal credentialing programs are accelerating contactless card deployment across government and commercial facilities.
- Manufacturing Localization:Brazil's domestic secure component production is reducing import dependency and shortening lead times for regional integrators.
Market Restraints
- ANATEL Certification Barriers:Brazil's telecommunications regulator imposes lengthy hardware approval timelines that exclude non-compliant international suppliers.
- Semiconductor Supply Concentration:Secure microcontroller sourcing remains concentrated in Asian foundries, exposing Latin American assemblers to input volatility.
- Legacy RFID Lock-In:Existing 125 kHz proximity infrastructure across aging commercial buildings creates technical friction for 13.56 MHz smart card upgrades.
Strategic Opportunities
- Colombia Infrastructure Buildout:Bogotá's commercial real estate expansion and smart city initiatives present underpenetrated demand for integrated access systems.
- Mobile Wallet Convergence:The interface between physical access credentials and digital identity wallets opens white space for platform-agnostic credential providers.
- Cloud Architecture Migration:Recurring software revenue models from cloud-based access management are capturing margin pools that hardware commoditization has eroded.
Industry Challenges
- Encryption Expertise Scarcity:Regional system integrators face acute shortages of firmware engineers capable of implementing AES-128 credential encryption.
- Multi-Site Deployment Complexity:Enterprises operating across Brazil, Mexico, and Colombia struggle with harmonizing access policies across heterogeneous legacy and modern reader infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Card-Based Access Control Market |
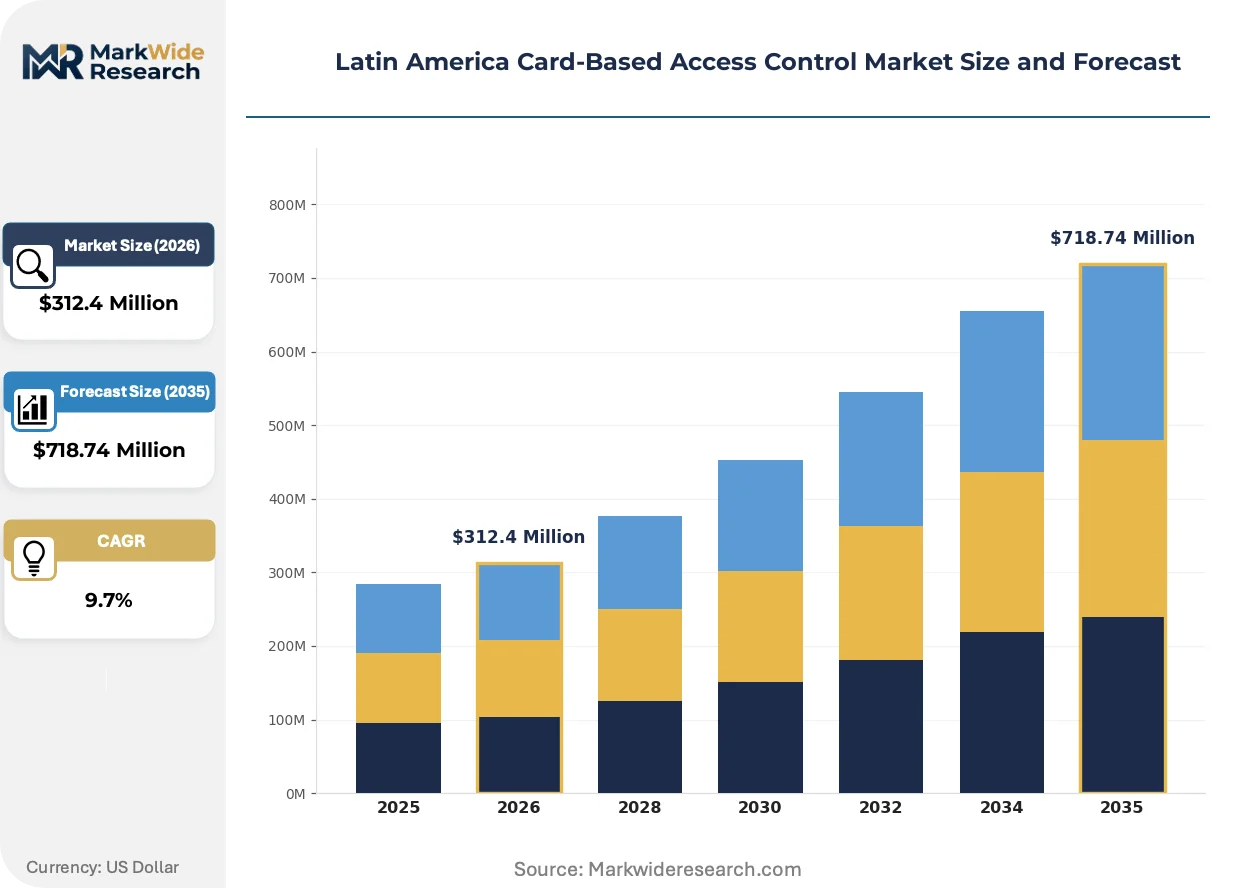
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cards, Proximity Cards, Magnetic Stripe Cards, Biometric Cards Technology: RFID, NFC, Biometrics, Optical End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Government Agencies Installation: On-Premises, Cloud-Based, Hybrid Systems, Mobile Integration |
| Companies Covered | HID Global Corporation, ASSA ABLOY AB, Allegion PLC, ADT LLC, Honeywell International Inc, Robert Bosch GmbH, Johnson Controls, Siemens, IDEMIA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Card-Based Access Control Market Trends and Innovations
Credential technology is bifurcating between legacy proximity systems and mobile-enabled smart card platforms, with deployment architecture choices increasingly determining vendor margin structures across Latin American commercial security budgets.
Multi-technology readers capable of simultaneous 125 kHz proximity and 13.56 MHz smart card authentication are hybridizing installed base migration paths. Facility managers in São Paulo and Mexico City commercial towers are specifying these units to bridge legacy credential populations with NFC-enabled mobile deployments. This dual-frequency capability is compressing rip-and-replace cycles while extending incumbent hardware lifecycles.
Brazil's ANATEL certification requirements for radio-frequency equipment are tightening electromagnetic compatibility testing protocols for card reader imports. The regulator's updated technical specifications are disqualifying lower-cost Asian hardware that lacks localized compliance documentation. Mexican and Colombian distributors are responding by prioritizing suppliers with established Brazilian regulatory affairs capabilities.
Building automation procurement teams are consolidating physical security spending under single-source facilities management contracts. This purchasing consolidation is displacing standalone access control vendors in favor of integrated building technology platforms. The shift is most visible in Brazil's Class A office developments, where landlords bundle access, HVAC, and energy management under unified service agreements.
Latin America Card-Based Access Control Market Segmentation
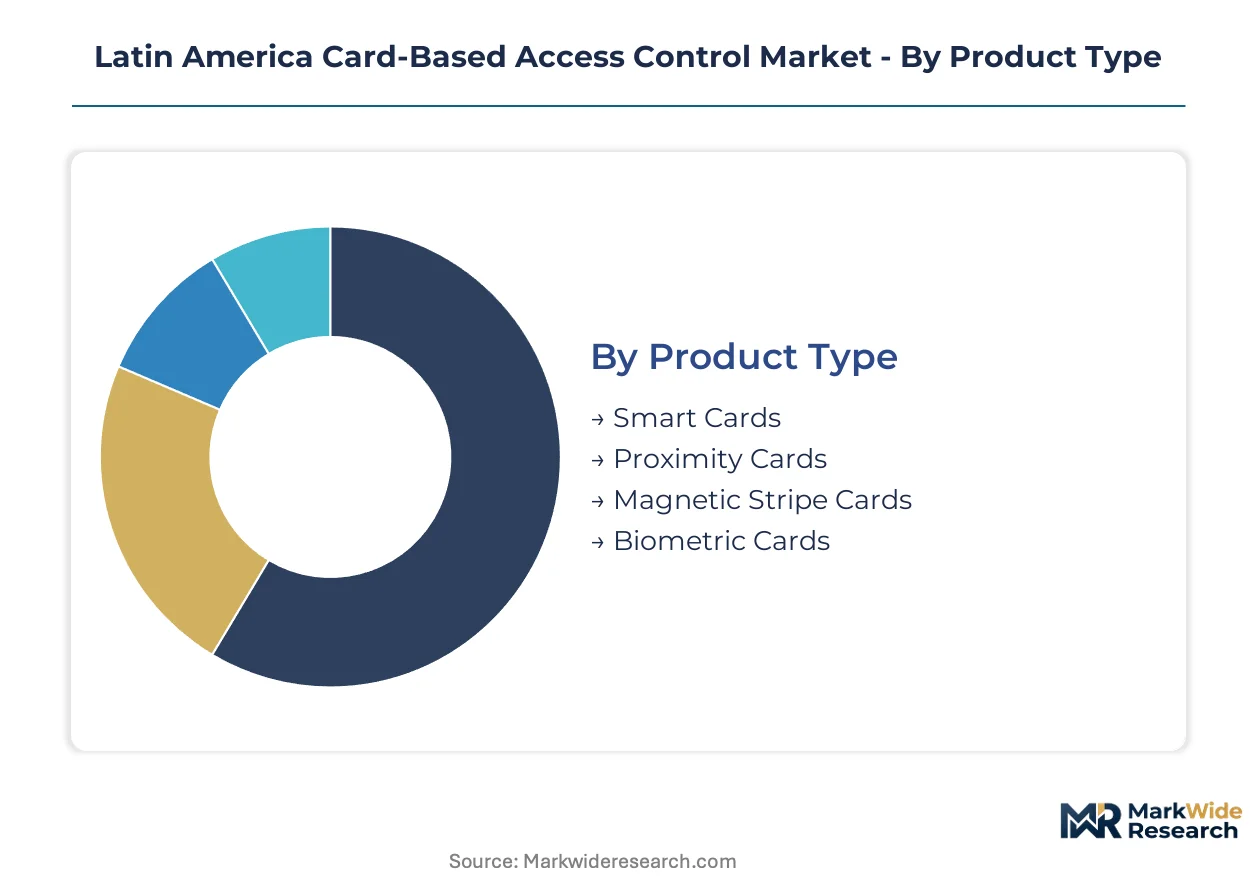
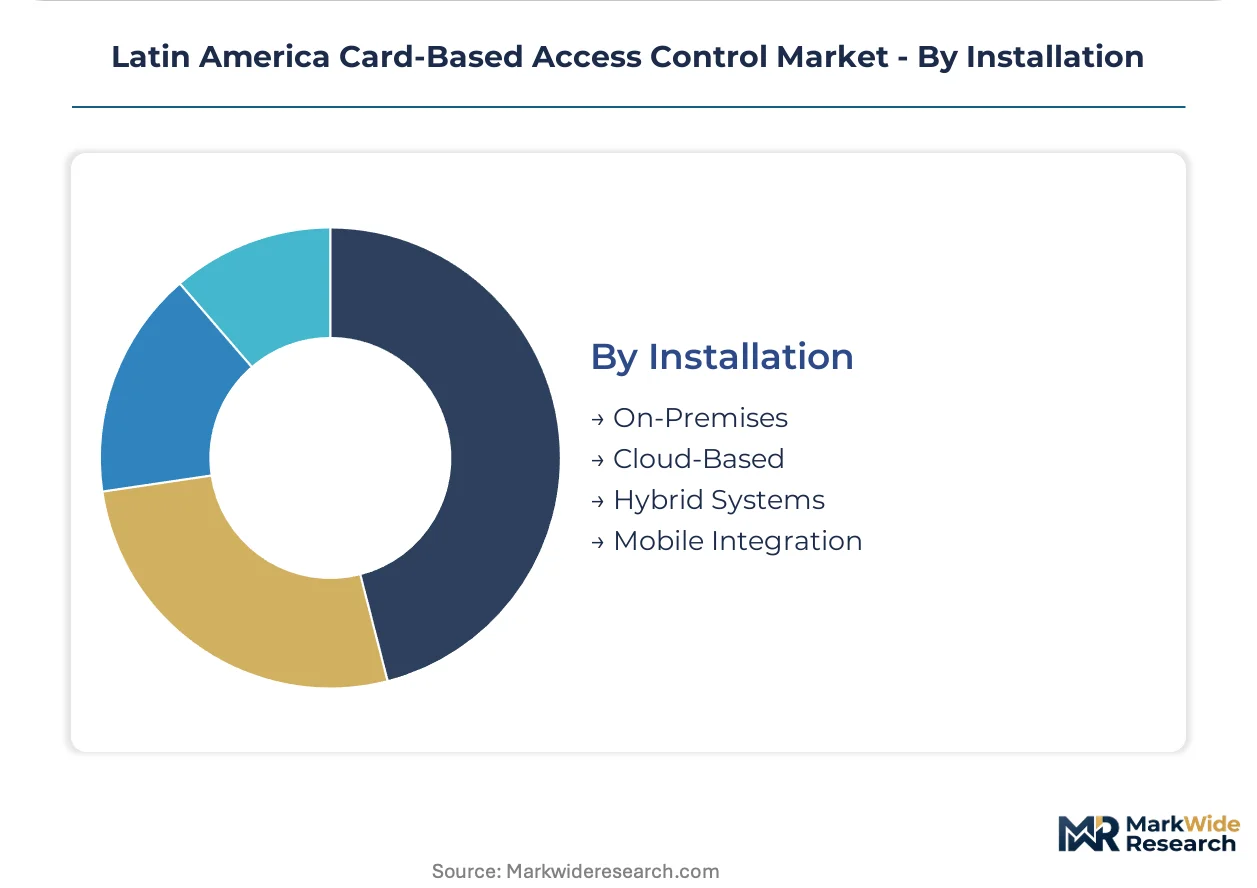
Segmentation in Latin America's card-based access control market reveals divergent technology lifecycles and deployment economics. Product architecture choices determine hardware margins, while installation models reshape recurring revenue capture across Brazilian and Mexican commercial estates.
Product Type:
Mature credential formats coexist with emerging biometric platforms across Latin American facility deployments.
- Smart Cards:13.56 MHz contactless credentials with embedded secure microcontrollers enable AES-128 encryption for LGPD and INAI compliance. São Paulo corporate towers and Mexico City government complexes are standardizing on these for multi-application campus credentials.
- Proximity Cards:Legacy 125 kHz passive RFID credentials dominate installed volumes across aging commercial buildings. Brazil's vast existing reader base creates upgrade friction, though multi-technology readers are bridging migration paths.
- Magnetic Stripe Cards:Declining format retained in budget-constrained educational institutions and smaller healthcare facilities.
- Biometric Cards:Fingerprint-on-card technology emerging in high-security federal applications and financial data centers.
Proximity cards retain volume leadership; biometric cards hold the steepest expansion curve.
Technology:
Cost tier differentiation separates established radio-frequency platforms from premium biometric and optical alternatives.
- RFID:Radio-frequency identification spans 125 kHz proximity through 13.56 MHz high-frequency bands. Brazil's manufacturing localization is reducing component costs for regional system integrators.
- NFC:Near-field communication credentials enable smartphone wallet integration. Mexico's federal credentialing mandates are accelerating contactless deployment across government and commercial sectors.
- Biometrics:Fingerprint, iris, and facial recognition modules command premium pricing in data center and research facility applications.
- Optical:Barcode and QR-based credentials persist in visitor management and temporary access scenarios.
RFID maintains installed base dominance; NFC gains share fastest through mobile convergence.
End User:
Application intensity varies sharply across customer types, with compliance exposure driving procurement sophistication.
- Corporate Offices:Brazil's Class A developments and Mexico City commercial towers are consolidating physical security under integrated building management platforms. LGPD liability exposure is expanding encryption requirements.
- Educational Institutions:Universities across Colombia and Chile are deploying multi-technology readers to bridge legacy student ID populations with mobile credential pilots.
- Healthcare Facilities:Patient data protection mandates under national health privacy frameworks are accelerating smart card adoption for staff access.
- Government Agencies:Mexico's INAI standards and federal credentialing programs are mandating encrypted contactless formats for facility entry.
Corporate offices concentrate premium spending; government agencies show the most uniform compliance-driven upgrade trajectory.
Installation:
Margin structures diverge between capital-intensive on-premises deployments and recurring-revenue cloud architectures.
- On-Premises:Local server installations with dedicated database management remain prevalent in Brazilian manufacturing and Colombian mining operations with air-gapped security requirements.
- Cloud-Based:SaaS access management platforms are capturing margin pools through subscription models. Mexico's improving data center infrastructure is enabling regional hosting compliance.
- Hybrid Systems:Edge computing with cloud backup balances latency sensitivity with centralized policy management. Preferred by multi-site enterprises operating across Brazil, Mexico, and Colombia.
- Mobile Integration:Smartphone-based credentialing via Apple Wallet and Google Pay APIs. Bogotá smart city initiatives are piloting transit-access convergence.
On-premises retains legacy dominance; mobile integration is climbing the fastest as wallet ecosystems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANATEL certification requirements in Brazil anchor regional regulatory frameworks, while Mexico's INAI standards and Colombia's smart city programs create differentiated compliance and demand environments across Latin American access control markets.
Brazil
Corporate office towers in São Paulo and Rio de Janeiro are expanding physical security budgets under LGPD enforcement pressure. ANATEL's electromagnetic compatibility testing protocols disqualify non-compliant hardware imports. Manufacturing clusters in São Paulo state are localizing secure microcontroller assembly to shorten credential lead times.
Mexico
Federal credentialing mandates are accelerating NFC-enabled contactless deployment across government facilities and commercial campuses. INAI data protection standards require encrypted access log retention extending seven years. Mexico City commercial real estate developers are bundling access control with building automation under unified facilities management contracts.
Colombia
Bogotá's smart city initiatives are piloting transit-access credential convergence for municipal workforce management. National data protection authority guidelines are tightening audit trail requirements for healthcare and financial institutions. Medellín's technology district is attracting regional system integrators establishing Andean footholds.
Chile
Mining operations in the Atacama and Antofagasta regions are specifying hybrid cloud-on-premises architectures for air-gapped security compliance. National cybersecurity frameworks are extending to physical access systems in critical infrastructure. Santiago's Class A office stock is consolidating vendor relationships under integrated building technology platforms.
Argentina
Buenos Aires commercial property managers are retrofitting legacy 125 kHz proximity systems with multi-technology readers to bridge credential populations. Central bank cybersecurity circulars are influencing access control specifications for financial data centers. Córdoba's university corridor is deploying mobile credential pilots for student campus access.
Latin America Card-Based Access Control Market Competitive Landscape
Capability concentration sits with credential technology specialists; scale advantage sits with diversified building technology conglomerates. The market exhibits tiered structure with premium encryption providers, mid-market hardware assemblers, and value-oriented distributor brands. Two strategic archetypes dominate: integrated building automation platforms and standalone access control specialists. M&A activity concentrates on cloud software capabilities, while geographic expansion targets Colombian and Chilean distribution channels.
Within the credential technology tier, HID Global Corporation and IDEMIA occupy positions exemplifying secure microcontroller and biometric authentication specialization. ASSA ABLOY AB anchors the door hardware integration archetype through its Swedish multinational structure. These three entities represent contrasting strategic positions: pure-play credential engineering, diversified physical security portfolios, and building envelope hardware convergence.
| Leading Market Players |
|---|
| HID Global Corporation |
| ASSA ABLOY AB |
| Allegion PLC |
| ADT LLC |
| Honeywell International Inc |
| Robert Bosch GmbH |
| Johnson Controls |
| Siemens |
| IDEMIA |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Brazil's secure credential assembly plants is compressing supplier margins while forcing hardware vendors to absorb ANATEL certification costs, a dynamic that simultaneously erodes pricing power for commoditized proximity readers and concentrates premium capture among encrypted smart card specialists.
Pricing Analysis
Brazil-Mexico price spreads of 15-25% for equivalent multi-technology readers reflect ANATEL compliance premiums and localized assembly advantages. Three-tier pricing structure across premium encryption, standard multi-frequency, and economy proximity tiers segments buyer budgets. Pricing pressure stems from cloud software subscriptions displacing hardware margins in corporate procurement. Educational institutions exhibit highest price sensitivity; federal agencies under INAI mandates show lowest.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates supply chain risk planning for secure microcontroller sourcing. Component flows concentrate in China, South Korea, and domestic Brazilian assembly facilities. Raw material dependencies span silicon wafers, ferrite antenna cores, and PVC card substrates. Single-source vulnerability persists for AES-128 encryption chipsets. Distribution runs through Mexico City and São Paulo-based system integrators with direct federal contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America card-based access control market is entering a cyclical recovery phase as Brazil's LGPD enforcement wave triggers replacement cycles for non-compliant legacy infrastructure.
For Market Incumbents: Pre-empt cloud-native entrants by accelerating SaaS platform development for multi-site enterprise accounts. Secure firmware engineering talent pools in São Paulo and Mexico City before encryption expertise scarcity intensifies. Defend against mobile wallet convergence threats through Apple Wallet and Google Pay API partnerships. Prioritize ANATEL certification maintenance as a barrier to Asian hardware competitors. For New Entrants and Emerging Players: Establish a beachhead in Colombia's Bogotá smart city infrastructure buildout before incumbent distribution networks consolidate. Target hybrid cloud-on-premises architectures for Chilean mining operations with air-gapped security requirements. Exploit white space in biometric card deployments for Brazilian financial data centers. Pursue direct contracting relationships with national credentialing authorities as the fastest path to volume. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based access management software as recurring revenue models reduce working capital requirements. Five-to-ten year viability favors platform-agnostic credential providers with mobile wallet integration capabilities. Acquisition target archetype: regional system integrators with established ANATEL regulatory affairs capabilities and federal contracting credentials. Watch cloud software revenue mix as the inflection indicator separating premium from commodity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Migration | SaaS architectures capture recurring revenue pools that hardware commoditization has eroded across Brazilian corporate estates. |
| Multi-Technology Reader Development | Dual-frequency 125 kHz/13.56 MHz capability bridges legacy infrastructure with NFC mobile deployments in Mexico City towers. |
| ANATEL Certification Investment | Brazilian regulatory compliance creates defensible moats against lower-cost Asian hardware imports lacking localized documentation. |
| Mobile Wallet Integration | Apple Wallet and Google Pay API partnerships position vendors for federal credentialing convergence in Mexico's INAI framework. |
| Regional Distribution Expansion | Colombian and Chilean channel control captures underpenetrated demand before integrated building technology platforms consolidate procurement. |
Research Methodology
A standing panel of physical security directors, federal credentialing program managers, system integration firm principals, and ANATEL regulatory affairs specialists provided ongoing calibration throughout the research cycle. Primary interview data combined with secondary validation from ANATEL certification databases, INAI compliance filings, Brazilian customs import records for secure components, and commercial real estate development permits across São Paulo and Mexico City. Bottom-up credential volume estimates triangulated against top-down security spending surveys from corporate facility managers.
Scenario-bracketing framed demand projections across the analysis window, modeling LGPD enforcement intensity and NFC migration pace as primary demand swing variables. Segmentation dimensions included product architecture, deployment model, end-user vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new construction penetration rates. Cloud software revenue trajectories and mobile wallet adoption curves informed technology transition timing assumptions.
Stress conditions across semiconductor supply disruption, ANATEL certification timeline extensions, and LGPD penalty escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about encryption standard adoption and federal credentialing program expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Physical Access Control Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
US Access Control Market
Access Control Systems
Smart Entry System Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Locks Market
Access Control Systems
Wireless Security System Market