
 Middle East and Africa Safety Motion Control Market | 2026-2036
Middle East and Africa Safety Motion Control Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Safety Motion Control Market Foresight
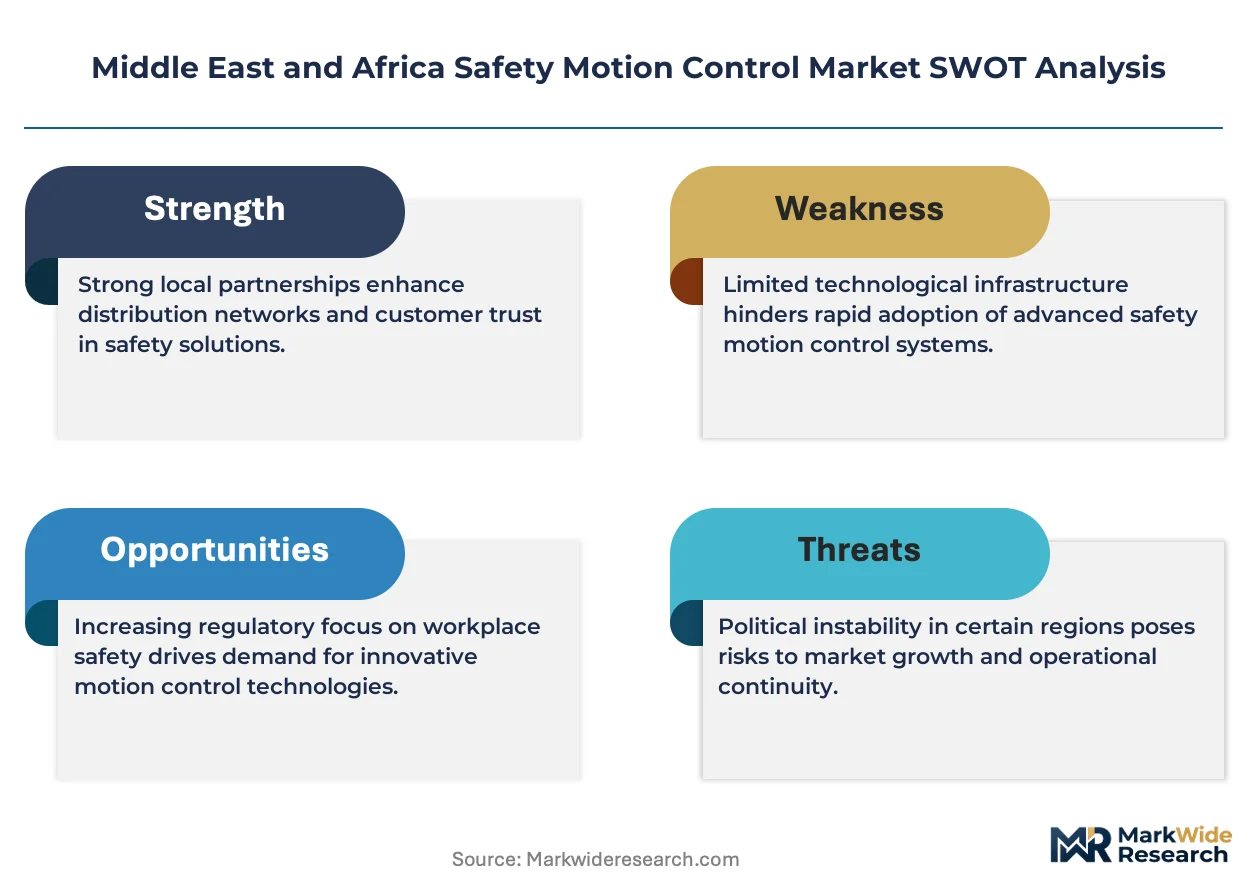
The Middle East and Africa safety motion control market is restructuring around a widening gap between premium integrated platforms and commodity safety relays. Tier-one oil and gas operators demand SIL 3-certified systems with predictive diagnostics, while smaller manufacturing facilities prioritize basic interlock devices. ABB leverages its process automation heritage to anchor large petrochemical contracts across the Gulf. Siemens competes through its TIA Portal-integrated safety portfolio, while SICK Group specializes in optoelectronic protective devices for hazardous zone applications.
Safety motion control encompasses electromechanical and electronic systems designed to monitor, restrict, or halt mechanical motion when personnel enter danger zones, typically operating with response times below 20 milliseconds and certified to IEC 61508 or ISO 13849 performance levels. These systems protect workers from crushing, shearing, and entanglement hazards in automated production environments. Safety sensors dominate product-level revenue due to mandatory guarding requirements in heavy industries, while PLC-based architectures lead technology adoption as facilities consolidate control and safety on unified platforms. The food processing end-user segment shows structural momentum from hygiene-rated safety components that withstand caustic washdown cycles.
Saudi Arabia's SFDA and the UAE's ESMA enforce machinery safety conformity assessment procedures that align with EU machinery directive principles, compelling importers to certify products through notified bodies. South Africa's Department of Employment and Labour administers occupational health inspections that drive retrofit demand in legacy mining and metals plants. Stakeholders must monitor how Egypt and Nigeria develop national standards bodies capable of enforcing safety integrity requirements as domestic manufacturing expands.
Market Dynamics
The Middle East and Africa safety motion control market is bifurcating around IEC 61508 SIL certification tiers, with Gulf petrochemical operators demanding predictive diagnostic capabilities while North African manufacturers struggle to justify premium safety architectures against basic interlock budgets.
Growth Catalysts
- SIL 3 Mandates in Hydrocarbon Processing:Saudi Arabia's SFDA and the UAE's ESMA now require functional safety assessments for rotating equipment in hazardous zones, compelling facility upgrades across Jubail Industrial City and Ruwais.
- South African Mine Safety Enforcement:The Department of Employment and Labour conducts unannounced occupational health inspections that trigger immediate retrofit demand for legacy conveyor guarding systems.
- Integrated Safety Networks:Ethernet-based safety protocols are consolidating discrete safety relays into unified PLC architectures, reducing wiring complexity and response latency in automated production lines.
Market Restraints
- Copper and Rare Earth Input Volatility:Safety encoder and servo motor production depends on copper windings and neodymium magnets, with price swings compressing margins for regional distributors.
- European Component Supply Concentration:Critical safety PLC modules and certified sensors originate from German and Swiss manufacturing bases, exposing buyers to extended lead times and currency risk.
- Substitution by Mechanical Guarding:Basic physical barriers remain the default in cost-sensitive Egyptian and Nigerian manufacturing, delaying electronic safety system adoption.
Strategic Opportunities
- Underpenetrated Moroccan Automotive:Renault-Nissan's Tangier Med plant complex and emerging EV battery suppliers create demand for hygiene-rated safety components in cleanroom assembly environments.
- UAE Free Zone Regulatory Tailwind:Dubai's Jebel Ali Free Zone Authority offers streamlined ESMA conformity assessment pathways, accelerating time-to-market for imported safety systems.
- Safety-over-EtherCAT Convergence:The integration of real-time industrial Ethernet with TÜV-certified safety stacks enables single-cable architectures that reduce installation labor in greenfield Gulf facilities.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:SIL verification and validation requires certified TÜV Rheinland or exida engineers, with fewer than 200 qualified practitioners across the entire MEA region.
- Legacy Pneumatic System Integration:Decades-old air-logic safety circuits in Saudi and South African plants resist electronic retrofit without complete control architecture replacement.
- Extended IEC 61508 Certification Timelines:Third-party assessment bodies in Europe create 9-14 month bottlenecks for new product introductions, delaying revenue recognition for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Safety Motion Control Market |
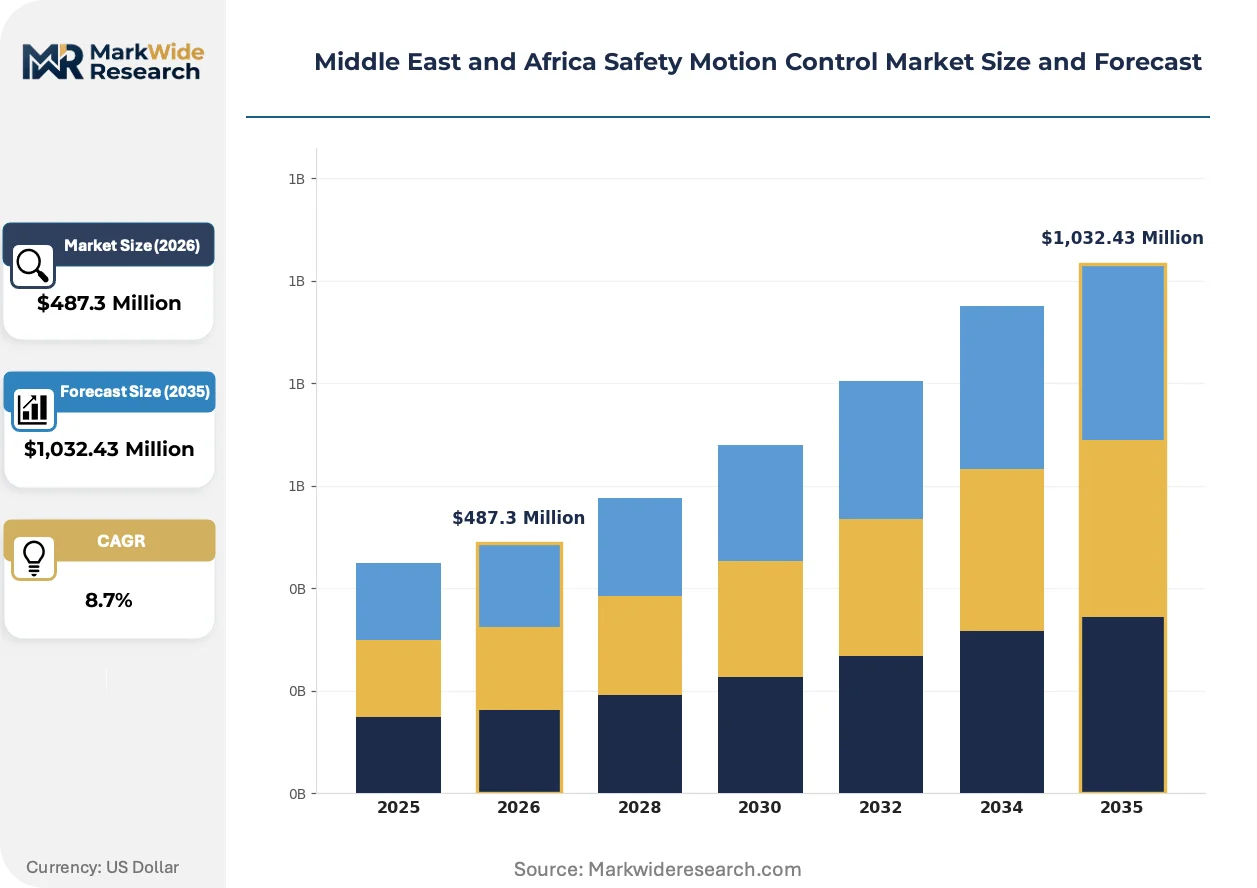
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Sensors, Control Modules, Safety Relays, Drives End User: Manufacturing, Automotive, Aerospace, Food Processing Technology: PLC-Based, Safety Networks, Safety Software, Drive Technology Application: Industrial Automation, Robotics, Material Handling, Machine Tooling |
| Companies Covered | Rockwell Automation, ABB, Schneider Electric, Mitsubishi Electric, General Electric, Siemens, SICK Group, Bosch Rexroth, Yaskawa, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Safety Motion Control Market Shifts & Advancements
Active safety architectures are displacing passive guarding across Middle Eastern process industries, while African mining operators confront legacy system obsolescence through staged retrofit programs rather than greenfield replacement.
Safe torque off functionality embedded within servo drives is overtaking external safety contactor arrangements in high-inertia applications. Oil and gas operators in Abu Dhabi's downstream corridor specify integrated safe motion modules to eliminate mechanical brake wear and reduce emergency stopping distances. The technology is compressing panel space requirements and simplifying safety circuit documentation for complex multi-axis systems.
Saudi Arabia's SFDA has aligned machinery safety conformity assessment with EU machinery directive principles, requiring notified body certification for all imported safety components. This regulatory convergence is elevating documentation burdens for Asian manufacturers while creating competitive advantage for European suppliers with existing CE infrastructure. Petrochemical end-users in Jubail now demand SIL capability certificates as standard procurement documentation.
Buyers in South Africa's platinum belt are unbundling safety system procurement from capital equipment packages, engaging specialized integrators for functional safety validation independent of OEM supply. This behavior fragments vendor relationships and extends project timelines but reduces long-term compliance risk. The pattern is most visible in Rustenburg and Limpopo mining clusters where occupational health litigation has intensified.
Middle East and Africa Safety Motion Control Market Segmentation
Safety motion control procurement in the Middle East and Africa fragments across certification tiers, end-use risk profiles, and integration architectures. Buyers in Saudi Arabia's Jubail Industrial City and South Africa's platinum belt apply divergent selection criteria that reshape vendor positioning.
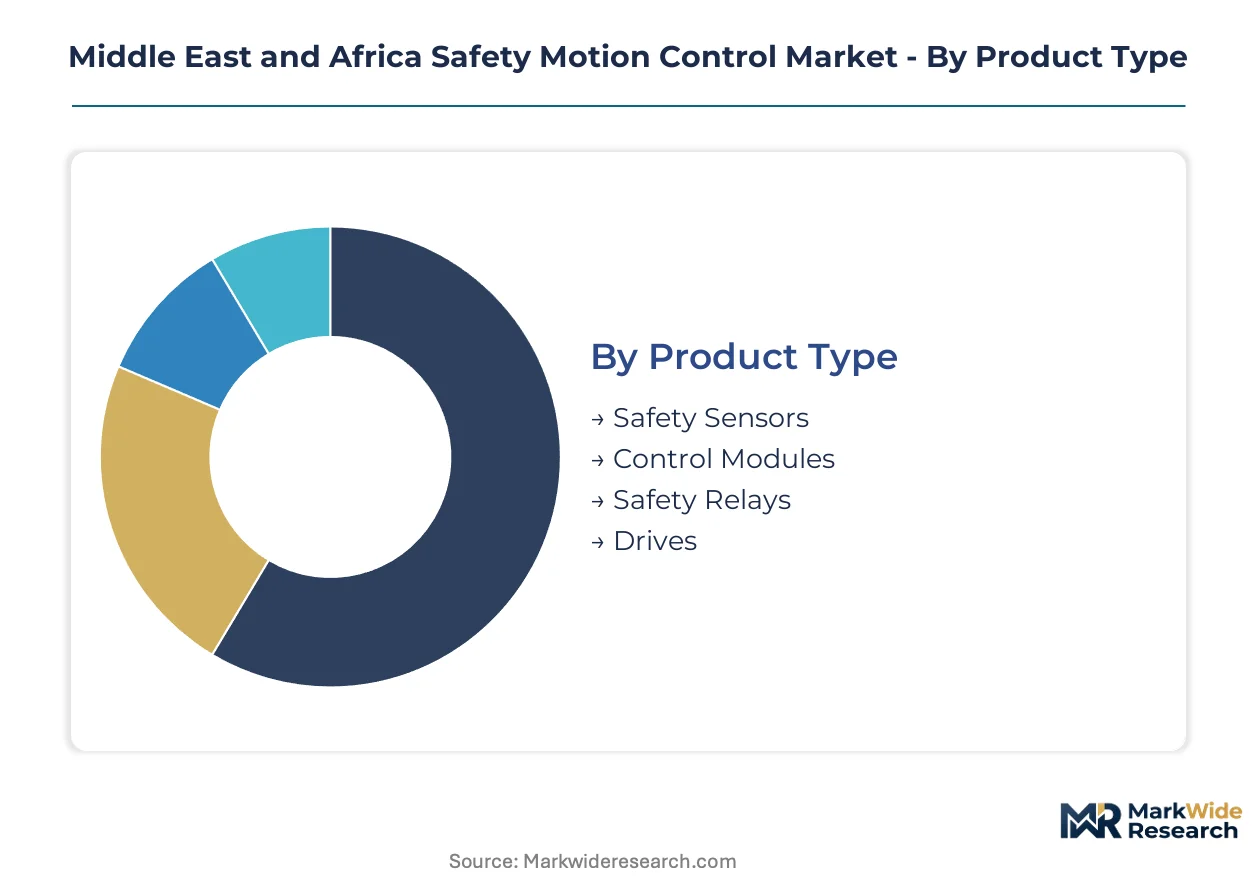
Product Type:
SIL certification requirements from Saudi Arabia's SFDA and the UAE's ESMA concentrate procurement budgets on hardware categories with TÜV-validated failure modes. Each product type carries distinct conformity assessment burdens.
- Safety Sensors:Photoelectric, laser scanner, and pressure-sensitive mat configurations detect personnel intrusion with response latencies below 10 milliseconds. Demand clusters in Saudi petrochemical facilities where zone 0/1 hazardous area ratings mandate explosion-protected housings. SFDA machinery safety directives now require third-party validation of sensor safety functions.
- Control Modules:Programmable safety controllers execute logic for complex multi-zone guarding with SIL 3 capability. South African mining operators in Rustenburg and Limpopo specify these for conveyor retrofit projects following Department of Employment and Labour enforcement actions. ESMA conformity assessment pathways in Dubai's Jebel Ali Free Zone accelerate import clearance.
- Safety Relays:Hardwired expansion modules for discrete interlock circuits.
- Drives:Servo and variable frequency units with safe torque off embedded.
Safety Sensors sits at the top of the volume ranking, with Control Modules climbing the fastest.
End User:
Regulatory pressure intensity varies sharply across end-use sectors, with hydrocarbon processing facing mandatory functional safety assessments while food processing navigates hygiene-rated component specifications.
- Manufacturing:Discrete assembly and process operations in UAE free zones deploy integrated safety PLCs to consolidate control architectures. Dubai's manufacturing clusters prioritize Ethernet-based safety networks to reduce installation labor. Basic mechanical guarding persists in cost-sensitive Egyptian and Nigerian facilities.
- Food Processing:Hygiene-rated safety components withstand caustic washdown cycles and IP69K pressure cleaning. Demand concentrates in Morocco's Tangier Med automotive supplier park where cleanroom assembly requirements cross-apply to food-grade safety standards. Stainless steel housings and sealed cable glands dominate specification sheets.
- Automotive:Renault-Nissan's Tangier operations and emerging EV battery suppliers.
- Aerospace:MRO facilities and component manufacturing in UAE and Saudi Arabia.
Manufacturing captures the largest procurement volume, though Food Processing is gaining share fastest on hygiene-rated safety component demand.
Technology:
Integration depth determines technology selection, with Gulf petrochemical operators consolidating on unified platforms while North African manufacturers retain discrete architectures.
- PLC-Based:Integrated safety and standard control on single hardware platforms reduces panel space and wiring complexity. Saudi Aramco downstream facilities in Ruwais specify these architectures for rotating equipment protection. SIL 3 capability certificates are now standard procurement documentation.
- Safety Networks:EtherCAT, PROFIsafe, and CIP Safety protocols transmit safety data over standard Ethernet cabling. Greenfield Gulf facilities adopt single-cable architectures to compress installation timelines. TÜV-certified protocol stacks enable response times below 20 milliseconds.
- Safety Software:Configuration and diagnostic tools for functional safety validation.
- Drive Technology:Integrated safe motion modules with embedded safe torque off.
PLC-Based architectures lead current deployment, with Safety Networks expanding most quickly on greenfield project specifications.
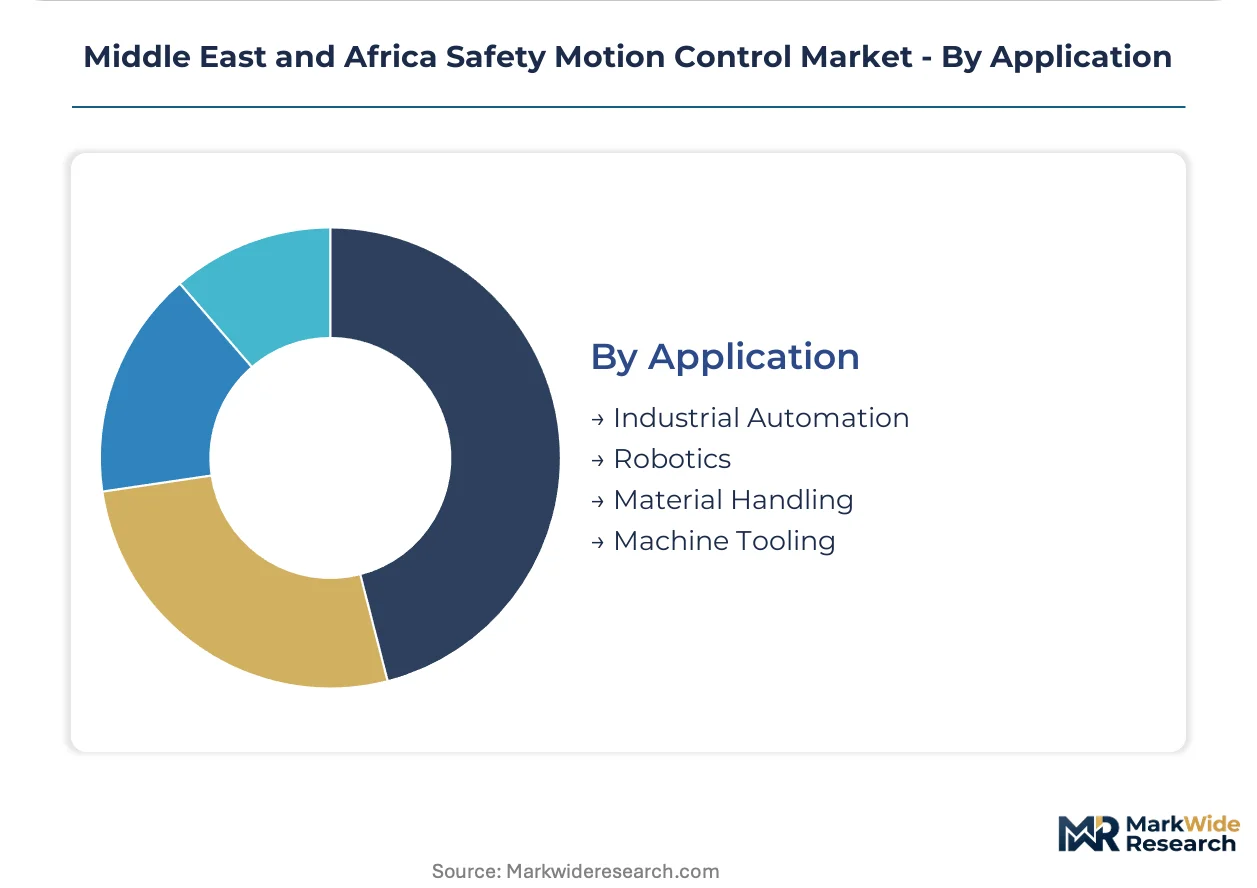
Application:
Risk exposure severity shapes application-level demand, with high-inertia rotating equipment commanding premium safety architectures.
- Industrial Automation:Process plant and assembly line guarding across Jubail Industrial City and Ruwais. SFDA mandates functional safety assessments for rotating equipment in hazardous zones. Predictive diagnostic capabilities are now standard requirements for tier-one oil and gas operators.
- Robotics:Collaborative and traditional industrial robot cell guarding with speed and separation monitoring. UAE manufacturing free zones deploy light curtain and laser scanner configurations for flexible production layouts. Force-limiting collaborative applications drive demand for PLd-rated safety systems.
- Material Handling:Conveyor, crane, and automated guided vehicle protection systems.
- Machine Tooling:Metal cutting and forming equipment with high-speed rotating spindles.
Industrial Automation dominates application-level revenue, with Robotics showing the steepest expansion trajectory on collaborative system deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands the highest safety motion control procurement volumes across the Middle East and Africa, while South Africa drives the most intensive retrofit activity through occupational health enforcement. The regional landscape fragments across Gulf petrochemical investment cycles and African mining safety mandates.
Saudi Arabia
Jubail Industrial City and Ruwais anchor demand for SIL 3-certified systems protecting rotating equipment in downstream hydrocarbon facilities. The Saudi Food and Drug Authority mandates functional safety assessments for machinery in hazardous zones, compelling facility-wide upgrades. Tier-one operators in the Eastern Province now require predictive diagnostic capabilities as standard procurement documentation.
United Arab Emirates
Dubai's Jebel Ali Free Zone and Abu Dhabi's downstream corridor concentrate manufacturing and petrochemical automation investment. The Emirates Authority for Standardization and Metrology operates streamlined conformity assessment pathways that accelerate safety system imports. Greenfield facilities in Khalifa Industrial Zone adopt single-cable Ethernet safety architectures to compress installation timelines.
South Africa
Rustenburg and Limpopo mining clusters generate urgent retrofit demand following unannounced Department of Employment and Labour inspections. The country's occupational health litigation surge has fragmented procurement patterns, with end-users engaging specialized integrators for functional safety validation independent of OEM supply. Platinum belt operators unbundle safety system specification from capital equipment packages.
Morocco
Renault-Nissan's Tangier Med automotive complex and emerging EV battery suppliers create demand for hygiene-rated safety components. The country's national standards body is developing machinery safety frameworks aligned with EU directive principles. Cleanroom assembly environments in the northern industrial zone specify stainless steel safety housings and IP69K-rated cable glands.
Egypt
Cost-sensitive manufacturing facilities in Cairo and Alexandria industrial zones retain basic mechanical guarding as the default protection method. The country's national standards body lacks enforcement capacity for safety integrity requirements, delaying electronic safety system adoption. Importers face documentation burdens without streamlined conformity assessment pathways comparable to Gulf free zones.
Middle East and Africa Safety Motion Control Market Competitive Landscape
Top-tier vendors anchor large petrochemical and hydrocarbon processing contracts, while mid-tier specialists occupy discrete safety component niches. European automation conglomerates leverage existing CE certification infrastructure to accelerate Saudi and UAE regulatory clearance. Two strategic archetypes dominate: integrated platform providers consolidating control and safety on unified architectures, and optoelectronic specialists delivering hazardous zone-rated protective devices. Competitive moves center on functional safety engineering talent acquisition and localized certification support partnerships.
Within the integrated automation tier, ABB and Siemens exemplify contrasting approaches to Gulf market penetration. ABB leverages its process automation heritage to anchor downstream petrochemical contracts, while Siemens competes through TIA Portal-integrated safety portfolios. SICK Group occupies a distinct position among optoelectronic protective device specialists, with hazardous zone applications representing its core market anchor.
| Leading Market Players |
|---|
| Rockwell Automation |
| ABB |
| Schneider Electric |
| Mitsubishi Electric |
| General Electric |
| Siemens |
| SICK Group |
| Bosch Rexroth |
| Yaskawa |
| Others |
Supply & Pricing Matrix
Captive certification infrastructure in European manufacturing bases anchors both supply security and pricing power for SIL-rated safety components. Buyers across Saudi Arabia's Jubail Industrial City and South Africa's platinum belt face extended lead times and currency exposure because TÜV-validated production clusters in Germany and Switzerland concentrate certified component output.
Pricing Analysis
Capacity additions in German automation manufacturing are reshaping price floors for SIL 3-certified control modules across the Middle East and Africa. Three-tier pricing structure across SIL 3 premium, SIL 2 standard, and basic interlock economy levels stratifies procurement budgets, with certification grade and predictive diagnostic capability driving differentiation. Cost compression in the economy tier is intensifying because Egyptian and Nigerian manufacturers substitute mechanical guarding for electronic systems. Tier-one oil and gas operators in Ruwais show minimal price sensitivity, while North African discrete manufacturers prioritize upfront capital minimization.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions is elevating landed costs for safety PLC modules and certified sensors destined for Gulf petrochemical facilities. Critical production draws from Germany, Switzerland, and Japan for TÜV-certified safety stacks and explosion-protected sensor housings. Neodymium magnet and copper winding dependencies expose encoder and servo motor supply to commodity price swings. Single-source vulnerability concentrates in European third-party assessment bodies creating certification bottlenecks. Distribution runs through Dubai's Jebel Ali Free Zone for streamlined ESMA clearance into UAE and Saudi markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Safety motion control margins across the Middle East and Africa are expanding through predictive diagnostic premium-tier adoption in Gulf hydrocarbon processing. Cost-down pressure from integrated safety-over-Ethernet architectures is compressing installation labor and panel space requirements.
For Market Incumbents: Extend functional safety engineering certification support partnerships into Saudi Arabia and South Africa to counter talent scarcity. Anchor large petrochemical contracts through localized SIL validation capabilities. Deepen backward integration into safety software stacks to differentiate against commodity relay competitors. Defend against Asian manufacturers with streamlined ESMA conformity assessment pathways by leveraging existing CE infrastructure. For New Entrants and Emerging Players: Mid-tier Moroccan automotive suppliers represent an underserved buyer archetype with hygiene-rated safety component demand from Renault-Nissan's Tangier Med ecosystem. Target Egypt's cost-sensitive manufacturing facilities with mechanical-to-electronic safety retrofit bundles priced below full SIL architectures. Pursue South African mining integrator partnerships for unbundled functional safety validation services independent of OEM supply chains. For Investors and Strategic Acquirers: Roll-up economics work for specialized functional safety integrators because occupational health litigation in South Africa's platinum belt fragments procurement patterns and creates acquisition targets with sticky validation relationships. The 5-to-10-year viability window favors platforms consolidating SIL engineering talent and localized certification support. Monitor ESMA and SFDA regulatory enforcement intensity as the primary inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SIL 3 Certification Investment | TÜV Rheinland validation accelerates Saudi SFDA machinery safety clearance for Jubail petrochemical operators. |
| Safety-over-EtherCAT Integration | Single-cable architectures reduce installation labor in Khalifa Industrial Zone greenfield deployments. |
| Functional Safety Talent Acquisition | Certified TÜV engineers enable independent validation services for South African mining retrofit demand. |
| Hygiene-Rated Component Development | IP69K-rated stainless steel housings capture Morocco Tangier Med automotive cleanroom specifications. |
| Free Zone Distribution Partnership | Jebel Ali streamlined ESMA pathways compress import lead times for UAE manufacturing clusters. |
Research Methodology
Multiple input streams — plant engineer interviews across Jubail and Ruwais, procurement director discussions in South African mining clusters, and regulatory affairs engagement with ESMA and SFDA officials — were reconciled against trade flow data and machinery safety certification databases. Secondary validation drew from IEC 61508 implementation guidelines, notified body assessment records, and industrial automation customs records. Bottom-up facility-level demand estimates and top-down petrochemical capital expenditure patterns were triangulated to anchor volume projections.
Data-stream reconciliation across product type, end-use sector, technology architecture, and application risk severity enabled segmentation-level modeling throughout the forecast period. CAGRs were derived from regression analysis against hydrocarbon processing investment cycles and mining safety enforcement intensity. Safety-over-Ethernet adoption curves and SIL 3 certification penetration rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; PLC-based architectures and safety sensors carry tighter precision than emerging safety software categories. Forecasts reflect assumptions about Saudi and UAE regulatory enforcement continuity and South African occupational health litigation trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Barricade Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market