
 Global Barrier Systems Market | 2026-2036
Global Barrier Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Barrier Systems Market Foresight
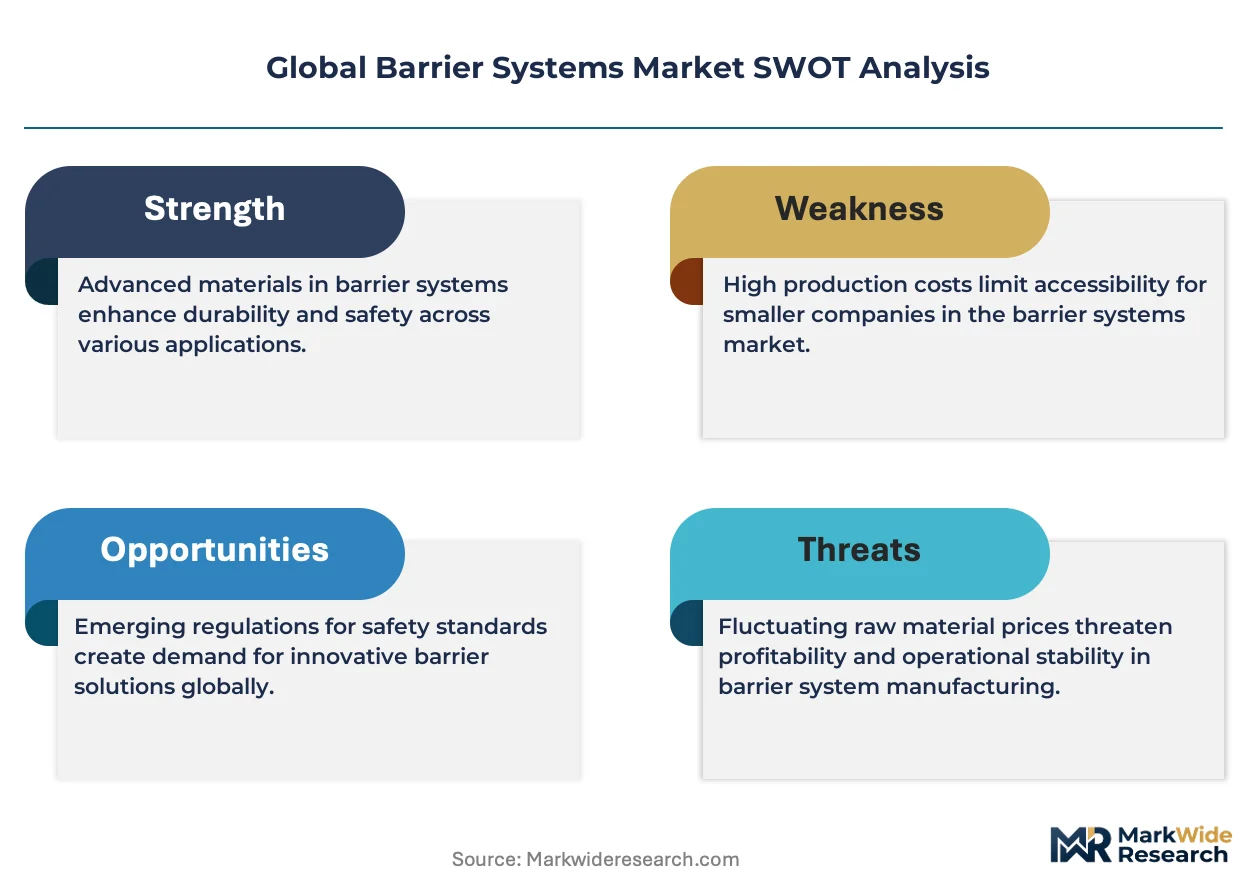
Composite polymer reinforcement is consolidating share from traditional steel in crash-rated barrier fabrication, cutting weight and extending service intervals. Hill & Smith Holdings PLC leverages its European manufacturing footprint to dominate highway safety barrier tenders. Tata Steel anchors its position through captive steel supply and backward integration into galvanizing operations. Bekaert differentiates via high-tensile wire expertise that transfers into anti-ram perimeter systems.
Barrier systems are engineered assemblies combining structural members, actuation mechanisms, and control interfaces designed to restrict, direct, or halt vehicle and pedestrian movement; crash-rated variants must certify to kinetic energy absorption thresholds measured in kJ impact loads. Their primary purpose spans perimeter hardening, traffic channelization, and credential-based access enforcement across critical infrastructure and commercial facilities. Boom barriers lead parking facility deployments due to low cycle-cost and rapid throughput, while speed gates capture margin pools in airport security zones where biometric integration commands premium positioning. Electro-mechanical technology is displacing hydraulic actuation in temperate climates, though pneumatic systems retain share in heavy-duty port and logistics applications.
Federal Highway Administration (FHWA) eligibility standards and European CE marking under the Construction Products Regulation shape product certification pathways and market access for crash-tested systems. The EU AI Act and emerging cybersecurity frameworks are beginning to constrain software-enabled access control barriers with networked authentication protocols. Stakeholders must weigh material substitution timelines against recertification costs when reconfiguring product portfolios.
Market Dynamics
Composite polymer reinforcement is unifying crash-rated barrier fabrication across highway and perimeter security applications, compressing traditional steel supply chains while extending service intervals and reducing transport costs for remote infrastructure deployments.
Growth Catalysts
- EU Green Deal mandates:Solar-powered barrier technologies with lower carbon footprints are gaining specification preference in European public procurement tenders for perimeter security and traffic management systems.
- India's urban infrastructure acceleration:Access control deployments at commercial complexes and transit hubs are expanding as municipal spending concentrates on smart city corridors and metro rail extensions.
- Biometric integration:Speed gates at airport security zones are capturing premium positioning through facial recognition and credential fusion, driving replacement cycles at aging terminals.
Market Restraints
- Steel price volatility:Galvanized steel coil fluctuations compress margin visibility for crash-rated barrier manufacturers dependent on commodity feedstock.
- Recertification cost burden:Federal Highway Administration eligibility standards and European CE marking under the Construction Products Regulation impose substantial retesting expenses when material formulations change.
- Hydraulic system obsolescence risk:Electro-mechanical actuation is displacing hydraulic systems in temperate climates, stranding service infrastructure and technical expertise investments.
Strategic Opportunities
- Asia-Pacific airport perimeter expansion:Passenger volume climbs across Indonesia, Vietnam, and the Philippines are triggering greenfield security installations with integrated barrier-command systems.
- EU AI Act compliance services:Software-enabled access control barriers with networked authentication protocols require cybersecurity framework adaptation, creating advisory and retrofit revenue streams.
- Pneumatic system specialization:Heavy-duty port and logistics applications in salt-air environments retain demand for corrosion-resistant pneumatic actuation, defensible against electromechanical substitution.
Industry Challenges
- Kinetic energy certification timelines:Crash-tested systems measured in kJ impact loads require extended validation protocols that delay product launches and freeze engineering resources.
- Legacy control interface integration:New barrier deployments must communicate with existing building management and security command systems, multiplying commissioning complexity and field service demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Barrier Systems Market |
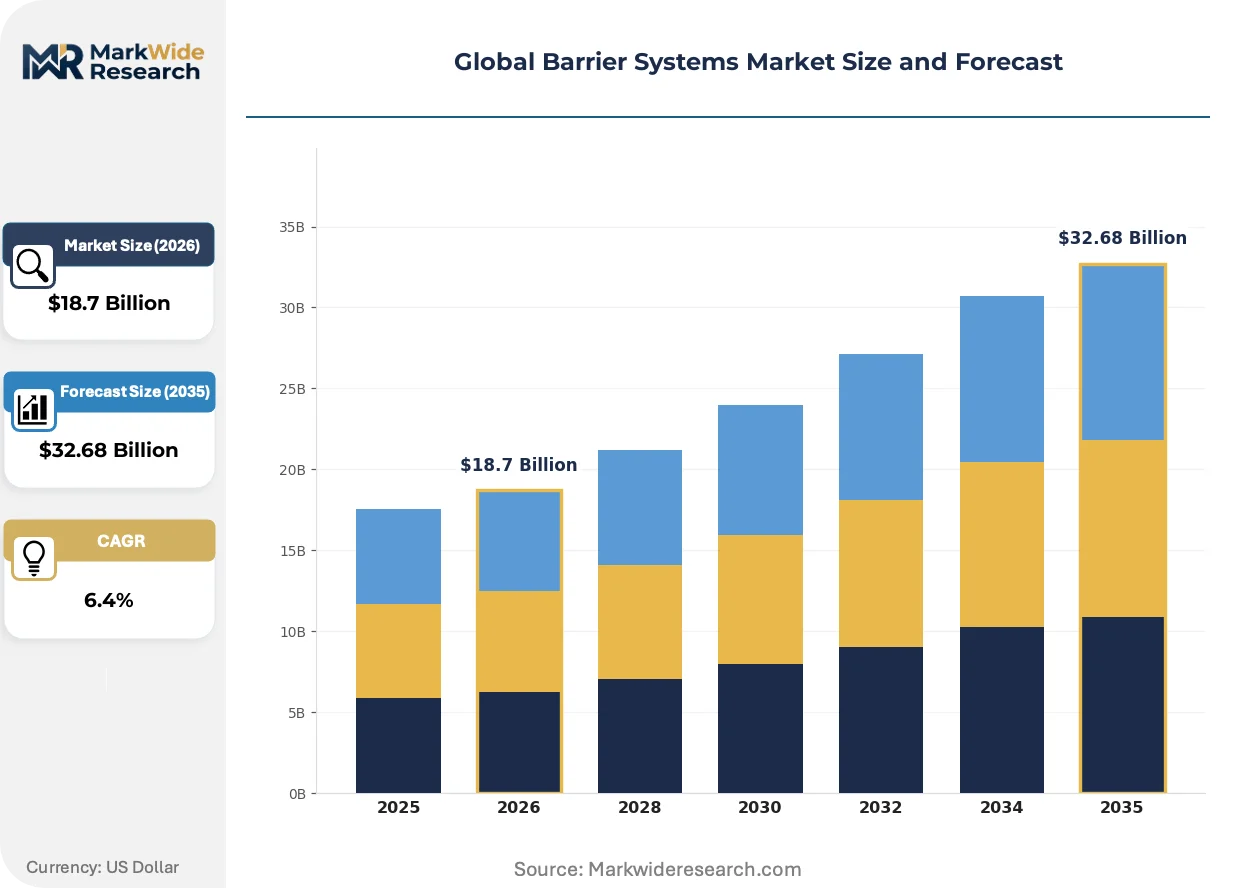
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Barriers, Boom Barriers, Speed Gates, Turnstiles, Swing Gates Technology: Hydraulic, Electro-Mechanical, Pneumatic, Magnetic, Solar-Powered Application: Parking Facilities, Perimeter Security, Access Control, Traffic Management, Event Venues End User: Commercial Complexes, Airports, Malls, Stadiums, Educational Institutions |
| Companies Covered | Hill & Smith Holdings PLC, Betafence Limited, Tata Steel, A-Safe, Delta Scientific Corporation, Trinity Industries, Valmont Industries Inc., Bekaert, Lindsay Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Barrier Systems Market Shifts & Advancements
Barrier system architectures are converging around modular, software-defined platforms that separate mechanical actuation from control intelligence, enabling remote diagnostics and predictive maintenance across distributed infrastructure estates.
Edge computing modules embedded at barrier control points are unifying local decision logic with centralized security policy enforcement. Airport operators in Germany and the Netherlands are piloting these architectures for biometric-credential verification at speed gates. This convergence is compressing the traditional separation between physical access control and IT security domains, forcing vendor consolidation around dual-competency engineering teams.
The EU AI Act and emerging cybersecurity frameworks are constraining software-enabled access control barriers with networked authentication protocols. Manufacturers must now document algorithmic transparency and data governance for facial recognition and behavioral analytics components. European perimeter security tenders are increasingly specifying AI Act compliance as a mandatory qualification criterion, favoring suppliers with established regulatory affairs capabilities.
Lifecycle service contracting is displacing transactional equipment sales in commercial and critical infrastructure segments. Facility managers at data centers and logistics hubs in Singapore and the United Arab Emirates are bundling barrier hardware with predictive maintenance and guaranteed uptime commitments. This shift compresses upfront capital recognition for manufacturers while extending customer lock-in and recurring revenue visibility.
Global Barrier Systems Market Segmentation
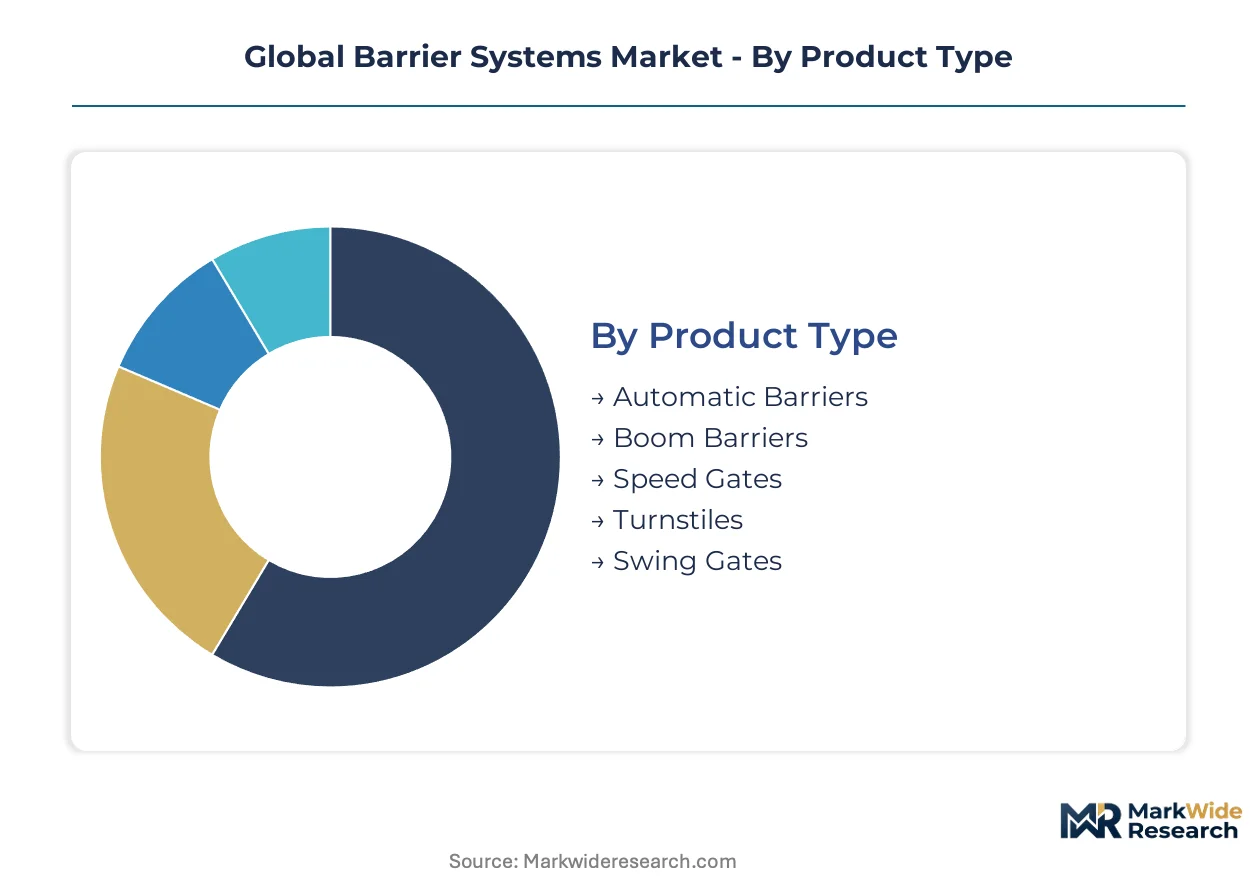
Barrier system procurement patterns diverge sharply across deployment contexts. Specification requirements for kinetic energy absorption, cycle frequency, and environmental resilience create distinct technology-product pairings that reshape competitive positioning in each vertical.
Product Type:
Technology leadership and certification thresholds separate premium crash-rated assemblies from high-volume access control hardware.
- Boom Barriers:Horizontal arm assemblies with electromechanical or hydraulic actuation dominate parking facility throughput optimization. Demand concentrates in India's commercial complex expansion and Southeast Asian transit hub retrofits where low cycle-cost and rapid vehicle processing outweigh security hardening requirements.
- Speed Gates:Biometric-integrated pedestrian channels with optical sensors and credential fusion modules capture premium positioning at airport security zones. Germany and Netherlands operators pilot edge-computing architectures for facial recognition verification, compressing physical access and IT security domains.
- Automatic Barriers:Programmable vehicle access assemblies with RFID and license plate recognition integration serve commercial and institutional perimeters.
- Turnstiles:Tripod, full-height, and optical variants channel pedestrian flow at stadiums and metro stations with fare collection integration.
- Swing Gates:Hinged panel systems for aesthetic perimeter applications at corporate campuses and residential estates.
Mature deployment sits with boom barriers. Newer deployment is concentrated in speed gates.
Technology:
Actuation mechanism selection hinges on duty cycle intensity, ambient corrosion exposure, and energy infrastructure reliability at installation sites.
- Electro-Mechanical:Motor-driven gear systems with programmable logic controllers displace hydraulic alternatives in temperate climates. Deployment accelerates across European parking facilities and commercial perimeters where reduced maintenance intervals and precise position control justify higher capital outlay.
- Pneumatic:Compressed-air actuation with corrosion-resistant cylinder assemblies retains defensible share in heavy-duty port applications. Salt-air environments at Singapore and UAE logistics hubs specify pneumatic systems for reliability where electromechanical sealing degrades.
- Hydraulic:Fluid-power systems with high force density serve legacy heavy-cycle installations though obsolescence risk strands technical infrastructure.
- Magnetic:Linear motor and magnetic levitation variants enable silent, frictionless operation at premium institutional settings.
- Solar-Powered:Photovoltaic-integrated barriers with battery backup address EU Green Deal procurement mandates and remote infrastructure without grid connectivity.
Electro-mechanical systems are gaining share fastest. Hydraulic installations face replacement pressure.
Application:
Security threat modeling and traffic engineering specifications determine barrier performance tier and integration complexity.
- Perimeter Security:Anti-ram and crash-rated assemblies certifying to kJ impact thresholds protect critical infrastructure. Asia-Pacific airport operators across Indonesia, Vietnam, and Philippines trigger greenfield installations with integrated command systems as passenger volumes climb.
- Parking Facilities:Revenue control and access optimization systems with high cycle frequency dominate commercial deployment scale.
- Access Control:Credential-verified entry points at data centers and logistics hubs shift toward lifecycle service contracting with uptime guarantees.
- Traffic Management:Highway safety barriers and lane control systems governed by FHWA eligibility standards and European CE marking requirements.
- Event Venues:Temporary and permanent crowd channelization with rapid deployment specifications for stadiums and exhibition centers.
Parking facilities represent the largest installed base. Perimeter security commands the steepest expansion trajectory.
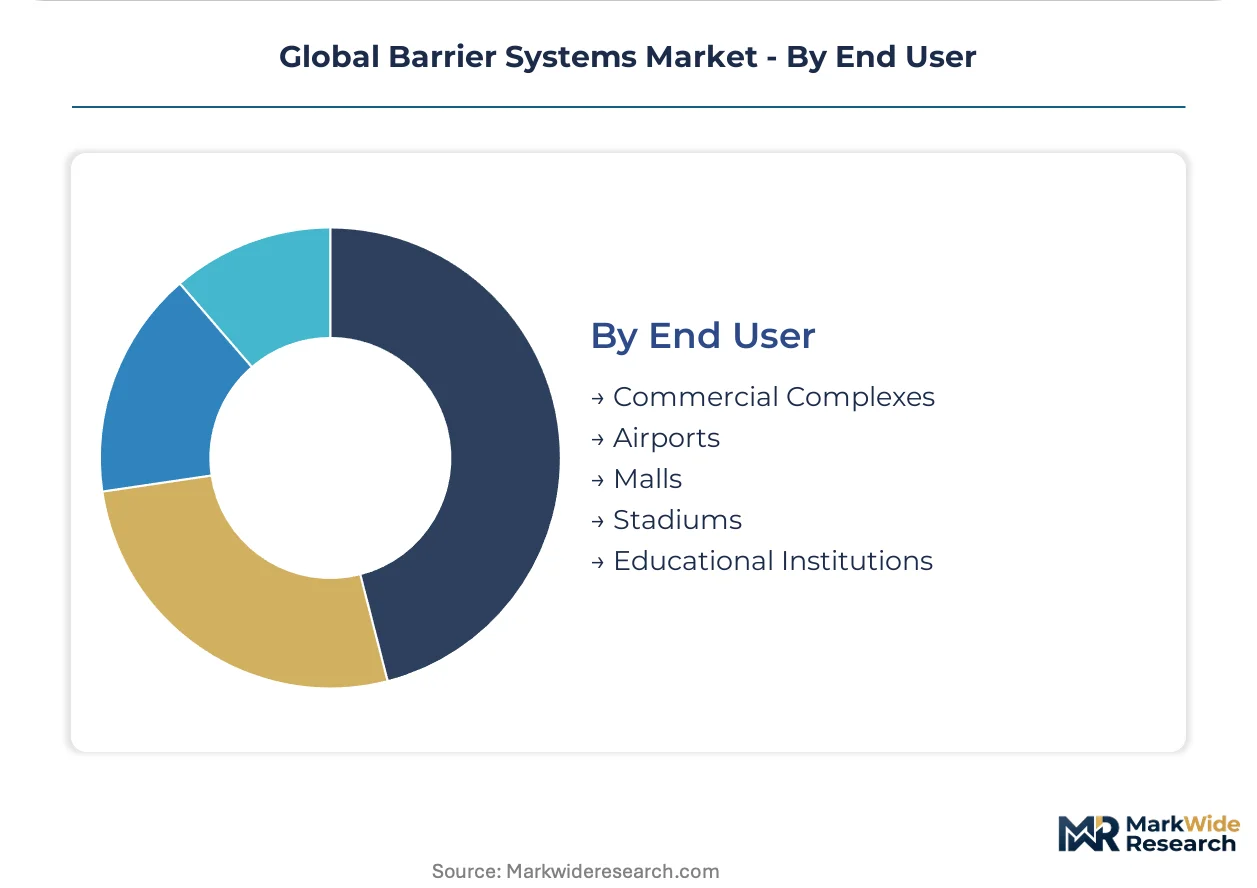
End User:
Facility type dictates security tier, aesthetic requirements, and procurement authority structure for barrier specification.
- Airports:Multi-layer security architectures with biometric speed gates and vehicle crash barriers face EU AI Act compliance constraints for algorithmic transparency. German and Dutch operators specify AI Act adherence as mandatory qualification criterion.
- Commercial Complexes:Mixed-use developments in India's smart city corridors bundle parking revenue control with pedestrian access management.
- Malls:High-throughput parking optimization with loyalty program integration drives boom barrier and turnstile deployment.
- Stadiums:Crowd safety regulations and anti-terrorism specifications shape turnstile and perimeter barrier selection.
- Educational Institutions:Campus-wide access control with emergency lockdown capabilities influences swing gate and speed gate procurement.
Commercial complexes anchor volume demand. Airports concentrate technology premium and regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in India, where urban infrastructure spending accelerates access control deployments at commercial complexes and transit hubs. Passenger volume climbs across Asia-Pacific airports trigger perimeter security installations. European procurement tilts toward solar-powered barriers under EU Green Deal mandates.
United States
Airport perimeter hardening and critical infrastructure protection drive specification demand for crash-rated assemblies. Federal Highway Administration eligibility standards govern highway safety barrier certification pathways. Dallas-Fort Worth and Atlanta airport authorities expand integrated barrier-command systems for multi-layer security architectures.
Germany
EU AI Act compliance constraints reshape software-enabled access control procurement at aviation facilities. CE marking under the Construction Products Regulation imposes retesting expenses for material formulation changes. Frankfurt and Amsterdam-Schiphol operators pilot edge-computing architectures for biometric verification at speed gates.
India
Smart city corridors and metro rail extensions concentrate municipal spending on parking revenue control and pedestrian access management. Bureau of Indian Standards certification requirements shape product qualification for domestic tenders. Mumbai and Delhi-NCR commercial complexes bundle boom barrier installations with transit hub retrofits.
Singapore
Data center and logistics hub operators shift toward lifecycle service contracting with uptime guarantees for access control systems. Salt-air environments specify pneumatic actuation for corrosion resistance against electromechanical sealing degradation. Jurong Port and Changi Airport logistics zones retain heavy-duty pneumatic barrier deployments.
United Arab Emirates
Remote infrastructure without grid connectivity drives photovoltaic-integrated barrier specifications with battery backup. Ministry of Health and Prevention facility standards influence perimeter security procurement at healthcare and research campuses. Dubai South and Abu Dhabi industrial zones deploy solar-powered barriers for desert logistics corridors.
Global Barrier Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with crash-rated system vendors commanding premium positioning against high-volume parking hardware suppliers. Market structure tilts toward consolidation at the top tier where certification barriers and recertification costs limit new entry, while mid-tier access control remains fragmented across regional fabricators. Strategic archetypes include steel-integrated conglomerates with captive metallurgical supply, polymer-composite specialists exploiting material substitution timelines, and electromechanical technology vendors displacing hydraulic legacy systems. Dominant competitive moves encompass backward integration into galvanizing operations and geographic expansion through European manufacturing footprints.
Within the steel-integrated tier, Hill & Smith Holdings PLC and Tata Steel occupy positions anchored by metallurgical supply chain control, while Bekaert exemplifies the high-tensile wire specialization archetype that transfers into anti-ram perimeter applications. These three entities represent distinct competitive vectors: European manufacturing scale, emerging market vertical integration, and advanced materials engineering respectively.
| Leading Market Players |
|---|
| Hill & Smith Holdings PLC |
| Betafence Limited |
| Tata Steel |
| A-Safe |
| Delta Scientific Corporation |
| Trinity Industries |
| Valmont Industries Inc. |
| Bekaert |
| Lindsay Corporation |
| Others |
Supply & Pricing Matrix
Galvanized steel coil price indices cascade through barrier systems supply chains, compressing margins for crash-rated manufacturers while amplifying pricing power for polymer-composite specialists with decoupled feedstock exposure. Steel-integrated conglomerates leverage captive metallurgical supply to stabilize tiered positioning against commodity-vulnerable fabricators.
Pricing Analysis
Volume concentrates in boom barriers and parking access hardware where per-unit transactional pricing dominates, while margin pools sit with biometric-integrated speed gates commanding project-based premiums. Price differentiation hinges on CE marking tier under the Construction Products Regulation and FHWA eligibility certification grade, with solar-powered variants capturing Green Deal procurement preference. Pricing pressure stems from steel price volatility eroding visibility for galvanized-dependent producers. Municipal buyers in India's smart city corridors exhibit highest price sensitivity; airport operators in Germany and the Netherlands show lowest sensitivity due to AI Act compliance mandates.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States anchor hub-and-spoke patterns for crash-rated and access control hardware. Manufacturing draws from galvanized steel coil, high-tensile wire, and polymer composite feedstocks. Single-source vulnerability concentrates in European CE marking testing facilities for kinetic energy certification. Distribution runs through specialized security integrators and direct OEM channels to airport authorities, commercial developers, and municipal procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over galvanizing operations and polymer formulation capabilities determines margin defensibility against steel price volatility.
For Market Incumbents: Deepen backward integration into captive steel supply and galvanizing operations to buffer commodity exposure. Lock in FHWA and CE marking certification portfolios before polymer substitution triggers recertification cost burdens. Secure long-term service contracts with Singapore and UAE data center operators to extend recurring revenue visibility against transactional hardware compression. For New Entrants and Emerging Players: Begin with pneumatic actuation specialization for salt-air port environments in Singapore and UAE logistics hubs where electromechanical sealing degrades. Target India's municipal parking and transit hub retrofits as the most penetrable volume segment. Pursue lifecycle service contracting as the primary go-to-market angle to bypass incumbent equipment relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor polymer-composite specialists with established CE marking pathways in Germany and the Netherlands during steel price spike windows. Long-term viability centers on regulatory affairs capabilities for EU AI Act compliance as algorithmic transparency mandates expand. Watch EU Green Deal procurement specification shifts as the inflection signal for solar-powered barrier technology premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing | Captive metallurgical supply insulates margin stability against steel coil volatility. |
| CE Marking Pre-Certification Investment | Early kinetic energy testing lock-in delays competitor polymer substitution timelines. |
| Lifecycle Service Contracting | Predictive maintenance bundling extends customer lock-in at Singapore data centers. |
| EU AI Act Compliance Documentation | Algorithmic transparency capabilities qualify vendors for Frankfurt airport tenders. |
| Pneumatic System Specialization | Corrosion-resistant actuation defends share in UAE salt-air logistics corridors. |
Research Methodology
Trade databases, customs filings, and construction procurement registries formed the secondary backbone for barrier systems volume estimation. Primary interviews with airport security directors, municipal procurement officers, commercial facility managers, and barrier OEM engineering heads validated specification trends and pricing dynamics. Bottom-up unit deployment modeling triangulated against top-down infrastructure spending allocation across the analysis window.
Historical trendline analysis of highway safety and perimeter security installations established baseline penetration patterns. The forecast framework segmented by product type, actuation technology, application context, and end-user facility class. CAGRs derived from infrastructure spending trajectories, regulatory mandate timelines, and material substitution elasticity. Industry-specific inputs incorporated EU Green Deal procurement specification shifts and India's smart city corridor acceleration.
Underlying measurement precision varies by segment; parking facility boom barriers carry tighter precision than emerging biometric speed gate deployments. Forecasts reflect documented assumptions regarding steel price stabilization and recertification protocol timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Locks Market
Access Control Systems
Car Security System Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Wireless Security System Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
France Access Control Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
US Access Control Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Global Industrial Safety Gates Market