
 Europe Home Security System Market | 2026-2036
Europe Home Security System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Security System Market Foresight
The EU AI Act is consolidating the cost-of-entry calculus for biometric-enabled security hardware across member states. Honeywell International leverages its building automation heritage to anchor integrated fire and intrusion portfolios in commercial verticals. Siemens competes through industrial-grade IoT architectures that extend from energy management into access control ecosystems. Verisure sustains its direct-to-consumer installation density across Northern European markets through proprietary monitoring infrastructure.
Europe home security systems encompass electromechanical and digital apparatus designed to detect unauthorized entry, environmental hazards, or system tampering through sensor arrays, control panels, and communication interfaces typically operating on 868 MHz or 2.4 GHz wireless protocols with battery backup redundancy. These installations serve residential and commercial premises by triggering alerts, activating deterrent measures, and enabling remote verification through cloud-connected platforms. Video surveillance and IoT-based technology segments command premium positioning as AI-enabled analytics shift margin pools from hardware sales toward recurring software services. Wireless intrusion alarm systems dominate unit volumes in residential retrofit applications across aging European housing stock, while hybrid architectures capture upgrade cycles in commercial facilities seeking legacy system preservation.
CE marking under the EU Radio Equipment Directive and GDPR biometric data governance jointly determine product certification pathways and data handling architectures for facial recognition deployments. The ECHA REACH framework restricts flame-retardant chemistries in plastic enclosures, forcing material substitutions that reshape component sourcing for enclosure manufacturers. Stakeholders must monitor harmonized standards evolution under the EU Cybersecurity Act as connected device mandates harden firmware update obligations and vulnerability disclosure timelines.
Market Dynamics
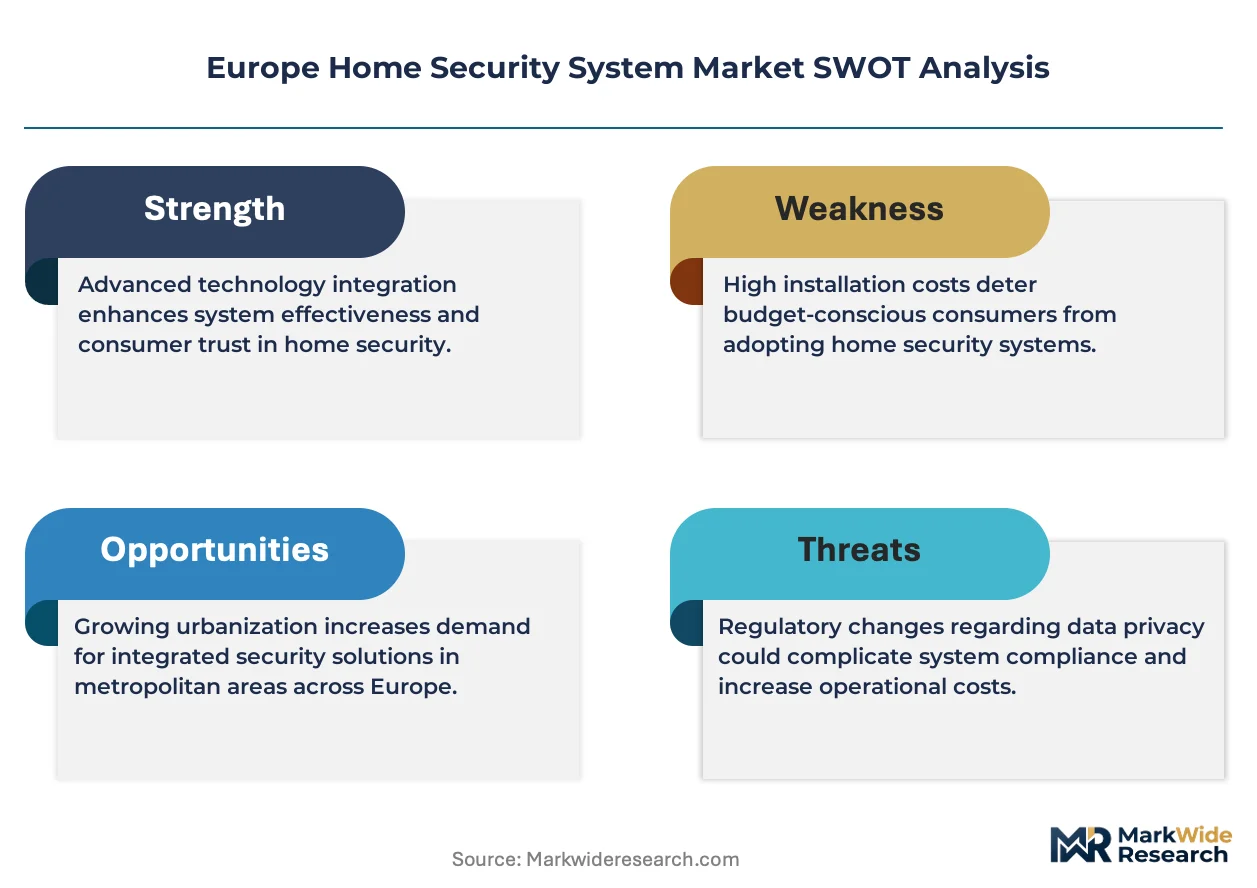
The EU AI Act's biometric surveillance provisions are forcing wholesale firmware architecture redesigns across installed security hardware bases, compressing upgrade cycles and fragmenting compliance pathways between member states.
Growth Catalysts
- CE marking under EU Radio Equipment Directive:Harmonized certification for 868 MHz and 2.4 GHz wireless protocols accelerates cross-border product deployment and reduces manufacturer retesting burdens.
- Urban renewal programs in Germany, France, and the United Kingdom:Mandated connected safety infrastructure in subsidized housing retrofits generates concentrated demand for wireless intrusion alarm systems.
- AI-enabled video analytics:Cloud-connected platforms shift revenue from one-time hardware sales toward recurring software services, expanding lifetime customer value.
Market Restraints
- GDPR biometric data governance:Facial recognition deployments require costly data handling architecture redesigns and explicit consent frameworks that lengthen sales cycles.
- ECHA REACH flame-retardant restrictions:Banned chemistries in plastic enclosures force material substitutions and supplier requalification for enclosure manufacturers.
- Legacy system preservation requirements:Commercial facilities demand hybrid architectures that maintain compatibility with decades-old wired installations, constraining design freedom.
Strategic Opportunities
- Underpenetrated Southern European residential markets:Spain and Italy exhibit lower smart home security penetration rates than Northern Europe, creating whitespace for direct-to-consumer installation networks.
- EU Cybersecurity Act harmonized standards:Incoming firmware update mandates and vulnerability disclosure timelines favor vendors with established security operations centers.
- Convergence of energy management and access control:Industrial-grade IoT architectures from building automation extend into integrated security ecosystems, opening cross-selling channels.
Industry Challenges
- Cybersecurity certification timeline compression:The EU Cybersecurity Act's evolving standards require continuous firmware validation that strains quality assurance resources.
- Integration complexity with proprietary monitoring infrastructure:Closed-protocol systems from established operators create interoperability barriers for new market entrants.
- Supply chain reconfiguration for REACH-compliant materials:ECHA restrictions force rapid supplier transitions with limited qualified alternatives for flame-retardant compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Security System Market |
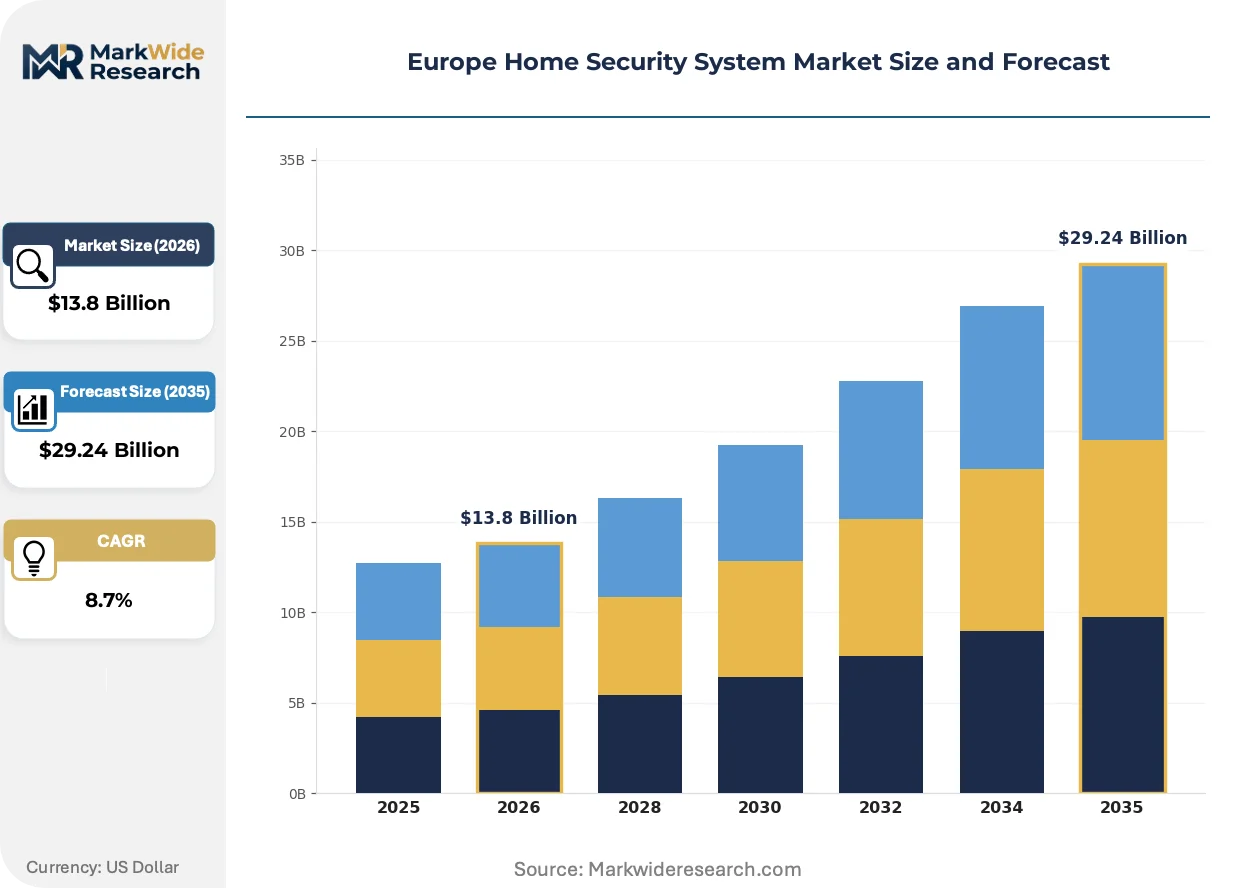
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $29.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrusion Alarm, Video Surveillance, Access Control, Fire Alarm Technology: Wired, Wireless, IoT-Based, Hybrid End User: Residential, Small Business, Large Enterprise, Government Installation Type: DIY, Professional, Integrated Systems, Managed Services |
| Companies Covered | Honeywell International, Siemens, Verisure, Sector Alarm, ASSA ABLOY, Prosegur, Schneider Electric, EPS Télésurveillance, Johnson Controls, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Security System Market Shifts & Advancements
Edge-based AI inference is redistributing computational load from cloud servers to local hardware, altering hardware cost structures and data sovereignty architectures across European deployments.
Wireless mesh networking protocols operating at sub-GHz frequencies are overtaking traditional star-topology Wi-Fi in residential retrofit applications. Installers across Germany and France favor these architectures for penetrating thick masonry walls in aging housing stock. Battery-powered sensor arrays with multi-year lifespans are compressing total cost of ownership calculations and displacing wired alternatives in heritage buildings where cable routing proves prohibitive.
The EU AI Act's risk-based classification system for biometric identification imposes conformity assessment obligations that hardware vendors previously avoided. High-risk system designations trigger third-party auditing requirements and technical documentation burdens. French and German regulators are interpreting implementation timelines most aggressively, forcing earlier compliance investments than peripheral member states.
Subscription-based monitoring contracts are displacing upfront equipment purchases in Northern European consumer segments. Verisure's proprietary infrastructure established this template, and competitors now unbundle hardware from service fees to match buyer preferences. The United Kingdom shows the fastest channel rotation, with direct-to-consumer brands capturing share from traditional security installers through app-first onboarding experiences.
Europe Home Security System Market Segmentation
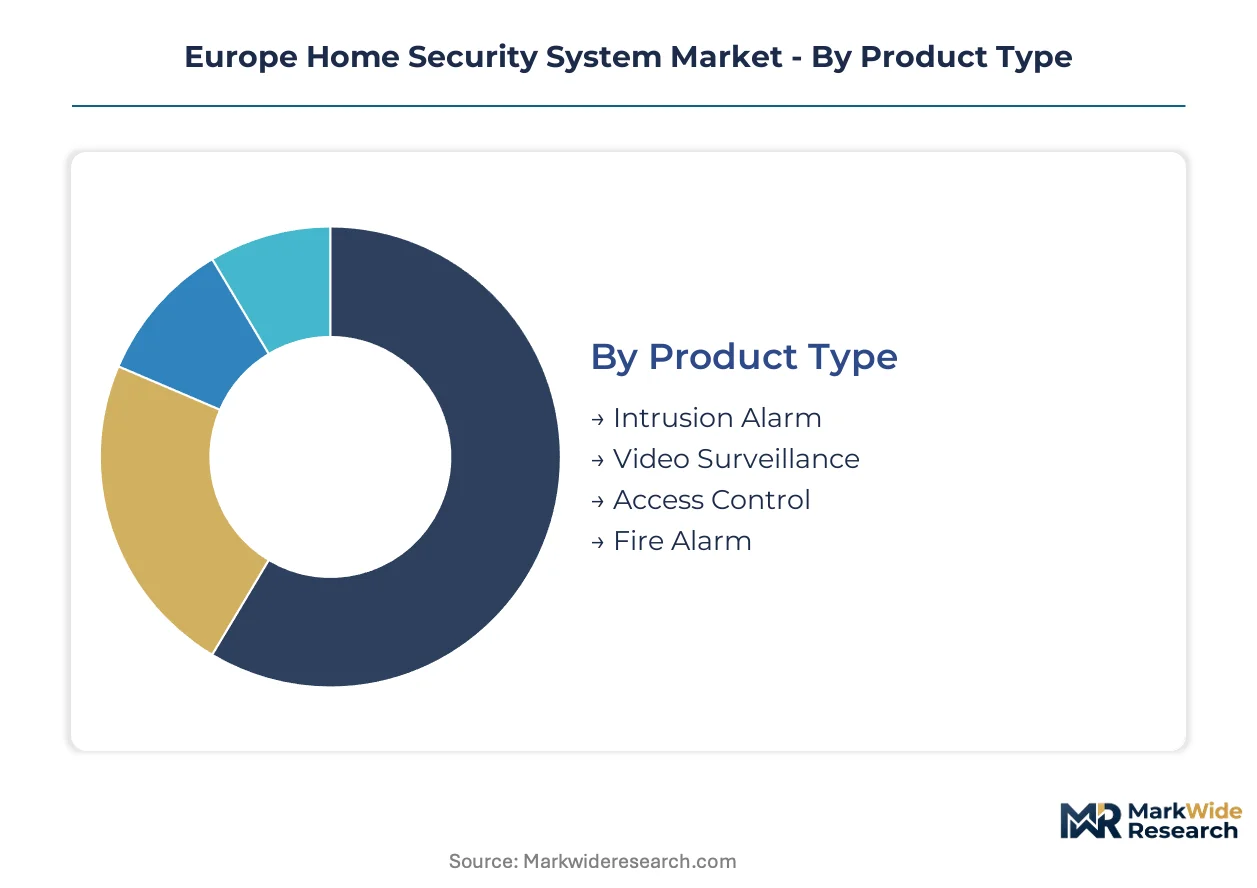
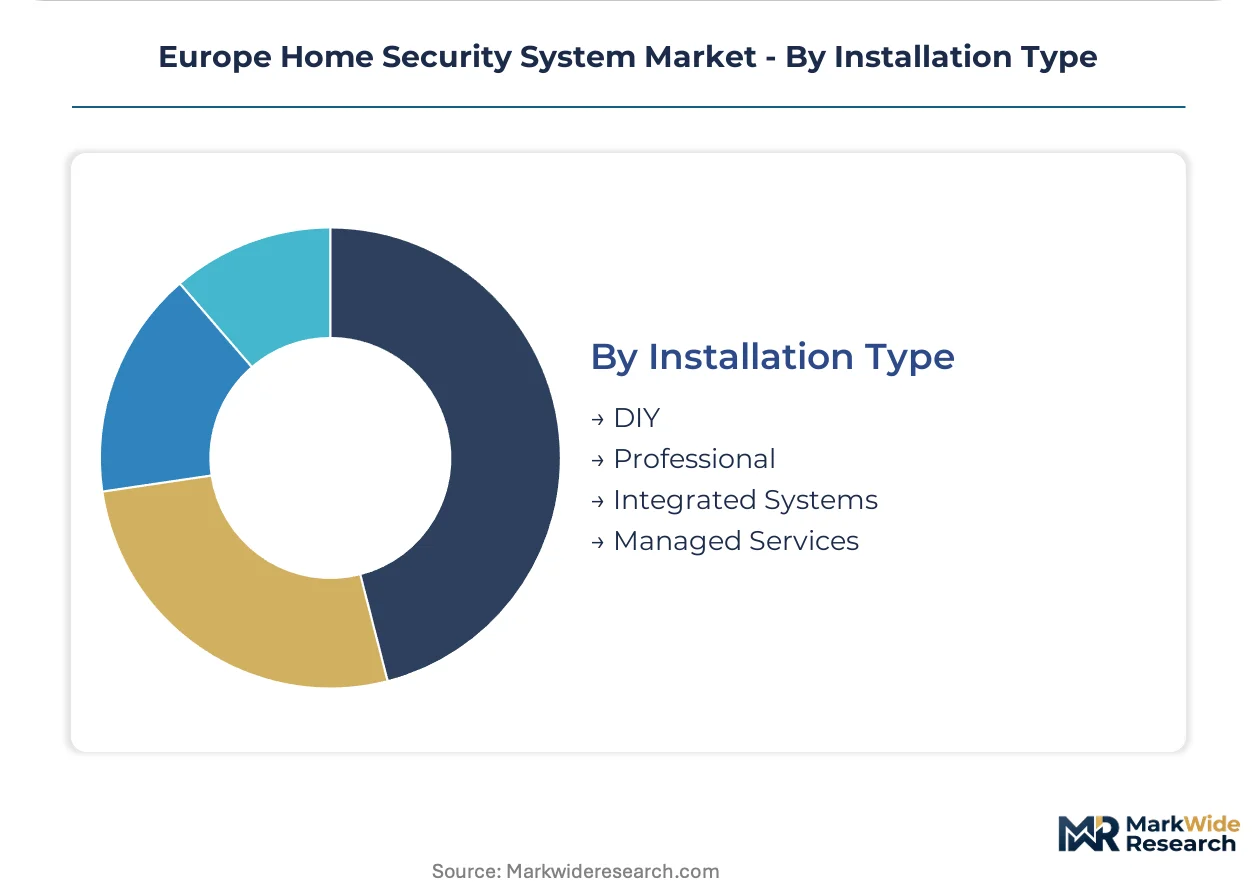
Segmentation in the Europe home security system market reveals how divergent buyer priorities—regulatory compliance, legacy infrastructure constraints, and service model preferences—fragment addressable demand across hardware, connectivity, and procurement dimensions.
Product Type:
Buyers differentiate primarily by whether they prioritize deterrence visibility, silent monitoring, or integrated life safety.
- Intrusion Alarm:Electromechanical sensor arrays detect unauthorized entry through door contacts, motion detectors, and glass-break sensors operating on 868 MHz wireless protocols. German and French urban renewal programs mandate these systems in subsidized housing retrofits, compressing procurement timelines for wireless variants. Battery-backed designs with multi-year lifespans displace wired alternatives in heritage buildings where cable routing faces preservation restrictions.
- Video Surveillance:IP camera networks with edge-based AI inference redistribute computational load from cloud servers to local hardware, altering data sovereignty architectures under GDPR. The United Kingdom shows fastest channel rotation toward subscription-based monitoring contracts, with direct-to-consumer brands capturing share from traditional installers through app-first onboarding. Cloud-connected platforms shift revenue from one-time hardware sales toward recurring software services.
- Access Control:Biometric and credential-based entry systems face EU AI Act conformity assessment obligations for facial recognition deployments. High-risk system designations trigger third-party auditing requirements and technical documentation burdens.
- Fire Alarm:Integrated life safety systems leverage building automation heritage to anchor commercial portfolios, with CE marking under the EU Radio Equipment Directive harmonizing cross-border deployment.
Intrusion alarm leads volumes today; video surveillance is gaining share fastest.
Technology:
Connectivity architecture selection hinges on masonry penetration requirements, legacy system preservation needs, and cybersecurity certification burdens.
- Wireless:Mesh networking protocols operating at sub-GHz frequencies overtake traditional star-topology Wi-Fi in residential retrofit applications. Installers across Germany and France favor these architectures for penetrating thick masonry walls in aging housing stock. Battery-powered sensor arrays compress total cost of ownership calculations and displace wired alternatives where cable routing proves prohibitive.
- IoT-Based:Cloud-connected platforms with AI-enabled analytics shift margin pools from hardware sales toward recurring software services. The EU Cybersecurity Act's incoming firmware update mandates and vulnerability disclosure timelines favor vendors with established security operations centers.
- Wired:Decades-old installations in commercial facilities demand hybrid architectures that maintain compatibility, constraining design freedom for pure-play wireless vendors.
- Hybrid:Dual-path connectivity preserves legacy investments while enabling incremental cloud feature upgrades, capturing upgrade cycles in facilities seeking staged modernization.
Wireless dominates residential unit volumes; IoT-based architectures show steepest expansion trajectory.
End User:
Scale determines procurement sophistication, from self-install app commerce to enterprise security operations center integration.
- Residential:Direct-to-consumer installation networks concentrate in Northern European markets, with subscription-based monitoring contracts displacing upfront equipment purchases. Spain and Italy exhibit lower penetration rates than Northern Europe, creating whitespace for proprietary infrastructure expansion.
- Large Enterprise:Industrial-grade IoT architectures extend from energy management into integrated security ecosystems, opening cross-selling channels for building automation vendors. Procurement demands hybrid architectures preserving decades-old wired installations.
- Small Business:Cost-constrained buyers favor unbundled hardware and service fees, matching preferences established by direct-to-consumer brands.
- Government:Mandated connected safety infrastructure in public facilities generates concentrated demand with extended compliance documentation requirements.
Residential captures greatest unit volumes; large enterprise delivers highest lifetime customer value expansion.
Installation Type:
Service model selection reflects buyer technical capability, regulatory complexity tolerance, and preference for capital versus operational expenditure treatment.
- DIY:App-first onboarding experiences capture share from traditional security installers in the United Kingdom, where channel rotation accelerates fastest. Self-install sensor arrays with multi-year battery lifespans reduce total cost of ownership for technically capable homeowners.
- Managed Services:Subscription-based monitoring contracts with proprietary infrastructure establish recurring revenue pools and customer lock-in through closed-protocol systems. Vulnerability disclosure timelines and continuous firmware validation requirements favor vendors with established security operations centers.
- Professional:Certified installer networks dominate commercial verticals where CE marking documentation and GDPR biometric data governance frameworks lengthen sales cycles.
- Integrated Systems:Converged energy management and access control deployments extend industrial-grade IoT architectures into unified building automation platforms.
Professional installation retains commercial dominance; managed services climb fastest in residential subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified security installation technicians concentrate in Germany's industrial corridors and the United Kingdom's southeast commuter belt, anchoring service capacity for retrofit demand across aging European housing stock.
Germany
Urban renewal programs in Berlin and Hamburg subsidize wireless intrusion alarm retrofits in post-war apartment blocks. The KBA's interpretation of EU AI Act timelines accelerates biometric compliance investments ahead of peripheral member states. Munich's building automation cluster anchors industrial-grade IoT architectures extending from energy management into access control ecosystems.
United Kingdom
Direct-to-consumer brands capture share from traditional installers through app-first onboarding experiences concentrated in London commuter zones. GDPR biometric data governance frameworks lengthen sales cycles for facial recognition deployments in commercial facilities. Birmingham's security distribution hub channels wireless mesh hardware into residential retrofit applications across Midlands heritage housing.
France
ANSM and CNIL regulators enforce aggressive EU AI Act implementation timelines for biometric surveillance systems in public housing. Lyon and Grenoble's smart city programs mandate connected safety infrastructure in subsidized residential retrofits. Parisian commercial real estate drives hybrid architecture demand preserving decades-old wired installations during staged modernization.
Spain
Lower smart home security penetration than Northern Europe creates whitespace for proprietary monitoring infrastructure expansion in Madrid and Barcelona metropolitan areas. ECHA REACH flame-retardant restrictions force rapid supplier transitions for enclosure manufacturers based in Valencia's plastics processing cluster. Andalusian urban renewal programs generate concentrated demand for battery-powered sensor arrays in heritage buildings.
Italy
Milan's industrial IoT ecosystem converges energy management with access control architectures serving commercial facility upgrade cycles. CE marking under the EU Radio Equipment Directive harmonizes cross-border deployment for 868 MHz wireless protocols manufactured in Emilia-Romagna's electronics corridor. Rome's public infrastructure mandates drive government procurement with extended compliance documentation requirements.
Europe Home Security System Market Competitive Landscape
The competitive structure tilts toward building automation heritage and proprietary monitoring infrastructure. Tiered concentration separates integrated industrial-grade vendors from direct-to-consumer installation networks. Three archetypes dominate: building automation extenders leveraging energy management platforms, proprietary monitoring operators with closed-protocol ecosystems, and diversified industrial conglomerates spanning fire and intrusion portfolios. Geographic expansion through certified installer networks and firmware architecture redesigns for EU AI Act compliance constitute the dominant competitive moves reshaping positioning.
Among diversified industrial conglomerates, Honeywell International and Siemens occupy positions exemplifying the building automation extender archetype, while Verisure anchors the proprietary monitoring infrastructure tier. These three names represent the spectrum from industrial-grade IoT architectures through direct-to-consumer subscription models, with each sitting within distinct margin pool capture mechanisms across hardware sales and recurring software services.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens |
| Verisure |
| Sector Alarm |
| ASSA ABLOY |
| Prosegur |
| Schneider Electric |
| EPS Télésurveillance |
| Johnson Controls |
| Others |
Supply & Pricing Matrix
Certified security installation technicians concentrate in Germany's industrial corridors and the United Kingdom's southeast commuter belt, anchoring service capacity that widens pricing-tier spreads between professionally installed systems and self-install alternatives. Labor-cost differentials between Northern European installer networks and Southern European whitespace markets stratify end-user pricing across subscription and transactional models.
Pricing Analysis
The bundled-versus-unbundled service split separates recurring subscription contracts from upfront hardware transactions across European consumer segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under CE marking and GDPR biometric compliance tiers. Cost compression in economy-tier hardware is intensifying because ECHA REACH flame-retardant substitutions force material requalification expenses onto enclosure manufacturers. Small business buyers exhibit highest price sensitivity, while large enterprise procurement tolerates premium positioning for integrated life safety architectures.
Supply Chain Analysis
Workforce availability constraints in Emilia-Romagna's electronics corridor and Valencia's plastics processing cluster tether component sourcing to qualified supplier pools with limited REACH-compliant alternatives. Germany, China, and South Korea anchor semiconductor and sensor module production for 868 MHz wireless protocols and edge-AI chipsets. Supply chain risk centers on single-source vulnerability for flame-retardant compound formulations following ECHA restrictions. Distribution runs through certified installer networks in commercial verticals and direct-to-consumer platforms in residential retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's home security system market operates as a stable compounder, with regulatory-mandated upgrade cycles under the EU AI Act and EU Cybersecurity Act generating predictable replacement demand across installed hardware bases.
For Market Incumbents: Anticipate firmware architecture redesign costs from EU AI Act biometric surveillance provisions by accelerating security operations center investments ahead of harmonized standards finalization. Backward integration into REACH-compliant flame-retardant material sourcing defends margin position against supplier requalification bottlenecks. Channel control through proprietary monitoring infrastructure maintains customer lock-in against direct-to-consumer app-first entrants.
For New Entrants and Emerging Players: Enter via underpenetrated Southern European residential markets in Spain and Italy, where proprietary monitoring infrastructure density lags Northern European benchmarks. Target Madrid and Barcelona metropolitan areas with subscription-based service models that displace upfront equipment purchases. Pursue app-first onboarding experiences matching United Kingdom channel rotation patterns.
For Investors and Strategic Acquirers: Building automation conglomerates with energy management platforms are the most active acquirer in this space, seeking access control ecosystem extensions. Mid-scale monitoring operators with closed-protocol installed bases represent priority acquisition archetypes over five-to-ten year holding windows. Watch EU Cybersecurity Act implementation timelines as inflection indicator for firmware update mandate compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Architecture Redesign | EU AI Act biometric surveillance provisions force third-party auditing investments ahead of peripheral member state timelines. |
| REACH-Compliant Material Sourcing | ECHA flame-retardant restrictions accelerate supplier transitions for Valencia-based enclosure manufacturers. |
| Security Operations Center Expansion | EU Cybersecurity Act vulnerability disclosure timelines favor vendors with established firmware validation capabilities. |
| Direct-to-Consumer Platform Launch | App-first onboarding experiences capture residential share from traditional installer networks in United Kingdom commuter zones. |
| Hybrid Architecture Development | Dual-path connectivity preserves legacy wired investments while enabling cloud feature upgrades in Parisian commercial real estate. |
Research Methodology
Direct dialogue with security system installers, building automation procurement leads, regulatory affairs specialists at hardware vendors, and monitoring service operations directors grounded qualitative assessment in operational realities. Secondary validation drew from CE marking documentation databases, ECHA REACH substance restriction filings, EU Cybersecurity Act harmonized standards drafts, and customs records for 868 MHz wireless equipment trade flows. Bottom-up unit shipment estimates triangulated against top-down addressable housing stock calculations.
Segmentation outputs across product type, connectivity technology, end-user scale, and installation service model populated the analytical framework across the projection horizon. CAGRs were derived from installed base replacement cycle analysis and urban renewal program procurement schedules. Forecast inputs incorporated EU AI Act implementation timeline variance between French, German, and peripheral regulator interpretations.
Inputs from installer network density surveys and REACH-compliant material supplier qualification records were available through the study window; gaps in real-time firmware compliance cost disclosures introduce uncertainty bands around vendor margin projections. Forecasts reflect documented assumptions regarding biometric surveillance risk classification enforcement intensity. Material deviation in EU Cybersecurity Act certification timeline compression or ECHA substance restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
GPS Smart Locks Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Middle-East and Africa Airport Passenger Screening Systems Market
Access Control Systems
Vehicle Security System Market
Access Control Systems
North America Access Control Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Digital Security Control Market