
 Global Automatic Door Control Market | 2026-2036
Global Automatic Door Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Door Control Market Analysis
Aftermarket service revenue is narrowing as a margin pool migration between activities as original equipment manufacturers capture recurring maintenance contracts previously held by independent service providers. ASSA ABLOY AB leverages its installed base across Europe to sustain long-term service agreements. Dormakaba Holding AG anchors its profitability through proprietary diagnostic software that locks in multi-year maintenance renewals. Nabtesco Corporation competes in Asia-Pacific through localized spare-part distribution networks that reduce third-party intervention.
Automatic door control encompasses electromechanical, hydraulic, pneumatic, and magnetic systems that regulate door motion through sensor-activated motor drives, typically operating at 24V DC with programmable opening speeds between 0.3 and 1.6 meters per second for pedestrian traffic management. Sliding doors dominate hospital and airport specifications where space constraints and high-frequency operation demand linear motion efficiency, while swing door retrofits represent the fastest-growing installation category as aging commercial buildings upgrade accessibility compliance. Electromechanical technology leads volume shipments due to its compatibility with building management system integration, though magnetic drive systems command premium positioning in noise-sensitive healthcare environments.
The EU Machinery Directive and CE marking framework mandate force limitation and emergency-stop functionality for all automated pedestrian door systems sold in member states, while the US FDA enforces infection-control accessibility standards in healthcare facilities that specify hands-free activation thresholds. Japan's METI energy-efficiency guidelines for building equipment are tightening standby power consumption limits for door operators in commercial applications. Stakeholders must monitor evolving interoperability standards between door controls and smart building platforms as procurement specifications shift toward integrated facility management ecosystems.
Market Dynamics
Touchless activation protocols are compressing specification cycles across healthcare and transportation infrastructure, as sensor-integrated door controls displace mechanical push-plate systems in renovation pipelines.
Growth Catalysts
- EU Machinery Directive force-limitation mandates:Member states now require certified emergency-stop functionality for all electromechanical pedestrian door operators, accelerating replacement of pre-2019 installations.
- Hospital infection-control specifications:Hands-free activation thresholds enforced by the US FDA in acute-care facilities are driving specification of microwave and infrared sensor arrays over contact-based alternatives.
- Southeast Asia infrastructure modernization:Public hospital renovation programs in Thailand, Vietnam, and Indonesia are specifying touchless entry systems as standard equipment in new clinical wings.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium-dependent magnetic drive systems face input cost volatility as processing capacity concentrates in China.
- CE marking compliance timeline:The EU Machinery Directive's tightened safety thresholds extend product certification cycles by four to six months for non-European manufacturers.
- Electromechanical actuator technical ceiling:Force-precision limitations at high-cycle frequencies restrict electromechanical systems from premium healthcare noise specifications.
Strategic Opportunities
- India commercial building retrofit wave:Aging office stock in Mumbai, Bangalore, and Delhi requires accessibility compliance upgrades without structural modification.
- Building management system convergence:Integration of door control APIs with BACnet and Modbus protocols enables centralized facility analytics.
- Japan METI standby power regulations:Tightened energy-efficiency guidelines for commercial building equipment create specification advantage for sub-5W idle-consumption operators.
Industry Challenges
- Electromechanical technician certification gaps:Qualified service personnel for 24V DC motor-drive diagnostics remain scarce in secondary Indian and Southeast Asian cities.
- Legacy pneumatic system integration friction:Retrofit projects in 1980s-era commercial buildings face incompatible pressure-line infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Door Control Market |
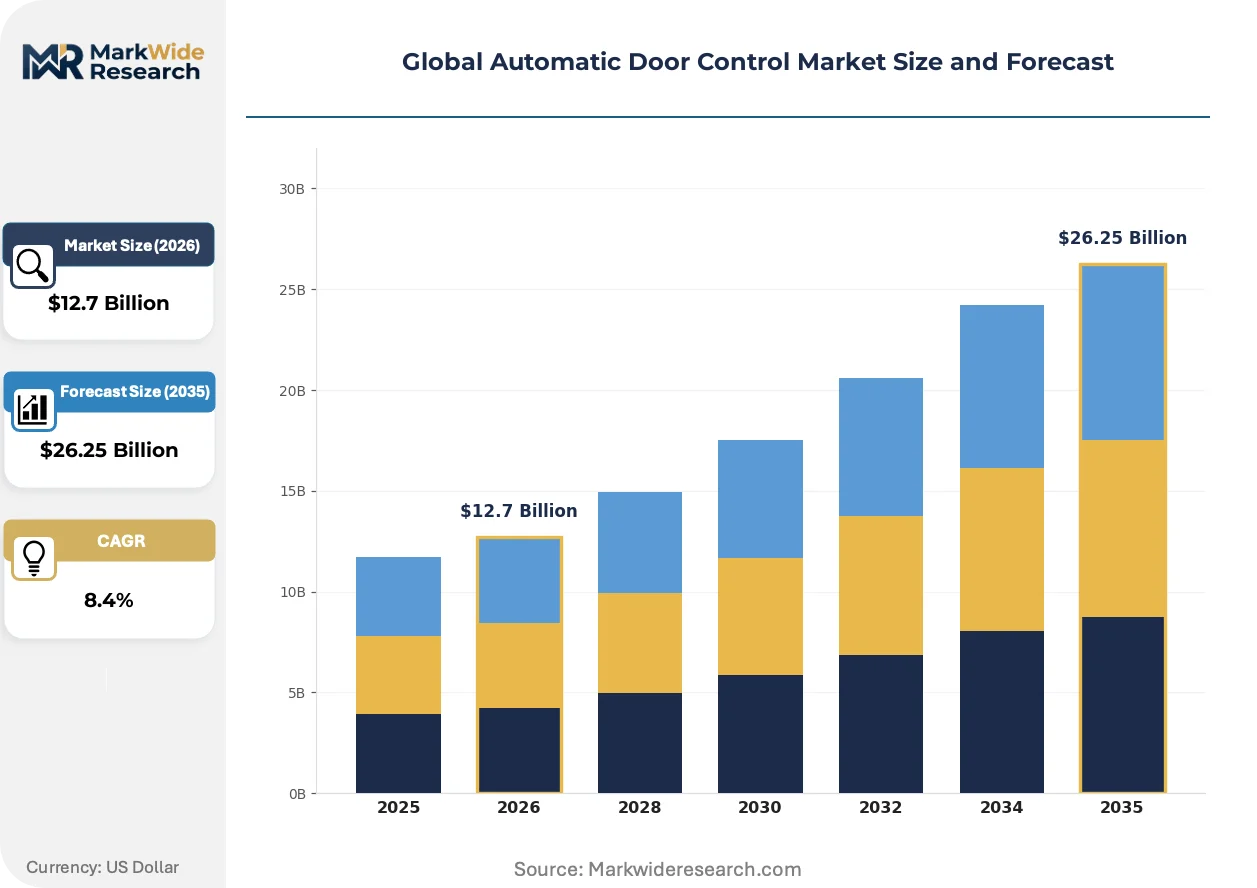
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Swing Doors, Folding Doors, Revolving Doors Technology: Electromechanical, Hydraulic, Pneumatic, Magnetic End User: Retail, Hospitals, Airports, Commercial Buildings Installation Type: New Installations, Retrofits, Upgrades, Maintenance |
| Companies Covered | ASSA ABLOY AB, Dormakaba Holding AG, GEZE GmbH, Stanley Access Technologies, Nabtesco Corporation, Horton Automatics, Royal Boon Edam International B.V., Panasonic Corporation, TORMAX USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Door Control Market Emerging Trajectories
Edge-computing sensor arrays are compressing response latency in high-frequency pedestrian environments. Three developments are restructuring competitive advantage.
Millimeter-wave radar sensors with onboard processing chips are digitizing activation protocols in airport and hospital corridors. Frankfurt Airport's Terminal 3 and Singapore Changi's renovation wings have specified these units for sub-200-millisecond detection-to-open cycles. The technology is digitizing maintenance workflows by embedding predictive-failure algorithms that transmit vibration signatures to facility management platforms.
The EU AI Act's risk-classification framework is extending conformity assessment requirements to sensor-integrated door controls with biometric-adjacent detection capabilities. Manufacturers must now document algorithmic transparency for systems deployed in member-state public buildings. German healthcare procurement offices have begun requiring AI Act compliance documentation alongside traditional CE marking.
Service-contract unbundling is fragmenting aftermarket revenue streams. Independent facility managers in the US and UK are negotiating à-carte diagnostic access rather than multi-year maintenance agreements. The shift is most visible in London's commercial office sector, where property technology platforms aggregate door-control health data across landlord portfolios.
Global Automatic Door Control Market Segmentation
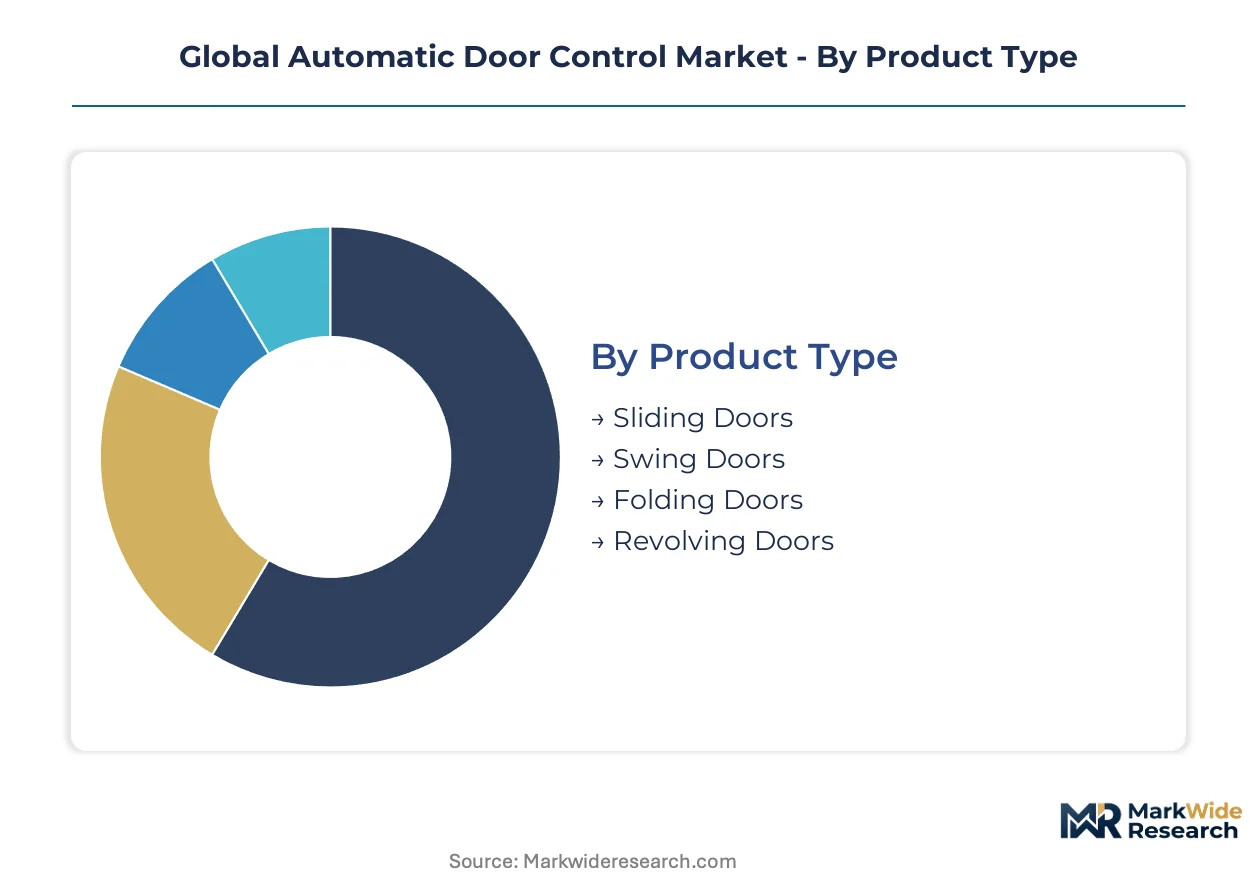
Automatic door control segmentation reveals how specification requirements diverge across building typologies and operational intensities. Product architecture, drive technology, and procurement timing each create distinct competitive battlegrounds with different margin profiles and service attach rates.
Product Type:
Linear motion systems dominate high-traffic corridors where space efficiency and cycle frequency determine specification.
- Sliding Doors:Telescopic or single-panel configurations operate on overhead track systems with 24V DC motor drives programmed for 0.3 to 1.6 meters per second opening speeds. Hospital infrastructure upgrades across Thailand, Vietnam, and Indonesia specify these as standard equipment in new clinical wings where infection-control protocols mandate hands-free entry.
- Swing Doors:Surface-mounted or concealed operators attach to traditional hinged frames, enabling accessibility compliance without structural modification. Aging commercial buildings in Mumbai, Bangalore, and Delhi are expanding this category fastest as retrofit activity accelerates to meet accessibility mandates.
- Folding Doors:Accordion-style panels stack laterally to maximize clear opening width in constrained vestibules. Regional rail stations in Germany specify these for platform access control.
- Revolving Doors:Continuous or three-wing configurations manage air infiltration in climate-controlled lobbies. Frankfurt Airport's Terminal 3 renovation has specified these for energy-efficient passenger flow management.
Established volume favors sliding configurations; emerging adoption favors swing door retrofits.
Technology:
Drive mechanism selection hinges on integration requirements, acoustic constraints, and building management system compatibility.
- Electromechanical:Brushless DC motor systems with programmable controllers dominate shipment volumes through BACnet and Modbus protocol compatibility. EU Machinery Directive force-limitation mandates are accelerating replacement of pre-2019 installations that lack certified emergency-stop functionality.
- Magnetic:Linear synchronous motor drives eliminate mechanical contact for sub-35 decibel operation. Premium healthcare specifications in noise-sensitive environments command this technology despite neodymium supply concentration in China creating input cost volatility.
- Hydraulic:Fluid-power actuators deliver high force density for heavy door panels in industrial applications. Japan's METI standby power regulations disadvantage these systems in commercial building specifications.
- Pneumatic:Compressed-air drives persist in legacy industrial facilities with existing pressure-line infrastructure. Retrofit friction in 1980s-era commercial buildings limits growth outside manufacturing environments.
Electromechanical systems capture volume leadership; magnetic drives claim premium positioning.
End User:
Operational intensity and regulatory exposure shape procurement sophistication across building categories.
- Hospitals:Acute-care facilities enforce US FDA infection-control accessibility standards specifying microwave and infrared sensor arrays. Touchless activation protocols are compressing specification cycles as mechanical push-plate systems face displacement.
- Airports:Terminal corridors demand sub-200-millisecond detection-to-open cycles enabled by millimeter-wave radar with onboard processing. Singapore Changi's renovation wings have specified these units for predictive-failure algorithm integration.
- Commercial Buildings:Office and mixed-use properties prioritize building management system convergence through standardized APIs. London's commercial office sector is fragmenting service-contract structures through property technology platform aggregation.
- Retail:High-frequency storefront activation emphasizes reliability and rapid service response. Independent facility managers in the US and UK are negotiating à-carte diagnostic access rather than multi-year maintenance agreements.
Healthcare and aviation concentrate premium specification; commercial retrofit activity scales volume opportunity.
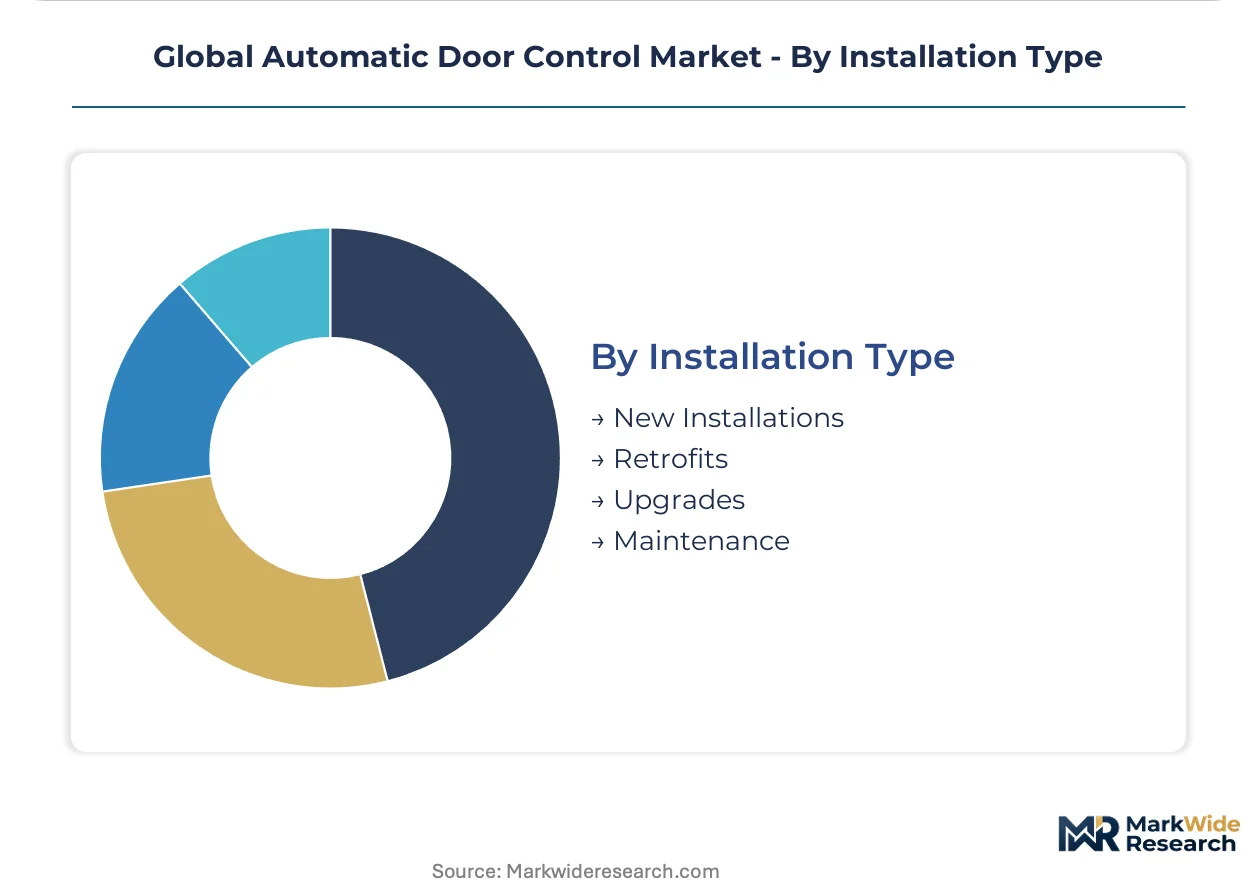
Installation Type:
Procurement timing determines margin structure and customer relationship durability.
- New Installations:Greenfield construction enables integrated specification of sensor arrays, door panels, and building management interfaces. Southeast Asia public hospital renovation programs are expanding this category through standardized clinical wing designs.
- Retrofits:Accessibility compliance upgrades in aging building stock without structural modification represent the steepest expansion trajectory. India's commercial building retrofit wave in Mumbai, Bangalore, and Delhi drives specification of surface-mounted operators.
- Upgrades:Component-level replacement of sensors, controllers, or drive mechanisms extends system lifecycle. EU AI Act risk-classification requirements are extending conformity assessment timelines for sensor-integrated controls with biometric-adjacent detection.
- Maintenance:Recurring service contracts are narrowing as original equipment manufacturers capture agreements previously held by independent providers. ASSA ABLOY AB leverages its installed base across Europe to sustain long-term agreements.
Retrofit activity commands growth momentum; maintenance revenue faces unbundling pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys magnetic drive systems for premium healthcare noise specifications, while India and Southeast Asian markets prioritize electromechanical retrofits for accessibility compliance in aging commercial stock.
Germany
Healthcare renovation pipelines in Bavaria and North Rhine-Westphalia specify sub-35 decibel magnetic drive systems for noise-sensitive clinical environments. The EU Machinery Directive's tightened force-limitation mandates accelerate replacement of pre-2019 electromechanical installations lacking certified emergency-stop functionality. Frankfurt Airport's Terminal 3 anchors aviation-sector demand for millimeter-wave radar integration.
United States
Acute-care facilities enforce FDA infection-control accessibility standards specifying microwave and infrared sensor arrays over mechanical push-plate systems. Independent facility managers in commercial office sectors negotiate à-carte diagnostic access rather than multi-year maintenance agreements. New York Metro and Chicago corridors concentrate retrofit activity for aging building accessibility compliance.
India
Aging office stock in Mumbai, Bangalore, and Delhi requires surface-mounted swing door operators for accessibility upgrades without structural modification. The country's national building code regulator tightens commercial accessibility mandates through state-level enforcement. Secondary cities face electromechanical technician certification gaps that constrain service response capabilities.
Japan
METI standby power regulations for commercial building equipment create specification advantage for sub-5W idle-consumption operators. Tokyo and Osaka healthcare facilities prioritize energy-efficient door control integration with building management systems. Kansai region airports specify predictive-failure algorithms for high-frequency pedestrian corridor management.
Thailand
Public hospital renovation programs specify touchless entry systems as standard equipment in new clinical wings. The country's national industrial standards body aligns with EU Machinery Directive safety thresholds for electromechanical pedestrian door operators. Bangkok medical infrastructure clusters drive specification of sensor-activated motor drives programmed for 0.3 to 1.6 meters per second opening speeds.
Global Automatic Door Control Market Vendor Landscape
Capability concentration sits with electromechanical system specialists; scale advantage sits with diversified building access conglomerates. The vendor base organizes around three strategic archetypes: European heritage manufacturers with installed-base service leverage, Asia-Pacific component integrators with localized distribution density, and North American retrofit specialists with accessibility compliance expertise. Dominant competitive moves include multi-year maintenance contract capture and proprietary diagnostic software deployment to lock in recurring revenue streams.
Within the European heritage tier, ASSA ABLOY AB and Dormakaba Holding AG occupy positions defined by long-term service agreement structures across regional installed bases. Nabtesco Corporation exemplifies the Asia-Pacific archetype through spare-part distribution network localization. These three entities represent contrasting geographic anchoring strategies rather than direct product competition.
| Leading Market Players |
|---|
| ASSA ABLOY AB |
| Dormakaba Holding AG |
| GEZE GmbH |
| Stanley Access Technologies |
| Nabtesco Corporation |
| Horton Automatics |
| Royal Boon Edam International B.V. |
| Panasonic Corporation |
| TORMAX USA Inc. |
| Others |
Supply Flow & Price Mechanics
Neodymium processing capacity concentration in China feeds directly into margin pool capture by magnetic drive system specialists serving premium healthcare specifications. Input cost volatility for rare-earth magnets compresses pricing power at the premium tier while electromechanical volume manufacturers absorb margin pressure through scale economies in 24V DC motor-drive production.
Pricing Analysis
Long-term service contracts dominate the commercial building segment, with multi-year maintenance agreements locking in recurring revenue streams for original equipment manufacturers. Pricing stratifies across premium, standard, and economy tiers based on noise specification compliance and building management system integration depth. Cost compression in the electromechanical tier intensifies because independent service providers cede aftermarket share to manufacturer-captive service networks. Healthcare facilities demonstrate the least price sensitivity due to FDA-mandated infection-control accessibility thresholds, while retail storefront operators negotiate aggressively for à-carte diagnostic access.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare-earth processing facilities, with secondary sourcing from Vietnamese and Australian mining operations. Brushless DC motors and programmable controllers rest on semiconductor inputs from Taiwan and South Korea, while aluminum extrusions for door panels hinge on Chinese and German mill capacity. Single-source vulnerability concentrates in neodymium supply chains, exposing magnetic drive manufacturers to export restriction risk. Distribution runs through manufacturer-direct specification in new construction projects, with authorized distributor networks handling retrofit and aftermarket service fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware shipments as predictive-maintenance software and multi-year diagnostic contracts capture margin pools previously held by independent providers. Recurring service agreements now represent the primary value-creation mechanism for established installed-base operators.
For Market Incumbents: Build proprietary diagnostic software moats that embed predictive-failure algorithms into facility management platforms. Capture maintenance contract renewals through vibration-signature telemetry and remote troubleshooting capabilities. Counter independent facility manager unbundling by offering API-level building management system integration that locks in long-term data dependencies. For New Entrants and Emerging Players: Build out localized spare-part distribution networks in secondary Indian and Southeast Asian cities where electromechanical technician certification gaps constrain incumbent service response. Target India's commercial building retrofit wave in Mumbai, Bangalore, and Delhi with surface-mounted swing door operators priced for accessibility compliance without structural modification. Lead with rapid-install value propositions and state-level building code alignment rather than premium specification chasing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European heritage manufacturers holding dense installed bases across Germany and adjacent markets. Five-to-ten year viability hinges on service-contract renewal rates and building management system convergence positioning. Watch for inflection signals in EU AI Act compliance documentation requirements for sensor-integrated controls with biometric-adjacent detection capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Diagnostic Software Deployment | Locks in multi-year maintenance renewals through predictive-failure algorithm integration with BACnet protocols. |
| Localized Spare-Part Distribution Buildout | Reduces third-party service intervention in Asia-Pacific markets through regional inventory positioning. |
| Building Management System API Integration | Enables centralized facility analytics convergence through standardized Modbus protocol compatibility. |
| EU AI Act Compliance Documentation Investment | Extends conformity assessment timelines for biometric-adjacent sensor controls in member-state public buildings. |
| Retrofit-Focused Product Line Expansion | Captures India's accessibility compliance wave with surface-mounted operators requiring no structural modification. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facility management directors, biomedical engineers specifying hospital entry systems, aftermarket service technicians, and procurement leads at airport authorities. Secondary validation drew from EU Machinery Directive implementation guidance, FDA infection-control accessibility standards, METI energy-efficiency guidelines, and customs trade data for electromechanical actuator imports. Bottom-up shipment estimates by product configuration and technology type were triangulated against top-down construction spending and building renovation pipeline data.
Calibration against historical specification cycles and regulatory compliance timelines anchored the analytical framework across the projection horizon. Segmentation modeling captured product architecture, drive technology, end-use building typology, and installation timing dimensions. CAGRs were derived from installed base growth rates, replacement cycle acceleration, and service-contract attach rate assumptions. Forecast inputs incorporated EU Machinery Directive force-limitation mandate compliance deadlines and Southeast Asia public hospital renovation program schedules.
Practitioners should monitor neodymium export policy shifts and EU AI Act risk-classification enforcement for early signals of input cost volatility and extended certification timelines. Forecasts reflect assumptions about technician certification pipeline development in secondary Indian cities and building management system protocol standardization trajectories. Cross-checking against national building code regulatory filings and hospital procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Car Security System Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
China Access Control Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
RFID Locks Market
Access Control Systems
Asia-Pacific Access Control Hardware Market